Report15 pages
El Seguro en el Ámbito de los Videojuegos
This industry guide, developed by the Spanish Video Game Association (AEVI) in collaboration with legal experts from Pérez-Llorca, serves as a strategic framework for managing risk within the video game development and publishing sectors. The primary thesis emphasizes that insurance is an essential mechanism for ensuring the financial viability of projects, acting as an indirect prevention tool against the inherent complexities of game production, such as tight delivery schedules, technical bugs, and intellectual property disputes.
The analysis identifies several critical risk categories specific to the gaming industry, including breach of delivery deadlines, transmission of computer viruses, and unauthorized data intrusions. Key findings highlight that Professional Civil Liability (RCP) and Errors and Omissions (E&O) insurance are the most vital protections for developers, covering involuntary contractual breaches and negligence. Furthermore, the guide underscores the rising importance of cybersecurity insurance to mitigate operational costs and reputational damage resulting from hacking, ransomware, and data leaks, which can trigger significant sanctions from regulatory bodies like the Spanish Data Protection Agency.
The scope of the guidance focuses on the Spanish market, referencing local legal standards and regulatory bodies, while covering the entire industry lifecycle from independent developers and freelancers to large publishers. It details specific coverage areas such as intellectual property infringement—protecting against claims regarding music, characters, and concept art—and liability for defamation or the unauthorized use of public images. Methodologically, the guide provides a practical checklist for insurance procurement, advising firms to utilize insurance brokerages for periodic contract reviews and to ensure all operational risks are disclosed to maintain policy validity.
- Professional Civil Liability (RCP) and Errors and Omissions (E&O) insurance are the primary mechanisms for protecting developers against involuntary contractual breaches and professional negligence.
- Cybersecurity insurance is essential for mitigating the operational costs and reputational damage associated with ransomware, data leaks, and hacking incidents.
- Insurance policies must specifically cover intellectual property infringement, including claims related to unauthorized use of music, character designs, and concept art.
- The Spanish Video Game Association (AEVI) and Pérez-Llorca identify breach of delivery deadlines, computer virus transmission, and unauthorized data intrusions as the most critical operational risks for game studios.
- Regulatory compliance, particularly regarding data protection standards enforced by the Spanish Data Protection Agency, is a major driver for adopting comprehensive insurance coverage.
+1
AEVIJan 2025
Report43 pages
Videojuegos en el Aula: ¿Qué se está haciendo en España? Manual para docentes 2025
Video games have become a central cultural and educational tool in Spain, where more than 22 million people—over half of them women—play an average of 8.2 hours each week. This widespread engagement is leveraged to motivate learning, prompting the development of a coordinated ecosystem that supplies teachers with curated resources, professional training, and ready‑to‑use platforms such as Dok Student, Cokitos, Mundo Primaria, Eutopía and Escapeweb. Publicly funded titles like ABC Dinos, BookyPets and Quijote: Quest for Glory employ RPG, tower‑defense and card mechanics to reinforce early literacy, while historically grounded games such as Dîrok, Plus Ultra Legado and El Enigma de Toledo integrate rigorous research into curricula, supporting both STEM competencies and language development.
A parallel surge in health‑oriented games addresses the mental‑health concerns of Spanish adolescents, with 41 % reporting problems and one‑third never having discussed them. These applications aim to provide preventive support and therapeutic engagement within school settings. Meanwhile, esports and gamified learning are gaining institutional traction; a national competition rewards winning schools with €20 000 in technology, and industry partnerships like GGTech’s site visits illustrate viable career pathways. Complementary initiatives, such as Cruz Roja’s 150‑hour Unity programming course for unemployed youth and the Andalusian “Desafía & Aprende” program, further embed game design skills into broader employment strategies.
Overall, the Spanish educational landscape demonstrates a rapid, multi‑sectoral integration of video games that spans literacy, history, health, and vocational training, reflecting a strategic response to the medium’s pervasive cultural presence and its potential to enhance learning outcomes across the country.
- Spain’s gaming ecosystem is supported by over 22 million players, with women accounting for more than half of the user base and an average weekly playtime of 8.2 hours.
- Educational integration is facilitated by a standardized infrastructure of platforms including Dok Student, Cokitos, Mundo Primaria, Eutopía, and Escapeweb.
- Publicly funded titles like ABC Dinos, BookyPets, and Quijote: Quest for Glory utilize RPG and tower-defense mechanics to improve early literacy, while games like Dîrok and El Enigma de Toledo support STEM and history curricula.
- To address the 41% of Spanish adolescents reporting mental health concerns, schools are increasingly adopting therapeutic and preventive video game applications.
- Institutional support for esports and gamification includes a national competition offering €20,000 in technology prizes and industry-led career exposure through partners like GGTech.
+3
AEVIJan 2025
Report25 pages
Global Business Strategies for K-Fashion: A Focus on K-Content
The analysis demonstrates that the future competitiveness of Korean fashion hinges on integrating cultural content with advanced technology and participatory fan ecosystems. Influencer campaigns have evolved from reliance on celebrity notoriety to collaborations built on shared values and fan‑aligned storytelling, positioning fan‑generated media as an active co‑marketing partner rather than a peripheral buzz generator. This shift amplifies brand authenticity and deepens consumer loyalty across global markets.
Artificial intelligence is identified as the primary catalyst reshaping product development, marketing, and sustainability. On‑demand production models, exemplified by Desigual’s AI‑driven forecasting, have markedly reduced inventory waste, while hyper‑personalized styling tools and virtual‑try‑on platforms are delivering measurable financial gains. Gentle Monster’s AI‑based recommendation engine lifted revenue by 25 %, and H&M’s deployment of digital twins curtailed refund rates, underscoring the profitability of AI integration. The emergence of agentic commerce, projected to mature by 2026, promises further automation of the purchase journey and deeper data‑driven consumer insights.
Geographically, the findings span a global perspective, encompassing major fashion hubs in North America, Europe, and Asia, and cover the period from the early 2020s through the anticipated developments of 2026. The scope encompasses the apparel, accessories, and eyewear segments, with particular emphasis on digital fashion, AI‑enabled supply chains, and the symbiotic relationship between K‑content and international consumer culture. Collectively, these insights outline a strategic roadmap for Korean fashion brands seeking to leverage cultural capital and technological innovation to secure sustainable growth worldwide.
- AI integration is a primary driver of profitability, evidenced by Gentle Monster’s 25% revenue increase through recommendation engines and H&M’s reduction in refund rates via digital twins.
- Korean fashion brands are shifting influencer strategies from celebrity-based notoriety to value-aligned storytelling, treating fan-generated media as a core co-marketing partner to boost authenticity.
- On-demand production models, such as those utilized by Desigual, are effectively leveraging AI-driven forecasting to minimize inventory waste and improve supply chain sustainability.
- Agentic commerce is projected to mature by 2026, a development expected to further automate the consumer purchase journey and provide deeper data-driven insights.
- Future competitiveness for Korean fashion relies on the strategic integration of cultural content, advanced technology, and participatory fan ecosystems across global markets.
KOCCA – Korea Creative Content AgencyJan 2025
Report6 pages
Securing Competitiveness in Human-Creativity-Driven BGM Production in the Age of AI-Generated Music: South Korea
The interview with Hong Eun‑Ji, CEO of T2Sound, examines how background‑music (BGM) producers in South Korea can preserve competitive advantage as AI‑generated music becomes increasingly affordable and rapid. The central thesis is that human creativity—particularly the ability to convey authentic emotion and intent—remains the decisive factor that AI cannot replicate, and that leveraging AI as a collaborative tool rather than a threat can enhance, not replace, the artistic value of BGM.
Key insights emphasize that quality and emotional resonance, achieved through meticulous mixing and mastering, are the core values guiding T2Sound’s work. The company prioritises collaboration with external creators, believing that collective expertise yields richer nuance than isolated in‑house production. Market trends reveal a shift among overseas buyers toward tracks with distinctive sonic signatures rather than generic pleasantness, and Korean BGM’s success abroad is linked to its unique emotional line and texture. In short‑form media, the interview highlights the necessity of an immediate, memorable hook within the first few seconds to secure brand recognition and audience immersion.
Looking ahead to 2026, the conversation predicts a consolidation around financially proven genres such as hip‑hop and trot in Korea, reflecting an industry increasingly driven by economic sustainability. The interview’s qualitative methodology—direct dialogue with a leading BGM provider—offers a focused perspective on the evolving interplay between AI tools, human artistry, and global market demands within the South Korean audio‑content sector.
- Human creativity remains the primary competitive advantage for BGM producers, as the ability to convey authentic emotion and intent cannot be replicated by AI.
- T2Sound maintains market competitiveness by prioritizing meticulous mixing and mastering to ensure high-quality emotional resonance, rather than competing solely on speed or cost.
- Global demand is shifting away from generic background music toward tracks with distinctive sonic signatures, with Korean BGM gaining traction due to its unique emotional texture.
- Short-form media content requires an immediate, memorable hook within the first few seconds to successfully secure brand recognition and audience immersion.
- T2Sound leverages a collaborative model with external creators to achieve richer artistic nuance than what is typically produced through isolated in-house workflows.
+1
KOCCA – Korea Creative Content AgencyJan 2025
Report15 pages
Interview with Yi Yuan, at Hiverlab: Southeast Asia
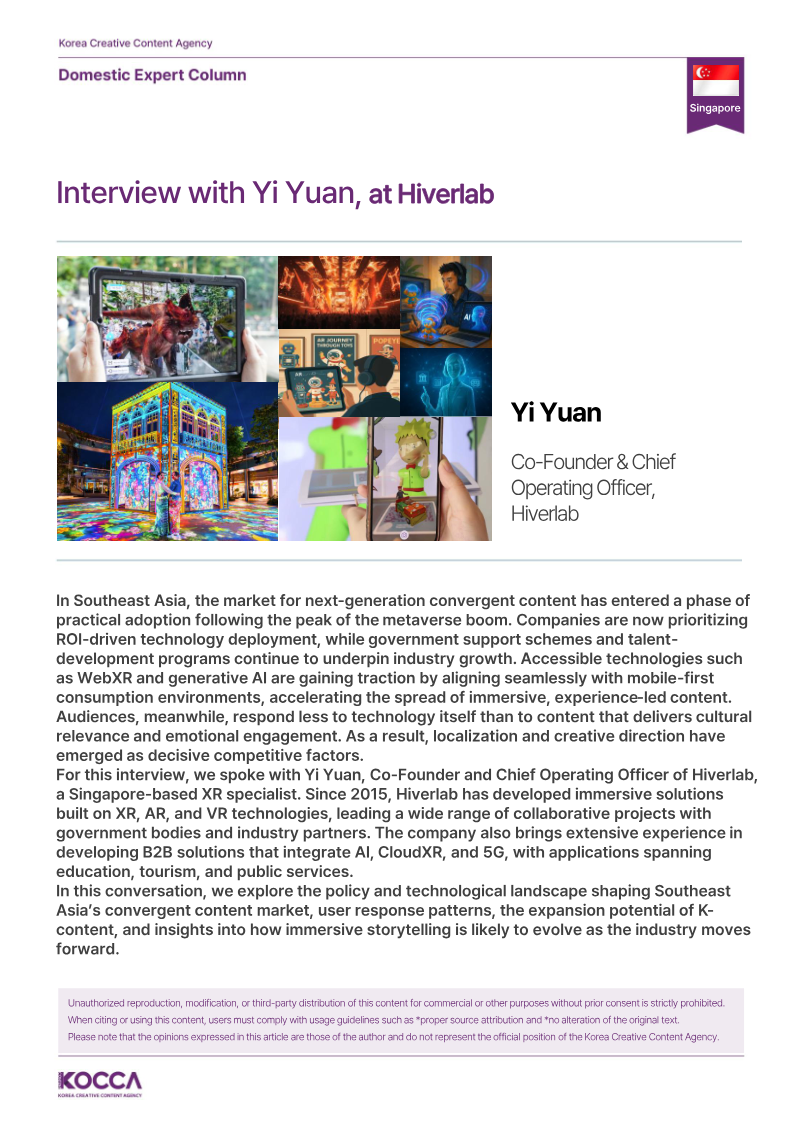
The interview underscores a shift in Southeast Asia’s convergent‑content market from speculative metaverse enthusiasm to a pragmatic, ROI‑driven landscape where augmented reality has become the primary vehicle for marketing and tourism initiatives. Growth is anchored in measurable outcomes such as cost‑reduction ratios and increased foot‑traffic, supported by government funding and a mobile‑first infrastructure that leverages WebXR and expanding 5G networks. Large‑scale AR deployments at heritage and tourist sites illustrate the sector’s scalability, emphasizing the necessity of culturally resonant storytelling, clear narrative structures, and quantitative metrics like dwell time and interaction density to assess engagement.
Effective experiences consistently incorporate gamified micro‑games and selfie‑style interactions that encourage user participation and social sharing. These design elements amplify interaction density and foster virality, reinforcing the importance of narrative quality over pure technological novelty. The chief operating officer highlights that AI‑generated, personalized storytelling—through digital humans and generative‑AI scripts—remains the chief catalyst for sustained user interest, with success measured by dwell time, interaction density and social‑virality indicators.
A principal commercial obstacle is the high bandwidth demand of simultaneous, large‑scale XR experiences. The rollout of 5G and cloud‑native architectures such as CloudXR has already mitigated latency and loading challenges, as demonstrated by the AR broadcast of Singapore’s Chingay festival in 2020. Continued expansion across the region will depend on further high‑bandwidth network deployment, sustained government infrastructure investment, and deeper integration of AI technologies to produce adaptive, immersive content.
- Southeast Asia’s convergent-content market has shifted from speculative metaverse projects to a pragmatic, ROI-driven focus on augmented reality for marketing and tourism.
- Success in the region is measured by quantitative metrics including dwell time, interaction density, and social-virality indicators rather than technological novelty.
- Large-scale AR deployments are currently anchored by government funding and mobile-first infrastructure, utilizing WebXR and 5G networks to ensure scalability.
- AI-generated personalized storytelling, including digital humans and generative-AI scripts, is identified as the primary catalyst for sustaining long-term user interest.
- High-bandwidth demands for simultaneous XR experiences are being addressed through cloud-native architectures like CloudXR, as evidenced by the 2020 AR broadcast of Singapore’s Chingay festival.
+1
KOCCA – Korea Creative Content AgencyJan 2025
Report30 pages
Growth of the Korean Emoticon Market: A New Distribution and Expansion Method for the K-Character Industry
The Korean emoticon market has evolved from a peripheral messaging feature into a multi‑billion‑won character‑IP industry, now valued at roughly KRW 1.5 trillion (≈US$1.2 trillion). This transformation is anchored by KakaoTalk, whose emoticon platform expanded from an initial KRW 100 billion base in the early 2010s to a dominant revenue stream that underpins a broader ecosystem of licensed characters and digital content. Over the past fourteen years, more than 850 000 distinct emoticons have been released, generating in excess of 300 billion individual sends, illustrating both high user engagement and the low‑sensitivity nature of the market’s cash flow.
The core of this growth lies in the development of unique intellectual‑property (IP) assets such as KakaoFriends and LINE Friends. These brands have transcended simple sticker usage to become central brand assets that are licensed across a spectrum of media, including merchandise, mobile games, animation, and information‑communication‑technology services. By converting emoticons into high‑value IP, companies have created diversified revenue channels that extend well beyond the messaging platform itself.
Export potential is accelerating, driven by corporate collaborations and strategic international expansion. Partnerships with established IP owners enable Korean firms to tap into global distribution networks, while the modular nature of emoticon‑based branding facilitates rapid adaptation to foreign markets. The overall trajectory suggests that the emoticon sector will continue to serve as a catalyst for the broader K‑character industry, reinforcing Korea’s position as a leading exporter of digital cultural content.
- The Korean emoticon market has grown into a KRW 1.5 trillion (≈US$1.2 trillion) industry, anchored by the KakaoTalk platform.
- Over the last 14 years, the market has seen the release of more than 850,000 distinct emoticons, resulting in over 300 billion individual sends.
- Emoticons have evolved from simple messaging features into high-value intellectual property (IP) assets, such as KakaoFriends and LINE Friends, that drive revenue across merchandise, mobile games, and animation.
- The industry has expanded significantly from its initial KRW 100 billion base in the early 2010s to become a primary revenue stream for digital content ecosystems.
- The sector’s growth is characterized by low-sensitivity cash flow and high user engagement, providing a stable foundation for broader K-character industry development.
+1
KOCCA – Korea Creative Content AgencyJan 2025
Report13 pages
Interview with Kim Yoo, License Manager at Bandai Namco Korea
The Japanese character market has evolved from a niche subculture into a mainstream value chain driven by a diverse demographic of high-spending fans. While male consumers maintain a strong presence in the traditional collectible figure segment, women in their 20s and 30s have emerged as a dominant force, shifting market demand toward lifestyle goods, customizable plush toys, and shareable social media content. This transformation is fueled by the global reach of streaming platforms, the normalization of fandom culture through K-pop, and an increasing consumer preference for immersive offline experiences such as pop-up stores and collaboration cafés.
Strategic success in this landscape requires a dual-track approach that balances mass-market accessibility with premium, limited-edition offerings. Current growth is heavily concentrated in cross-category collaborations where character intellectual properties intersect with fashion, digital goods, and the music industry. Navigating this market necessitates a deep understanding of multi-tiered licensing structures and a commitment to protecting the narrative integrity, or worldview, of each IP. Establishing long-term credibility through disciplined execution remains a prerequisite for international partners seeking to enter this competitive ecosystem.
Looking toward 2026, the industry is moving toward a hybrid model that prioritizes experiential content and convergence-driven trends. To remain competitive, businesses must develop the agility to identify these shifts early and execute initiatives swiftly. The integration of character IPs into broader cultural sectors like exhibitions and music suggests that the future of the market lies in creating holistic brand experiences rather than simple product manufacturing. This evolution underscores the necessity for strategic flexibility and rapid response to the changing tastes of a globalized fandom.
- The Japanese character market has shifted from a niche segment to a mainstream industry driven by high-spending female consumers in their 20s and 30s.
- Market demand is moving away from traditional collectible figures toward lifestyle goods, customizable plush toys, and content optimized for social media sharing.
- Strategic success requires a dual-track model that balances mass-market accessibility with premium, limited-edition product offerings.
- Growth is increasingly concentrated in cross-category collaborations that integrate character intellectual property with fashion, digital goods, and the music industry.
- The industry is transitioning toward a hybrid model by 2026 that prioritizes experiential, holistic brand experiences like pop-up stores and collaboration cafés over simple product manufacturing.
KOCCA – Korea Creative Content AgencyJan 2025
Report13 pages
Interview with Sarah Chung, Senior Manager at Disney Company
The interview underscores that the worldwide surge of Korean content is rooted in a “cocreator” fandom model, where streaming services offering seamless subtitle and dubbing options enable audiences to engage directly with material and co‑produce cultural moments. This participatory dynamic is amplified by nostalgia‑driven “comfort viewing” and the rapid diffusion of fan‑made short‑form clips on TikTok, which together reshape attention spans and create a feedback loop that fuels further consumption.
A key finding is that Korean productions are breaking out of traditional genre boundaries, as illustrated by titles such as The Glory, D.P., Sweet Home and Gyeongseong Creature. These series now contend not only with other OTT platforms but also with short‑form ecosystems like TikTok and YouTube, as well as user‑generated content. To secure global reach, Korean studios must prioritize distribution channels that combine extensive international footprints with aggressive off‑platform promotion, while exploiting AI‑driven recommendation engines to surface relevant titles amid an oversupply of options.
Looking ahead to 2026, success will depend on a balanced strategy that merges technological adaptability, clear conceptual storytelling, and format experimentation. Integrating nostalgia‑centric comfort viewing with cross‑platform interactive campaigns will allow Korean creators to navigate a fragmented global content landscape and maintain competitive relevance across both long‑form and short‑form media environments.
- The global success of Korean content is driven by a 'cocreator' fandom model, where streaming platforms leverage seamless localization tools to allow audiences to actively participate in cultural moments.
- Korean productions must now compete for attention against both traditional OTT platforms and short-form ecosystems like TikTok and YouTube, necessitating a shift in how content is marketed and consumed.
- To maintain global reach, studios must adopt a dual strategy of utilizing platforms with extensive international footprints while executing aggressive off-platform promotional campaigns.
- Success in a saturated market requires the integration of AI-driven recommendation engines to ensure content visibility amid an oversupply of available media options.
- Future competitive relevance through 2026 depends on blending nostalgia-driven 'comfort viewing' with cross-platform interactive campaigns that bridge long-form and short-form media.
KOCCA – Korea Creative Content AgencyJan 2025
Report10 pages
Interview with Lee, Su-Hyun: South Korea
The interview with Professor Lee Su‑Hyun of Seoul National University articulates digital transformation (DX) as a comprehensive restructuring of the Korean fashion value chain, extending beyond e‑commerce to encompass AI‑driven design, smart‑factory automation, and data‑centric marketing. By leveraging generative AI for 3‑D virtual prototyping, automated sewing, digital twins, and metaverse‑enabled retail experiences, the industry can cut sample costs, shorten lead times, and enhance personalized consumer interactions while supporting carbon‑neutral objectives such as on‑demand production and circular‑economy tracking.
Professor Lee emphasizes that smart apparel remains in early commercial stages, with functional niches in sports, healthcare, and disaster safety already demonstrating pilot deployments. Critical technical barriers include washability and durability of conductive fibers, sensor performance after repeated laundering, and the need for flexible, miniaturized battery solutions. Rapid advances in printed textile batteries and energy‑harvesting technologies are narrowing these gaps, yet mass‑production capacity and system integration lag behind leading markets in the United States and Germany.
Strategic recommendations focus on three business models: subscription‑based health and fitness services, interoperable platform modules detachable across garments, and specialized ceremonial wear where visible technology adds value. Successful scaling will require coordinated industry‑academia curricula, a robust talent pipeline, national standardization participation (e.g., IEC TC124), shared testing facilities, and proactive IP support to translate Korea’s strong patent portfolio into globally competitive products.
Looking ahead to 2026, AI and sustainability are projected to dominate the fashion sector. AI will become an essential capability across design, inventory, and personalization, while sustainability will drive digital traceability, carbon‑neutral manufacturing, and circular‑economy initiatives, together reshaping competitiveness criteria for the Korean fashion industry.
- South Korea’s fashion industry is undergoing a comprehensive digital transformation (DX) that integrates generative AI for 3-D virtual prototyping, smart-factory automation, and data-centric marketing to reduce sample costs and lead times.
- The adoption of on-demand production and digital traceability is being prioritized to meet carbon-neutral objectives and support circular-economy initiatives within the fashion value chain.
- Smart apparel development is currently limited to functional niches in sports, healthcare, and disaster safety, with technical progress hindered by the durability of conductive fibers and the need for miniaturized, flexible battery solutions.
- To achieve global competitiveness by 2026, the industry must overcome current lags in mass-production capacity and system integration compared to the United States and Germany.
- Strategic business models for smart apparel include subscription-based health services, modular, detachable technology components, and high-value ceremonial wear.
KOCCA – Korea Creative Content AgencyJan 2025
Report7 pages
Interview with Keunkyo Kim, Head of Global Business at NC AI
The interview articulates NC AI’s transformation from a game‑focused research lab into a national industrial‑AI hub, positioning Korea as a global center for “K‑AI.” It outlines the company’s ambition to leverage fourteen years of game‑AI expertise to drive cross‑industry innovation, emphasizing that AI has moved from a supporting role to a core driver of gameplay, content creation, and broader economic competitiveness.
NC AI, a subsidiary of NCSoft, has built a proprietary large‑language model called VARCO and the VARCO 3D engine, which can generate near‑realistic, physics‑based 3D environments from text or images. The firm was selected as one of five leaders in Korea’s Independent Foundation Model project and became the first Korean entity to deploy its LLM on AWS. An open‑source release of VARCO Vision 2.0 attracted over 10 000 downloads within ten days, reflecting a strategic push for global adoption and a vibrant developer ecosystem.
The company’s real‑time processing and reinforcement‑learning capabilities, honed in massive MMORPG settings, are now applied to digital twins for manufacturing, robotics, smart‑city, and defense sectors. NC AI pursues a dual‑track model—developing a 200‑billion‑parameter LLM while simultaneously creating lightweight, edge‑optimized multimodal diffusion models—to balance scale with field efficiency. Its proprietary safety filter, Safeguard, has been integrated into NCSoft’s NCER chatbot, underscoring a commitment to AI trustworthiness and standards collaboration.
Looking ahead, NC AI leads a consortium of 54 organizations to produce industry‑specific AI that validates in real‑world environments, aiming for Korean AI sovereignty and global leadership. By enabling user‑generated content through VARCO 3D, Voice, and animation tools, the firm promotes a “everyone can be a creator” ethos, encouraging young talent to contribute to a vertically integrated AI ecosystem that links industry, government, and academia and positions Korea as a powerhouse in the international AI landscape.
- NC AI is leveraging 14 years of MMORPG-based reinforcement learning and real-time processing expertise to expand from gaming into industrial sectors, including manufacturing, robotics, smart cities, and defense.
- The company is developing a dual-track AI strategy that balances a 200-billion-parameter large language model with lightweight, edge-optimized multimodal diffusion models for field efficiency.
- NC AI’s proprietary VARCO 3D engine enables the generation of physics-based 3D environments from text or images, while the open-source VARCO Vision 2.0 achieved over 10,000 downloads within ten days of release.
- As a leader in Korea’s Independent Foundation Model project, NC AI is the first Korean entity to deploy its proprietary LLM on AWS and currently heads a 54-organization consortium to drive industry-specific AI adoption.
- The firm is prioritizing AI safety and trustworthiness through its proprietary 'Safeguard' filter, which is already integrated into the NCER chatbot.
+1
KOCCA – Korea Creative Content AgencyJan 2025
Report60 pages
PowerUP: Spelbranschen – en svensk basnäring
Sweden’s video‑game sector is positioned as a culturally driven, “born‑global” industry that, despite generating more than SEK 3.5 billion in revenue and employing over 15 000 staff abroad, remains fragmented and under‑supported at the national level. The analysis maps the ecosystem of roughly 1 000 firms—87 % micro‑enterprises, 42 % with no employees, and only 1 % large companies—highlighting that 97 % of studios rely on regional clusters such as Skövde, Malmö and the northern hub, which suffer from chronic under‑financing and a lack of long‑term planning. The sector’s growth is constrained by low legitimacy, inadequate national financing mechanisms, and regulatory barriers that impede talent recruitment, especially for start‑ups and regional firms.
Key findings show a mismatch between the sector’s cultural impact—average player age 32, documented benefits for creativity, problem‑solving, STEM interest and mental health—and the absence of coordinated public‑private structures to translate these gains into economic value. Comparative data reveal Sweden’s early‑stage funding to be far below peer EU nations, while the talent pipeline is strained, with a projected need for 25 000 developers over the next decade and 40 % of the current workforce being foreign‑born. The report recommends establishing a comprehensive national game strategy, a dedicated investment fund modeled on Industrifonden, long‑term financing for regional clusters, and a Swedish games institute to de‑risk commercial projects and retain IP ownership.
To secure sustainable growth, the analysis calls for reform of innovation metrics, inclusion of game‑specific occupations in labour policy, expanded vocational and research education, and the separation of cultural and commercial funding streams. By implementing these measures, Sweden could elevate its position from the EU’s fourth‑largest producer to a leading contender alongside France and Germany by 2025.
- Sweden's video-game sector requires a national strategy and a dedicated investment fund to support an ecosystem of 1,000 firms, 87% of which are micro-enterprises.
- The industry faces a critical talent shortage with a projected need for 25,000 new developers over the next decade, while 40% of the current workforce is already foreign-born.
- Despite generating over SEK 3.5 billion in revenue and employing 15,000 staff abroad, the sector is hindered by inadequate national financing and regulatory barriers that impede start-up growth.
- 97% of studios are concentrated in regional clusters like Skövde, Malmö, and northern hubs, which currently suffer from chronic under-financing and a lack of long-term planning.
- The sector remains highly fragmented, with 42% of firms having no employees and only 1% classified as large companies.
DataspelsbranschenJan 2025
Report48 pages
Uppdaterad Statistik för de Kulturella och Kreativa Branscherna: Sverige
Sweden’s cultural and creative economy is quantified through an extensive 2023 update that records more than 140 000 firms employing roughly 250 000 people and generating over SEK 650 billion in turnover. Limited companies account for the bulk of activity (SEK 607 billion from 48 000 entities), while sole traders and other legal forms contribute SEK 16 billion and SEK 30 billion respectively. Revenue per employee averages SEK 2.6 million and intangible assets are valued at SEK 20 billion, underscoring the sector’s high productivity and knowledge intensity.
The core thesis asserts that existing SNI‑code classifications markedly under‑represent large and fast‑growing components such as digital platforms, video‑games, furniture design, and numerous craft activities, leading to distorted employment, value‑added and regional statistics. By revising the SNI list, eliminating irrelevant codes, and cross‑checking company accounts, a more accurate database—derived from roughly 73 000 active limited companies and refined to about 40 000 distinct firms—has been assembled. The transition to the 2025 SNI framework introduces five‑digit codes that improve granularity for design, illustration and literary arts, though short‑term classification gaps persist.
Turnover concentration is evident in a few dominant markets: music (SEK 11.4 billion, 12 % nominal growth), cultural events (SEK 42.3 billion), design (SEK 78.5 billion) and video‑games (SEK 34.6 billion). Data collection relied on commercial databases because Bolagsverket’s APIs cannot filter by SNI, highlighting a systemic data‑access limitation. The report recommends appointing a lead agency—suggested as Tillväxtverket—to oversee an annual analytical publication and maintain a comprehensive KKB database that integrates cultural VAT, service exports, firm size, region and activity type, ensuring reliable, comparable statistics across Sweden’s cultural and creative sectors.
- Sweden’s cultural and creative economy comprises over 140,000 firms and 250,000 employees, generating a total annual turnover exceeding SEK 650 billion.
- Limited companies drive the vast majority of sector revenue, contributing SEK 607 billion of the total turnover compared to SEK 46 billion from other legal entities.
- The sector demonstrates high productivity and knowledge intensity, with an average revenue per employee of SEK 2.6 million and intangible assets valued at SEK 20 billion.
- Key industry segments include design (SEK 78.5 billion), cultural events (SEK 42.3 billion), video games (SEK 34.6 billion), and music (SEK 11.4 billion, reflecting 12% nominal growth).
- Current SNI-code classifications significantly under-represent high-growth areas like digital platforms and video games, necessitating a transition to a more granular 2025 five-digit SNI framework.
Kreativ SektorJan 2025
Report32 pages
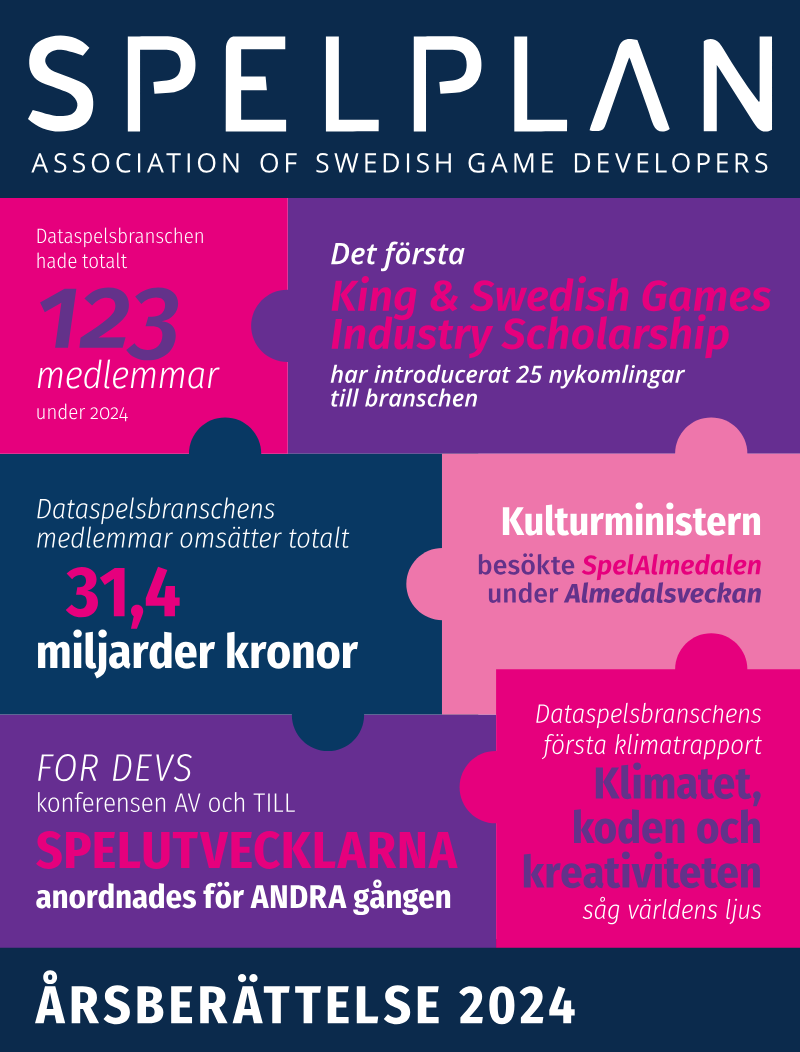
Association of Swedish Game Developers: 2024 Report
The 2024 overview of Sweden’s games industry presents a comprehensive assessment of the sector’s performance, challenges, and forward‑looking dynamics within the Swedish market. It argues that, despite a noticeable wave of studio closures, the industry remains resilient and is entering a phase of regeneration driven by regional clusters, targeted investment schemes, and internationally successful titles.
Analysis of the year shows that development activity is increasingly concentrated in hubs such as Skövde, where new studios have emerged and produced world‑hit games like Satisfactory, a title that secured both D.I.C.E. and Golden Joystick awards. This creative output underscores Sweden’s capacity to generate globally competitive products even as legacy firms exit the market. Growth is attributed largely to coordinated programmes—including Redeye Gaming Day, Invest in Games, and the EU‑funded CDG‑Booster mentoring cohort—that channel capital, mentorship, and market access to emerging developers.
The findings highlight a sector that, while contending with consolidation pressures, is expanding its export footprint and sustaining employment through the formation of new companies and the scaling of award‑winning projects. Investment in talent development and cluster formation emerges as a decisive factor in maintaining Sweden’s reputation as a leading European game‑development hub.
Overall, the 2024 snapshot confirms that Sweden’s games industry, spanning development, publishing, and ancillary services, continues to generate significant economic value and cultural impact, positioning itself for sustained growth in the coming years.
- Sweden’s games industry is undergoing a structural shift characterized by legacy studio closures offset by the emergence of new, high-performing development hubs.
- Regional clusters like Skövde have become primary drivers of industry output, exemplified by the commercial and critical success of the title Satisfactory.
- Industry resilience is supported by targeted support initiatives, including Redeye Gaming Day, Invest in Games, and the EU-funded CDG-Booster mentoring program.
- The sector is maintaining its international export footprint and employment levels by successfully scaling new companies and award-winning projects.
- Strategic investment in talent development and cluster-based infrastructure is identified as the core factor sustaining Sweden’s position as a leading European game-development hub.
+1
Spelplan-ASGDJan 2025
Report68 pages
Spelutvecklarindex: Sweden 2025
The analysis maps Sweden’s game‑development landscape, arguing that the sector’s rapid expansion has positioned the country as a leading European hub while simultaneously exposing new regulatory and societal challenges. Over the past twenty years the industry has multiplied from 71 firms with SEK 0.5 billion in revenue to more than 1 100 companies generating roughly SEK 37 billion—an increase of about 7 500 %—and employing 9 130 staff domestically, complemented by an additional 11 000 workers abroad. This growth underscores the sector’s escalating economic weight and its contribution to national employment.
Geographically, the ecosystem spans all Swedish counties, comprising over 300 development studios. The highest concentrations are found in Stockholm and its surrounding regions, notably Uppsala, Värmland and Örebro, where studio density exceeds twelve entries per county. Domestically, Swedish‑produced titles commanded the majority share of the Steam market in 2024, reflecting strong consumer preference for locally created content and reinforcing the sector’s market relevance.
Artificial intelligence has become a dual‑purpose tool within the industry: it is employed to generate novel game assets and to identify players exhibiting signs of radicalisation or harassment. The analysis stresses that radicalisation often migrates from in‑game interactions to external, unmoderated forums, distinguishing it from broader online hate. Consequently, it calls for coordinated, cross‑border interventions that involve regulators, academic researchers and game companies to mitigate these risks while preserving the sector’s innovative momentum.
- Sweden’s game industry has grown to over 1,100 companies generating SEK 37 billion in annual revenue, a 7,500% increase from the SEK 0.5 billion recorded twenty years ago.
- The sector currently employs 9,130 staff domestically and an additional 11,000 workers abroad.
- Swedish-produced titles held the majority market share on Steam in 2024, demonstrating strong consumer demand for local content.
- The industry ecosystem is comprised of over 300 development studios distributed across all Swedish counties, with the highest density concentrated in Stockholm, Uppsala, Värmland, and Örebro.
- Artificial intelligence is being utilized as a dual-purpose tool for both generating game assets and monitoring player behavior for signs of radicalization and harassment.
+1
DataspelsbranschenJan 2025
Report71 pages
State of AI Apps Report 2025
The analysis quantifies the rapid expansion of generative‑AI applications in the first half of 2025, documenting 1.6 billion downloads and $1.2 billion in in‑app‑purchase revenue. This represents a 67 percent increase in downloads and a 200 percent jump in revenue compared with the second half of 2024, indicating a pronounced acceleration in user adoption and monetisation. Engagement metrics rose in tandem, underscoring the sector’s heightened activity during this period.
User demographics reveal a pronounced male and youth bias: roughly 60 percent of users are male and nearly 70 percent are under 35. While flagship services such as ChatGPT and Google Gemini attract comparatively balanced audiences and exhibit strong cross‑app overlap, niche offerings—including Grok and DeepSeek—tend to cluster with privacy‑focused, crypto‑trading, and gaming user personas. This segmentation highlights divergent appeal across the generative‑AI landscape.
Advertising investment intensified, with OpenAI’s major campaign propelling it into the top‑ten spenders in key markets such as the United States, India and South Korea. AI‑driven ad creatives increasingly employ light‑hearted, animal‑centric visuals while emphasizing concrete everyday utilities, exemplified by Google Gemini’s car‑warning guidance and Microsoft Copilot’s quiz‑making and recipe‑generation tools. Spend estimates, tracked across U.S. platforms including Reddit, LinkedIn, TikTok and YouTube, illustrate the breadth of digital‑advertising channels leveraged.
Overall, the findings portray a sector experiencing explosive growth, a skewed yet evolving user base, and a surge in AI‑powered marketing activity across major global markets during H1 2025.
- Generative AI applications experienced explosive growth in H1 2025, reaching 1.6 billion downloads and $1.2 billion in in-app purchase revenue.
- Revenue growth significantly outpaced adoption, with a 200 percent increase in in-app purchase revenue and a 67 percent rise in downloads compared to H2 2024.
- The user base is heavily skewed toward younger males, with approximately 60 percent of users being male and nearly 70 percent under the age of 35.
- While flagship services like ChatGPT and Google Gemini maintain broad appeal, niche AI apps such as Grok and DeepSeek are increasingly associated with privacy-focused, crypto-trading, and gaming demographics.
- OpenAI has become a top-ten advertising spender in major markets including the United States, India, and South Korea.
+2
Sensor TowerJan 2025
Report40 pages
Gaming App Insights Report: 2025 Edition
The analysis tracks the state of the global mobile‑gaming market through 2024 and projects its trajectory toward 2025, emphasizing how emerging AI‑driven personalization will shape growth. It establishes that the sector is recovering from the volatility of 2023, with worldwide app installs climbing 4 % year‑over‑year in 2024, even as average session length contracted. Core user engagement metrics, however, show modest decline: day‑1 retention fell from 28 % to 27 % and median revenue per active user dropped from $0.31 to $0.28, indicating pressure on traditional monetization models. In contrast, advertising efficiency improved, reflected in higher installs per mille (IPM) and stronger ad‑performance indicators across major markets.
The report’s geographic scope is global, encompassing all major mobile‑gaming regions, and its temporal frame spans the 2023‑2025 period. It integrates data from app stores, ad networks, and cross‑platform measurement tools to deliver a comprehensive view of user acquisition, retention, and revenue trends. The central thesis posits that the next wave of growth will be powered by AI‑enabled, culturally tailored experiences that adapt difficulty, blend monetization formats, and deploy live events to boost lifetime value. Developers and marketers who adopt a metrics‑focused, AI‑augmented approach—identifying pivotal in‑game moments and steering users toward optimal pathways—are projected to achieve the most scalable expansion. Cross‑platform analytics suites are highlighted as essential for delivering the visibility required to implement these strategies effectively.
- Global mobile-gaming app installs grew by 4% year-over-year in 2024, signaling a recovery from 2023 market volatility.
- Monetization is under pressure as median revenue per active user declined from $0.31 to $0.28.
- User retention metrics weakened in 2024, with day-1 retention falling to 27% from the previous year's 28%.
- Advertising efficiency has improved, evidenced by higher installs per mille (IPM) and stronger performance indicators across major global markets.
- Average session lengths contracted in 2024, contributing to a modest overall decline in core user engagement metrics.
+2
AdjustJan 2025
Report37 pages
Japan Market Report 2025
The Japanese games market represents a unique and highly lucrative landscape, accounting for 9.1% of global games revenue despite containing only 2.2% of the global player base. Average revenue per user is significantly higher in Japan than in Western markets, with Japanese players spending approximately $223 compared to $145 in the United Kingdom. While the market is characterized by a strong preference for domestic franchises and Nintendo’s 70% dominance of console hardware, a substantial $2.5 to $3.0 billion opportunity exists for international stakeholders when excluding mobile and Nintendo platforms.
Demographic and behavioral data indicates that Japan’s PC and console player base is generally older than its Western counterparts. Player motivations also diverge sharply from global trends; Japanese gamers prioritize narrative depth, character design, and solo play, whereas Western players favor open worlds, high-end graphics, and competitive multiplayer. Genre preferences further illustrate this divide, with Japanese console players gravitating toward single-player RPGs and fantasy themes, while PC players increasingly embrace shooters and lower-priced co-op experiences.
The market has seen rapid PC revenue growth over the last seven years, though this trajectory is expected to stabilize through 2027. Conversely, the console segment has faced recent declines attributed to the Nintendo Switch lifecycle and a weaker slate of premium releases. International publishers face specific macroeconomic challenges, notably the weakening Japanese Yen against the U.S. Dollar. Despite these headwinds, titles such as Apex Legends and Genshin Impact have maintained massive free-to-play success, signaling continued potential for well-positioned global titles. This analysis utilizes data from the Newzoo Global Gamer Study, incorporating surveys from over 73,000 gamers across 37 markets to provide a comprehensive view of the 2025 landscape.
- Japan generates 9.1% of global games revenue from only 2.2% of the global player base, with an average revenue per user of $223 compared to $145 in the UK.
- International stakeholders have a $2.5 to $3.0 billion market opportunity when excluding mobile and Nintendo platforms, which currently command 70% of console hardware dominance.
- Japanese gamers prioritize narrative depth, character design, and solo play, contrasting with Western preferences for open worlds, high-end graphics, and competitive multiplayer.
- While PC revenue has experienced rapid growth over the last seven years, this trajectory is projected to stabilize through 2027.
- The console segment is currently facing declines due to the Nintendo Switch lifecycle and a weaker slate of premium releases.
+1
UKIE – UK Interactive EntertainmentJan 2025
Report13 pages
Shooter Games on Live Streaming Mini-Report
This analysis explores the landscape of shooter games on live streaming platforms from 2019 through 2025, tracking viewership trends, subgenre shifts, and the impact of esports. While shooters remain a cornerstone of the industry—consistently accounting for at least 20% of all gaming viewership—the genre has seen a 6% decline in market share since 2022. By 2024, shooters represented approximately one-in-five gaming hours watched, totaling 6.1 billion hours.
The data reveals a significant transition in subgenre dominance. Tactical shooters overtook battle royale games in 2023 to become the most-watched subgenre. This shift is largely driven by the sustained popularity of Valorant and Counter-Strike, which together claim 90% of tactical shooter viewership. Conversely, the battle royale subgenre has seen its viewership halve since its 2020 peak, despite the continued popularity of Fortnite. Other segments, such as extraction and arena shooters, have maintained stable but smaller market shares, with Escape From Tarkov accounting for nearly two-thirds of all extraction shooter hours.
Esports serves as a primary engine for the genre's visibility. By late 2025, nearly half of all Counter-Strike viewership was generated by esports events. Valorant maintains a balanced global presence, holding significant viewership shares across North America, Europe, Asia, and the Southern Hemisphere. In contrast, Counter-Strike remains heavily reliant on the European market, while PUBG Mobile dominates the mobile-centric Asian market.
The analysis also highlights the influence of individual creators and variety streamers. In 2024, Gaules emerged as the leading shooter streamer with 79.2 million hours watched. While Twitch remains the dominant platform for top creators, accounting for 73% of the top ten's viewership, the data shows high viewer overlap between franchises. For example, over 40% of Valorant viewers also engage with other tactical shooters, suggesting strong community fluidity across the genre. Methodology for these findings includes data aggregation from all major streaming platforms, excluding TikTok Live, with specific sentiment analysis conducted on Twitch chat data.
- Shooter games remain a pillar of live streaming, accounting for 6.1 billion hours watched in 2024, though their total market share has declined by 6% since 2022.
- Tactical shooters became the most-watched subgenre in 2023, with Valorant and Counter-Strike capturing 90% of that segment's viewership.
- Battle royale viewership has halved since its 2020 peak, despite the sustained popularity of Fortnite.
- Esports is a critical driver of engagement, accounting for nearly 50% of all Counter-Strike viewership by late 2025.
- Viewer demographics are geographically segmented, with Counter-Strike concentrated in Europe, PUBG Mobile dominating the Asian market, and Valorant maintaining a balanced global presence.
+2
Stream HatchetJan 2025
Report46 pages
Yearly Live Streaming Trends Report 2024
The live streaming industry experienced a period of stabilization and strategic maturation throughout 2024, characterized by a modest 3% year-over-year increase in total hours watched across major platforms. This growth brought the global annual viewership to approximately 35 billion hours, signaling a shift from the volatile surges of previous years toward a more sustainable, long-term trajectory. While Twitch maintained its position as the market leader in terms of total hours watched, its market share faced increasing pressure from YouTube Gaming and Kick, the latter of which saw a 45% increase in viewership as it successfully attracted high-profile creators through non-exclusive contracts and aggressive revenue-sharing models.
Geographically, the Asia-Pacific region remains the primary engine for mobile streaming growth, while North American and European markets show a deepening preference for high-production "eventized" content. Non-gaming content, specifically the Just Chatting category, continues to dominate the landscape, accounting for nearly 15% of all platform activity. However, the competitive gaming sector saw a resurgence driven by the massive success of tactical shooters and the expansion of co-streaming rights for major esports tournaments. These community-driven broadcasts often outperformed official channels, representing a fundamental shift in how audiences consume professional competitive play.
The integration of artificial intelligence and enhanced monetization tools defined the technological landscape of the year. Creators increasingly utilized AI-driven moderation and clip-generation tools to maximize reach across short-form video platforms like TikTok and Instagram Reels, which now serve as the primary discovery funnel for live broadcasts. Brands have responded by shifting budgets toward long-term creator partnerships rather than one-off sponsorships, seeking to capitalize on the high engagement rates of mid-tier streamers who boast more dedicated, niche communities. As the industry moves into 2025, the convergence of live commerce and interactive broadcasting is expected to become the next major frontier for platform revenue.
- The live streaming industry reached 35 billion hours watched in 2024, reflecting a stable 3% year-over-year growth rate as the market shifts toward long-term sustainability.
- Kick grew its viewership by 45% in 2024 by leveraging aggressive revenue-sharing models and non-exclusive contracts to challenge Twitch’s market leadership.
- The 'Just Chatting' category remains the dominant content type, accounting for nearly 15% of all platform activity across the industry.
- Co-streaming rights for major esports tournaments have fundamentally changed consumption habits, with community-driven broadcasts frequently outperforming official tournament channels.
- Short-form video platforms like TikTok and Instagram Reels have become the primary discovery funnels for live streaming, driven by the adoption of AI-powered clip-generation tools.
+2
Stream HatchetJan 2025
Report26 pages
Global Sports Tech Market Report H1 2025
In the first half of 2025 the global sports‑technology sector recorded approximately $52 billion in announced or closed transactions, underscoring a rapid acceleration of both merger‑and‑acquisition activity and capital raising. Roughly $32 billion stemmed from 233 M&A deals, while a record‑high $6.6 billion was secured through 239 private‑placement rounds, more than 80 % of which involved early‑stage companies. The capital influx was driven by a mix of strategic consolidations—most notably TSG Consumer’s $1.5 billion acquisition of EOS Fitness and RTL’s $613 million purchase of Sky Deutschland—alongside a wave of targeted investments such as Valeas’s $110 million majority stake in Ticketmanager, Genstar’s acquisition of Playmetrics for integration with Stack Sports, and IMG’s takeover of SportsRecruits. Deal multiples varied across subsectors, reflecting divergent growth trajectories within wearables, fan‑engagement platforms, and performance‑analytics solutions.
Geographically, the activity spanned North America, Europe and emerging markets, with transaction processing centralized through Drake Star Securities LLC in the United States and its UK affiliate, Drake Star UK Limited, both operating under FINRA regulation and SIPC membership. This infrastructure ensures compliance and investor protection for institutional participants. The concentration of early‑stage financing and the prevalence of large‑scale consolidations together signal a market transitioning from fragmented innovation toward integrated platforms capable of delivering end‑to‑end sports experiences. The data suggest that investors and strategic acquirers view the sector as a high‑growth arena, positioning it for continued expansion and deeper consolidation throughout the remainder of 2025.
- The global sports tech market reached a total deal value of $51.9 billion in H1 2025 across 503 announced or closed transactions.
- M&A activity dominated the sector with $32.2 billion in disclosed deal value across 233 deals, led by TSG Consumer’s $1.5 billion acquisition of EōS Fitness.
- Private placements hit a record $6.6 billion across 239 deals, highlighted by Infinite Reality raising $3 billion and DAZN securing $1.8 billion.
- Investor appetite for new sports-focused capital remains high with over $3.5 billion in new funds announced, including the $1.2 billion Checketts Sports fund.
- Disney acquired a 70% stake in FuboTV for $220 million in cash and a $145 million loan, creating a provider with 6.2 million subscribers.
+1
Drake Star PartnersJan 2025