Whitepaper19 pages
Monetization Landscape for Video Games in MENA
The gaming market across the MENA-3 region—comprising Saudi Arabia, the United Arab Emirates, and Egypt—is undergoing a period of rapid expansion, with total revenue projected to reach $2.7 billion by 2028. This growth is fueled by a confluence of high internet penetration, significant government investment, and a young, tech-savvy demographic. While the region presents a lucrative opportunity, it remains highly fragmented, necessitating nuanced monetization strategies that account for stark economic differences, such as the preference for premium and subscription models in wealthy Gulf states versus the dominance of free-to-play structures in Egypt.
A critical barrier to entry in this market is the low penetration of traditional credit cards, which has historically hindered revenue conversion. To address this, developers are increasingly shifting toward Direct-to-Consumer platforms. This strategic pivot allows companies to bypass high app store commissions while integrating essential local digital wallets and alternative payment methods. By adopting these flexible, localized payment infrastructures, developers can effectively reach the region’s significant unbanked and underbanked populations, ensuring broader accessibility and higher conversion rates.
Recent performance data underscores the efficacy of this localized approach, as evidenced by a 12.6% increase in regional sales and a 45% surge in games distributed through D2C ecosystems over the past two years. Long-term success in the MENA region depends on a developer’s ability to navigate these complex payment landscapes while simultaneously prioritizing cultural adaptation. By combining region-specific pricing strategies with multi-platform engagement, stakeholders can better capitalize on the region’s burgeoning digital economy and secure a sustainable foothold in this high-growth market.
- The MENA-3 gaming market (Saudi Arabia, UAE, and Egypt) is projected to reach $2.7 billion in total revenue by 2028.
- Direct-to-Consumer (D2C) distribution has surged by 45% over the past two years, helping developers bypass app store commissions and integrate local payment methods.
- Localized payment strategies, including the integration of digital wallets, have contributed to a 12.6% increase in regional sales.
- Monetization models must be bifurcated by economic region, favoring premium and subscription services in wealthy Gulf states while prioritizing free-to-play structures in Egypt.
- Low traditional credit card penetration remains a primary barrier to entry, necessitating the adoption of alternative payment infrastructures to capture unbanked and underbanked demographics.
+1
Niko PartnersJan 2025
Report23 pages
PC & Console Year in Review: 2025
The 2025 PC and Console Year in Review provides a comprehensive analysis of the global gaming landscape, focusing on market performance, consumer behavior, and development trends. The primary thesis highlights that while pre-launch marketing and wishlist campaigns remain foundational for success, post-release player reception and the integration of social, co-op elements are the primary drivers of long-term revenue and sustainability. The analysis covers the period from January 1, 2025, through late 2025, utilizing proprietary data estimates to track sales, player engagement, and platform distribution across global markets.
Key findings indicate that the premium game market remains dominant, accounting for 78% of Steam’s $16.8 billion revenue. Indie developers continue to capture significant market share, contributing over 25% of Steam’s total revenue, with "Triple-I" titles demonstrating exceptional return on investment. Geographically, China has solidified its position as a critical market, serving as the top region for Steam and a major driver for both Western and Eastern-developed titles. Furthermore, the data reveals a shift in marketing efficacy; while wishlist counts are rising, conversion rates are declining, forcing studios to experiment with in-game incentives and community-driven engagement strategies.
Genre trends show that action, adventure, and RPG titles continue to lead in player interest, though "cute" and atmospheric games experienced significant year-over-year growth in revenue. Co-op mechanics have emerged as a vital pillar for commercial success, with 11 of the top 20 highest-grossing titles featuring cooperative elements. From a technical perspective, Unreal Engine maintains its status as the market leader for AA and AAA development, while many studios continue to leverage proprietary engines for large-scale projects. The report concludes that while pre-launch hype is a useful tool for visibility, the post-release sales trajectory is ultimately dictated by player sentiment and the ability of a title to foster sustained social interaction.
- Premium games dominate the market, accounting for 78% of Steam’s $16.8 billion total revenue in 2025.
- Cooperative gameplay is a primary driver of commercial success, with 11 of the top 20 highest-grossing titles featuring co-op mechanics.
- Indie developers contribute over 25% of Steam’s total revenue, with 'Triple-I' titles delivering exceptional return on investment.
- China has become the top global region for Steam, serving as a critical market for both Western and Eastern-developed titles.
- Marketing efficacy is shifting as wishlist counts rise while conversion rates decline, necessitating a move toward in-game incentives and community-driven engagement.
+3
Alinea AnalyticsJan 2025
Report38 pages
From Data to Personas: The 2025 Guide to US Gaming Audiences
The modern gaming landscape in the United States has evolved into a diverse, cross-generational ecosystem that fundamentally challenges outdated stereotypes of the solitary, young male player. Current data indicates that today’s gaming population is characterized by middle-to-high-income individuals who prioritize quality, convenience, and social connectivity. Far from being sedentary, these consumers frequently integrate digital play with active, outdoor lifestyles, sports participation, and family-oriented activities. This shift reflects a broader demographic reality where gaming serves as a primary form of entertainment across all age groups and socioeconomic backgrounds.
Consumer behavior within this segment extends well beyond the digital realm, as gamers demonstrate significant purchasing power and a strong affinity for premium brands, casual dining, and higher education. Analysis reveals a consistent tendency for these audiences to over-index on online shopping and delivery services, favoring mainstream, value-oriented brands across the retail and fitness sectors. These habits suggest that gaming is not an isolated hobby but a central component of a lifestyle defined by convenience and digital-physical integration.
Segmentation reveals distinct behavioral patterns that allow for more nuanced marketing strategies. For instance, sports-oriented gamers gravitate toward fast-food and convenience-driven brands, whereas those who favor board, puzzle, and trivia games tend to be older, more education-focused, and financially prudent. By moving past monolithic industry tropes, advertisers can leverage these granular insights to execute more precise, data-driven campaigns. Ultimately, the gaming audience represents a highly active, diverse, and economically influential consumer base that requires sophisticated engagement strategies tailored to specific lifestyle personas rather than generalized assumptions.
- The US gaming population is characterized by middle-to-high-income individuals who integrate digital play into active, outdoor, and family-oriented lifestyles rather than operating as a sedentary, isolated demographic.
- Gamers demonstrate significant purchasing power with a strong affinity for premium brands, higher education, and convenience-based services like online shopping and delivery.
- Gaming has evolved into a cross-generational, mainstream form of entertainment that transcends traditional age and socioeconomic stereotypes.
- Consumer behavior within the gaming segment is highly segmented, with sports-oriented gamers favoring fast-food and convenience brands, while puzzle and trivia gamers skew older and more financially prudent.
- Effective marketing in 2025 requires moving away from monolithic industry tropes in favor of granular, data-driven strategies tailored to specific lifestyle personas.
+2
AnzuJan 2025
Report74 pages
Games Industry Employment Survey: Europe 2025
The European games industry is currently navigating a period of profound instability, characterized by widespread layoffs and a significant exodus of talent. Over the past year, 26% of professionals have faced involuntary unemployment, with junior-level staff suffering a disproportionate 39% exit rate. This volatility is driven by a transition from rapid market expansion to a focus on operational optimization, further complicated by the rapid integration of artificial intelligence. While 63% to 69% of the workforce now utilizes AI for core tasks, this shift has fostered deep-seated skepticism among creative and quality assurance roles regarding long-term job security and the potential devaluation of human expertise.
Financial dissatisfaction has become a defining feature of the current landscape, exacerbated by salary freezes, reduced bonuses, and a persistent gender pay gap. With over a third of companies eliminating financial bonuses entirely, salary has emerged as the primary motivator for 87% of employees. This economic pressure, combined with a lack of structured support—such as the absence of dedicated diversity and inclusion specialists in 67% of firms—has contributed to a sharp decline in employee engagement. Burnout, affecting up to 63% of the workforce, and ineffective management are now the leading drivers for professionals considering career changes or leaving the industry altogether.
Despite these challenges, the workforce remains committed to hybrid work models, though a growing disconnect exists between employee preferences for flexibility and actual workplace mandates. Relocation trends have shifted toward a pragmatic focus on cost-of-living stability rather than traditional geographic mobility. As the industry matures, the data underscores a critical need for improved management practices and better alignment between organizational goals and employee well-being to mitigate the ongoing loss of talent and restore professional morale across the European sector.
- The European games industry is experiencing significant volatility, with 26% of professionals facing involuntary unemployment and a 39% exit rate among junior-level staff.
- Financial dissatisfaction is widespread, as 87% of employees now prioritize salary above all else following salary freezes and the elimination of bonuses at over one-third of firms.
- Burnout affects up to 63% of the workforce, serving as a primary driver for professionals considering leaving the industry alongside ineffective management practices.
- While 63% to 69% of employees now utilize AI for core tasks, the integration has triggered deep skepticism regarding job security and the devaluation of human expertise.
- Organizational support structures are lacking, evidenced by the absence of dedicated diversity and inclusion specialists in 67% of European gaming companies.
+2
InGameJobJan 2025
Report3 pages
2025 Half-Year Market Model Update: Asia & MENA
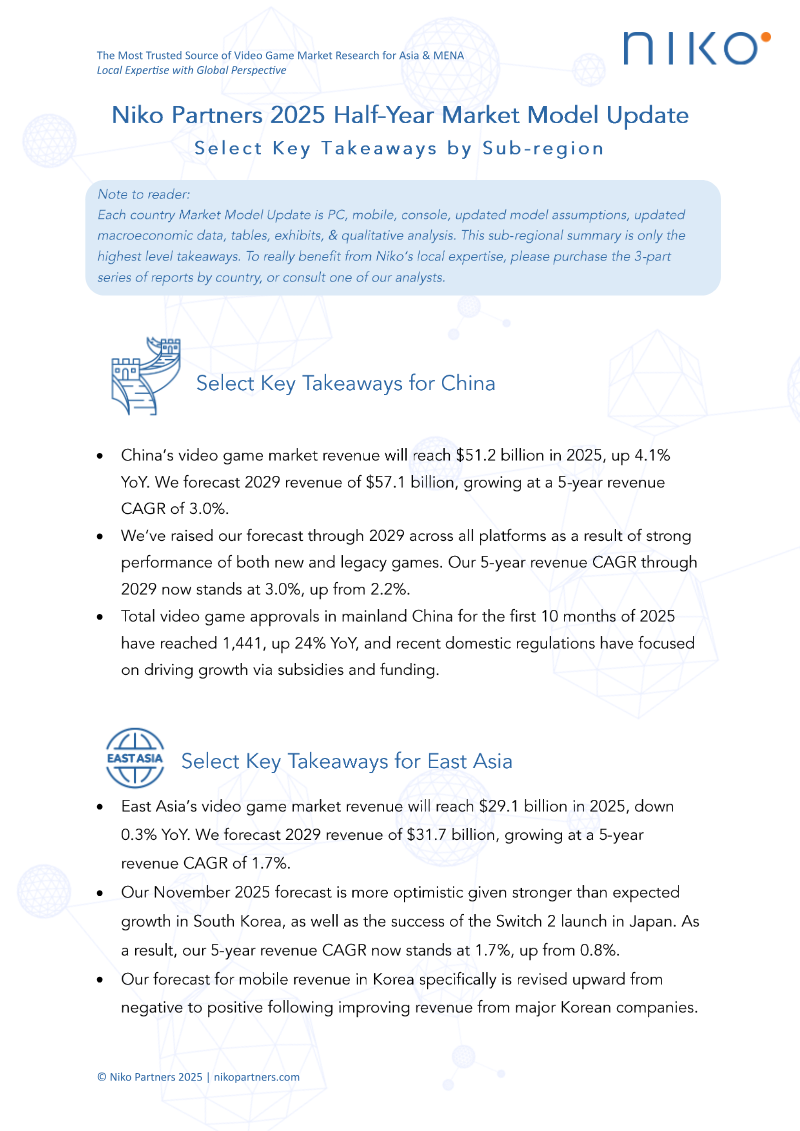
The 2025 Half-Year Market Model Update provides a comprehensive assessment of the video game industry across Asia and the Middle East and North Africa (MENA) region. By synthesizing macroeconomic data, platform-specific performance metrics, and regulatory developments, the analysis offers updated revenue forecasts through 2029 for key markets, including China, East Asia, India, Southeast Asia, and the MENA-3 region. The primary objective is to adjust long-term growth expectations based on recent industry performance, government policy shifts, and evolving consumer behavior.
Regional performance varies significantly, with India emerging as a high-growth market, projected to reach $1.1 billion in 2025 with a robust 12.9% five-year compound annual growth rate (CAGR). China remains the dominant market, with 2025 revenue expected to hit $51.2 billion, supported by a 24% year-over-year increase in game approvals. Conversely, East Asia and Southeast Asia show more moderate growth trajectories, with five-year CAGRs of 1.7% and 3.5%, respectively. The MENA-3 region is forecasted to reach $2.2 billion in 2025, though long-term projections have been tempered by economic headwinds in Egypt and slower mobile growth in Saudi Arabia and the UAE.
Methodologically, these insights are derived from proprietary market models that integrate platform-specific data for PC, mobile, and console segments. The analysis highlights the critical role of government intervention, such as the PROG act in India and regulatory subsidies in China, in shaping market expansion. By updating previous forecasts to reflect current fiscal realities and hardware cycles, such as the Switch 2 launch in Japan, the findings offer a refined outlook for stakeholders navigating the complex regulatory and economic landscapes of these diverse geographic segments.
- China remains the dominant regional market with projected 2025 revenue of $51.2 billion, bolstered by a 24% year-over-year increase in game approvals.
- India is positioned as a high-growth market expected to reach $1.1 billion in 2025 with a 12.9% five-year compound annual growth rate (CAGR).
- The MENA-3 region is forecasted to reach $2.2 billion in 2025, though long-term growth is tempered by economic headwinds in Egypt and slowing mobile performance in Saudi Arabia and the UAE.
- East Asia and Southeast Asia exhibit moderate growth trajectories, with five-year CAGRs of 1.7% and 3.5%, respectively.
- Market expansion across these regions is increasingly driven by government policy, including the PROG act in India and regulatory subsidies in China.
+5
Niko PartnersJan 2025
Report26 pages
Video Gaming Report 2025: How Platforms Are Colliding and Why This Will Spark the Next Era of Growth
The global video game industry is currently emerging from a three-year period of stagnation, transitioning toward a future defined by platform convergence and hardware-agnostic ecosystems. The traditional era of console-centric competition is being replaced by a multiplatform landscape where success is increasingly dictated by community engagement, user-generated content, and discoverability. This structural shift is underpinned by the integration of generative AI, the expansion of cloud gaming, and the diversification of distribution channels, which collectively aim to move the industry beyond the limitations of legacy hardware.
Cloud gaming is projected to reach $18.3 billion in revenue by 2030, serving as a primary catalyst for this growth. However, this transition introduces significant challenges, most notably the risk of market saturation caused by an influx of low-quality, AI-generated content. To maintain profitability and relevance, developers are pivoting toward direct-to-consumer monetization strategies, including tiered pricing models, windowing, and the integration of in-game advertising. These tactics are designed to capture value from a increasingly price-conscious global player base while navigating a shifting regulatory environment.
The dominance of incumbent app stores is simultaneously being challenged by the rise of developer-owned webstores and alternative distribution platforms. While these new channels offer the potential for improved margins and deeper player relationships, their long-term viability depends on the industry’s ability to address consumer concerns regarding security and platform convenience. Ultimately, the next era of growth will be defined by the ability of stakeholders to balance technological innovation with the necessity of fostering sustainable creator economies, ensuring that discoverability remains the central pillar of the modern gaming experience.
- Cloud gaming is projected to reach $18.3 billion in revenue by 2030, acting as a primary driver for industry growth as the market moves toward hardware-agnostic ecosystems.
- The industry is shifting from console-centric competition to a multiplatform model where success depends on user-generated content, community engagement, and discoverability.
- Developers are adopting direct-to-consumer monetization strategies—including tiered pricing, windowing, and in-game advertising—to address a price-conscious global player base.
- The rise of developer-owned webstores and alternative distribution platforms is challenging the dominance of incumbent app stores to improve margins and deepen player relationships.
- Market saturation caused by an influx of low-quality, AI-generated content poses a significant risk to profitability and requires a focus on sustainable creator economies.
+3
Boston Consulting GroupJan 2025
Whitepaper11 pages
Gaming's Cheating Crisis: The Impact on Players and Profit
The gaming industry is currently facing a widespread crisis regarding online cheating, which significantly undermines player retention, community trust, and developer revenue. This analysis, based on a survey of 2,013 gamers across the United Kingdom and the United States, reveals that cheating is no longer a fringe issue but a pervasive challenge affecting the majority of the gaming population. The findings underscore a critical need for industry-wide accountability measures to restore fair play and protect the financial health of game studios.
Data indicates that 80% of gamers have encountered cheating in online environments, with over half experiencing it at least monthly. This prevalence has direct consequences for business performance: 42% of players have considered quitting games entirely due to the presence of cheaters, and 55% have either reduced or ceased in-game spending. The impact is particularly acute among high-value players who spend between $11 and $50 monthly, a segment that represents the revenue backbone for many developers.
Despite these challenges, the gaming community remains highly receptive to robust solutions. A significant 83% of respondents expressed a greater likelihood to play games marketed as cheat-free, and 73% are willing to undergo identity verification to ensure a fair environment. Furthermore, there is strong support for systemic accountability, with 79% of gamers advocating for penalties that apply across multiple titles to prevent ban evasion.
The research concludes that while traditional anti-cheat measures are necessary, they are insufficient without mechanisms that enforce persistent, cross-game consequences. By adopting identity-based verification and unified accountability systems, developers have a clear opportunity to mitigate the negative financial impacts of cheating, improve player retention, and foster more sustainable, trustworthy gaming communities.
- Cheating is a pervasive issue, with 80% of gamers encountering it and over 50% experiencing it at least monthly.
- The presence of cheaters directly impacts revenue, as 55% of players have reduced or stopped in-game spending, particularly among high-value spenders.
- Cheating is a significant churn driver, with 42% of players reporting they have considered quitting games entirely due to unfair play.
- There is strong consumer demand for stricter security, with 83% of players more likely to play games marketed as cheat-free and 73% willing to undergo identity verification.
- 79% of gamers support systemic, cross-title penalties to prevent ban evasion and ensure persistent accountability.
+2
PlaySafe IDJan 2025
Report37 pages
2025 GDC Trends Report
The global video game industry is undergoing a strategic pivot toward operational sustainability and niche market penetration as of 2025. Developers are increasingly moving away from high-risk, large-scale AAA live service projects in favor of smaller, cost-effective titles that prioritize player retention over aggressive acquisition. This shift is mirrored in the mobile sector, where hybrid-casual models and data-driven advertising are gaining prominence, alongside a notable resurgence in HTML5 gaming as a platform for broader accessibility.
Technological integration remains a primary driver of industry evolution, particularly regarding generative AI and extended reality. While AI tools are being rapidly adopted to accelerate prototyping and enhance non-player character complexity, their implementation is tempered by significant concerns surrounding copyright, ethics, and long-term job security. Simultaneously, the VR, AR, and MR sectors are transitioning toward mass-market accessibility, with a focus on affordable hardware and the development of immersive multiplayer experiences. These trends are underscored by the success of titles like Balatro, which exemplify the growing market appetite for innovative, independent-minded gameplay.
The industry is also experiencing a fundamental change in its social and structural foundations. The formalization of labor organization, exemplified by the debut of the United Videogame Workers, reflects a growing commitment to addressing developer burnout and workplace equity. Furthermore, the industry is standardizing accessibility through initiatives like the ESA’s Accessible Games program, recognizing that inclusive design is essential for long-term growth. As funding becomes more selective, developers are increasingly relying on robust community building as a primary mechanism to secure investment and ensure the viability of their projects in a competitive global landscape.
- Developers are shifting away from high-risk AAA live service projects to prioritize smaller, cost-effective titles that focus on long-term player retention.
- Generative AI is being widely adopted to accelerate prototyping and increase NPC complexity, though its use remains constrained by ongoing ethical, copyright, and job security concerns.
- The mobile gaming sector is pivoting toward hybrid-casual models and data-driven advertising, while HTML5 gaming is seeing a resurgence as a tool for broader accessibility.
- The VR, AR, and MR sectors are moving toward mass-market adoption by prioritizing affordable hardware and immersive multiplayer experiences.
- Labor organization is becoming formalized, with groups like the United Videogame Workers emerging to address industry-wide issues of developer burnout and workplace equity.
+1
Game Developers ConferenceJan 2025
Report19 pages
Global Gaming M&A and Growth Financing Advisory: Q1 2025
The global gaming industry experienced a notable resurgence in early 2025, characterized by a rebound in merger and acquisition activity and sustained interest in private financing. During the first quarter, 48 announced acquisitions reached a total value of $4.4 billion, anchored by the significant $3.5 billion acquisition of Niantic’s games division by Scopely. Simultaneously, the private placement market remained active, recording 149 deals worth $3.5 billion. These investments were primarily concentrated in mobile-focused developers and companies integrating artificial intelligence into their entertainment platforms, with major strategic entities like Savvy Games Group and Tencent continuing to drive market momentum.
Despite this activity, the financial landscape remains bifurcated. While the broader sector shows signs of recovery, with the Drake Star Gaming Index posting a 16.37% gain, performance remains highly volatile across the top 35 public gaming companies. Valuation disparities are particularly pronounced; industry leaders such as NVIDIA and AppLovin command premium revenue multiples, while many other firms face a more challenging environment. Furthermore, while early-stage funding remains accessible, later-stage financing continues to present significant hurdles for companies seeking capital.
Looking forward, the industry is positioned for a gradual increase in consolidation as public markets stabilize. Strategic focus is shifting toward the integration of AI and advanced technological platforms, which are expected to serve as primary catalysts for future growth. As market conditions improve, the sector is likely to see a renewed pipeline of initial public offerings, signaling a transition toward a more mature and diversified investment climate for global gaming stakeholders.
- Q1 2025 saw 48 M&A deals totaling $4.4 billion, headlined by Scopely’s $3.5 billion acquisition of Niantic’s games division.
- The private placement market recorded 149 deals worth $3.5 billion, with capital primarily flowing into mobile developers and AI-integrated entertainment platforms.
- The Drake Star Gaming Index rose 16.37% in Q1 2025, though performance remains volatile across the top 35 public gaming companies.
- Valuation gaps are widening, with industry leaders like NVIDIA and AppLovin commanding premium revenue multiples while other firms face significant capital constraints.
- While early-stage funding remains accessible, companies seeking later-stage financing continue to face substantial hurdles.
+2
Drake StarJan 2025
Report65 pages
The State of AAA Game Advertising: 2023 Review
The 2023 AAA game advertising landscape underwent a strategic pivot toward launch-focused campaigns, with new releases accounting for half of all top-tier spending. This shift reflects a broader industry trend of prioritizing high-impact, multi-channel visibility to capture immediate market share. While YouTube remains the dominant advertising medium for PC and console titles, publishers have increasingly diversified their media mix by integrating Facebook, TikTok, and Instagram to target specific demographics. This evolution in outreach is complemented by a growing reliance on platform-based partnerships, such as deep Xbox branding and hardware collaborations, which serve to anchor major titles within broader ecosystem strategies.
Creative execution in 2023 varied significantly based on the title’s core value proposition. Successful campaigns ranged from the consistent, exploration-themed branding of single-player experiences like Hogwarts Legacy to the dark, horror-inspired aesthetics and live-service integration of titles like Diablo IV. Furthermore, the industry increasingly utilized transmedia efforts and review-based accolades to sustain momentum. However, the year also highlighted the risks of fragmented marketing, as seen with Call of Duty: Modern Warfare III, which suffered from a lack of a cohesive reveal campaign and negative consumer perception regarding its status as a standalone sequel.
Ultimately, the year demonstrated that while massive advertising budgets and established intellectual property remain primary drivers for AAA success, organic viral growth and streamlined gameplay models also provide viable paths to market dominance. The industry is currently defined by a tension between traditional, high-spend multi-channel campaigns and the rising influence of mobile-first strategies and community-driven engagement. As publishers navigate these shifting dynamics, the ability to align creative messaging with specific platform strengths and cross-industry partnerships has become the definitive factor in maintaining visibility within an increasingly competitive global market.
- In 2023, AAA publishers shifted toward launch-focused campaigns, with new releases accounting for 50% of all top-tier advertising expenditure.
- While YouTube remains the primary advertising medium for PC and console games, publishers are increasingly diversifying their media mix by integrating Facebook, TikTok, and Instagram to target specific demographics.
- Strategic platform-based partnerships, such as deep Xbox branding and hardware collaborations, are now essential for anchoring major titles within broader ecosystem strategies.
- The failure of Call of Duty: Modern Warfare III demonstrated that fragmented marketing and a lack of a cohesive reveal campaign can severely damage consumer perception and market performance.
- Successful 2023 campaigns utilized varied creative strategies, ranging from exploration-themed branding for single-player titles like Hogwarts Legacy to horror-inspired aesthetics and live-service integration for Diablo IV.
+3
Sensor TowerJan 2025
Report10 pages
Take Rates in China: Will Quality Development Beat Out Traditional Distribution?
The Chinese mobile gaming market is currently undergoing a significant shift in distribution dynamics as developers increasingly challenge the traditional 50% take rates imposed by domestic Android app stores. While global discourse remains focused on the 30% take rate standard contested in the Epic v. Apple litigation, Chinese developers face a more restrictive domestic environment where smartphone manufacturers and major tech firms consolidate power through the Mobile Hardcore Alliance and the Global Developer Service Alliance. These entities justify high fees by providing integrated marketing and distribution services, yet these costs have become a primary point of contention for major studios.
To circumvent these high fees, prominent developers such as miHoYo, Lilith Games, and NetEase are increasingly adopting direct-to-consumer distribution models. By leveraging high-quality intellectual property, substantial marketing budgets, and community-driven platforms like TapTap and Bilibili, these studios can bypass traditional stores entirely. This strategy allows developers to retain significantly higher gross profit margins—often exceeding 95%—compared to the 50% margin typically realized through standard distribution channels. The success of these titles has begun to force concessions, as evidenced by Xiaomi offering reduced take rates to high-profile games like Genshin Impact.
The industry landscape is bifurcated, as smaller developers often remain dependent on traditional stores for the reach and infrastructure necessary to sustain their operations, viewing the 50% fee as an acceptable cost of doing business. However, the rise of direct distribution and community-centric marketing signals a broader trend where quality content and brand loyalty are becoming more influential than traditional store placement. As developers continue to prioritize direct engagement and alternative platforms, the dominance of traditional Android app stores in China faces mounting pressure, potentially reshaping the economic model of the global mobile gaming industry.
- Major Chinese developers like miHoYo, Lilith Games, and NetEase are bypassing traditional Android app stores to achieve gross profit margins exceeding 95%, compared to the 50% margin typical of standard distribution.
- The Chinese mobile gaming market is dominated by a 50% take rate imposed by smartphone manufacturers and tech firms organized under the Mobile Hardcore Alliance and the Global Developer Service Alliance.
- High-profile titles are successfully leveraging direct-to-consumer models and community platforms like TapTap and Bilibili to circumvent traditional distribution fees.
- The shift toward direct distribution has forced some concessions from traditional stores, such as Xiaomi offering reduced take rates for high-profile games like Genshin Impact.
- The market is bifurcated, as smaller developers remain dependent on traditional stores for necessary infrastructure and reach, accepting the 50% fee as a standard cost of business.
+2
NikoJan 2025
Report35 pages
Guide to Growing Chinese Gaming Apps Overseas
Chinese gaming developers are aggressively expanding their global footprint by leveraging sophisticated monetization models and high-volume, AI-driven marketing strategies. The primary objective for these publishers is to balance the high revenue potential of mature markets like the United States, Japan, and South Korea against the rising costs of user acquisition. By prioritizing video advertising, which currently yields the highest Day 7 return on ad spend at 21%, developers are successfully capturing market share in competitive strategy and RPG segments.
Success in these international territories is increasingly predicated on hyper-localization and technological integration. Publishers are utilizing generative AI to streamline the production of localized ad creatives, voice-overs, and performance-tested copy, allowing for rapid iteration and regional customization. Leading titles demonstrate that high-engagement gameplay loops—such as the inclusion of social hangout spaces, customizable home systems, and minigame integrations—are essential for sustaining long-term retention. These efforts are further bolstered by strategic partnerships with local influencers and the implementation of innovative, time-limited gacha mechanics.
To maintain consistent growth, developers are diversifying their engagement tactics through gamified live events, including seasonal collections and interactive board-style challenges. These features, combined with trial character systems, allow publishers to cater to varied player motivations while maintaining a steady revenue stream. By synthesizing competitive intelligence with agile content updates, Chinese gaming apps are effectively navigating the complexities of global expansion, ensuring that both monetization and user interest remain high across diverse geographic regions.
- Video advertising is the most effective monetization channel for Chinese developers in mature markets, currently yielding a 21% Day 7 return on ad spend.
- Generative AI is being deployed at scale to automate the production of localized ad creatives, voice-overs, and performance-tested copy to reduce costs and speed up regional market entry.
- Long-term player retention is increasingly driven by integrating social hangout spaces, customizable home systems, and minigames into core gameplay loops.
- Developers are prioritizing expansion into high-revenue mature markets, specifically the United States, Japan, and South Korea, to offset rising global user acquisition costs.
- Engagement is being sustained through gamified live events, such as seasonal collections and interactive board-style challenges, alongside trial character systems.
+6
EAJan 2025
Report25 pages
The Big Game Engine Report: 2025
The game engine landscape is undergoing a significant transition as developers increasingly move away from proprietary, in-house solutions in favor of established third-party platforms. This shift is driven by the need for immediate development readiness, access to advanced graphical features like Nanite and Lumen, and the ability to leverage a broader, pre-trained talent pool. While custom engines historically dominated the industry, their market share has declined sharply over the last decade, falling to approximately 13% of new releases by 2024.
Unreal Engine has emerged as the primary beneficiary of this trend, particularly among large-scale AAA studios. By 2024, Unreal Engine and custom engines collectively accounted for the majority of unit sales on Steam, with Unreal Engine 5 becoming the industry standard for high-fidelity projects. Conversely, Unity maintains a dominant position in terms of the sheer volume of games released, particularly within the indie and smaller-scale development sectors. However, Unity faces intensifying competition from smaller, specialized engines like Godot and GameMaker, which have captured a growing segment of the indie market.
The analysis, which covers over 13,000 games released on Steam, utilizes proprietary tagging and estimation methodologies to track engine adoption trends. Data indicates that engine preference is heavily influenced by game scale and genre; high-graphics, large-budget titles skew heavily toward Unreal Engine, while strategy and simulation games remain strongholds for Unity. Looking toward 2030, the industry is expected to see continued consolidation as more studios abandon legacy in-house tools to mitigate the high costs of engine maintenance, further cementing the market dominance of third-party public engines.
- Proprietary in-house engines have seen their market share of new game releases decline to approximately 13% by 2024.
- Unreal Engine 5 has established itself as the industry standard for high-fidelity, large-scale AAA projects.
- Unity maintains market dominance by volume, particularly within the indie and smaller-scale development sectors.
- Engine selection is highly correlated with project type, as high-graphics titles favor Unreal Engine while strategy and simulation games remain concentrated in Unity.
- Specialized engines like Godot and GameMaker are successfully capturing an increasing share of the indie market, intensifying competition for Unity.
+3
VG InsightsJan 2025
Report40 pages
The Gaming App Insights Report 2025: Unlocking Growth Opportunities for Mobile Marketers
The mobile gaming industry is entering a period of strategic recalibration, projected to reach $126.1 billion in revenue by 2025. This growth is underpinned by a transition toward hybrid monetization models and the integration of AI-powered personalization to combat persistent retention challenges. While global install volume grew by 4% in 2024, the market exhibits a distinct geographic divide; North American and European markets face stagnation, whereas Latin America and the Middle East and North Africa regions demonstrate robust expansion. Success in this evolving landscape requires developers to move beyond traditional acquisition, favoring diversified channels such as Connected TV and localized, player-centric engagement strategies.
Data from early 2025 indicates that user tracking remains a pivotal operational hurdle, with global App Tracking Transparency opt-in rates hovering at 37.9%. Although arcade games have seen notable improvements in opt-in performance, the United States remains relatively static at 32%, underscoring the necessity for refined messaging strategies to maintain visibility. Concurrently, the industry is grappling with a complex financial environment characterized by rising costs per install and declining average revenue metrics. These headwinds are forcing a shift in marketing tactics, as developers increasingly rely on a broader array of acquisition partners and data-informed creative experimentation to sustain growth.
Ultimately, the path to profitability in 2025 lies in prioritizing long-term player value over short-term acquisition metrics. By leveraging AI-driven optimization and fostering community-building initiatives, developers can mitigate the impact of declining revenue per user. The industry is clearly moving toward a more sophisticated, data-reliant ecosystem where the ability to measure performance across fragmented channels—including mobile and Connected TV—is essential for maintaining a competitive advantage in a maturing global market.
- The mobile gaming market is projected to reach $126.1 billion in revenue by 2025, driven by a shift toward hybrid monetization and AI-powered personalization.
- Global install volume grew by 4% in 2024, but growth is geographically polarized with stagnation in North America and Europe contrasted by expansion in Latin America and the MENA region.
- Global App Tracking Transparency (ATT) opt-in rates remain low at 37.9%, with the United States market stagnant at a 32% opt-in rate.
- Developers face a challenging financial environment defined by rising costs per install and declining average revenue metrics, necessitating a shift toward long-term player value over short-term acquisition.
- To sustain growth, developers must diversify acquisition channels beyond traditional mobile ads, specifically integrating Connected TV and data-informed creative experimentation.
+5
GamingReportJan 2025
Report15 pages
Interactive Entertainment: Global Market Sizing & Forecast 2025
The global interactive entertainment market is poised for a recovery in 2025, with total consumer spending projected to reach $250.2 billion, representing a 4.6% year-over-year growth. This rebound follows a period of cyclical transition, characterized by a significant contraction in console hardware sales and a strategic shift toward efficiency and transmedia integration among major industry players. The analysis, which synthesizes company financials and industry data, highlights a market moving toward next-generation experiences while navigating economic uncertainty.
Software publishing remains the primary revenue driver, expected to total $196 billion in 2025. Mobile gaming continues to lead as the largest segment, with $115.7 billion in projected 2025 revenue, despite ongoing challenges related to market saturation and rising user acquisition costs. Conversely, the hardware sector is experiencing a sharp 31% decline in console revenue for 2024, signaling the end of the current console cycle. However, this is partially offset by resilient growth in gaming PC components and a consistent demand for gaming accessories, which are forecasted to grow by 5% in 2025.
Emerging technologies, including virtual reality, blockchain gaming, and web-based platforms, show potential for growth but remain secondary to established software markets. Meanwhile, the esports and live-streaming sectors face persistent profitability challenges, with esports revenue trending downward. In response to these pressures, major entertainment conglomerates are pivoting toward transmedia strategies and in-game advertising, leveraging established intellectual property to engage audiences across digital worlds. Industry leadership remains optimistic, focusing on operational efficiency and high-profile content releases to sustain long-term growth through 2025 and beyond.
- The global interactive entertainment market is projected to reach $250.2 billion in 2025, marking a 4.6% year-over-year recovery.
- Software publishing remains the dominant revenue driver at $196 billion, with mobile gaming leading the sector at $115.7 billion despite rising user acquisition costs.
- The console hardware sector is in a significant downturn, evidenced by a 31% decline in revenue during 2024 as the current cycle concludes.
- Gaming PC components and accessories are providing a buffer against hardware losses, with a forecasted growth rate of 5% in 2025.
- Major industry players are shifting toward transmedia strategies and in-game advertising to leverage existing intellectual property amid economic uncertainty.
+3
AldoraJan 2025
Report23 pages
2025 Mobile Gaming Benchmarks
The mobile gaming landscape in 2024 faced significant challenges regarding player loyalty, as 75 percent of titles failed to maintain a 3 percent retention rate by the 28th day. This decline underscores a critical industry shift where long-term viability is increasingly tethered to sophisticated content pacing, refined progression systems, and seamless onboarding experiences. Because retention serves as the primary engine for both user acquisition return on investment and sustainable monetization, developers must prioritize data-backed strategies to mitigate rising churn rates across the global market.
Engagement metrics reveal a nuanced performance gap between platforms and regions. While iOS continues to demonstrate superior early-stage engagement compared to Android, regional behaviors vary significantly; the Middle East currently leads in retention, whereas Africa and Oceania report the highest average playtime and session lengths, respectively. Genre-specific performance further complicates these trends, as Board and Card games exhibit robust long-term retention, contrasting sharply with Multiplayer titles that struggle to retain users despite commanding the longest average session durations of 8 to 9 minutes.
These insights, derived from an expansive dataset of over 100,000 active games, highlight the necessity of granular performance benchmarking. By comparing individual game metrics—including monetization, engagement, and retention—against global standards filtered by genre and player spending habits, studios can effectively optimize their development cycles. Ultimately, the industry is moving toward a model where success is no longer defined by broad acquisition, but by the precise, data-driven calibration of the player experience to ensure longevity in an increasingly competitive mobile ecosystem.
- 75 percent of mobile games failed to achieve a 3 percent retention rate by day 28 in 2024, highlighting a widespread struggle to maintain long-term player loyalty.
- Retention is the primary driver for both user acquisition ROI and sustainable monetization, making it the most critical metric for long-term viability.
- Multiplayer titles command the longest average session durations of 8 to 9 minutes but struggle significantly with long-term user retention.
- Board and Card games currently demonstrate the most robust long-term retention performance compared to other genres.
- Regional engagement varies significantly, with the Middle East leading in retention, while Africa and Oceania lead in average playtime and session length, respectively.
+2
GameAnalyticsJan 2025
Report25 pages
The Big Game Engine Report: End of the Era of In-House Engines
The game engine landscape is undergoing a significant structural shift, characterized by the decline of proprietary in-house technology in favor of established third-party platforms. While custom engines historically dominated the industry, their market share has eroded substantially over the last decade, falling to approximately 13 percent of new releases by 2024. This transition is driven by the increasing complexity of modern development, which makes the maintenance of internal engines cost-prohibitive and less efficient compared to the immediate, high-fidelity capabilities offered by public alternatives.
Unreal Engine has emerged as the primary beneficiary of this trend, particularly within the AAA segment. Following the release of Unreal Engine 5, the platform has successfully reclaimed market share lost during the pandemic, becoming the preferred choice for large-scale, high-budget productions. Conversely, Unity maintains a dominant position in terms of total volume of games released, particularly among indie and smaller developers, though it faces increasing competition from smaller engines like Godot, which has seen notable growth since 2020. Despite Unity’s high release volume, Unreal Engine and custom AAA engines continue to command a larger portion of total units sold, underscoring their prevalence in high-performing commercial titles.
The analysis relies on data from over 13,000 games released on Steam, utilizing proprietary estimation algorithms and tagging methodologies to categorize engine usage by game size, genre, and unit sales. The findings indicate that while the choice of engine is often dictated by project scale—with smaller titles favoring Unity and larger, graphics-intensive projects gravitating toward Unreal Engine—the industry is moving toward a standardized ecosystem. As studios weigh the benefits of third-party support, talent accessibility, and advanced graphical features against the loss of proprietary control, the reliance on external engines is expected to continue its upward trajectory through 2030.
- Proprietary in-house engine usage has declined significantly, accounting for only 13 percent of new game releases by 2024.
- Unreal Engine has become the industry standard for high-budget AAA productions, particularly following the release of Unreal Engine 5.
- Unity maintains the highest total volume of game releases, primarily driven by adoption among indie and smaller-scale developers.
- While Unity leads in release volume, Unreal Engine and custom AAA engines command a larger share of total units sold in the commercial market.
- The open-source Godot engine has experienced notable growth since 2020, emerging as a competitive alternative to established platforms.
+3
Video Game InsightsJan 2025
Report23 pages
The State of Puzzle Games: An Analysis of the Puzzle Category in Mobile Gaming
The mobile puzzle game market is undergoing a significant structural evolution, characterized by a shift in product models and a notable rise in hybridcasual gaming. This analysis, covering global data from January 2018 through June 2023, examines the performance of various puzzle sub-genres, including swap, blast, chain, and pair mechanics. By leveraging store intelligence and download estimates from the Apple App Store and Google Play, the findings highlight how developers are increasingly integrating meta-features and diversified monetization strategies to sustain revenue in a maturing landscape.
A central finding is the remarkable growth of the hybridcasual product model, which saw a 430% increase in revenue between early 2022 and early 2023. While traditional casual games continue to dominate overall market share through consistent operations and robust meta-features, they have experienced modest declines in both downloads and revenue. Conversely, hybridcasual titles—particularly within the pair sub-genre—have successfully captured user interest by blending accessible gameplay with more sophisticated monetization tactics, such as in-app purchases, which were previously less common in hypercasual-leaning segments.
The data indicates that sub-genres like pair have emerged as high-growth areas, with hybridcasual revenue in this category rising from $7 million in the first quarter of 2022 to $40 million by the first quarter of 2023. Meanwhile, other established sub-genres, such as merge and physics, have seen download declines as their reliance on hypercasual models wanes. Successful top-tier games across all categories now frequently employ a combination of live operations, season passes, and social clans to drive engagement. Ultimately, the puzzle market is moving toward a hybrid approach, where the simplicity of casual mechanics is increasingly supported by the deeper monetization and retention frameworks typically associated with mid-core titles.
- The hybridcasual puzzle model experienced a 430% revenue increase between early 2022 and early 2023, signaling a major shift in market structure.
- Hybridcasual revenue in the 'pair' sub-genre grew from $7 million in Q1 2022 to $40 million in Q1 2023.
- Traditional casual puzzle games are experiencing modest declines in both downloads and revenue despite maintaining overall market share through robust meta-features.
- Established sub-genres like merge and physics are seeing download declines as their reliance on hypercasual models diminishes.
- Top-tier puzzle games are increasingly adopting mid-core retention and monetization strategies, including live operations, season passes, and social clans.
+3
Sensor TowerJan 2025
Report20 pages
The Importance of Wishlists in 2025: Do Wishlists Matter?
Steam wishlists serve as a critical metric for predicting commercial success in the video game industry, functioning as a primary indicator of pre-launch momentum. Data analysis reveals that wishlist distribution is highly top-heavy, with a significant majority of games launching with fewer than 10,000 wishlists, while only a small fraction of titles achieve the 100,000-plus threshold required to reliably forecast a breakout performance. There is a strong 70% correlation between pre-launch wishlist counts and first-month unit sales, particularly for titles that surpass the 100,000-wishlist milestone.
Genre-specific trends highlight that action and adventure titles consistently generate the highest levels of pre-release buzz, often benefiting from the brand equity and marketing budgets of AAA and AA publishers. Conversely, casual and MMO titles frequently rely on post-launch engagement, such as live updates and community building, rather than pre-release wishlist accumulation. Regardless of genre, the timing of a Steam page launch is vital; top-performing games typically establish their presence six to twelve months before release, utilizing a steady stream of trailers and development updates to build and maintain audience interest.
The findings are based on an analysis of games launched on Steam from March 2024 onwards, utilizing proprietary estimation models and industry data. The research emphasizes that while wishlists are not a guarantee of success for every title, they act as a essential barometer for market interest. For developers and publishers, the data underscores that early visibility and sustained marketing efforts are necessary to reach the wishlist tiers that statistically correlate with long-term commercial viability.
- Steam wishlists are a primary indicator of commercial success, showing a 70% correlation between pre-launch counts and first-month unit sales.
- The 100,000-wishlist threshold is the critical benchmark required to reliably forecast a breakout performance for a new title.
- The vast majority of games launch with fewer than 10,000 wishlists, reflecting a highly top-heavy distribution of pre-launch momentum.
- Top-performing titles typically establish their Steam page six to twelve months before release to maintain audience interest through consistent updates.
- Action and adventure games generate the highest pre-release buzz, while casual and MMO titles rely more heavily on post-launch engagement than wishlist accumulation.
+3
Video Game InsightsJan 2025
Report26 pages
Key Insights into Role-Playing Games (RPGs)
Role-Playing Games (RPGs) represent the highest-revenue genre in the global gaming market as of 2022. The genre is characterized by deep character development, party-based mechanics, and progression systems centered on quests and combat. While RPGs are played across all platforms, they maintain a strong presence on PC and console, where they consistently rank among the top genres for monthly active users.
The demographic profile of the RPG audience is predominantly male, accounting for 58% of players, and skews toward younger age groups, with 59% of the player base falling between the ages of 10 and 30. Engagement patterns reveal that RPG players are highly active, averaging 18.8 sessions per month. The genre also demonstrates significant cross-genre appeal, with high player overlap in the adventure, shooter, and battle royale categories. High magical fantasy remains the most popular thematic element, utilized by 63% of the player base, while skill and talent trees serve as the most prevalent gameplay mechanic.
Monetization within the RPG space is dominated by pay-to-play models, which reach 97% of the player base, followed closely by in-app purchases at 90%. Geographically, the United States and Japan lead in monthly active users on PC and console. The genre also maintains a robust live-streaming presence, generating 205 million hours watched across platforms like Twitch and Facebook Gaming in June 2022. These insights are derived from data covering 37 markets, excluding China and India, and utilize proprietary gamer segmentation to analyze player motivations, viewing habits, and engagement metrics across the broader gaming ecosystem.
- As of 2022, Role-Playing Games (RPGs) rank as the highest-revenue genre in the global gaming market.
- The player base is predominantly male (58%) and young, with 59% of users falling between the ages of 10 and 30.
- Monetization is heavily driven by pay-to-play models used by 97% of the player base, supplemented by in-app purchases at 90%.
- High magical fantasy is the dominant theme, appearing in 63% of RPGs, while skill and talent trees remain the most prevalent gameplay mechanics.
- RPG players exhibit high engagement, averaging 18.8 sessions per month, with significant audience overlap in the adventure, shooter, and battle royale genres.
+2
NewzooJan 2025