Moon Active
17 documents in the library are about Moon Active, from writers such as Deconstructor of Fun, GameRefinery and Game World Observer, the newest from 2026. Each has a summary and key insights with the page they come from.
- Country
- Israel
- Games
- Coin Master, Wonderball Heroes, Super Sam Adventures
- Links
- Official site
Company data from IGDB.com
Key figures
Moon Active is actively diversifying its portfolio to reduce dependency on Coin Master, which currently accounts for 70% of the company's $1.5 billion annual revenue.
Deconstructor of Fun, 2025 · TWIG #344 AppLovin’s Record Quarter, Moon Active’s New Games and Battlefield’s Big Comeback,, p. 56
Notable publishers falling just outside the top 10 include Bandai Namco ($450 million), Moon Active ($390 million), and Zynga ($372 million).
Game World Observer, 2024 · Tencent Leads Mobile Publishers by Revenue: H1 2024
Documents about Moon Active
Xbox's weird 'North Star', Sybo and Subway Surfers, App Store emulators, Peridot's death, more
The mobile games industry is currently navigating a period of strategic realignment, marked by shifting corporate priorities and evolving platform dynamics.
- Xbox has adopted 'daily active players' as its new core metric, yet the company's recent strategic communications largely ignore its mobile gaming division despite mobile likely representing the majority of its active player base.
- Subway Surfers developer Sybo is shifting its revenue strategy for the new title Subway Surfers City, aiming for a higher ratio of in-app purchases compared to the original game, which currently relies on ad revenue for 80% to 85% of its income.
- Apple's App Store has seen over 60 million downloads of game emulators, but developers report that Apple's backend tools remain dated and fail to provide a developer experience commensurate with the high commission fees Apple collects.
🚨📢 Breaking News: Apple AI money, rewarded roll-up, mobile funding wave
The mobile gaming industry is currently defined by three major trends: the indirect monetization of generative AI, a resurgence in venture capital funding for game studios, and the consolidation of rewarded user acquisition (UA) platforms.
- Major industry players are prioritizing control over distribution infrastructure, evidenced by NCSoft’s $202 million acquisition of a 70% stake in Just Play and Nazara Technologies’ $100 million investment in Blue Tile and Best Play.
- The mobile gaming industry is undergoing a consolidation of rewarded user acquisition firms, allowing companies to build proprietary ecosystems that bypass traditional ad networks.
- Apple is projected to generate nearly $1 billion in annual revenue from third-party generative AI applications by collecting 15% to 30% commission fees on subscriptions through the App Store.
Red Dead Redemption, Moon Active, Playtika, Liftoff, 2025's top games, data, jobs and more
This analysis examines the state of the mobile games industry as of early 2026, focusing on performance metrics, corporate restructuring, and market trends.
- The mobile gaming market is dominated by a few high-earning titles, led by Honor of Kings ($1.68B in China), Last War ($1.57B), and Roblox ($1.5B) in 2025.
- Strategy games remain the industry's most lucrative genre, generating $13 billion in total market revenue during 2025.
- Playtika is restructuring its operations by laying off 500 employees to pivot toward AI-driven automation and a leaner corporate model.
TWIG #344 AppLovin’s Record Quarter, Moon Active’s New Games and Battlefield’s Big Comeback,
Global gaming revenue remains heavily concentrated in North America and Europe, which together generate nearly half of all industry earnings despite housing only one-fifth of the total player base.
- AppLovin has achieved significant financial outperformance, reporting 77% revenue growth and 156% net income growth driven by advanced ad-tech and e-commerce diversification.
- North America remains the industry's most critical commercial market, with players spending an average of $325 annually—2.5 times the rate of European players.
- Moon Active is actively diversifying its portfolio to reduce dependency on Coin Master, which currently accounts for 70% of the company's $1.5 billion annual revenue.
Did Coin Master Just Copy (back) Monopoly Go?
The mobile gaming industry is currently witnessing a high-stakes competitive cycle characterized by iterative cloning and aggressive user acquisition strategies.
- The 'coin looter' subgenre is currently defined by a competitive cycle of iterative cloning between industry giants Moon Active and Scopely, with Moon Active’s latest title mirroring the mechanics of Scopely’s Monopoly Go.
- Market success in this sector is increasingly driven by 'UA arbitrage,' where firms prioritize outspending competitors on user acquisition over product innovation or unique feature sets.
- The industry has evolved into a 'red ocean' where large, well-capitalized firms prioritize long-term market dominance and aggressive user acquisition over immediate profitability.
Week in Mobile Games E61: Zynga's successes and failures, and Moon Active takes the fight to Scopely
The mobile gaming industry is currently defined by a strategic shift toward hybrid-casual models, the dominance of 4X strategy titles, and the ongoing evolution of direct-to-consumer monetization.
- Whiteout Survival has become a dominant 4X strategy title, generating over $3 billion in gross player spending in less than 30 months.
- Rolic successfully transitioned to a hybrid-casual model, with its top title Color Block Jam earning over $100 million by leveraging a challenging difficulty curve to drive retention.
- Publishers are increasingly shifting away from pure hyper-casual mechanics toward hybrid-casual models that prioritize long-term engagement and in-app purchases.
TWIG #340 Scopely Goes to War, Roblox Gambles on IP and Turkey Rises
The mobile gaming industry is currently defined by an aggressive arms race in user acquisition, particularly within the coin-battler genre.
- The mobile coin-battler genre has become a 'red ocean' where market dominance is driven by industrial-scale user acquisition spending by giants like Scopely and Moon Active, creating high barriers to entry for smaller developers.
- Corporate friction is intensifying over performance-based earn-outs, exemplified by a dispute between Krafton and Unknown Worlds involving a $250 million earn-out and allegations of strategic project delays.
- Major publishers are increasingly integrating AI-driven development tools to streamline production, leading to staff reductions in design roles at companies like King.
Examining a Decade of Gaming Startup Exit Paths
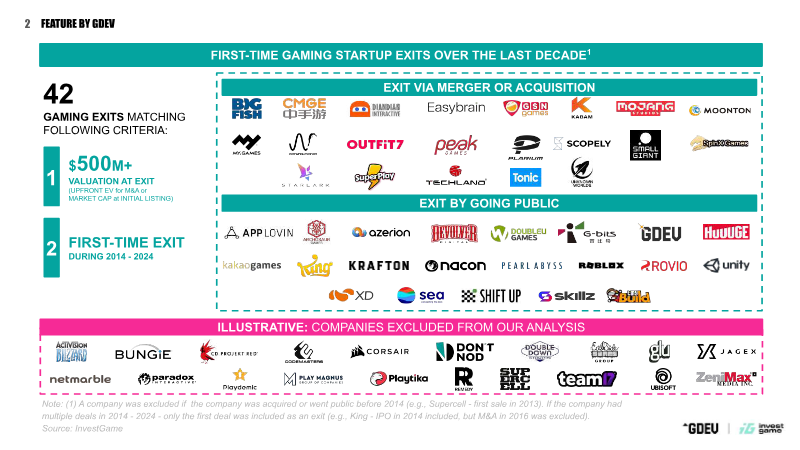
The global gaming industry saw forty-two first-time startup exits with valuations exceeding $500 million between 2014 and 2024.
- Mobile gaming dominates the exit landscape, accounting for 75% of all major deals and achieving liquidity approximately 40% faster than PC or console-focused startups.
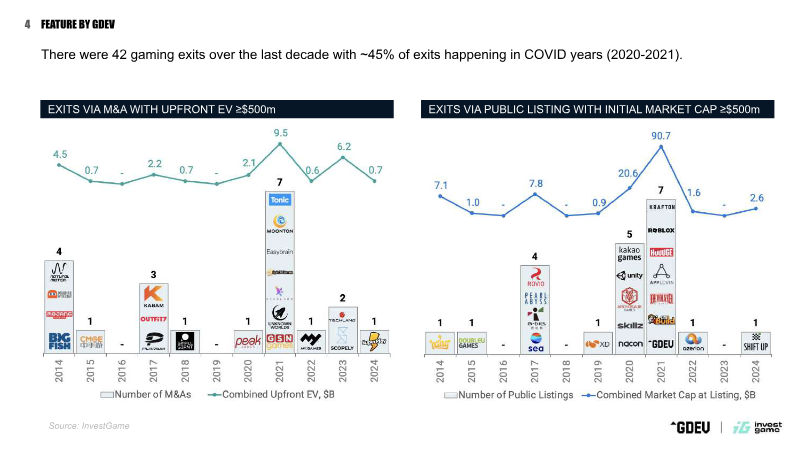
- Between 2014 and 2024, there were 42 first-time startup exits valued over $500 million, with 45% of these events concentrated in the 2020–2021 pandemic period.
- Exit strategy is highly correlated with valuation: M&A is the primary path for companies under $1 billion, while public offerings are the exclusive route for those valued at $5 billion or more.
Top Casual Games Publishers of 2024
The mobile gaming landscape in 2024 remains dominated by the casual games segment, with Scopely emerging as the leading publisher by net in-app purchase revenue.
- Scopely emerged as the top casual games publisher by net in-app purchase revenue in 2024, generating $1.63 billion between January and November.
- Playrix ($1.53 billion), King ($1.28 billion), and Dream Games ($1.25 billion) followed Scopely to round out the top four highest-earning casual publishers.
- The success of 'Monopoly Go!' was the primary driver for Scopely's top ranking, with the title having grossed over $3 billion globally to date.
Tencent Leads Mobile Publishers by Revenue: H1 2024
Tencent maintains its dominant position in the global mobile gaming market, leading the industry in revenue for the first half of 2024.
- Tencent dominated the mobile gaming market in the first half of 2024, generating $3.2 billion in in-app purchase revenue.
- Scopely secured the second position with $931 million in revenue, nearly tripling its performance compared to the same period in 2023 due to the success of Monopoly Go!.
- NetEase ($912 million), Playrix ($873 million), and miHoYo ($764 million) rounded out the top five highest-grossing mobile publishers.
TWIG #281 Switch 2, Moon Active 💗 Spyke Games, Helldivers vs. PSN
The global gaming industry is currently navigating a period of intense structural realignment, defined by aggressive cost-cutting, strategic consolidation, and a volatile relationship between developers and their player bases.
- The gaming industry is undergoing a structural shift characterized by aggressive cost-cutting and studio closures, exemplified by Microsoft’s recent efforts to reconcile high subscription-model costs with sustainable profitability.
- Community sentiment has become a critical operational risk, as demonstrated by the successful player backlash against Sony’s mandatory account-linking policy for Helldivers 2, which forced a policy reversal.
- Mobile gaming remains a primary growth engine, with titles like Monopoly GO! achieving massive revenue run rates and successfully attracting new demographics.
The Zen Match Case: How a First Mover Fell Behind
The mobile puzzle game Zen Match serves as a primary case study for the challenges faced by first-mover titles in the evolving Tile Match genre.
- Moon Active acquired Zen Match for up to $150 million in late 2022, but the title has since faced stagnating performance, record-low user acquisition, and declining revenue.
- Zen Match is suffering from the Innovator’s Dilemma, where adherence to original design mechanics prevents the game from meeting shifting player expectations.
- Competitors like Tile Busters are capturing market share by integrating complex Match-3 inspired mechanics and obstacles that outperform Zen Match’s simpler design.