Newzoo
Research100 documents
Documents
Report13 pages
Newzoo DLC Content Report 2023
This analysis examines the impact of downloadable content (DLC) on player engagement and revenue across the PC and console markets. Covering the period from April 2020 to April 2023, the study evaluates over 1,600 DLC releases across 37 major global markets. The findings demonstrate that DLC serves as a critical tool for extending game longevity and driving monetization, particularly within the live-service model. In 2022, DLC sales accounted for 13% of total PC revenue and 7% of console revenue in the United States, highlighting a stronger reliance on add-on content among PC audiences.
The research indicates that DLC launches provide a significant boost to player activity, with an average increase of 11% in Monthly Active Users (MAU) during the launch month. Medium-sized games, defined as those with 250,000 to 2 million MAU, saw the most substantial benefit, averaging a 22% growth rate. From a genre perspective, strategy games experienced the highest engagement spikes at 30.5%, followed by role-playing games at 21.1%. However, the data also reveals a trend of declining engagement in the months following a release, suggesting that players often churn or move to other titles once they have consumed the new content.
Case studies of The Sims 4 and Dead Cells illustrate diverse strategic approaches to content delivery. Electronic Arts successfully utilized a "free-to-play" funnel by releasing a free update immediately before a paid expansion, resulting in the most successful launch week in the franchise's recent history. Conversely, Dead Cells demonstrated the power of crossovers, with its Return to Castlevania DLC driving a 225% increase in MAU. Despite these spikes, the analysis notes that retention remains a challenge, as a significant majority of players do not return for subsequent updates, emphasizing the constant need for fresh content to maintain a stable player base.
- DLC launches drive an average 11% increase in Monthly Active Users (MAU), with medium-sized games (250,000 to 2 million MAU) experiencing the highest growth at 22%.
- Strategy games see the largest engagement spikes from DLC at 30.5%, followed by role-playing games at 21.1%.
- In 2022, DLC sales accounted for 13% of total PC revenue and 7% of console revenue in the United States, indicating a higher reliance on add-on content on PC.
- Retention remains a persistent challenge, as most players do not return for subsequent updates and engagement typically declines in the months following a release.
- Strategic content delivery, such as Electronic Arts' free-to-play funnel for The Sims 4 or the 225% MAU spike driven by the Dead Cells 'Return to Castlevania' crossover, can significantly boost performance.
+1
NewzooMay 2023
Report13 pages
How DLC boosts engagement for PC and console games
Downloadable content (DLC) serves as a critical driver for player engagement and long-term monetization in the PC and console gaming sectors. Analyzing over 1,600 content releases between April 2020 and April 2023 across 37 major markets, data indicates that DLC launches provide an average monthly active user (MAU) boost of 11%. This impact is most pronounced for medium-sized games with 250,000 to 2 million MAU, which experienced a 22% growth during launch months. While these releases successfully spike interest, engagement typically declines in the months following the initial release, highlighting the necessity of a consistent content pipeline to maintain player interest.
Monetization trends in the United States further underscore the importance of post-launch content. In 2022, DLC accounted for 13% of PC revenue and 7% of console revenue, contributing to a landscape where in-game spending represents nearly half of total industry earnings. Strategy games emerged as the top-performing genre for DLC-driven growth, seeing a 30.5% average increase in MAU, followed by role-playing and adventure titles. These findings suggest that genres requiring deep mechanical updates or narrative expansions benefit most from the DLC model.
Case studies of The Sims 4 and Dead Cells illustrate diverse strategic approaches to content delivery. Electronic Arts successfully utilized a "free-to-play" transition combined with a free base-game update to prime the audience for the "Growing Together" expansion, resulting in its most successful launch week since 2015. Conversely, Dead Cells demonstrated the power of high-profile collaborations, such as the Castlevania DLC, which drove a 225% MAU increase. However, the data also reveals a retention challenge, as a significant majority of players who engage with new DLC do not remain active in subsequent non-update months. This emphasizes that while DLC is a potent tool for re-acquisition and revenue, sustaining a permanent player base remains a complex hurdle for live-service titles.
- DLC releases drive an average 11% increase in monthly active users (MAU), with medium-sized games (250,000 to 2 million MAU) seeing the highest impact at 22% growth.
- Strategy games benefit most from the DLC model, recording a 30.5% average increase in MAU, followed by role-playing and adventure titles.
- DLC is a significant revenue driver, accounting for 13% of PC revenue and 7% of console revenue in the U.S. during 2022.
- High-profile collaborations can trigger massive short-term spikes, evidenced by the Dead Cells 'Castlevania' DLC which drove a 225% increase in MAU.
- Strategic content delivery, such as Electronic Arts' combination of a free-to-play transition and base-game updates for The Sims 4, can achieve record-breaking expansion launches.
+1
NewzooMay 2023
Report52 pages
Global Games Market Report: August 2023
The global games market is entering a period of recovery in 2023, characterized by a projected revenue of $187.7 billion and a total player base of 3.38 billion. This 2.6% year-on-year growth signals a stabilization following the post-pandemic market correction of 2022. While mobile gaming remains the largest revenue segment, console gaming serves as the primary catalyst for this year’s expansion, rebounding significantly from previous development delays. Looking toward 2026, the industry is expected to maintain this upward trajectory, with total revenues forecasted to reach $212.4 billion.
Regional performance remains uneven, as strong console demand in Western markets contrasts with slower growth in the Asia-Pacific region, where regulatory challenges in China continue to dampen momentum. To mitigate rising production costs and extended development cycles, studios are increasingly prioritizing live-service monetization models and integrating generative AI into their workflows. While these technologies offer potential for streamlined asset creation and prototyping, their long-term viability is complicated by unresolved legal and ethical concerns regarding copyright and intellectual property.
The industry is undergoing a structural shift toward digital-first engagement, evidenced by the continued decline of physical media and the rise of transmedia strategies and influencer-led development. Hardware diversification is also accelerating, with the emergence of complementary handheld devices expanding the reach of traditional platforms. Despite these advancements, specific genres are experiencing shifting player preferences; while adventure and shooter titles remain dominant, the battle royale genre is losing traction. Furthermore, the mobile sector faces persistent headwinds in monetization and user acquisition, largely driven by evolving privacy policies that have impacted the performance of previously lucrative genres like RPGs.
- The global games market is projected to reach $187.7 billion in 2023, reflecting a 2.6% year-on-year growth and a total player base of 3.38 billion.
- Console gaming is the primary driver of 2023 market expansion, rebounding from previous development delays to help push total industry revenues toward a forecasted $212.4 billion by 2026.
- Studios are increasingly adopting live-service monetization and generative AI to combat rising production costs and longer development cycles, despite ongoing legal and ethical uncertainties surrounding IP.
- Regional growth is uneven, with strong Western console demand contrasting with slower performance in the Asia-Pacific region due to regulatory challenges in China.
- The mobile gaming sector faces significant headwinds in user acquisition and monetization as evolving privacy policies negatively impact the performance of genres like RPGs.
+3
NewzooJan 2023
Report42 pages
How Different Generations Engage with Video Games Today
Gaming has evolved into the primary entertainment medium for younger generations, with 94% of Gen Alpha identifying as game enthusiasts. This shift signifies a transition from gaming as a solitary hobby to a multi-dimensional "way of life" that encompasses playing, viewing, and socializing. While mobile gaming maintains universal appeal across all age groups, younger cohorts like Gen Alpha and Gen Z are significantly more likely to engage across multiple platforms and participate in virtual social environments. These younger players demonstrate high spending conversion rates, with approximately 60% investing in games, often driven by a desire for social immersion and diverse genres such as Adventure and Battle Royale.
In contrast, older generations like Gen X and Baby Boomers exhibit more utilitarian engagement patterns. These cohorts primarily favor casual puzzle-solving titles and are motivated by achievement, mastery, and time-saving mechanics. While 70% of younger players are "player-viewers" who consume gaming video content for entertainment and social connection, older players use video content more informationally, such as for reviews or tutorials. This generational divide extends to brand discovery; younger players are increasingly open to discovering new brands within game worlds, making the medium a vital marketing tool for reaching modern consumers.
The global gaming landscape is characterized by both universal franchises and distinct regional preferences. Major titles like Call of Duty, Fortnite, and Genshin Impact maintain a massive international presence, yet markets such as China, Japan, and South Korea continue to support region-specific hits like Honor of Kings and Lineage. Across these diverse geographies, the 2023 data highlights that gaming has become a central pillar of social interaction and brand engagement, particularly as younger generations integrate virtual experiences into their daily identities and consumption habits.
- Gaming has become the primary entertainment medium for younger generations, with 94% of Gen Alpha identifying as game enthusiasts.
- Approximately 60% of younger players invest in games, driven by a preference for social immersion and genres like Adventure and Battle Royale.
- 70% of younger players are 'player-viewers' who consume gaming content for social connection, whereas older generations use such content primarily for information like reviews and tutorials.
- Younger cohorts engage across multiple platforms and virtual social environments, while Gen X and Baby Boomers favor casual puzzle titles focused on mastery and time-saving mechanics.
- Younger players are increasingly receptive to brand discovery within game worlds, positioning gaming as a critical marketing channel for modern consumer engagement.
+1
NewzooJan 2023
Report66 pages
How UGC, AI, & Cloud Are Transforming Gaming
The gaming industry is currently undergoing a fundamental transformation driven by the social behaviors of Gen Alpha and Gen Z, over 90% of whom utilize gaming as their primary interactive outlet. This demographic shift has catalyzed the rise of User-Generated Content (UGC), artificial intelligence, and cloud infrastructure, collectively democratizing development and allowing indie titles to compete with AAA productions. The cloud gaming market is expanding rapidly, reaching nearly 400 million users within four years, while the integration of AI in gaming is projected to achieve a $4.2 billion valuation by 2029.
UGC has emerged as a critical driver of retention, with dominant platforms like Roblox, Minecraft, and Fortnite accounting for 19% of total global playtime and distributing over $1.3 billion to creators in 2023. To overcome the technical and legal hurdles of content creation, the industry is increasingly turning to generative AI, a sector expected to reach $1.8 billion by 2025. These tools automate complex processes such as texture upscaling and level generation, lowering the barrier to entry for creators across diverse genres.
While cloud technology offers the potential for real-time updates and massive concurrency, infrastructure limitations remain a significant bottleneck. Approximately 76% of players identify latency as a primary concern, suggesting that while 5G will eventually facilitate mass consumer adoption, the immediate utility of the cloud lies in B2B applications like secure playtesting and instant discoverability. The convergence of these technologies is ultimately moving the industry toward a live-service ecosystem of "endless games," where the boundaries between traditional media and interactive community-driven platforms continue to blur.
- User-generated content (UGC) is a primary driver of player retention, with Roblox, Minecraft, and Fortnite accounting for 19% of global playtime and distributing $1.3 billion to creators in 2023.
- The integration of AI in gaming is projected to reach a $4.2 billion valuation by 2029, while the generative AI sector specifically is expected to hit $1.8 billion by 2025.
- Cloud gaming has scaled to nearly 400 million users in four years, though 76% of players cite latency as a primary barrier to mass adoption.
- Generative AI is lowering development barriers by automating complex technical tasks like texture upscaling and level generation, enabling indie titles to compete with AAA productions.
- Over 90% of Gen Alpha and Gen Z now utilize gaming as their primary interactive outlet, forcing a shift toward live-service ecosystems and community-driven platforms.
+2
NewzooJan 2023
Report58 pages
PC & Console Gaming Report 2023
The PC and console gaming market entered a corrective phase in 2022, generating $92.3 billion in revenue despite a 2.2% year-on-year decline and a 15% drop in playtime. This contraction represents a stabilization toward pre-pandemic levels rather than a long-term downturn, as the market still outperformed pre-COVID forecasts by more than $32 billion. While total engagement fell, particularly among hardcore players who reduced playtime by 37%, the industry maintains a massive global audience of 1.1 billion PC and 611 million console players. This foundation is increasingly defined by a shift toward recurring revenue, with microtransactions and downloadable content now accounting for nearly half of all consumer spending.
Market dynamics are currently shaped by the dominance of established live-service titles and the successful integration of transmedia strategies. Games like Fortnite and Roblox continue to lead in monthly active users, while media adaptations have proven effective at revitalizing older intellectual properties. The player base has also become more diverse and socially driven, with women comprising 40% of the audience and 72% of users engaging across multiple platforms. Beyond traditional gameplay, three-quarters of players participate in social activities or content creation, indicating that gaming has evolved into a broader lifestyle ecosystem where multi-platform "core gamers" represent the highest-value consumer segment.
The outlook for 2023 and beyond suggests a robust recovery fueled by stabilized hardware supply chains and a dense schedule of highly anticipated blockbuster releases. While PC revenue is expected to grow steadily, console gaming is positioned as the primary driver of market expansion over the next three years. High consumer awareness for upcoming major titles, combined with the continued pivot toward hybrid monetization and cross-media expansion, points toward a resilient industry capable of sustaining growth well above historical norms. This trajectory reinforces the transition of the sector from a product-based model to a service-oriented landscape defined by long-term engagement and social connectivity.
- The PC and console market generated $92.3 billion in 2022, representing a 2.2% year-on-year decline that signals a stabilization toward pre-pandemic levels rather than a long-term downturn.
- Microtransactions and downloadable content now account for nearly 50% of total consumer spending, reflecting a fundamental industry shift from product-based sales to a service-oriented model.
- Engagement metrics saw a significant contraction in 2022, with total playtime dropping 15% and hardcore player activity falling by 37%.
- The industry maintains a massive reach of 1.1 billion PC players and 611 million console players, with 72% of users now engaging across multiple platforms.
- Console gaming is projected to be the primary driver of market expansion over the next three years, supported by stabilized hardware supply chains and a dense pipeline of blockbuster releases.
+2
NewzooJan 2023
Report36 pages
A New Era of Engagement in Media & Entertainment
The media and entertainment landscape is undergoing a fundamental generational shift toward active engagement, characterized by a seamless blend of physical and digital activities. Younger audiences, particularly Gen Z, are leading this transition by prioritizing interactive experiences over passive consumption. For the first time, Gen Z spends more time on video games and virtual worlds, averaging 12.2 hours per week, than on traditional broadcast or subscription television. This demographic also demonstrates a high level of creative participation, with 68% identifying as digital creators and spending three times more hours on user-generated content than Gen X.
Video games have emerged as the primary driver of this engagement, commanding a 72% active participation rate among US consumers. While movies and series still lead in total weekly volume at 17 hours, the gap is narrowing as gaming platforms like Fortnite and Roblox evolve into holistic entertainment hubs. These virtual spaces now serve as venues for socializing, attending concerts, and digital commerce, effectively functioning as early iterations of a persistent metaverse. This shift is further evidenced by the success of transmedia franchises and cross-media intellectual property strategies that bridge the gap between gaming, film, and music.
The future of the industry lies in the convergence of physical and digital worlds through interoperable 3D spaces that foster deeper fandom. Brands are increasingly integrating into these ecosystems through digital collectibles and in-game partnerships to capture the attention of younger consumers. High-profile investments in virtual fashion and NFTs underscore the growing economic value of digital assets within these environments. Ultimately, the industry is moving away from a model of passive viewership toward one defined by persistent, interactive, and creator-driven experiences that unify physical and virtual identities.
- Gen Z now spends an average of 12.2 hours per week on video games and virtual worlds, surpassing the time they dedicate to traditional broadcast or subscription television.
- Video games command a 72% active participation rate among US consumers, narrowing the volume gap with traditional media, which currently averages 17 hours of weekly consumption.
- 68% of Gen Z identify as digital creators, spending three times more hours on user-generated content than Gen X.
- Gaming platforms like Fortnite and Roblox are evolving into holistic entertainment hubs that facilitate socializing, live concerts, and digital commerce.
- Industry growth is increasingly driven by transmedia strategies and the integration of brands into virtual ecosystems through digital collectibles and in-game partnerships.
+1
NewzooJan 2023
Report28 pages
Newzoo’s Global Gamer Study 2023
Gaming engagement in 2023 has evolved into a multidimensional experience that extends far beyond active play to include viewing, socializing, and content creation. Data indicates that 79% of the total online population are game enthusiasts, with over half of all consumers engaging with games in more than one way. This trend is most pronounced among younger generations; 94% of Gen Alpha and 90% of Gen Z are classified as enthusiasts, frequently participating in "other" engagement activities like visiting online gaming communities or attending conventions.
The research highlights a significant shift toward multi-platform play, with 47% of gamers utilizing at least two platforms. A particularly high-value cohort, "tri-platform players" (15% of the player base), averages over 11 hours of play per week and shows a high propensity for spending, with 85% having made in-game purchases in the last six months. While mobile remains the most accessible entry point due to low hardware barriers, console gaming maintains the highest player-to-payer conversion rate, driven by subscriptions and pay-to-play models. Across all platforms, 57% of players are payers, motivated primarily by special offers and the desire to unlock exclusive content or customization options.
Gaming platforms have also emerged as powerful marketing channels. Approximately 50% of players and viewers report discovering new brands through gaming, and players generally hold more positive attitudes toward brands—particularly in the sports, beverage, and technology sectors—compared to non-players.
This analysis is based on Newzoo’s 2023 Global Gamer Study, which utilized Computer-Assisted Web Interviewing (CAWI) between February and May 2023. The methodology involved a representative sample of 74,295 respondents aged 10 to 65 across 36 global markets, covering North America, Europe, MEA, Latin America, and Asia-Pacific.
- Gaming is now a multidimensional ecosystem where 79% of the online population are enthusiasts, with over 50% of consumers engaging through a mix of playing, viewing, socializing, and content creation.
- Younger demographics show the highest engagement levels, with 94% of Gen Alpha and 90% of Gen Z participating in gaming activities beyond just active play.
- Multi-platform gaming is a significant trend, with 47% of gamers using at least two platforms and a high-value 'tri-platform' cohort (15% of players) averaging over 11 hours of play per week.
- Across all platforms, 57% of players are payers, with 85% of tri-platform players having made in-game purchases in the last six months to access exclusive content or customization.
- While mobile remains the most accessible entry point, console gaming maintains the highest player-to-payer conversion rate due to subscription and pay-to-play models.
+1
NewzooJan 2023
Report29 pages
Analyzing the Consumer and Market Impacts of Chinese Games Market Policies
China’s gaming market, the largest in the world by revenue and player count, is currently defined by a complex and increasingly restrictive regulatory environment. Primary governmental concerns center on minor protection and the mitigation of gaming addiction, which officials often characterize as a negative social influence. Key mandates include strict playtime limits for users under 18—restricted to one hour on weekend and holiday evenings—and the implementation of mandatory real-name verification systems. While minor spending accounts for less than 2% of revenue for major firms like Tencent and NetEase, these regulations threaten long-term market growth by reducing the future pipeline of engaged players and esports talent.
The administrative process for securing game licenses has become a significant barrier to entry. Following a nine-month freeze on approvals ending in early 2022, the government has adopted a rigorous scoring system that evaluates titles on societal values, cultural propagation, and original design. Foreign entities face additional hurdles, as they must partner with local publishers and navigate an approval process that is often slower than that for domestic titles. Consequently, many developers have shifted focus toward multi-platform releases, as a single license now covers mobile, PC, and console versions, streamlining the path to market.
Despite these restrictions, a robust grey market persists. Players frequently utilize virtual private networks (VPNs) and game accelerators to access international platforms like Steam, while console users often purchase hardware and software from overseas markets to bypass local content limitations. Additionally, some mobile developers utilize ad-based monetization models to operate without formal licenses, though regulators have recently begun cracking down on this practice.
In response to domestic pressures, Chinese gaming giants are aggressively expanding internationally. This strategy involves establishing overseas development studios, acquiring global talent, and launching international publishing labels. By leveraging their expertise in free-to-play mechanics and live operations, Chinese companies are successfully capturing market share in Western and other Asian markets, effectively diversifying their revenue streams away from the unpredictable regulatory landscape at home.
- Chinese gaming giants like Tencent and NetEase are aggressively expanding internationally through studio acquisitions and global publishing labels to mitigate domestic regulatory volatility.
- Government regulations restrict users under 18 to one hour of gaming on weekend and holiday evenings, a policy that threatens the long-term pipeline of players and esports talent despite minor spending accounting for less than 2% of major firms' revenue.
- The game licensing process now utilizes a rigorous scoring system evaluating societal values and cultural propagation, following a nine-month approval freeze that ended in early 2022.
- Foreign developers face significant barriers to entry, requiring local publishing partners and navigating a slower approval process compared to domestic titles.
- Developers are increasingly utilizing multi-platform releases to streamline market entry, as a single license now covers mobile, PC, and console versions.
+1
NewzooNov 2022
Report43 pages
Global Cloud Gaming Report: 2022
The global cloud gaming market is entering a phase of maturity, with 2022 revenues projected to reach $2.4 billion supported by a base of 31.7 million paying users. Despite high-profile shifts in the ecosystem, such as the closure of Google Stadia, the industry remains fundamentally viable as major platform holders like Xbox and PlayStation successfully integrate cloud technology to complement traditional hardware. This evolution is primarily driven by the increasing seamlessness of services, which allows players to bypass local hardware limitations and access high-end content instantly across a diverse range of devices.
Market projections indicate a robust growth trajectory through 2025, at which point paying users are expected to reach 86.9 million and annual revenues are forecasted to climb to $8.2 billion. This expansion is underpinned by the global rollout of 5G networks, improved service profitability, and the emergence of cloud infrastructure as the foundational backbone for the metaverse. Strategic scaling by major players, including Alibaba’s YuanJing, aims to support massive concurrent user experiences while overcoming the constraints of physical hardware on a global scale.
Technological innovation in infrastructure-as-a-service models is further accelerating adoption by lowering costs for both telecom operators and consumers. By utilizing GPU edge computing within carrier networks, providers can deliver high-quality gaming experiences with reduced latency. The industry is also refining its internal metrics and consumer segmentation, distinguishing between cloud-enabled and cloud-native content to better target diverse player demographics. These developments suggest that cloud gaming is transitioning from a niche technology into a central pillar of the broader interactive entertainment landscape.
- The global cloud gaming market is projected to grow from $2.4 billion in 2022 to $8.2 billion by 2025.
- The paying user base is expected to expand significantly from 31.7 million in 2022 to 86.9 million by 2025.
- Cloud gaming is shifting from a niche technology to a core industry pillar as major platforms like Xbox and PlayStation integrate cloud services to complement traditional hardware.
- Technological advancements, specifically the deployment of 5G networks and GPU edge computing within carrier networks, are reducing latency and lowering costs for providers and consumers.
- Cloud infrastructure is increasingly positioned as the foundational backbone for the metaverse, with companies like Alibaba’s YuanJing scaling to support massive concurrent user experiences.
+1
NewzooSept 2022
Report51 pages
Global Esports & Live Streaming Market Report 2022
The global esports and live streaming industry is undergoing a period of robust expansion, with total esports revenue projected to reach $1.38 billion in 2022 and an audience base of 532 million people. This growth trajectory is expected to continue, with market valuations potentially hitting $1.86 billion by 2025. While sponsorship remains the dominant revenue stream, accounting for nearly 60 percent of total earnings, the industry is actively diversifying its financial models. Organizations are increasingly pivoting toward direct-to-fan strategies, including digital merchandise, loyalty programs, and educational initiatives, to mitigate risk and transition toward sustainable, lifestyle-oriented business models.
The live streaming sector serves as a critical pillar of this ecosystem, with its audience projected to grow to 1.41 billion by 2025. Market dominance is currently split between major platforms like Twitch, YouTube Gaming, and Facebook Gaming, each leveraging distinct regional strengths. Twitch maintains a stronghold in Western PC and console markets, whereas YouTube and Facebook are capitalizing on the rapid proliferation of mobile gaming in emerging economies. These platforms are further evolving by integrating non-gaming content and interactive features to enhance user retention and broaden monetization opportunities.
Despite the positive outlook, the industry must navigate potential volatility stemming from shifting media consumption habits, evolving publisher investment strategies, and the lingering economic effects of the pandemic. Nevertheless, the sector remains highly attractive to stakeholders due to its core demographic of young, high-income professionals. As the market matures, the integration of co-streaming and the expansion into emerging regions—supported by localized platforms—will be essential for maintaining long-term growth and fostering deeper engagement with a global, digitally native audience.
- Global esports revenue is projected to reach $1.38 billion in 2022, with a total audience of 532 million, and is expected to grow to $1.86 billion by 2025.
- Sponsorship currently accounts for nearly 60% of total esports revenue, though organizations are shifting toward direct-to-fan models like digital merchandise and loyalty programs to improve financial sustainability.
- The live streaming audience is forecast to reach 1.41 billion by 2025, driven by the integration of non-gaming content and interactive features to boost user retention.
- Market dominance in live streaming is split between Twitch, which leads in Western PC and console markets, and YouTube Gaming and Facebook Gaming, which are capturing growth in mobile-first emerging economies.
- The industry remains highly attractive to stakeholders due to its core demographic of young, high-income professionals.
+3
NewzooJan 2022
Report18 pages
Consumer Insights: Games and Esports 2022
The Consumer Insights: Games and Esports 2022 report provides a comprehensive analysis of global gaming behaviors, motivations, and market engagement. The primary purpose of the research is to equip game developers, publishers, and industry stakeholders with actionable data to benchmark titles, understand player demographics, and identify growth opportunities across 36 diverse international markets. By examining over 100 key performance indicators, the analysis offers a granular view of how players interact with PC, console, and mobile platforms.
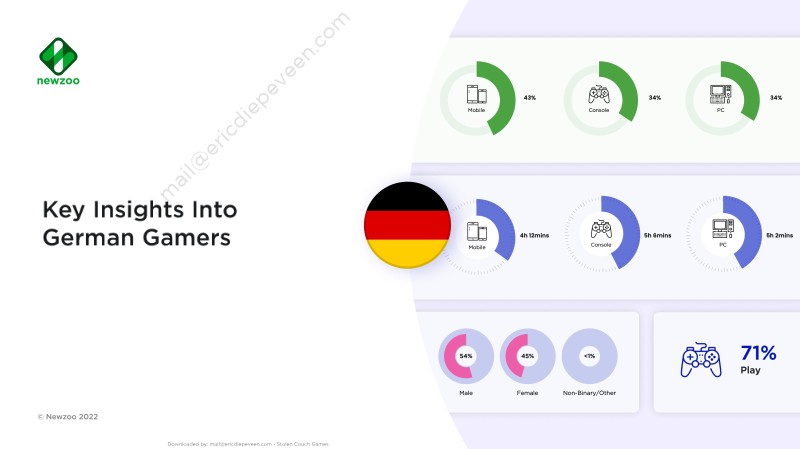
The research is underpinned by a robust methodology, drawing on survey data from over 75,000 consumers worldwide. The findings highlight distinct engagement patterns, such as the prevalence of specific gaming personas—notably Time Fillers and Mainstream Gamers—and the interplay between playing and viewing habits. For instance, data from the German market indicates that while playing remains the dominant activity, a significant portion of the population also engages with gaming video content and esports. Furthermore, the report identifies key drivers for consumer spending, noting that price sensitivity, the desire for exclusive content, and social connectivity are primary motivators for financial investment in games.
Covering a broad geographic scope that includes North America, Europe, Latin America, the Middle East, and the Asia-Pacific region, the report serves as a strategic tool for navigating the complex global gaming landscape. By synthesizing metrics such as monthly active users, daily active users, and lifetime player value, the analysis facilitates a deeper understanding of the motivations driving player behavior. Ultimately, the findings emphasize that a nuanced approach to audience segmentation and platform-specific engagement is essential for companies seeking to reach and retain diverse gaming populations in an increasingly competitive entertainment market.
- The research is based on a global dataset of over 75,000 consumers across 36 international markets, covering North America, Europe, Latin America, the Middle East, and the Asia-Pacific region.
- Consumer spending is primarily driven by three factors: price sensitivity, the desire for exclusive content, and the need for social connectivity.
- Gaming engagement is categorized into distinct personas, with 'Time Fillers' and 'Mainstream Gamers' identified as the most prevalent segments.
- Player behavior analysis utilizes over 100 key performance indicators, including monthly active users (MAU), daily active users (DAU), and lifetime player value (LPV).
- Engagement patterns in markets like Germany demonstrate that gaming video content and esports are significant activities that complement traditional gameplay.
+5
NewzooJan 2022