Investment
Documents
Video Games Ecosystem Report: Cyprus 2025
The report outlines a rapidly expanding video‑games ecosystem in Cyprus, projecting market revenue to surge from $1.2 billion in 2023 to $6.7 billion by 2025, with a compound annual growth rate of 5.96 % through 2030. The growth is driven by a growing number of tech firms relocating to the island, with 282 startups reported in July 2025—39 funded, 15 in Series A rounds, and one unicorn. Over 600 companies of varying sizes now operate locally, benefiting from Cyprus’s favorable tax regime, EU membership, and supportive regulatory framework.
Key success stories highlight local studios such as MY.GAMES and Ludus, whose mobile titles have achieved multi‑million downloads and cross‑platform revenue streams exceeding $2 million. The mobile segment dominates, with Playrix, Easybrain, and Outfit7 leading in casual and puzzle games; yet PC and console titles from Wargaming and Digital Vortex Entertainment demonstrate a growing presence in the market. Cross‑platform development and cloud gaming are emerging trends, offering opportunities for developers skilled across mobile and PC.
The island’s advantages include competitive corporate tax rates, strategic positioning between Europe and the Middle East, a growing talent pool enriched by relocation of experienced developers, and increasing investment in esports and blockchain gaming. The report also promotes the WN Conference Cyprus (September 2025) as a networking and market‑entry platform, anticipating attendance of 700+ participants. Overall, the data portray Cyprus as an attractive hub for game development and investment, poised for continued expansion through 2030.
- Cyprus's video game market revenue is projected to grow from $1.2 billion in 2023 to $6.7 billion by 2025, with a compound annual growth rate of 5.96% through 2030.
- The local ecosystem has expanded to over 600 companies, including 282 startups as of July 2025, with 39 funded, 15 in Series A rounds, and one unicorn.
- Mobile gaming remains the dominant segment, led by major players such as Playrix, Easybrain, and Outfit7, while PC and console development is represented by firms like Wargaming and Digital Vortex Entertainment.
- Local studios such as MY.GAMES and Ludus have successfully leveraged cross-platform development, with individual titles generating revenue exceeding $2 million.
- The industry is supported by a favorable tax regime, EU membership, and a strategic geographic position between Europe and the Middle East.
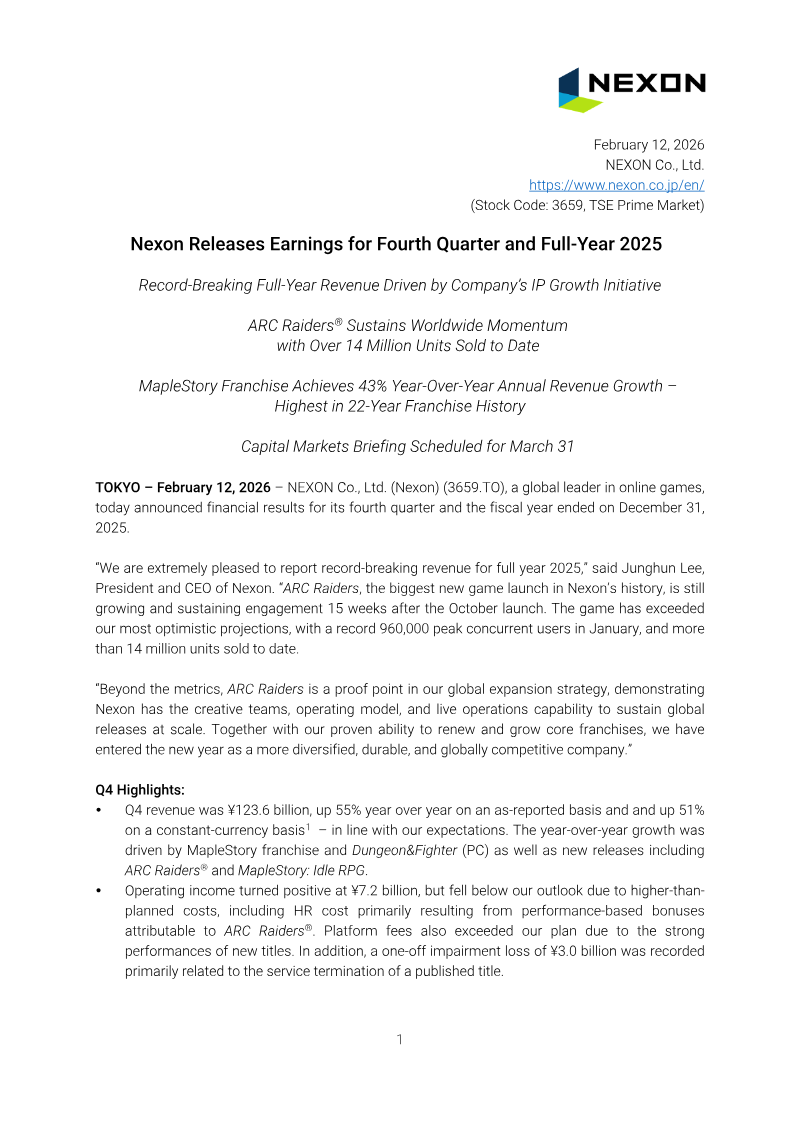
Nexon Releases Earnings for Fourth Quarter and Full-Year 2025
Nexon reported record-breaking financial results for the fiscal year ended December 31, 2025, driven by a strategic IP growth initiative that balanced the expansion of legacy franchises with successful new global launches. Full-year revenue reached ¥475.1 billion, a 6% increase year-over-year, while operating income remained stable at ¥124.0 billion. The fourth quarter saw a significant revenue surge of 55% to ¥123.6 billion, although net income declined 66% to ¥10.9 billion, primarily due to fluctuations in foreign exchange gains compared to the previous year and higher-than-anticipated costs related to performance bonuses and platform fees.
The growth was spearheaded by the launch of ARC Raiders, which sold over 14 million units within 15 weeks and achieved a peak of 960,000 concurrent users. Simultaneously, the 22-year-old MapleStory franchise delivered its highest annual revenue in history, growing 43% year-over-year. This performance offset a 21% decline in the Dungeon&Fighter franchise, despite a strong recovery in its PC segment in China and Korea. The period was also marked by a significant player trust initiative regarding MapleStory: Idle RPG; a coding error led Nexon to offer full refunds, resulting in a ¥9 billion reduction in Q4 revenue.
Geographically, the results reflect Nexon’s successful diversification beyond its traditional Asian strongholds into Western markets via console and PC platforms. Looking ahead to the first quarter of 2026, the company expects revenue growth between 32% and 44%, supported by sustained momentum from new titles and major updates to core IPs. Nexon remains committed to aggressive shareholder returns, doubling its dividend and completing a ¥100 billion share buyback program during the fiscal year.
- Nexon achieved record full-year 2025 revenue of ¥475.1 billion, a 6% year-over-year increase, with operating income holding steady at ¥124.0 billion.
- The new title ARC Raiders was a major growth driver, selling over 14 million units within 15 weeks and reaching a peak of 960,000 concurrent users.
- The 22-year-old MapleStory franchise reached record annual revenue with 43% year-over-year growth, helping to offset a 21% decline in the Dungeon&Fighter franchise.
- Q4 net income dropped 66% to ¥10.9 billion due to foreign exchange fluctuations, increased platform fees, and performance bonuses.
- A player trust initiative following a coding error in MapleStory: Idle RPG resulted in a ¥9 billion revenue reduction in Q4 due to full customer refunds.
Vietnam Innovation and Private Capital Report: 2025
Vietnam’s 2025 Innovation and Private Capital Report positions the country as a rapidly ascending tech‑investment hub in Southeast Asia, underpinned by steady macro growth and decisive policy support. A 6 % annual real GDP expansion, a $36 B digital economy, and the landmark Resolution No. 57‑NQ/TW collectively create a macro‑environment that attracts both domestic and foreign capital. Private‑capital activity in 2024 totaled $2.3 B across 141 deals, with buyouts dominating but early‑stage venture capital rebounding sharply in the second half of the year. High‑tech sectors—particularly AI, AgriTech, Green Tech, semiconductors, and data centers—experienced multi‑fold funding surges, reflecting a shift toward technology‑driven value creation.
The labor market fuels consumer and industrial demand: Vietnam ranks second in Southeast Asia for workforce size, with a growing middle‑affluent class projected to exceed 45 % of the population by 2030. Strong education outcomes and a youthful, tech‑savvy demographic drive growth in retail, e‑commerce, digital health, and edtech. Tier‑2 cities such as Bac Ninh, Can Tho, and Da Nang emerge as new growth poles, supported by government investment in transportation, renewable energy, and digital infrastructure.
Resolution No. 57 sets ambitious 2030–2045 targets—30–50 % GDP share from digital and high‑tech exports, 80 % cashless transactions, and 2 % of GDP allocated to R&D (60 % private). It outlines strategic actions in AI, 6G, talent development, and digital governance to attract at least five global tech giants for R&D and manufacturing. Projected economic gains from AI alone could reach $120 B by 2040, while renewable energy and climate‑tech investments are already reshaping the power sector through flexible PPAs and green‑credit programs.
Overall, Vietnam’s coordinated policy framework, expanding talent pool, and maturing private‑capital ecosystem converge to make the country a compelling destination for long‑term value creation across high‑growth technology, green infrastructure, and consumer markets within Southeast Asia.
- Vietnam’s digital economy has reached a valuation of $36 billion, supported by a 6% annual real GDP growth rate.
- Private capital investment in 2024 totaled $2.3 billion across 141 deals, with a notable rebound in early-stage venture capital during the second half of the year.
- Resolution No. 57-NQ/TW mandates that by 2030–2045, digital and high-tech exports must account for 30–50% of GDP, with 2% of GDP allocated to R&D.
- The middle-affluent class is projected to exceed 45% of the total population by 2030, driving significant demand in retail, e-commerce, digital health, and edtech.
- AI integration is projected to generate $120 billion in economic gains for Vietnam by 2040, supported by strategic government initiatives in 6G and digital governance.
Aream & Co. Gaming CEO Survey 2025
The survey, conducted by Aream & Co., gauges executive optimism regarding consumer spending on gaming in 2025 across multiple channels and functional areas. Overall, 49 % of respondents view spending as “more optimistic,” another 49 % see it as unchanged, and only 2 % are less optimistic. When broken down by platform, mobile spending is perceived as more optimistic (49 %) while PC and console views are split between “more” (15–33 %) and “about the same.” In‑app purchases are viewed as more optimistic (80 %) versus in‑app advertising (41 %).
Key challenges identified include content saturation and over‑supply, with 33 % citing these as concerns; marketing environment issues affect 49 %, and macro conditions are a worry for 17 %. Despite these, 54 % anticipate more new games in 2025, and 37 % expect higher average budgets. Marketing spend is expected to rise for 48 %, while engineering and game development are seen as more optimistic (71 % and 42 %).
The survey also highlights a strong appetite for mergers and acquisitions, with 71 % expecting more M&A activity. Advanced integration across multiple functions is viewed as more optimistic (49 %) but limited implementation remains a concern.
The data derive from a global sample of gaming CEOs, reflecting perspectives across mobile, PC, console, and various functional departments. The findings suggest a cautiously optimistic outlook for 2025, tempered by supply‑side pressures and marketing challenges.
- Industry sentiment for 2025 is largely stable or positive, with 98% of CEOs reporting that consumer spending will be either unchanged (49%) or more optimistic (49%).
- M&A activity is expected to accelerate, with 71% of executives anticipating an increase in deal-making throughout 2025.
- In-app purchases are the primary revenue driver, with 80% of respondents optimistic about growth compared to only 41% for in-app advertising.
- Investment in development remains a priority, as 71% of CEOs are optimistic about engineering budgets and 42% about game development, with 37% expecting higher average project budgets.
- Marketing remains a critical pain point, with 49% of executives citing the current marketing environment as a major challenge despite 48% planning to increase their marketing spend.
Connecting Digital Investments and Real Estate: Malaysia’s Competitive Advantage
The analysis establishes that Malaysia’s competitive edge stems from the tight integration of digital investment flows with commercial‑real‑estate development, positioning the country as a regional hub for high‑value technology activities. By concentrating the majority of foreign digital capital within a narrow geographic corridor, the nation creates a synergistic environment where advanced infrastructure and specialized real‑estate assets reinforce each other, driving sustained economic benefits.
Data reveal that 95 percent of approved digital‑investment projects, amounting to RM 342.6 billion, are located in the Klang Valley, Johor and Penang, with the Klang Valley alone accounting for roughly three‑quarters of total digital foreign direct investment. This region hosts a diversified portfolio that includes data‑centre and cloud services, fintech platforms, artificial‑intelligence applications, and global‑business‑services/KPO operations, collectively generating RM 13.9 billion in digital‑sector employment value. Johor’s contribution is anchored in large‑scale hyperscale data‑centre campuses, while Penang’s niche lies in semiconductor‑linked activities, offering targeted opportunities for developers.
A streamlined MDLR framework, co‑created with the Malaysia Digital Economy Corporation, reduces digital‑real‑estate standards to four core criteria, shifting focus to building‑level attributes such as robust digital infrastructure, connectivity, energy resilience and security. This refined approach equips developers and investors with clear benchmarks to align property supply with the evolving demands of the digital economy, ensuring that real‑estate assets remain adaptable and future‑proof across the identified clusters.
- Malaysia has attracted RM 342.6 billion in approved digital investments, with 95 percent of these projects concentrated in the Klang Valley, Johor, and Penang.
- The Klang Valley serves as the primary digital hub, accounting for approximately 75 percent of the nation's total digital foreign direct investment.
- Digital-sector employment across these investment clusters generates a total value of RM 13.9 billion.
- Regional investment is specialized, with Johor focusing on hyperscale data-centre campuses and Penang concentrating on semiconductor-linked activities.
- The MDLR framework standardizes digital real estate into four core criteria: digital infrastructure, connectivity, energy resilience, and security.
Major Organizational, Operational and Portfolio Reset to Reclaim Creative Leadership and Restore Sustainable Growth
Ubisoft has initiated a major organizational and operational reset designed to reclaim creative leadership and restore sustainable growth in an increasingly selective AAA market. This strategic pivot addresses rising development costs and the competitive challenges of establishing new intellectual properties. The transformation is built upon three primary pillars: the implementation of a new operating model, a refocused game portfolio with a revised three-year roadmap, and a significant rightsizing of the global organization to improve agility and reduce fixed costs.
The new operating model decentralizes production into five distinct Creative Houses supported by a centralized Creative Network and Core Services. These houses are specialized by genre and business model, focusing on billionaire brands like Assassin’s Creed and Far Cry, competitive shooters such as Rainbow Six and Ghost Recon, live-service experiences, immersive narrative universes, and casual family-friendly titles. To support this focus, Ubisoft has discontinued six games—including the Prince of Persia: The Sands of Time remake and four unannounced titles—while allocating additional development time to seven other projects to ensure higher quality standards.
Financial restructuring is a critical component of this reset, with the company targeting a total reduction in fixed costs of approximately €500 million by March 2028 compared to FY23 levels. This includes the closure of studios in Halifax and Stockholm, alongside restructurings in Abu Dhabi, RedLynx, and Massive. For FY26, the group anticipates net bookings of approximately €1.5 billion and a non-IFRS EBIT loss of around €1 billion, largely due to a €650 million one-off accelerated depreciation from canceled and delayed titles. Moving forward, the group aims to reach a run-rate fixed cost base of €1.25 billion by 2028, prioritizing robust cash generation and a more disciplined approach to capital allocation.
- Ubisoft is targeting a €500 million reduction in fixed costs by March 2028 compared to FY23 levels to restore sustainable growth.
- The company is restructuring into five specialized Creative Houses to focus on core franchises like Assassin’s Creed, Far Cry, and Rainbow Six while improving operational agility.
- Ubisoft has canceled six projects, including the Prince of Persia: The Sands of Time remake and four unannounced titles, while extending development timelines for seven others to prioritize quality.
- The company projects an FY26 non-IFRS EBIT loss of approximately €1 billion, driven by €650 million in one-off depreciation charges from canceled and delayed games.
- To achieve a target run-rate fixed cost base of €1.25 billion by 2028, Ubisoft is closing studios in Halifax and Stockholm and restructuring operations in Abu Dhabi, RedLynx, and Massive.
2026 US Venture Capital Outlook
The 2026 US venture capital outlook projects a cautiously optimistic landscape, driven largely by an explosive surge in early‑stage activity and the continued dominance of artificial intelligence (AI) startups. AI firms now command 65 % of venture capital, fueling near‑record first‑financing counts and setting a high bar for late‑stage valuations. While liquidity remains the primary constraint—exit values are projected below $300 billion and limited LP enthusiasm persists—the emergence of improved secondary markets and a potential rebound in initial public offerings are expected to alleviate pressure. Multistage firms that focus on seed rounds are poised to sustain growth across both early and later stages, yet emerging managers may face fundraising challenges that could curtail diversification.
A widening gap between AI‑focused, high‑growth startups and their slower‑moving peers is evident. In Q3 2025 the United States hosted 830 active unicorns with a record $3.9 trillion post‑money valuation, yet many of these firms are liquidity‑constrained and struggle to secure follow‑on funding. AI companies dominate late‑stage deals, with median Series C and D+ valuations reaching $838 million; AI rounds exceed non‑AI deals by roughly 26 % at Series D+, underscoring investor confidence in the AI boom while highlighting potential risks if public AI valuations contract.
Fundraising is projected to rebound to $100‑$130 billion in 2026, largely driven by recycled distributions that are expected to account for roughly 70 % of new commitments. Strong exit activity through 2025 and renewed interest in AI‑focused funds—such as a $10 billion Andreessen Horowitz vehicle—underpin this outlook. However, risks remain: a potential liquidity reversal or recession‑induced sentiment decline could keep commitments below $100 billion, tempering the projected recovery.
- AI startups currently command 65% of all venture capital, driving record-high median valuations of $838 million for Series C and D+ rounds.
- The US venture capital market is projected to see a fundraising rebound to $100–$130 billion in 2026, with approximately 70% of new commitments expected to come from recycled distributions.
- As of Q3 2025, the US hosted 830 active unicorns with a combined post-money valuation of $3.9 trillion, though many face significant liquidity constraints and difficulties securing follow-on funding.
- AI-focused late-stage deals currently command a 26% valuation premium over non-AI counterparts, creating a widening performance gap between high-growth AI firms and slower-moving peers.
- Liquidity remains a primary market constraint, with total exit values for 2026 projected to remain below $300 billion despite anticipated improvements in secondary markets and IPO activity.
China WeChat Mini Games Industry Report 2026
The WeChat Mini Games industry in China has emerged as a dominant, high-growth sector within the broader digital ecosystem. As of 2026, the market is characterized by a rapid shift from simple casual titles toward mid-to-hardcore genres, including strategy, RPG, and tower defense games. This evolution is underscored by a significant increase in paid user acquisition, with over 51,000 games actively running advertisements in 2025, a figure that substantially outpaces traditional mobile game growth.
Market data indicates that the Mini Games sector generated RMB 53.535 billion (approximately $7.65 billion) in 2025, representing a 34.39% year-over-year increase, with projections exceeding RMB 70 billion for 2026. Revenue is primarily driven by in-app purchases, which account for 68.11% of total earnings, while advertising monetization contributes the remaining 31.89%. WeChat maintains a leadership position among competing platforms, boasting a 51.5% penetration rate and an industry-wide monthly active user base of 571 million as of August 2025.
User engagement remains high, with the average daily playtime exceeding 60 minutes and a daily session frequency of approximately 5.1 times. The core demographic is aged 24–40, with a majority residing in tier-3 cities or below. Successful titles increasingly utilize hybrid gameplay mechanics, such as combining MMORPG elements with idle or strategy features, to maintain player retention.
For international developers, the market presents significant opportunities but requires navigating complex regulatory and technical barriers. Successful entry necessitates partnering with local Chinese publishers to manage ISBN licensing, payment integration, and platform-specific performance optimizations. Technical requirements are stringent, as games must typically load in under 10 seconds and adhere to strict package size limits, often requiring the use of specialized engines like Cocos or Laya to ensure compatibility within the WeChat environment.
- The WeChat Mini Games market reached RMB 53.535 billion in 2025, a 34.39% year-over-year increase, with projections exceeding RMB 70 billion for 2026.
- WeChat dominates the sector with a 51.5% platform penetration rate and 571 million monthly active users as of August 2025.
- Revenue is primarily driven by in-app purchases (68.11%), supplemented by advertising monetization (31.89%).
- The industry is shifting toward mid-to-hardcore genres like RPG and strategy, supported by over 51,000 games actively running paid advertisements in 2025.
- Core user engagement is high, averaging over 60 minutes of daily playtime across 5.1 daily sessions, primarily among users aged 24–40 in tier-3 cities or below.
Leveling Up for the New Reality: The Gaming Report
The report examines the global gaming market’s evolution from 2017 to 2028, highlighting a post‑pandemic correction that has shifted growth expectations from double‑digit rates to modest expansion. Global revenue by type rose 1 % CAGR (2017–2023), with mobile, PC, and console segments contributing $1.2 trillion in 2023; cloud/VR sales remain niche but are projected to grow at 5 % CAGR (2023–2028). Emerging platforms such as cloud AR/VR and user‑generated content show market sizes of $939 million (2024) to $1.75 billion (2028), yet infrastructure constraints limit mass adoption.
Development economics reveal a widening gap: AAA development budgets increased 360 % (2012–2023 average) while sales and marketing costs rose 220 %, yet the number of AAA titles released fell by 73 %. Mobile publishers mirror this trend, with development costs up 54–92 % and releases declining. Console revenues are projected to outpace AAA budgets, with a 5 % CAGR in development spending versus 8 % in console revenue growth (2017–2028). Survey data indicate that most publishers expect to maintain or modestly increase budgets, with only 5–10 % planning reductions.
Monetization shifts are pronounced in consoles: subscription services and premium digital sales will dominate, while mobile revenue increasingly relies on in‑app advertising (up to 31 % of mobile share). Consumer willingness to accept ads varies by platform, with over half of core PC/console gamers open to advertising in premium titles. Geographic analysis shows Chinese players exhibit the highest willingness to pay, and emerging‑economy gamers spend more time playing than their developed‑economy counterparts. Age segmentation reveals younger cohorts favor action/adventure, whereas older players gravitate toward puzzles and casual games. The report concludes that technological advances, particularly generative AI, may enable cost efficiencies but will likely be leveraged to fund larger, higher‑quality titles rather than reduce overall budgets.
- AAA development budgets surged 360% between 2012 and 2023, while the volume of AAA title releases dropped by 73%, signaling a shift toward fewer, more expensive productions.
- Global gaming revenue grew at a 1% CAGR from 2017 to 2023, reflecting a post-pandemic correction that has moved the industry from double-digit growth to modest expansion.
- Mobile revenue is increasingly driven by in-app advertising, which now accounts for up to 31% of the segment's total share.
- While cloud and VR remain niche, they are projected to grow at a 5% CAGR through 2028, with emerging platforms like cloud AR/VR and user-generated content expected to reach $1.75 billion in market size by 2028.
- Console revenue is projected to grow at an 8% CAGR through 2028, outpacing the 5% CAGR in development spending for the same period.
Square Enix Next: That Excitement Once Again
Square Enix’s recent performance review exposes a persistent decline in revenue growth and profitability over the past three years, with operating income falling 32 % and ROE dropping 61 %. The downturn is driven primarily by weak margins in both high‑definition (HD) and small‑dungeon (SD) game segments, excessive portfolio fragmentation, sub‑optimal product design and promotion, and escalating development costs. While the MMO licensing arm remains the sole growth driver (+11 %), overall gaming revenue has slipped, with HD and SD titles declining 4 % and 5 % respectively. Operating margins for these segments hover around 35–40 %, noticeably higher than the industry average of 28 % but still lagging behind competitors, indicating inefficiencies that are not being adequately addressed.
The company’s medium‑term “Reboots” plan offers only high‑level directions without concrete key performance indicators or quantitative targets. Critical gaps include a lack of clear business‑portfolio strategy, insufficient disclosure on non‑core business rationales, and no defined mechanisms for monitoring progress or maximizing shareholder value. Capital allocation disclosures are similarly weak: cost‑of‑capital calculations, ROE and ROIC targets, and hurdle rates are absent, while share‑buyback authorization remains unused despite a sharp price decline. SG&A costs exceed peer norms by 5–6 ppt, driven largely by an oversized sales force, further eroding profit margins.
Geographically, SD game revenue is almost entirely domestic; the Japanese market has contracted 2 % annually since 2020, and overseas growth remains only 3 %. The company’s global SD strategy is inert, with a 7 % overseas expansion rate falling short of projected growth and flagship titles such as FFVII Ever Crisis deriving 70 % of revenue from Japan. Non‑core Amusement and Publishing businesses are undervalued, with a significant conglomerate discount relative to peers and declining sales and margins. Limited cross‑synergy between game and publishing arms further hampers value creation.
In summary, Square Enix faces a multifaceted challenge: declining core game performance, weak strategic direction and KPI setting, high SG&A costs, and an underperforming non‑core portfolio. Addressing these issues through tighter cost control, clearer performance metrics, aggressive overseas expansion, and potential portfolio optimization is essential to restore corporate value and achieve sustainable growth.
- Square Enix has experienced a significant financial decline over the past three years, marked by a 32% drop in operating income and a 61% decrease in return on equity (ROE).
- Core gaming segments are underperforming, with HD and SD game revenues falling 4% and 5% respectively, while MMO licensing remains the only growth driver at +11%.
- Operating margins for HD and SD segments remain inefficient at 35–40%, and SG&A costs exceed industry norms by 5–6 percentage points due to an oversized sales force.
- The company's 'Reboots' medium-term plan lacks concrete KPIs, quantitative targets, and clear capital allocation strategies, such as defined hurdle rates or ROIC goals.
- Square Enix’s SD game revenue is heavily reliant on the contracting Japanese market, with flagship titles like 'FFVII Ever Crisis' generating 70% of their revenue domestically.
Wyniki Finansowe 3Q25
This financial analysis details the third-quarter 2025 performance of PCF Group S.A. (People Can Fly), a global game development studio. The primary thesis centers on a strategic pivot toward financial stability following a period of reorganization and disappointing performance from self-published titles. The scope covers the group’s global operations, including studios in Warsaw, Montreal, Newcastle, and Dublin, with a specific focus on the nine-month period ending September 30, 2025.
The financial data reveals a significant net loss of 117 million PLN for the first nine months of 2025, compared to a 33.3 million PLN loss in the same period of 2024. This deficit is largely driven by substantial non-cash write-offs totaling over 100 million PLN. Key impairments include a 92 million PLN write-down for the project Lost Rift (Victoria) following its Early Access launch on September 25, 2025, which failed to meet sales and player reception expectations. Other write-offs include 6 million PLN for PCF Chicago goodwill and 5 million PLN for Unreal Engine licenses. Despite these losses, revenues increased to 152.1 million PLN from 131.9 million PLN year-over-year, bolstered by work-for-hire (WFH) projects such as Delta, Zulu, and Echo.
The group’s methodology emphasizes "adjusted EBITDA" to illustrate underlying operational health, reporting a corrected EBITDA of 6 million PLN for the first nine months of 2025. Following a reorganization that left the workforce at 756 employees, the company is shifting its strategy to prioritize cash flow. Future objectives include securing at least one new WFH contract by the end of 2025, scaling back the Lost Rift team to achieve self-funding by 2026, and halting investment in new self-published projects until the group generates positive cash flow. Current active partnerships include ongoing projects with Microsoft, Krafton, and Sony.
- PCF Group S.A. reported a net loss of 117 million PLN for the first nine months of 2025, a significant increase from the 33.3 million PLN loss recorded in the same period of 2024.
- A 92 million PLN write-down for the project 'Lost Rift' (Victoria) following its September 25, 2025, Early Access launch was the primary driver of the group's financial deficit.
- Despite the net loss, total revenue grew to 152.1 million PLN in the first nine months of 2025, up from 131.9 million PLN in 2024, driven by work-for-hire projects including Delta, Zulu, and Echo.
- The company reported an adjusted EBITDA of 6 million PLN for the first nine months of 2025, which management uses to demonstrate underlying operational health despite total losses.
- PCF Group is halting investment in new self-published titles until the company achieves positive cash flow and is prioritizing securing at least one new work-for-hire contract by the end of 2025.
Integrated Report: Value Creation Story
DeNA entered a transformative "Second Founding" phase in FY2024, marked by a significant financial recovery and a strategic pivot toward company-wide AI integration. Revenue reached 164.0 billion yen with a Non-GAAP operating profit of 32.9 billion yen, driven primarily by the global success of Pokémon Trading Card Game Pocket. While the Game Business remains the core profit engine, the organization is diversifying its portfolio across Live Streaming, Healthcare, and a record-performing Sports segment to mitigate the volatility of hit-driven cycles. The company has established a FY2026 Non-GAAP operating profit target of 15.0 billion yen, emphasizing sustainable, structural growth over short-term gains.
Central to this evolution is the "AI-ALL-IN" strategy, which aims to double productivity and launch approximately 10 AI-native products. This transition is supported by a robust human capital framework, including the DeNA AI Readiness Score (DARS) to track employee literacy and a shift toward market-linked, performance-based compensation. To manage development risks, the Game Business has adopted a "soft launch strategy" focused on iterative testing. Meanwhile, the Sports segment achieved 40 billion yen in revenue, and the Healthcare division is pivoting toward medical digital transformation despite facing recent impairment losses.
Governance and sustainability are integrated into this value creation story through a board composed of 50% independent directors and a rigorous risk management framework. DeNA maintains high standards for data security and has committed to a 58.8% reduction in Scope 1 and 2 emissions by FY2033. By balancing aggressive AI adoption with disciplined capital allocation—including strategic share sales and increased dividends—the organization seeks to harmonize social value with long-term profitability across its diverse digital and physical business ecosystems.
- DeNA achieved 164.0 billion yen in revenue and 32.9 billion yen in Non-GAAP operating profit in FY2024, largely fueled by the global performance of Pokémon Trading Card Game Pocket.
- The company is executing an 'AI-ALL-IN' strategy targeting a 100% increase in productivity and the launch of approximately 10 AI-native products.
- The Sports segment has become a major revenue pillar, generating 40 billion yen in the last fiscal year, helping to diversify the company away from hit-driven game cycles.
- Management has set a conservative FY2026 Non-GAAP operating profit target of 15.0 billion yen, prioritizing structural, sustainable growth over short-term volatility.
- To improve operational efficiency, the company implemented the DeNA AI Readiness Score (DARS) to track employee literacy and transitioned to a market-linked, performance-based compensation model.