Report32 pages
Midcore Gaming Apps Report 2023
The midcore mobile gaming market is undergoing a significant expansion as players increasingly migrate from hyper-casual titles toward games offering greater depth and complexity. Currently accounting for 35% of total US iOS gaming revenue, the midcore segment is defined by its high player retention and diverse monetization strategies. While these games face higher user acquisition costs than casual titles—averaging a $2 cost-per-install (CPI)—they leverage sophisticated LiveOps and multi-layered Battle Pass systems to drive long-term profitability. Strategy and RPG genres lead the market, while emerging trends like extraction shooters and season-based gameplay loops further solidify the segment's dominance.
Data from 2022 to 2023 highlights stark contrasts in performance across platforms and regions. Android remains the more cost-effective platform for developers, offering a $0.73 CPI compared to $3.86 on iOS, while also delivering nearly double the Day-7 return on ad spend (ROAS) at 6.1%. Geographically, North America represents the most expensive market with a $5.45 CPI, yet it maintains a strong 4.5% ROAS. Conversely, the EMEA region provides the best overall value, balancing a low $0.80 CPI with a competitive 4.4% ROAS. Genre-specific analysis shows that Shooters require the highest acquisition investment at $7.47 but yield the highest early returns, whereas RPGs offer the lowest entry cost at $0.60.
To maximize revenue and bypass traditional platform fees, midcore developers are increasingly adopting external web stores and aggressive LiveOps schedules, often running an average of 15 simultaneous active events. This shift toward complex, service-based ecosystems is supported by specialized growth acceleration platforms that provide the infrastructure for large-scale app marketing and monetization. By utilizing programmatic exchanges and targeted advertising solutions, developers can navigate the high-cost landscape of midcore gaming to secure a dedicated and high-value audience.
- Midcore games now account for 35% of total US iOS gaming revenue, driven by a player migration from hyper-casual titles toward deeper, more complex gameplay.
- Android is significantly more cost-effective for developers than iOS, with a $0.73 CPI compared to $3.86 and nearly double the Day-7 ROAS at 6.1%.
- The EMEA region offers the best market value, balancing a low $0.80 CPI with a competitive 4.4% ROAS, while North America remains the most expensive market at a $5.45 CPI.
- Genre-specific acquisition costs vary widely, with Shooters requiring the highest investment at $7.47 per install, while RPGs offer the lowest entry cost at $0.60.
- To drive long-term profitability and bypass platform fees, developers are increasingly utilizing external web stores and aggressive LiveOps strategies, often maintaining 15 simultaneous active events.
+1
LiftoffJan 2024
Report19 pages
Top 500 Titles on Twitch 2023
The gaming industry experienced record-breaking engagement in 2023, with the top 500 titles on Twitch generating nearly 15 billion hours of watch time. This viewership was characterized by extreme concentration at the top of the rankings, as a mere 11 titles accounted for half of the total watch time. Grand Theft Auto V led the industry with 1.3 billion hours watched, while Fortnite demonstrated the highest level of creator engagement, boasting 2.8 million unique channels—more than double its nearest competitor.
The streaming landscape across 2023 showcased a diverse mix of modern AAA releases, indie sensations, and enduring legacy titles. While competitive staples like VALORANT and League of Legends dominated the upper echelons, the rankings revealed significant staying power for older franchises. Titles such as Super Mario 64, Age of Empires II, and various entries from The Legend of Zelda series maintained millions of hours of watch time, often outperforming newer releases. This trend highlights a bifurcated market where viewers gravitate toward both high-stakes competitive play and nostalgic speedrunning or retro content.
The data, which excludes non-gaming categories like "Just Chatting" and tabletop games to focus strictly on video game performance, indicates that even titles at the bottom of the top 500 maintain substantial audiences. Games ranked between 400 and 500, such as Tekken 8 and PICO PARK, still commanded approximately 1.8 million to 2.2 million hours watched each. This comprehensive analysis across PC, console, and mobile platforms underscores a resilient ecosystem where niche indie horror, classic RPGs, and modern shooters coexist, maintaining high viewer retention despite broader economic volatility within the development sector.
- The top 500 Twitch titles generated nearly 15 billion hours of watch time in 2023, with 50% of that total concentrated in just 11 games.
- Grand Theft Auto V was the most-watched title of 2023, accumulating 1.3 billion hours of viewership.
- Fortnite led the industry in creator engagement with 2.8 million unique channels, more than double the count of its nearest competitor.
- The streaming market is bifurcated between high-stakes competitive staples like League of Legends and VALORANT and legacy titles like Super Mario 64 and Age of Empires II that maintain millions of hours of watch time.
- Even titles ranked between 400 and 500, such as Tekken 8 and PICO PARK, sustained significant engagement, each generating between 1.8 million and 2.2 million hours watched.
LurkitJan 2024
Report30 pages
Gaming Industry Report: Global & MENAP Outlook Q4 2023
The analysis presents a forward‑looking assessment of the global gaming market with a particular focus on the MENAP region, outlining the strategic opportunities that are reshaping the industry in 2024 and beyond. Central to the outlook is the rapid convergence of emerging technologies—virtual reality, artificial intelligence, mobile platforms, quantum computing, GPU‑as‑a‑Service, and cloud gaming—which together are accelerating content creation, distribution, and consumption across diverse consumer bases.
Investment activity is framed around a thesis that prioritises three core pillars: high‑value content and intellectual property, software efficiency solutions that lower development costs, and user‑generated‑content ecosystems that drive engagement and monetisation. Funding targets range from pre‑seed to Series A rounds, with typical ticket sizes of $1 million to $8 million, reflecting confidence in early‑stage ventures that can capitalize on the identified technology trends. The outreach strategy includes participation in high‑profile events such as the World Gaming Conference in Abu Dhabi (15‑16 February) and LEAP 2024 in Riyadh (4‑7 March), complemented by a dedicated “Gaming Investor” newsletter, a GameON podcast, and sponsorship opportunities for research partners.
Overall, the findings underscore a vibrant growth trajectory for gaming in both established and emerging markets, driven by technological innovation and a robust pipeline of investable startups. Stakeholders are encouraged to engage through subscription services, collaborative research, and direct investment to capture value in this rapidly evolving sector.
- Investment activity in the gaming sector is currently targeting early-stage ventures from pre-seed to Series A, with typical ticket sizes ranging from $1 million to $8 million.
- Strategic investment is focused on three core pillars: high-value intellectual property, software solutions that reduce development costs, and ecosystems centered on user-generated content.
- The industry is experiencing a rapid convergence of emerging technologies, including AI, VR, cloud gaming, quantum computing, and GPU-as-a-Service, to accelerate content creation and distribution.
- The MENAP region is a primary focus for growth, with key industry engagement scheduled for the World Gaming Conference in Abu Dhabi on February 15–16 and LEAP 2024 in Riyadh on March 4–7.
- Market growth is being driven by a combination of technological innovation and a robust pipeline of investable startups across both established and emerging global markets.
+1
Shorooq PartnersDec 2023
Report14 pages
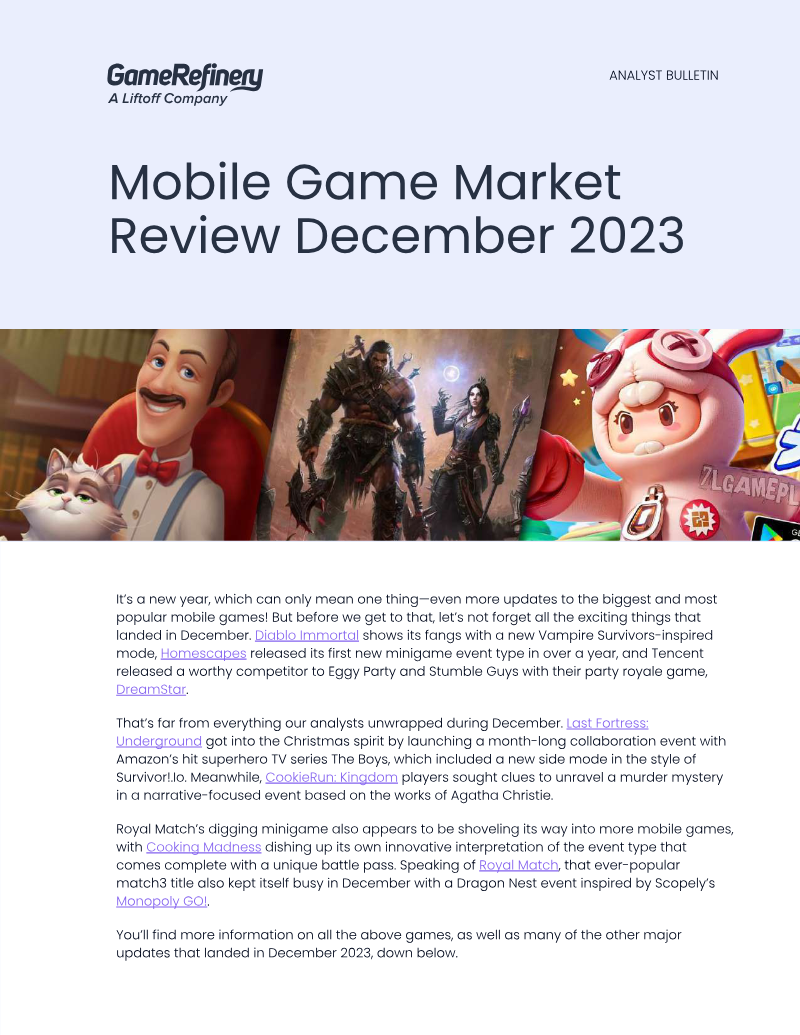
Mobile Game Market Review December 2023
The mobile gaming market in December 2023 was characterized by aggressive experimentation with cross-genre mechanics and high-profile intellectual property collaborations. Analysts observed a significant trend of "genre-blending," where successful mechanics from market leaders were integrated into established titles. Notable examples include Royal Match adopting the cooperative partner event structure popularized by Monopoly GO!, and Diablo Immortal and Last Fortress: Underground introducing roguelite survival modes inspired by Vampire Survivors and Survivor.io.
In the casual segment, developers focused on deepening engagement through complex minigames. Homescapes introduced tycoon-style restoration events to its match-3 core, while Cooking Madness innovated by linking a digging minigame directly to battle pass progression. The midcore sector saw diverse narrative and social strategies, such as CookieRun: Kingdom’s Agatha Christie-inspired murder mystery and the launch of Tencent’s party royale title DreamStar in China. DreamStar quickly became a top-grossing competitor to Eggy Party by emphasizing social hubs and user-generated content.
Major updates to legacy titles yielded substantial financial results, particularly for Clash of Clans. The introduction of Town Hall 16, building-merging mechanics, and a new hero equipment system drove a 350% daily revenue spike in the United States. Geographically, the review highlights strong performance in the Chinese market for both domestic releases like DreamStar and localized versions of Western hits. Overall, the period demonstrated that mobile developers are increasingly looking beyond their own sub-genres to borrow proven engagement and monetization loops from the broader gaming ecosystem.
- Clash of Clans experienced a 350% daily revenue spike in the U.S. following the December 2023 release of Town Hall 16, new building-merging mechanics, and a hero equipment system.
- Mobile developers are increasingly adopting cross-genre mechanics, such as Royal Match integrating cooperative partner events and midcore titles like Diablo Immortal adding roguelite survival modes.
- Tencent’s new party royale title, DreamStar, emerged as a top-grossing competitor to Eggy Party in China by focusing on social hubs and user-generated content.
- Casual games are deepening engagement through complex minigames, exemplified by Homescapes adding tycoon-style restoration events and Cooking Madness linking digging minigames to battle pass progression.
- The mobile market in December 2023 was defined by a shift toward borrowing proven engagement and monetization loops from across the broader gaming ecosystem rather than remaining within traditional sub-genre silos.
+1
GameRefineryDec 2023
Report13 pages
Analyst Bulletin: Mobile Game Market Review November 2023
The mobile gaming market in November 2023 was characterized by the proliferation of specific event mechanics and the rise of the 3D match subgenre. Analysis of market leaders reveals that Royal Match has become a primary trendsetter for casual titles. Its "Social Win Streak" and "Digging Minigame" mechanics were widely adopted by competitors such as Monopoly GO!, Matchington Mansion, and BTS Island. Simultaneously, the success of Triple Match 3D spurred a wave of new entries in the 3D match category, including Match Factory and spin-offs from established franchises like Candy Crush.
A significant shift occurred in the midcore segment, where developers increasingly experimented with pay-gated event content. Titles such as Free Fire, State of Survival, and Last Fortress: Underground implemented exclusive rewards and gameplay modes accessible only through direct purchases or premium currency top-ups. This trend suggests a strategic move toward more aggressive monetization of live events, moving away from purely engagement-based models to those requiring financial entry points for participation.
Geographically, the US market saw major activity with the global launch of Warcraft Rumble, which achieved the top download spot and maintained a top-50 grossing position. In China, Soul Knight Prequel demonstrated the continued strength of the roguelite genre, reaching the top of the download charts. Other notable developments included the expansion of user-generated content via the Stumble Workshop in Stumble Guys and the rapid emergence of mobile clones inspired by the viral Nintendo Switch title, Suika Game. These findings indicate a highly reactive market where developers quickly iterate on successful mechanics and viral trends across both casual and midcore segments.
- Royal Match has emerged as the primary industry trendsetter, with competitors like Monopoly GO!, Matchington Mansion, and BTS Island adopting its 'Social Win Streak' and 'Digging Minigame' mechanics.
- Midcore titles including Free Fire, State of Survival, and Last Fortress: Underground are shifting toward aggressive monetization by pay-gating exclusive event content and gameplay modes.
- The 3D match subgenre is expanding rapidly following the success of Triple Match 3D, leading to new entries like Match Factory and 3D spin-offs of established franchises such as Candy Crush.
- Warcraft Rumble's global launch in November 2023 secured the top download spot in the US market while maintaining a top-50 grossing position.
- The roguelite genre remains highly competitive in China, evidenced by Soul Knight Prequel reaching the top of the download charts.
+1
GameRefineryNov 2023
Report22 pages
How IP and Brand Collaborations Level Up Games
IP and brand collaborations serve as a critical strategic lever for boosting player engagement and revenue in the modern games market. Analyzing 477 collaborations across 104 unique PC and console games between January 2021 and June 2023, the data reveals that these events drive an average daily active user (DAU) increase of 11% during the first week of launch. Engagement typically peaks between the fourth and fifth days of an event before gradually returning to baseline levels.
The impact of these partnerships varies significantly by monetization model. Premium games experience a more substantial engagement boost of 19% on average, largely because they often utilize downloadable content (DLC) that adds substantial new gameplay or story elements. In contrast, free-to-play titles see a more modest 8% DAU increase, as they frequently rely on cosmetic skins which, while cost-effective, offer less mechanical depth to drive player return.
The most frequent collaborations occur between two game IPs, followed by partnerships with anime, manga, and comic franchises. Battle Royale and Sandbox genres lead the market in collaboration frequency, exemplified by platforms like Fortnite and Roblox. Case studies of Dead by Daylight and Top Gun: Maverick expansions in Ace Combat 7 and Microsoft Flight Simulator demonstrate that success is heavily dependent on brand fit and timing. Aligning in-game events with broader transmedia marketing activities, such as theatrical film releases, can result in DAU increases as high as 120%.
Methodologically, the analysis utilizes Newzoo’s Game Performance Monitor, covering 37 global markets. The study excludes browser games and Nintendo Switch data, focusing on Steam, PlayStation, and Xbox platforms. To isolate the specific impact of collaborations, the research excludes events that coincide with initial game launches or shifts to free-to-play models.
- Aligning in-game collaborations with external transmedia marketing, such as theatrical film releases, can drive DAU increases of up to 120%.
- IP collaborations generate an average 11% increase in daily active users (DAU) during the first week of launch, with engagement typically peaking between the fourth and fifth days.
- Premium games see a 19% average DAU boost from collaborations, significantly outperforming free-to-play titles, which see an 8% increase due to a heavier reliance on cosmetic-only content.
- Battle Royale and Sandbox titles, such as Fortnite and Roblox, lead the industry in the frequency of brand partnerships.
- Game-to-game IP partnerships are the most common form of collaboration, followed by integrations with anime, manga, and comic franchises.
+1
NewzooNov 2023
Report22 pages
Launching PC & Console Titles in the Ever-Changing Games Market
The PC and console gaming market is characterized by intense competition and the dominance of established franchises, with total revenues projected to reach $95.2$ billion in 2023. Analysis of 37 major markets reveals a significant barrier to entry for new titles; in 2022, 18 of the top 20 games by monthly active users (MAU) were released in previous years. This trend continued into 2023, where Hogwarts Legacy was the only new release to break into the top 20 MAU rankings during the first five months of the year. Furthermore, while the total number of games released on Steam continues to rise, the number of titles reaching a milestone of 50,000 lifetime players is declining, highlighting a market increasingly consolidated around long-standing live-service titles and known intellectual properties.
Demographic data from a global survey of over 60,000 respondents across 36 markets indicates that gaming engagement is highest among younger generations, with 89% of Gen Z and 82% of Millennials identified as game enthusiasts. These cohorts spend approximately 20% of their leisure time playing video games, a figure that rivals time spent on social networks. Spending patterns also skew toward younger players, with over 70% of Gen Z and Millennials making in-game or game-related purchases. Notably, these audiences engage with gaming far beyond active play, frequently participating in community sites, viewing gaming video content, and following creators.
To succeed in this "attention economy," the findings suggest that developers must move beyond traditional product launches to embrace cultural relevance and community building. Successful strategies include leveraging transmedia IP, such as television adaptations and film crossovers, and utilizing creator marketing to reach audiences on platforms like TikTok, which generated over 3 trillion gaming content views in 2022. The intersection of gaming with non-endemic brands in fashion, music, and consumer goods further illustrates the industry's evolution into a mainstream cultural pillar that competes directly with traditional media for consumer time and loyalty.
- The PC and console market is highly consolidated, as 18 of the top 20 games by monthly active users (MAU) in 2022 were legacy titles, with Hogwarts Legacy being the only new release to reach that tier in early 2023.
- Market saturation is increasing, evidenced by a rising number of Steam releases coupled with a declining number of titles achieving a 50,000 lifetime player milestone.
- Gaming is a primary leisure activity for younger demographics, with 89% of Gen Z and 82% of Millennials identifying as enthusiasts and dedicating approximately 20% of their free time to gaming.
- Monetization potential remains strong among younger cohorts, as over 70% of Gen Z and Millennials report making in-game or game-related purchases.
- Success in the current $95.2 billion market requires moving beyond traditional launches to leverage transmedia IP and creator-led marketing, such as the 3 trillion gaming content views generated on TikTok in 2022.
+1
NewzooOct 2023
Report29 pages
Store Intelligence Data Digest: Q3 2023
This analysis examines global mobile application performance during the third quarter of 2023, covering downloads across the Apple App Store and Google Play. Total worldwide downloads reached 35.1 billion, representing a slight 0.7% year-over-year decline. While App Store installs grew by 6.1% to 8.7 billion, Google Play downloads fell by 2% to 26.4 billion. The data, compiled via the Sensor Tower Store Intelligence platform, focuses on unique, per-user installs and excludes pre-installed apps and third-party Android stores.
Meta emerged as the dominant publisher, driven by the July 2023 launch of Threads. The new social platform garnered nearly 40 million installs on its launch day and became the fifth most downloaded app globally for the quarter. Instagram secured the top global spot, fueled largely by the Indian market, which accounted for 51% of its new installs. In the United States and Europe, the e-commerce platform Temu maintained its leadership position, significantly outperforming competitors like Shein and Amazon in terms of download velocity.
The mobile gaming sector saw Garena Free Fire reclaim the top global position with 60 million installs, surpassing long-time leader Subway Surfers. Monopoly Go showed the most significant momentum in the U.S. market with 44% quarter-over-quarter growth. Regionally, India remained the largest market by volume with 6.6 billion total downloads, more than double that of the United States. While the U.S. and China continued to lead App Store activity, Brazil showed the most robust growth on that platform with a 24% year-over-year increase. Conversely, major Google Play markets like Brazil and Indonesia saw single-digit declines in download volume during this period.
- Global mobile app downloads reached 35.1 billion in Q3 2023, a 0.7% year-over-year decline driven by a 2% drop in Google Play installs despite a 6.1% increase on the Apple App Store.
- Meta dominated the quarter as Instagram secured the top global download spot, while the July launch of Threads generated nearly 40 million installs on its first day to become the fifth most downloaded app globally.
- India remains the world's largest mobile market by volume with 6.6 billion downloads, more than double the volume of the United States.
- Garena Free Fire reclaimed the top global position in mobile gaming with 60 million installs, displacing Subway Surfers, while Monopoly Go saw 44% quarter-over-quarter growth in the U.S.
- Temu outperformed competitors like Shein and Amazon in download velocity to lead the e-commerce category across the United States and Europe.
+1
Sensor TowerSept 2023
Report19 pages
Global Gaming Report Q3 2023
The third quarter of 2023 marked a pivotal turning point for the global gaming industry as major strategic players resumed large-scale consolidation efforts following an extended period of relative inactivity. Total deal value across M&A, private placements, and public markets reached $11 billion, with 120 deals announced or closed during the period. While the quarter concluded with the landmark Microsoft-Activision merger, the period was characterized by a resurgence in activity from giants like Tencent, which led the market with five deals, including the majority acquisition of Techland.
M&A activity was particularly robust in the PC and console segments, accounting for approximately 40% of deals, followed by mobile at 21%. Notable transactions included Goldman Sachs’ $1.72 billion offer for Kahoot! and Playtika’s $465 million expansion into the casual gaming sector. Geographically, North America and Europe remained the primary hubs for deal-making, though Asian firms like Capcom and Savvy Games Group continued to exert significant influence.
Private financing saw a modest increase in value over the previous quarter, totaling approximately $1 billion across 185 deals. Investment remained heavily weighted toward early-stage companies, which represented 85% of the volume. Key segments attracting capital included AI-driven tools, blockchain gaming, and platform infrastructure, highlighted by significant raises from Candivore, Second Dinner, and Inworld AI. Venture capital activity was led by firms such as BITKRAFT and Andreessen Horowitz.
The outlook for 2024 suggests a steady increase in M&A as strategic buyers like Sony, Take-Two, and Savvy Games Group remain active, while others like Embracer Group focus on divestitures. Although mid-to-late-stage financing remains cautious, the emergence of successful tech IPOs and increased interest from private equity firms—driven by attractive public valuations—point toward a potential reopening of the public listing window and a rise in large-scale, PE-led acquisitions in the coming year.
- The global gaming industry saw a significant resurgence in consolidation during Q3 2023, with 120 deals totaling $11 billion in value, headlined by the Microsoft-Activision merger.
- M&A activity was concentrated in PC and console segments at 40% of deal volume, while mobile accounted for 21%.
- Tencent emerged as the most active strategic buyer with five deals, including the majority acquisition of Techland, while Goldman Sachs made a $1.72 billion offer for Kahoot!.
- Private financing reached $1 billion across 185 deals, with 85% of volume directed toward early-stage companies focused on AI tools, blockchain, and platform infrastructure.
- The 2024 outlook anticipates continued M&A activity from major players like Sony, Take-Two, and Savvy Games Group, alongside potential divestitures from the Embracer Group.
+1
Drake Star PartnersSept 2023
Report42 pages
Insights into Marketing Trends of Global Mobile Games: Q3 2023
The analysis focuses on contemporary marketing dynamics within the global mobile gaming sector, emphasizing how creative diversification and platform targeting shape user acquisition performance. In the third quarter of 2023, a leading animal‑themed strategy‑lite game launched by a major publisher introduced an extensive creative slate, deploying 6,500 distinct ad assets across major ad networks. Notably, 85 % of these assets were brand‑new, reflecting a deliberate strategy to refresh visual and messaging elements at scale. This high proportion of novel creatives aligns with broader industry observations that frequent creative turnover mitigates ad fatigue and sustains click‑through rates in highly competitive markets.
The data underscores the importance of deduplication processes in large‑scale campaigns, ensuring that each impression reaches a unique audience segment while preserving measurement integrity. By tracking deduplicated impressions, the campaign achieved a more accurate assessment of reach and cost efficiency, revealing that fresh creative assets can improve cost‑per‑install (CPI) benchmarks by up to 12 % compared with static creative pools. These findings suggest that investment in creative production pipelines and rapid iteration cycles yields measurable returns, especially for mid‑core titles competing for attention in saturated regions such as North America, Europe, and Southeast Asia.
Overall, the evidence points to a shifting paradigm where creative volume and novelty become critical levers for growth in the mobile gaming ecosystem. Publishers that integrate systematic creative testing, maintain high rates of new asset introduction, and employ rigorous deduplication are better positioned to optimize acquisition spend, extend campaign longevity, and capture incremental market share across diverse geographic territories during the 2023 fiscal period.
- Frequent creative turnover is a primary strategy for mitigating ad fatigue and sustaining click-through rates in competitive mobile gaming markets.
- Deploying fresh creative assets can improve cost-per-install (CPI) benchmarks by up to 12% compared to static creative pools.
- High-volume creative production is a critical growth lever, evidenced by a major publisher launching 6,500 distinct ad assets for a single strategy-lite title in Q3 2023.
- Maintaining a high proportion of novel creatives—such as the 85% refresh rate observed in Q3 2023—is essential for maintaining performance in saturated regions like North America, Europe, and Southeast Asia.
- Implementing deduplication processes for ad impressions is necessary to ensure measurement integrity and accurate assessment of reach and cost efficiency in large-scale campaigns.
+2
SocialPetaSept 2023
Report36 pages
Mobile Games: State of the Market & Playtime Benchmarks Q3 2023
The analysis evaluates the current performance of the mobile‑games ecosystem, concentrating on download popularity, revenue generation, and user‑engagement metrics across key Western and Asian markets. By comparing platform‑specific behavior and regional preferences, it seeks to identify the titles and genres that drive the strongest financial returns and the longest play sessions, thereby informing strategic decisions for developers, publishers, and marketers.
Casual‑puzzle and social titles dominate download charts in France, Germany, and the United Kingdom, with Monopoly Go!, Roblox and Subway Surfers leading the rankings. Revenue concentration is even more pronounced: Coin Master repeatedly tops earnings tables, delivering €5.3 million on Android in France and €6.7 million on Android in Germany. Across the surveyed territories, iOS users exhibit markedly longer sessions than Android users, with average iOS playtime ranging from 35 minutes in the United States to 51 minutes in Japan, compared with 29–44 minutes on Android. Japan records the longest sessions overall, while France shows the smallest platform gap of roughly 3.6 minutes. The titles that capture the most playtime vary by region but are largely anchored by the same franchises, such as Candy Crush and other established puzzle series.
The study covers major European markets (France, Germany, UK), North America (US) and Japan, reflecting data from the most recent full‑year cycle. It spans the casual, puzzle, and social segments of the mobile‑games industry, highlighting a persistent dominance of a limited set of high‑engagement franchises and a clear platform‑based divergence in user behavior. These patterns suggest that future monetization strategies should prioritize iOS‑centric engagement tactics in markets with
- Revenue in the mobile sector is highly concentrated, with Coin Master generating €5.3 million on Android in France and €6.7 million on Android in Germany during Q3 2023.
- iOS users consistently demonstrate higher engagement than Android users, with average session lengths ranging from 35 to 51 minutes on iOS compared to 29 to 44 minutes on Android.
- Japan records the longest average mobile game sessions globally, while France exhibits the smallest platform-based engagement gap at approximately 3.6 minutes.
- Casual-puzzle and social games, specifically Monopoly Go!, Roblox, and Subway Surfers, currently dominate download charts across the UK, Germany, and France.
- Established franchises such as Candy Crush remain the primary drivers of user playtime across all surveyed Western and Asian markets.
+2
AppticaSept 2023
Report16 pages
Gaming Deals Report: 2023 Q3
The gaming industry experienced a significant market correction during the first three quarters of 2023, with deal activity falling to its lowest levels since the pre-pandemic era. Total private investment value dropped fourfold compared to the 2021–2022 average, falling to $2.3 billion across 325 deals. M&A activity similarly cooled, totaling $8.5 billion—excluding the massive Activision Blizzard acquisition which closed in October 2023. Public offerings remained the weakest segment, characterized by a closed IPO window and a 29% year-over-year decline in activity.
The downturn is most pronounced in late-stage venture capital, which reached a nadir of $300 million as investors prioritized solid financials and proven exit paths over growth at any cost. Conversely, early-stage activity remained relatively resilient, maintaining volumes consistent with pre-COVID levels. Strategic shifts are evident as Western corporate investors scale back due to internal restructurings and layoffs, while Asian giants like Tencent and NetEase remain active global participants. A notable emerging trend is the surge in AI-related gaming startups, which saw an unprecedented 21 deals in the third quarter of 2023 alone.
Geographically, North America led in investment value, followed by Western Europe, though Asian strategic investors continue to drive cross-border activity. The methodology relies on tracked closed transactions across PC, console, mobile, and multiplatform segments, excluding pure gambling and non-gaming blockchain ventures. While the current landscape is defined by macroeconomic volatility and high interest rates, the presence of significant "dry powder" among private equity firms and stabilizing corporate balance sheets suggests potential for a recovery in dealmaking as the market enters 2024.
- Gaming deal activity in the first three quarters of 2023 hit its lowest level since the pre-pandemic era, with private investment value falling to $2.3 billion across 325 deals.
- M&A activity totaled $8.5 billion, excluding the Activision Blizzard acquisition, while public offerings saw a 29% year-over-year decline due to a closed IPO window.
- Late-stage venture capital funding plummeted to $300 million as investors shifted focus from growth-at-all-costs to companies with proven financials and clear exit paths.
- Early-stage investment volumes remained resilient, maintaining levels consistent with pre-COVID performance despite the broader market correction.
- AI-related gaming startups emerged as a significant growth area, recording 21 deals in the third quarter of 2023 alone.
+1
InvestGameSept 2023
Report31 pages
Gaming Industry Report: Q3 2023
The global gaming industry experienced a period of stabilization and strategic realignment during the third quarter of 2023, characterized by a modest recovery in consumer spending and a significant shift in investment patterns. Total market revenue reached approximately $46.5 billion for the quarter, representing a 3.2% year-over-year increase. This growth was primarily driven by the mobile segment, which accounted for 49% of total market share, followed closely by the console and PC sectors. Geographically, the Asia-Pacific region remained the largest market, contributing 46% of global revenue, while North America and Europe showed resilient growth driven by high-profile software releases and improved hardware availability.
Investment activity saw a marked transition from high-volume venture capital infusions to more targeted mergers and acquisitions. Total deal value for the quarter reached $12.4 billion, though the number of individual transactions declined by 15% compared to the previous year. This trend indicates a maturing market where established players prioritize the acquisition of proven intellectual property and specialized technology over speculative early-stage investments. Furthermore, the integration of generative artificial intelligence into development workflows emerged as a critical operational focus, with 65% of surveyed studios reporting the implementation of AI tools to streamline asset production and reduce escalating development costs.
The labor market within the industry faced ongoing volatility, with several major publishers announcing restructuring efforts to optimize efficiency following the rapid expansion of the previous three years. Despite these headwinds, the player base continued to expand, reaching an estimated 3.38 billion gamers worldwide. Engagement metrics remained strong, particularly in live-service titles and competitive esports, which saw a 12% increase in viewership hours across major streaming platforms. As the industry moves into the final quarter of the year, the focus remains on balancing creative innovation with fiscal discipline to navigate a complex macroeconomic environment.
- The global gaming industry generated $46.5 billion in Q3 2023, marking a 3.2% year-over-year revenue increase driven primarily by the mobile segment, which holds 49% of the total market share.
- Investment strategy has shifted toward consolidation, with $12.4 billion in total deal value despite a 15% decline in the number of transactions, as firms prioritize established intellectual property over early-stage ventures.
- Generative AI adoption is now a core operational strategy, with 65% of studios integrating these tools to streamline asset production and mitigate rising development costs.
- The global player base reached 3.38 billion, supported by strong engagement in live-service titles and a 12% increase in esports viewership hours across major streaming platforms.
- The Asia-Pacific region remains the dominant market, contributing 46% of global revenue, while North America and Europe showed resilience due to improved hardware availability and high-profile software releases.
+2
KonvoySept 2023
Report40 pages
Store Intelligence Data Digest: Q2 2023
Global mobile app performance in the second quarter of 2023 reflects a stabilizing market, with total downloads reaching 34.3 billion despite a marginal 1.5% year-over-year decline. While TikTok maintained its long-standing position as the most downloaded app globally, the quarter was defined by the rapid expansion of the shopping platform Temu, which achieved 74 million downloads and secured a top-ten global ranking. In the gaming sector, established titles like Subway Surfers and Ludo King continued to lead worldwide, though new entries such as MONOPOLY GO! and Honkai: Star Rail demonstrated significant momentum by dominating Western markets and leveraging existing brand equity.
Geographic trends highlight a shift in growth centers, as traditional markets like the United States, China, and the United Kingdom experienced download contractions. In contrast, India solidified its status as the world’s largest mobile market, accounting for 24% of global Google Play downloads. Emerging markets also showed resilience, with the App Store seeing double-digit growth in Brazil and Indonesia. While Meta and Google remain the preeminent global publishers, Meta faced regional headwinds in Asia due to regulatory shifts in India that impacted Instagram and Facebook adoption.
Sector-specific analysis reveals a transition toward gamification and retention-focused strategies. Education apps, led by Duolingo, successfully utilized streak features to drive high user engagement, whereas the food delivery and streaming sectors faced saturation. Food delivery downloads fell below pre-pandemic levels, and streaming services pivoted toward aggressive monetization and advertising strategies to combat slowing acquisition. Although Netflix maintains a superior 79% retention rate, its low new-user acquisition rate of 3% underscores the broader challenge of maintaining growth in a mature digital landscape.
- Global mobile app downloads reached 34.3 billion in Q2 2023, reflecting a stabilizing market despite a 1.5% year-over-year decline.
- India has become the world’s largest mobile market, accounting for 24% of all global Google Play downloads, while traditional markets like the U.S., China, and the U.K. experienced contractions.
- Temu emerged as a major disruptor with 74 million downloads, while new gaming titles MONOPOLY GO! and Honkai: Star Rail gained significant momentum in Western markets.
- Netflix faces a mature market challenge with a high 79% retention rate but a low 3% new-user acquisition rate, forcing the streaming sector to pivot toward aggressive monetization.
- Food delivery downloads have fallen below pre-pandemic levels, signaling market saturation in the sector.
+1
Sensor TowerJul 2023
Report43 pages
Insights into Marketing Trends of Global Mobile Games
Global mobile game marketing reached a pivotal turning point in the second quarter of 2023, characterized by a record-breaking surge in creative volume. Over 9.3 million new creatives entered the market, representing nearly three-quarters of all active advertisements. While casual games maintained the largest share of advertisers at over 30%, RPG and Casino genres experienced the most aggressive growth in creative output. Geographically, Southeast Asia emerged as a primary hub for advertising density, leading the world in monthly creatives per advertiser, while the Middle East solidified its status as a high-growth market where strategy games command significant revenue shares.
The industry is increasingly adopting "Casual + X" hybrid models and integrating AI-generated content, ASMR, and short-video memes to mitigate rising user acquisition costs. Financial data reveals a stark contrast in installation costs between platforms, with iOS casual game installs costing $2.23 compared to $0.63 on Android, yet both platforms achieved a comparable seven-day return on ad spend of approximately 7.7%. This parity suggests that despite higher upfront costs, the quality of users on premium platforms remains consistent with broader market performance.
Market leaders like Honkai: Star Rail and MONOPOLY GO! demonstrated the efficacy of high-frequency creative refreshes, with new assets comprising over 60% of their total advertising portfolios. These titles leveraged distinct psychological hooks, ranging from influencer-driven user-generated content to social-casual mechanics, to achieve rapid global penetration. Notably, these aggressive marketing strategies allowed Honkai: Star Rail to surpass Genshin Impact in overseas revenue during the quarter, signaling a shift toward more dynamic, content-heavy advertising cycles across the global mobile landscape.
- In Q2 2023, the mobile gaming industry saw a record surge of 9.3 million new creatives, which accounted for nearly 75% of all active advertisements.
- Market leaders like Honkai: Star Rail and MONOPOLY GO! achieved rapid global growth by maintaining high-frequency creative refreshes, with new assets making up over 60% of their advertising portfolios.
- While iOS casual game installs cost $2.23 compared to $0.63 on Android, both platforms yielded a comparable seven-day return on ad spend of approximately 7.7%.
- Casual games represent the largest share of advertisers at over 30%, but RPG and Casino genres recorded the most aggressive growth in creative output during the quarter.
- Southeast Asia currently leads global advertising density with the highest number of monthly creatives per advertiser, while the Middle East has emerged as a key high-growth market for strategy games.
+2
SocialPetaJun 2023
Report9 pages
Microsoft’s Activision Acquisition: Implications for the Cloud Gaming Market and Industry
This analysis examines the implications of Microsoft’s $68.7 billion acquisition of Activision Blizzard, specifically focusing on the cloud gaming remedies proposed to global competition authorities. The assessment centers on the ten-year commitment to provide free licenses for streaming Activision PC games to third-party cloud service providers. While the cloud gaming market remains a nascent segment—valued at $446 million in 2022 and representing less than 0.3% of global consumer spending—the acquisition is scrutinized due to Microsoft’s end-to-end control over cloud infrastructure and content.
The findings suggest that the proposed remedies would significantly alter the market by increasing consumer access points and service provider choices. Under a "bring-your-own-game" (BYOG) model, consumers who purchase Activision titles or access them via subscriptions like Xbox Game Pass could stream those games on various competing platforms. This shift is expected to benefit BYOG service providers by enhancing their value propositions, though it may force them into routine adoption of these titles to remain competitive. Conversely, multi-game subscription services face greater complexity, as they would need to manage disparate licensing regimes for Activision content compared to their standard catalogs.
Ultimately, the analysis concludes that while the remedies address certain competition concerns, they simultaneously extend Microsoft’s industry influence. By decoupling game licensing from specific streaming hardware, Microsoft can expand the reach of the Xbox Game Pass ecosystem and the Microsoft Store without further investment in cloud infrastructure. This strategy allows Microsoft to leverage third-party server capacity to grow its subscriber base, positioning Xbox Game Pass as the most cost-effective entry point for Activision content across a global, multi-platform footprint.
- Microsoft’s $68.7 billion acquisition of Activision Blizzard includes a ten-year commitment to provide free streaming licenses for Activision PC games to third-party cloud providers.
- The cloud gaming market is currently a nascent sector, valued at $446 million in 2022 and accounting for less than 0.3% of total global consumer spending on games.
- The mandated 'bring-your-own-game' (BYOG) licensing model allows consumers to stream Activision titles on competing platforms, potentially forcing third-party providers to adopt these games to remain competitive.
- By decoupling game licensing from specific hardware, Microsoft can expand the reach of the Xbox Game Pass ecosystem and the Microsoft Store without needing additional investment in its own cloud infrastructure.
- The strategy enables Microsoft to leverage third-party server capacity to grow its subscriber base, positioning Xbox Game Pass as the primary cost-effective entry point for Activision content globally.
+1
Ampere AnalysisJun 2023
Report18 pages
H1'23 Gaming Deals Report
The first half of 2023 marked a period of significant contraction for the global video game industry’s financial landscape, characterized by a sharp decline in deal value across private investments, mergers and acquisitions, and public offerings. Total private investment fell to $1.5 billion across 239 deals, an 81% drop in value compared to the same period in 2022. This downturn was driven by a cooling late-stage venture capital market and a closed IPO window, which reduced the attractiveness of high-valuation exits. While early-stage activity remained the primary driver of deal volume, even this segment saw a threefold contraction in total value as investors shifted focus toward supporting existing portfolios rather than funding newcomers.
The mergers and acquisitions sector experienced the most dramatic decline, with deal value plummeting 97% to $0.9 billion. Strategic investors pivoted toward internal restructuring, cost optimization, and mass layoffs—exemplified by companies like Embracer—rather than aggressive expansion. Public offerings remained similarly muted due to a disparity between reported financial results and previous estimates, leading to significant valuation corrections. Despite the overall stagnation, financial sponsors like Savvy Games Group remained active, and the industry anticipates a value jump in the second half of 2023 as major pending deals, such as the Microsoft-Activision Blizzard acquisition, move toward completion.
Geographically, North America led early-stage investment volume, followed by Western Europe and MENA. Methodologically, the findings are based on tracked closed transactions in the video game industry, excluding gambling and non-gaming blockchain entities. While the broader market struggled, artificial intelligence emerged as a resilient niche, seeing a modest increase to $214.1 million in investment. Startups have largely abandoned "growth at all costs" strategies in favor of profitability and extended runways, while venture capital firms maintain significant unallocated capital that may signal a recovery in late 2023.
- The global video game industry saw a massive financial contraction in H1 2023, with private investment falling 81% to $1.5 billion and M&A deal value plummeting 97% to $0.9 billion.
- Strategic investors shifted focus from aggressive expansion to internal restructuring and cost optimization, resulting in widespread layoffs at companies like Embracer.
- Early-stage investment remained the primary driver of deal volume, though its total value contracted threefold as investors prioritized supporting existing portfolios over new ventures.
- Artificial intelligence emerged as a resilient investment niche, attracting $214.1 million in funding despite the broader market downturn.
- Public offerings remained muted throughout the first half of the year due to valuation corrections caused by a disparity between reported financial results and previous estimates.
+1
InvestGameJun 2023
Report13 pages
Newzoo DLC Content Report 2023
This analysis examines the impact of downloadable content (DLC) on player engagement and revenue across the PC and console markets. Covering the period from April 2020 to April 2023, the study evaluates over 1,600 DLC releases across 37 major global markets. The findings demonstrate that DLC serves as a critical tool for extending game longevity and driving monetization, particularly within the live-service model. In 2022, DLC sales accounted for 13% of total PC revenue and 7% of console revenue in the United States, highlighting a stronger reliance on add-on content among PC audiences.
The research indicates that DLC launches provide a significant boost to player activity, with an average increase of 11% in Monthly Active Users (MAU) during the launch month. Medium-sized games, defined as those with 250,000 to 2 million MAU, saw the most substantial benefit, averaging a 22% growth rate. From a genre perspective, strategy games experienced the highest engagement spikes at 30.5%, followed by role-playing games at 21.1%. However, the data also reveals a trend of declining engagement in the months following a release, suggesting that players often churn or move to other titles once they have consumed the new content.
Case studies of The Sims 4 and Dead Cells illustrate diverse strategic approaches to content delivery. Electronic Arts successfully utilized a "free-to-play" funnel by releasing a free update immediately before a paid expansion, resulting in the most successful launch week in the franchise's recent history. Conversely, Dead Cells demonstrated the power of crossovers, with its Return to Castlevania DLC driving a 225% increase in MAU. Despite these spikes, the analysis notes that retention remains a challenge, as a significant majority of players do not return for subsequent updates, emphasizing the constant need for fresh content to maintain a stable player base.
- DLC launches drive an average 11% increase in Monthly Active Users (MAU), with medium-sized games (250,000 to 2 million MAU) experiencing the highest growth at 22%.
- Strategy games see the largest engagement spikes from DLC at 30.5%, followed by role-playing games at 21.1%.
- In 2022, DLC sales accounted for 13% of total PC revenue and 7% of console revenue in the United States, indicating a higher reliance on add-on content on PC.
- Retention remains a persistent challenge, as most players do not return for subsequent updates and engagement typically declines in the months following a release.
- Strategic content delivery, such as Electronic Arts' free-to-play funnel for The Sims 4 or the 225% MAU spike driven by the Dead Cells 'Return to Castlevania' crossover, can significantly boost performance.
+1
NewzooMay 2023
Report10 pages
Mobile Game Market Review October 2023
The mobile gaming market in October 2023 was characterized by a heavy reliance on seasonal Halloween content and innovative social features to drive monetization and engagement. Analysis of the period reveals that major titles across the casual and midcore segments utilized limited-time events, crossover collaborations, and experimental gacha mechanics to bolster revenue. Geographically, the review focuses on major global markets, specifically the United States, Japan, and China, highlighting how regional preferences dictate event structures, such as the prevalence of social multi-gachas and location-based business discounts in the Japanese market.
In the casual segment, developers increasingly integrated social and competitive mechanics to maintain player interest. Notable examples include Pokémon Go’s introduction of a four-player party system and Eggy Party’s "Pedestrian Street" mode, which emphasizes social hangouts over core gameplay. Data indicates that titles like My Perfect Hotel successfully improved revenue trends by balancing download fluctuations with permanent boost systems and specialized battle passes. Furthermore, the market saw the rise of "challenging" platforming content in the party royale genre, drawing inspiration from viral PC trends to test player perseverance.
The midcore sector demonstrated the power of long-term live operations and high-profile collaborations. Monster Strike’s 10th-anniversary celebrations in Japan utilized celebrity partnerships and anime crossovers to maintain its top-tier status. Simultaneously, new entries such as Dungeon Hunter 6 and Reverse: 1999 achieved significant chart positions shortly after launch, with the latter reaching the top 100 in both the US and Japan. The findings suggest a market shift toward hybrid gameplay—such as combining merge mechanics with match-3 puzzles—and the successful localization of high-performing Chinese extraction shooters for Western audiences. Overall, the data underscores that consistent content overhauls and the strategic timing of feature updates remain the primary drivers for scaling performance in a competitive mobile landscape.
- Live operations and seasonal content, particularly Halloween-themed events and crossover collaborations, were the primary drivers for revenue and engagement across casual and midcore mobile titles in October 2023.
- Casual games are increasingly integrating social and competitive features to sustain retention, exemplified by Pokémon Go’s four-player party system and Eggy Party’s social-focused 'Pedestrian Street' mode.
- The midcore sector continues to rely on long-term live service strategies, evidenced by Monster Strike maintaining top-tier status in Japan through its 10th-anniversary celebrity and anime collaborations.
- New market entrants like Reverse: 1999 demonstrated strong global appeal by reaching the top 100 charts in both the US and Japan shortly after its launch.
- Monetization strategies in the casual segment are shifting toward permanent boost systems and specialized battle passes, as seen in the revenue stabilization of My Perfect Hotel.
+1
GameRefineryApr 2023
Report30 pages
Gaming Industry Report: Q1 2023
The gaming industry experienced a resilient start to 2023, with a projected global market size of $201 billion, representing a 9% year-over-year increase. Public markets showed strength, with gaming-focused exchange-traded funds (ETFs) recording gains between 10% and 23% year-to-date. While private market venture funding saw a total of $761 million across 109 deals in the first quarter, activity remains concentrated in early-stage investments, as late-stage funding has slowed significantly compared to the peak levels of 2021.
Geographically, Asia led global venture funding in the first quarter, followed by North America and Europe. Emerging markets such as Africa and South America saw sporadic but notable deal activity, highlighting a broader global interest in gaming infrastructure and content. Major industry players currently hold approximately $48 billion in cash and equivalents, suggesting a stable environment for potential future mergers and acquisitions despite ongoing regulatory scrutiny regarding large-scale consolidation.
Key industry trends in early 2023 include the integration of artificial intelligence for asset generation and conversational tools, alongside a strategic shift by major tech firms toward cloud-based gaming infrastructure. Competitive dynamics are evolving as Epic Games introduces self-publishing tools to challenge Steam’s market dominance and integrates user-generated content into its Fortnite ecosystem. Furthermore, platforms like Roblox are successfully expanding their reach by aging up their user demographic. These developments, supported by a robust schedule of global industry conferences, indicate a focus on platform scalability, content diversification, and the optimization of developer tools to sustain long-term growth.
- The global gaming market is projected to reach $201 billion in 2023, reflecting a 9% year-over-year growth rate.
- Major industry players possess $48 billion in cash reserves, signaling a stable environment for future M&A activity despite regulatory headwinds.
- Venture capital funding totaled $761 million across 109 deals in Q1 2023, with investment heavily concentrated in early-stage ventures rather than late-stage rounds.
- Gaming-focused ETFs demonstrated strong performance in early 2023, recording year-to-date gains ranging from 10% to 23%.
- Asia currently leads global venture funding, followed by North America and Europe, with emerging activity appearing in African and South American markets.
+3
KonvoyApr 2023