Key insights
7 slides
The rising bill
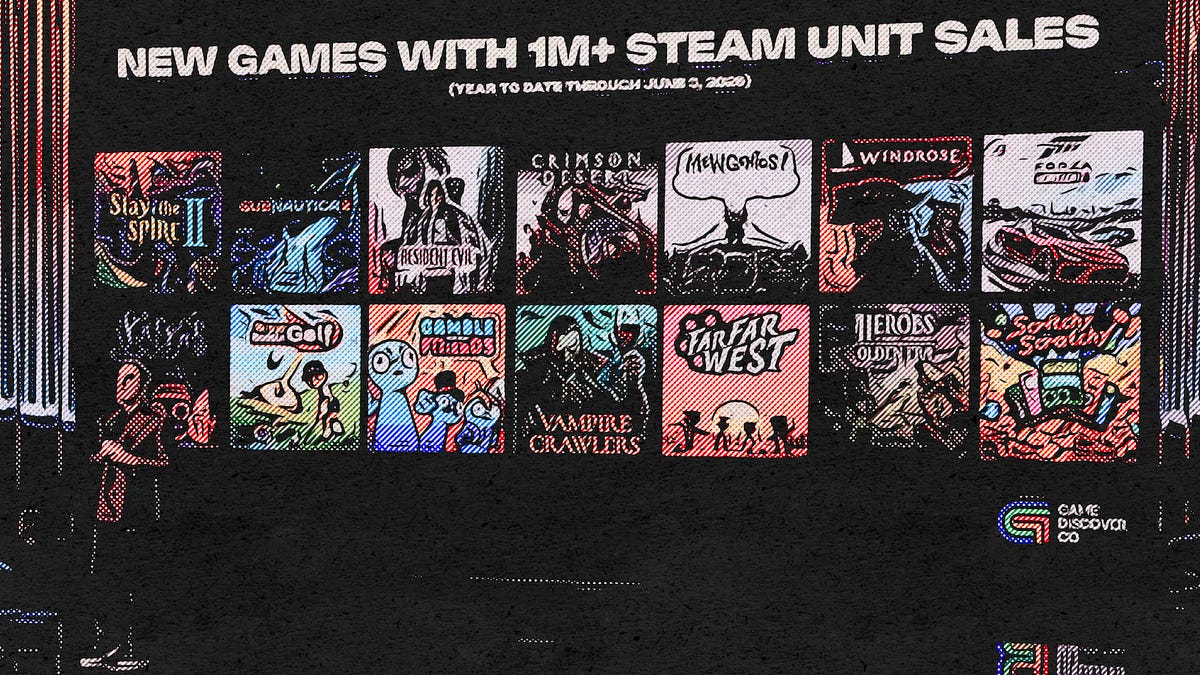
Steam revenue grew by $1.41 billion in the first half of 2026.
Back-catalog sales added $1.80 billion during the period. New release revenue shrank by $0.39 billion.
Key number
Existing titles generated 78% of Steam revenue in 2026.
The share of total Steam revenue from existing titles rose from 71% to 78% between 2025 and 2026. Revenue from new releases fell 14% to $2.40 billion.
What changed
Steam's top 10 titles fell from a 2023 peak of $4.3 billion.
The blockbuster tier's revenue declined for two consecutive years, dropping to $4.0 billion in 2025. The top 10's revenue share fell from a 2019 peak of 41% to 28% by 2025.
The mid-market rise
The mid-market segment quadrupled in revenue from 2019 to 2025.
Titles ranked 101 to 1,000 grew from $1.1 billion in 2019 to $4.5 billion in 2025.
The hidden cost
Spending on older games rose 26% while player counts fell 10%.
Analysis of a same-game panel of over 16,000 titles shows spending on pre-2024 catalog titles rose 26% in the first half of 2026. Average daily player counts for those same games fell 10%.
Like buying books you never read.
The risk
New releases face a structural disadvantage against a discounted library.
New game releases now compete against a massive, discounted library of established titles. This makes the traditional blockbuster-only strategy less effective as a hedge against risk.
The projection
Top 10 titles are projected to account for less than 25% of revenue.
Steam's top 10 titles are projected to account for less than 25% of total platform revenue by the end of 2027. This is down from 41% in 2019.
1 / 7
Ask AI about this report