indie
CompanyUnited States
Documents about indie
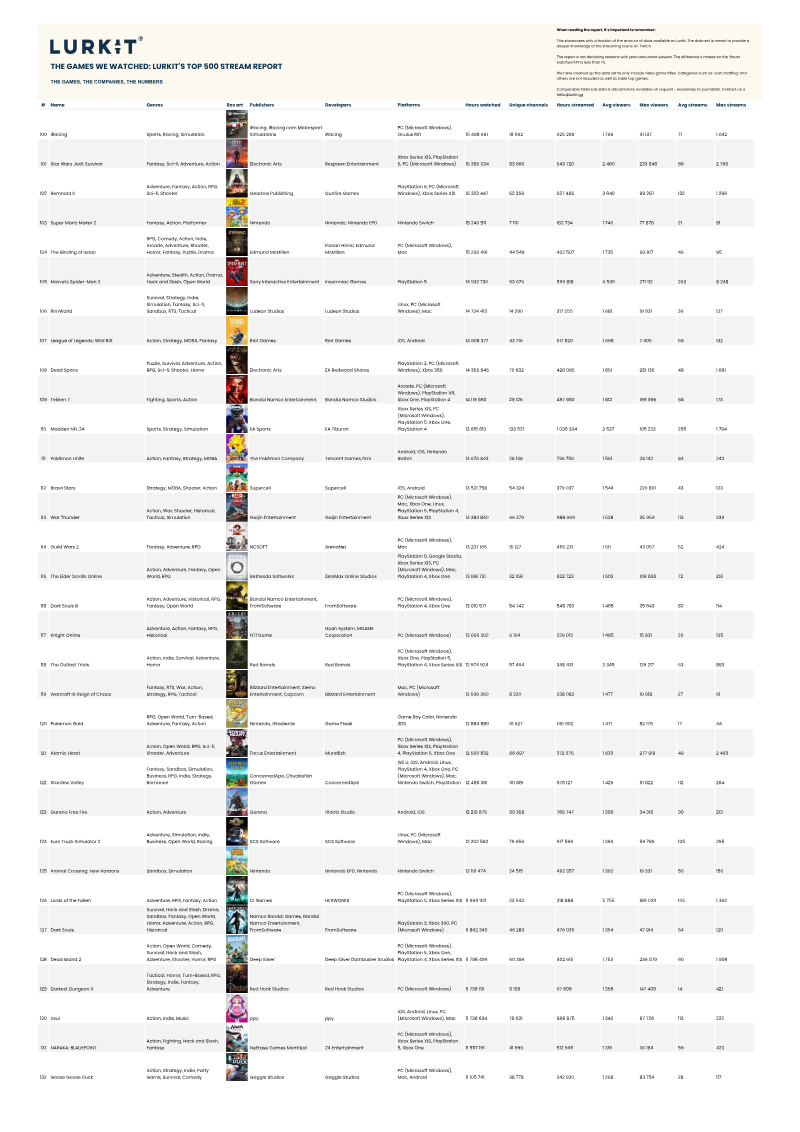
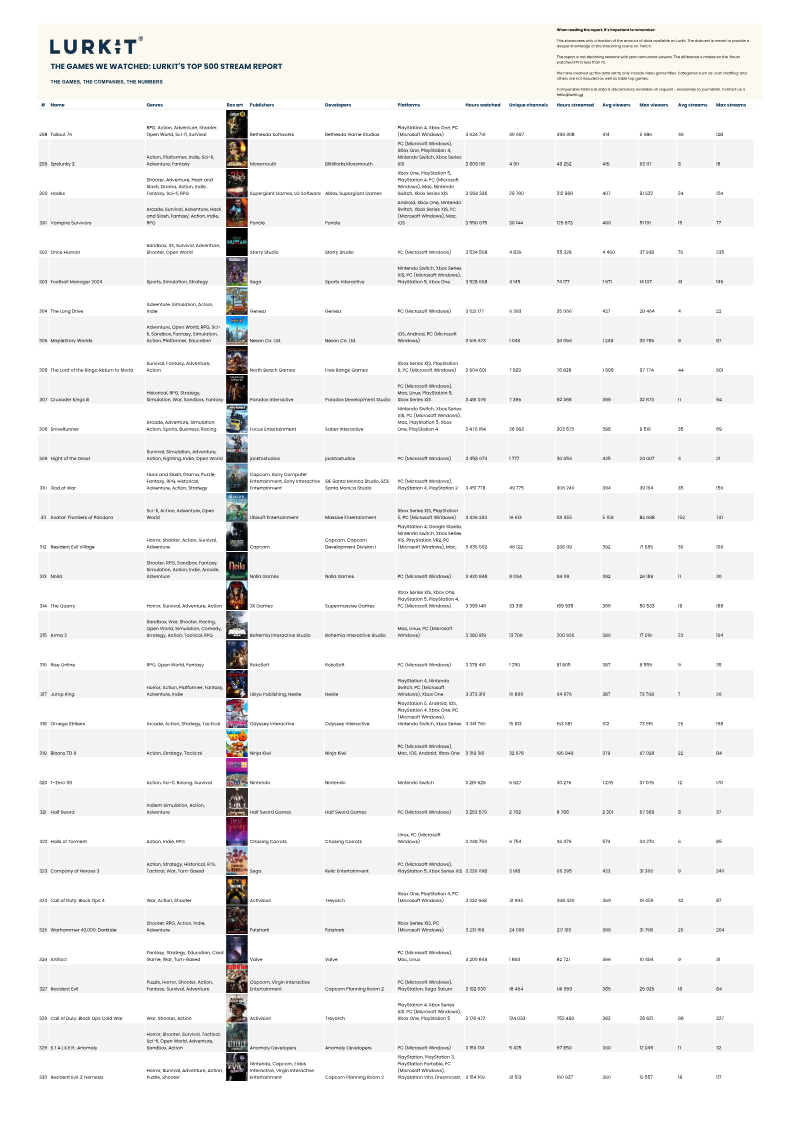
Top 500 Titles on Twitch 2023
The gaming industry experienced record-breaking engagement in 2023, with the top 500 titles on Twitch generating nearly 15 billion hours of watch time.
- The top 500 Twitch titles generated nearly 15 billion hours of watch time in 2023, with 50% of that total concentrated in just 11 games.
- Grand Theft Auto V was the most-watched title of 2023, accumulating 1.3 billion hours of viewership.
- Fortnite led the industry in creator engagement with 2.8 million unique channels, more than double the count of its nearest competitor.

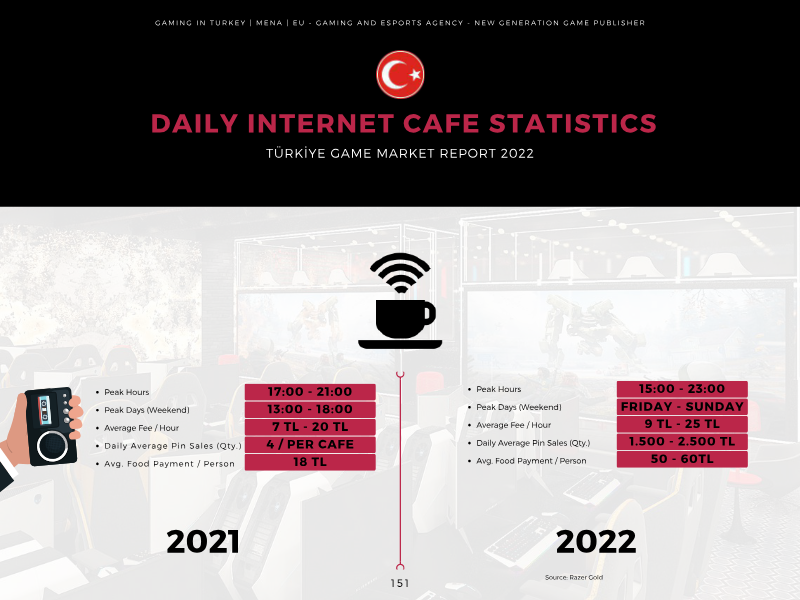
Turkey Game Market 2022 Report
The Turkish gaming market in 2022 serves as a critical case study of a high-growth production hub navigating significant domestic economic volatility.
- The Turkish gaming market experienced a significant revenue contraction in 2022, falling to $625 million from $1.2 billion in 2021 due to currency depreciation and reduced consumer purchasing power.
- Despite the revenue decline, Istanbul remains a global investment hub, ranking second in Europe and fifth globally with over $424 million secured across gaming transactions in 2022.
- The industry is projected to maintain a 24.1% compound annual growth rate through 2026, driven by a strategic shift toward mid-core, PC, and console development alongside AI and blockchain integration.
The Game Industry of Poland: 2023 Report
The Polish game industry has matured into a formidable global force, characterized by a sophisticated, export-oriented business model that prioritizes premium PC and console development.
- Poland’s game industry generated €1.286 billion in annual revenue as of 2022, driven by a business model that exports 75–90% of its production to international markets like the U.S., China, and Western Europe.
- The sector is experiencing a strategic consolidation phase, with 494 active studios shifting toward larger team sizes and high-budget productions despite a plateau in the total number of studios.
- The industry maintains a strong global competitive position, holding the second-highest share of titles on Steam’s global wishlist and achieving consistent year-on-year growth of 11% to 15%.
Ayudas AEVI Innovación: Edición 2023
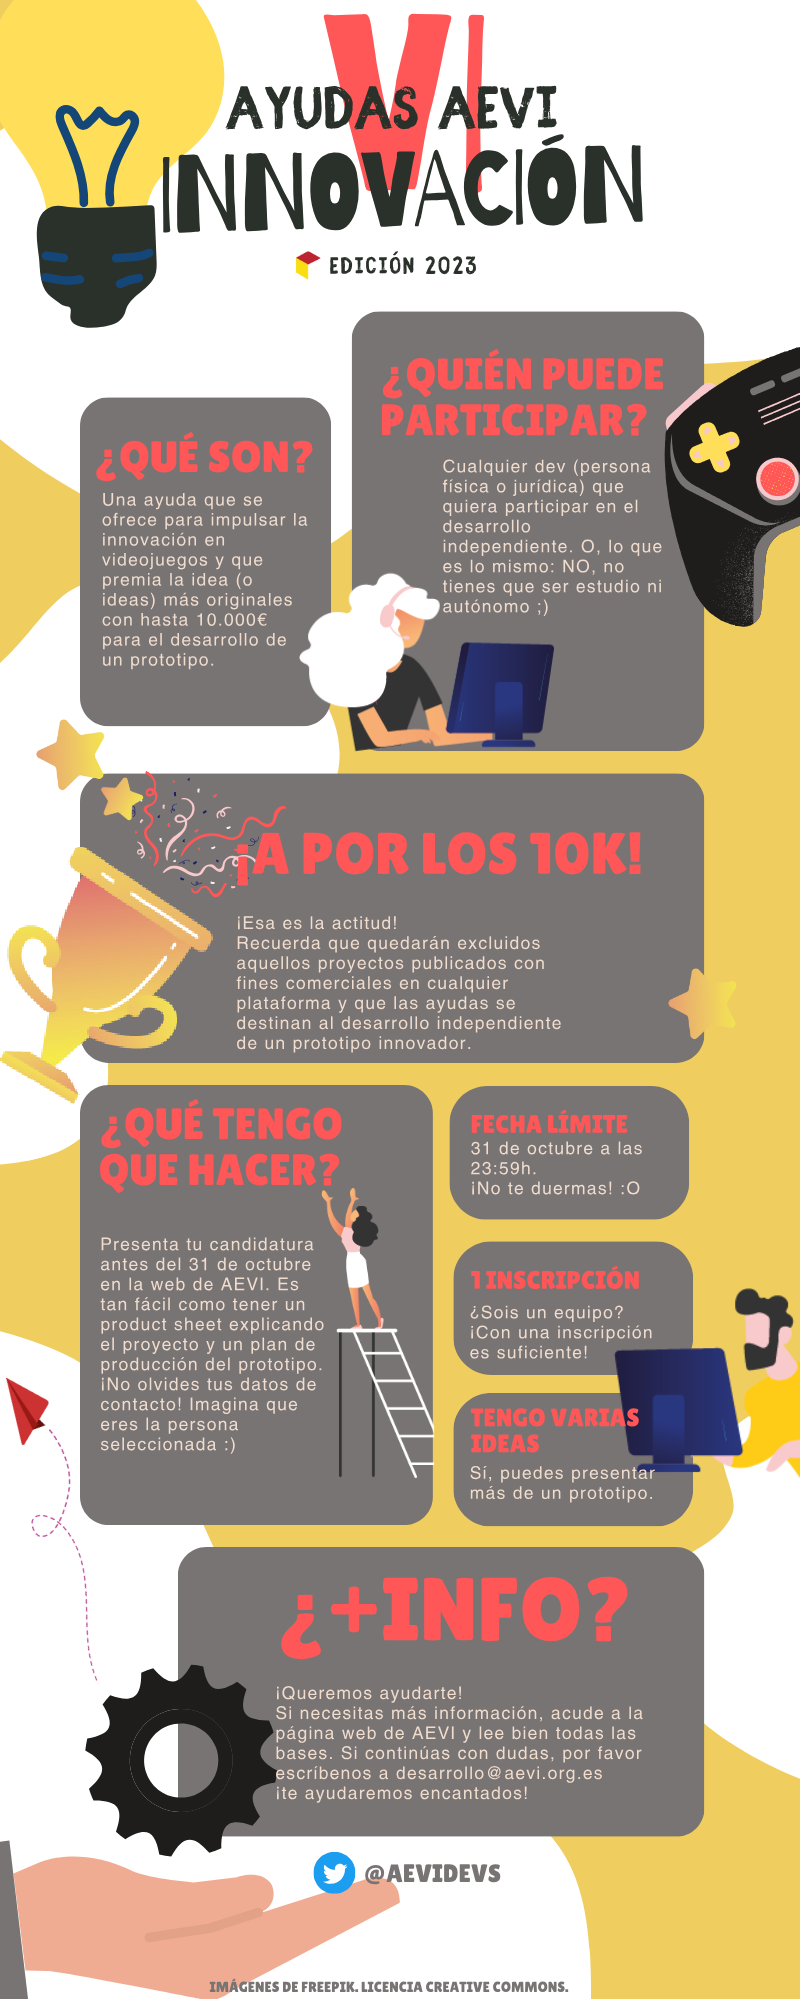
The AEVI Innovation program for 2023 offers financial support of up to €10,000 to independent developers—both individuals and legal entities—who wish to create an innovative prototype in the video-game sector.
- The AEVI Innovation program provides financial grants of up to €10,000 to support the development of innovative video game prototypes.
- Applications must be submitted by the deadline of 31 October at 23:59 via the official AEVI website.
- Eligible projects must be non-commercial and cannot have been previously published on any platform.
Gaming Report 2023
The global gaming industry in 2023 is defined by a strategic shift toward development efficiency and long-term player retention.
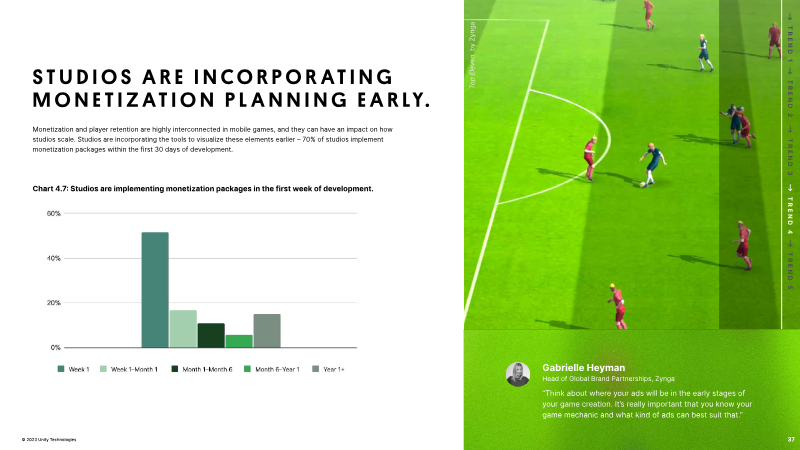
- To ensure financial viability, 70% of studios now integrate monetization and LiveOps within the first 30 days of development, contributing to a 33% increase in average game lifespans.
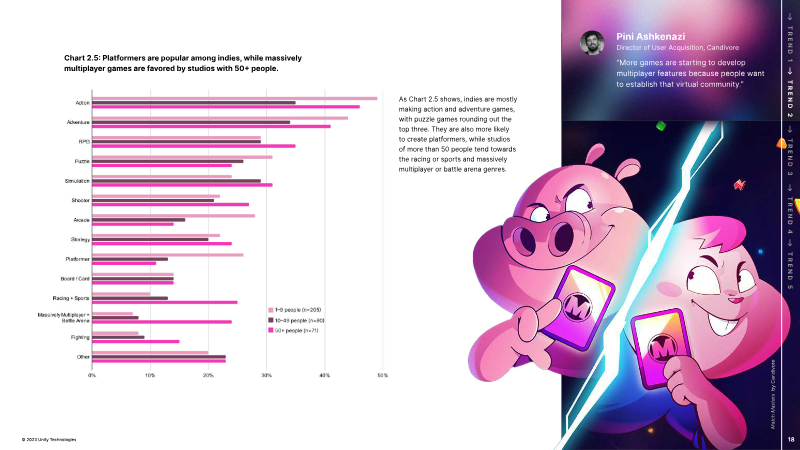
- Development efficiency has accelerated, with 62% of indie developers now shipping titles in under a year by utilizing premade assets and reducing average developer hours.
- Monetization models are shifting toward a balance between ad-supported structures and in-app purchases, supported by a 27% rise in battle pass adoption.
State of the Game Industry 2023
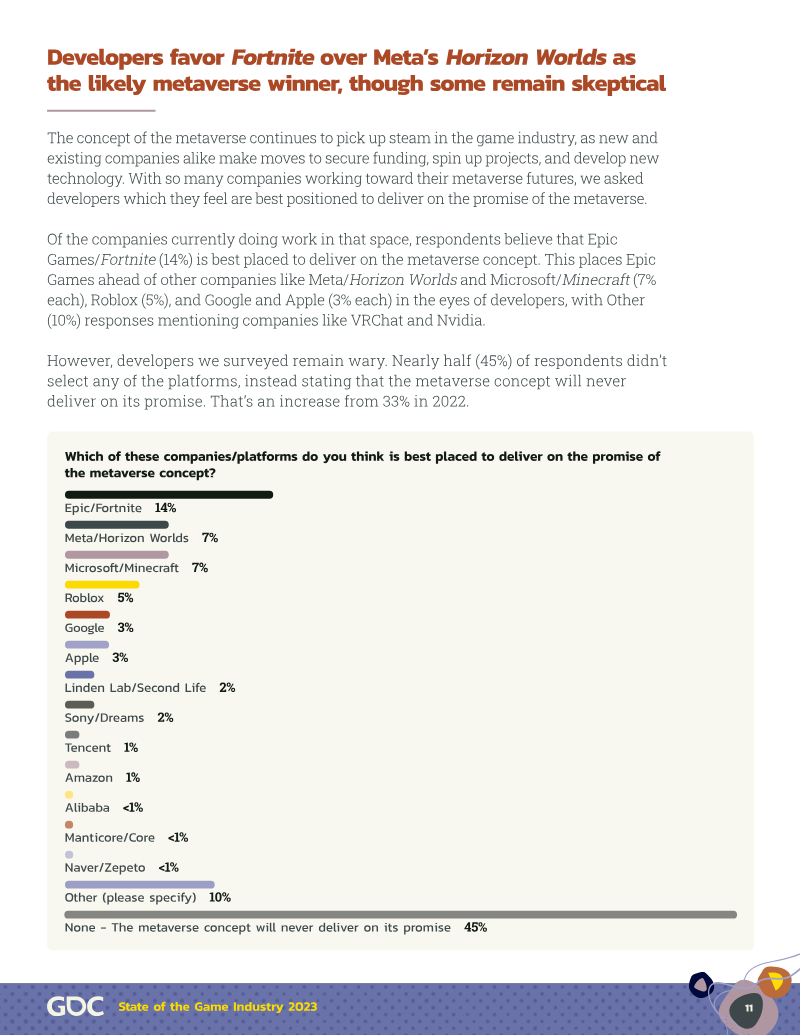
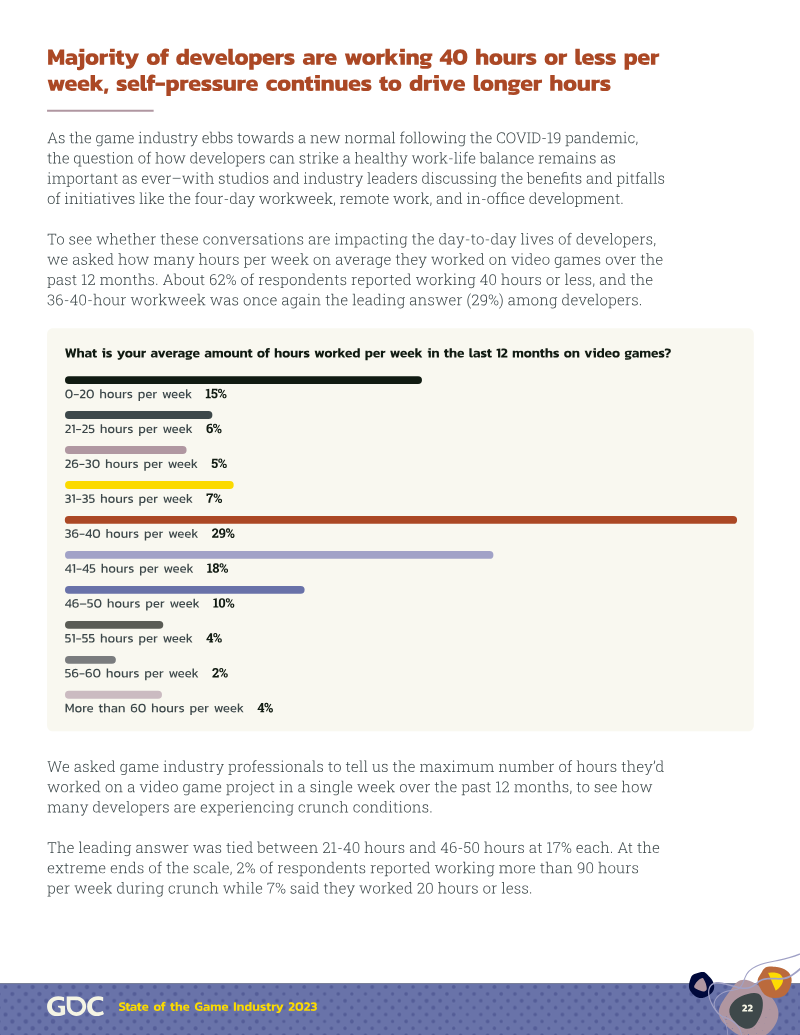
The global game development landscape in 2023 is characterized by a return to established platforms and a growing skepticism toward speculative technologies.
- The industry is pivoting toward technological pragmatism, with PC as the primary development focus and PlayStation 5 as the preferred console, while interest in blockchain and the metaverse has significantly declined.
- Workplace culture is under scrutiny as 40% of the workforce reports experiencing player harassment, with community managers and marginalized groups being the most affected.
- Labor tensions are rising, characterized by majority support for unionization among developers and widespread concern regarding the market impact of large-scale studio acquisitions.
State of Game Development & Design Report 2023
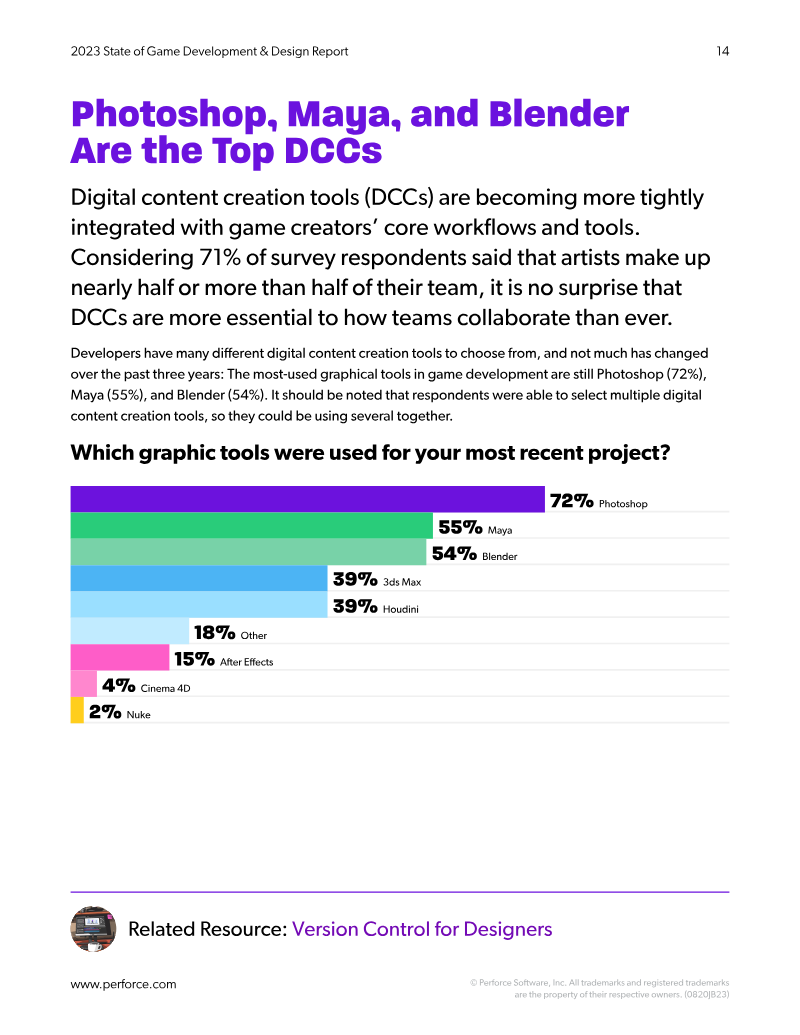
The 2023 State of Game Development & Design Report provides a comprehensive analysis of the current trends, technological preferences, and operational hurdles facing the global gaming industry.
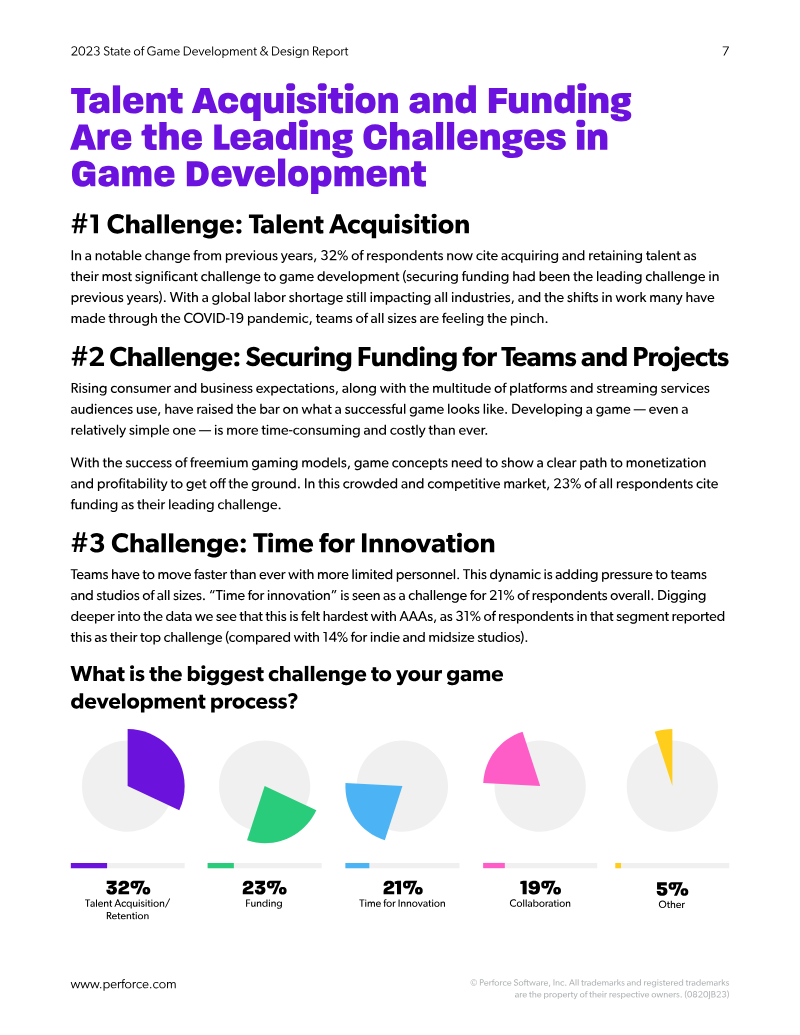
- Talent acquisition and retention has overtaken funding as the industry's primary challenge, cited by 32% of developers as their leading hurdle.
- Development velocity is a critical issue for AAA studios, with 49% of respondents identifying time-related bottlenecks and lengthy build times as their greatest operational obstacle.
- Unreal Engine is the industry's leading game engine with 57% usage, while Perforce Helix Core has become the standard for version control, utilized by 73% of developers.
UK Games Jobs Summary: November 2022
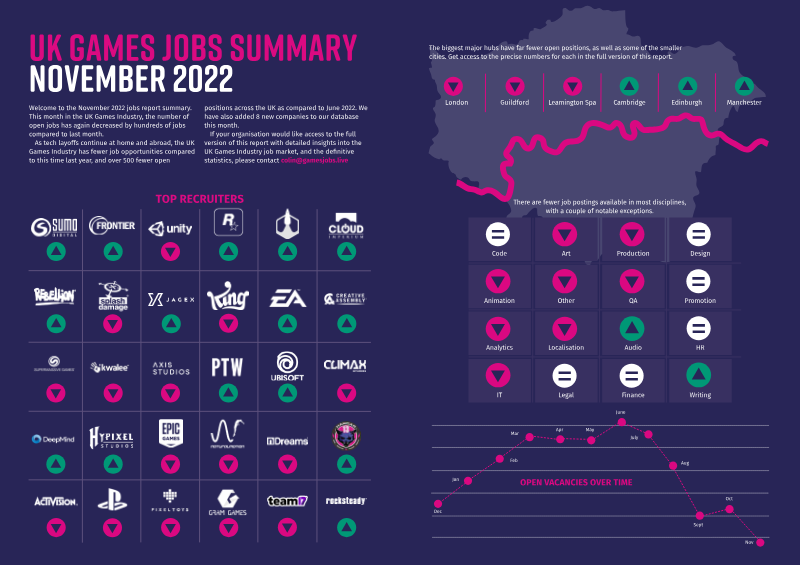
The United Kingdom games industry experienced a notable contraction in recruitment activity during November 2022, continuing a downward trend observed throughout the second half of the year.
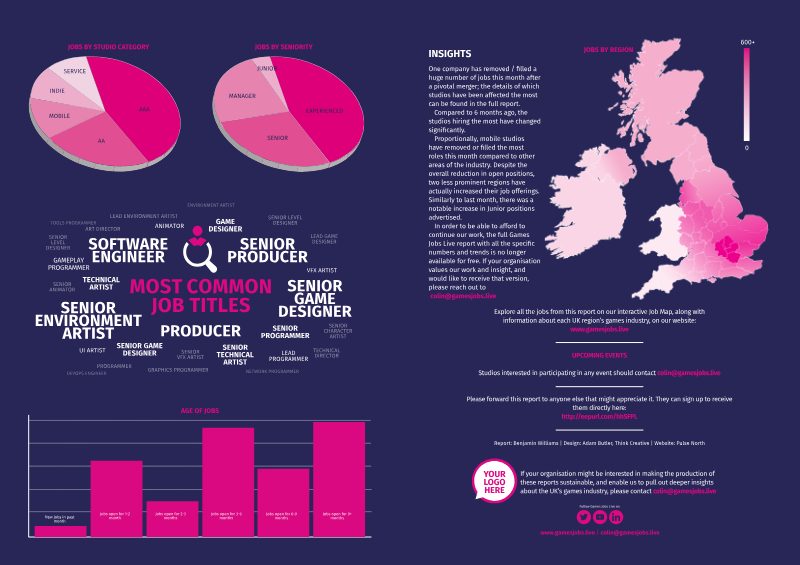
- UK games industry recruitment contracted significantly in November 2022, resulting in over 500 fewer open vacancies compared to June 2022.
- Mobile studios experienced the highest proportional reduction in job postings, largely driven by the completion or cancellation of roles following corporate mergers.
- Despite the broader market decline, the industry added over 600 new job postings during the month, and the total number of tracked studios grew by eight companies.
Unity Gaming Report 2022
The global gaming industry experienced a massive production surge throughout 2021, characterized by a 93% increase in game creation and a 31% rise in the number of active creators.
- Publishers operating across three or more genres generate up to 197% more daily revenue than those specializing in a single category, yet 76% of developers remain focused on a single genre.
- The gaming industry saw a 93% increase in game creation and a 30% rise in total revenue in 2021, with hypercasual titles experiencing a 137% production surge and a 162% increase in in-app purchase revenue.
- Industry consolidation reached record levels with $85 billion in acquisitions, while small indie studios continue to drive innovation by utilizing accessible tools and analytics.
M&A Medley: 8 Acquisitions
Embracer Group has executed a strategic expansion through the acquisition of eight distinct entities, including CrazyLabs, Ghost Ship Games, Easy Trigger Games, Force Field VR, DigixArt, Slipgate Ironworks, 3D Realms, and a majority stake in Grimfrost.
- Embracer Group acquired eight entities—CrazyLabs, Ghost Ship Games, Easy Trigger Games, Force Field VR, DigixArt, Slipgate Ironworks, 3D Realms, and a majority stake in Grimfrost—to expand its mobile, VR, and indie gaming footprint.
- The acquisitions involve an initial purchase price of SEK 2.7 billion, with total potential consideration reaching SEK 4.7 billion based on performance milestones through 2029.
- These investments are projected to contribute between SEK 2,000 and 3,000 million in net sales and SEK 350 to 550 million in Operational EBIT for the fiscal year ending March 2023.
Annual Barometer of the Video Game Industry in France 2021
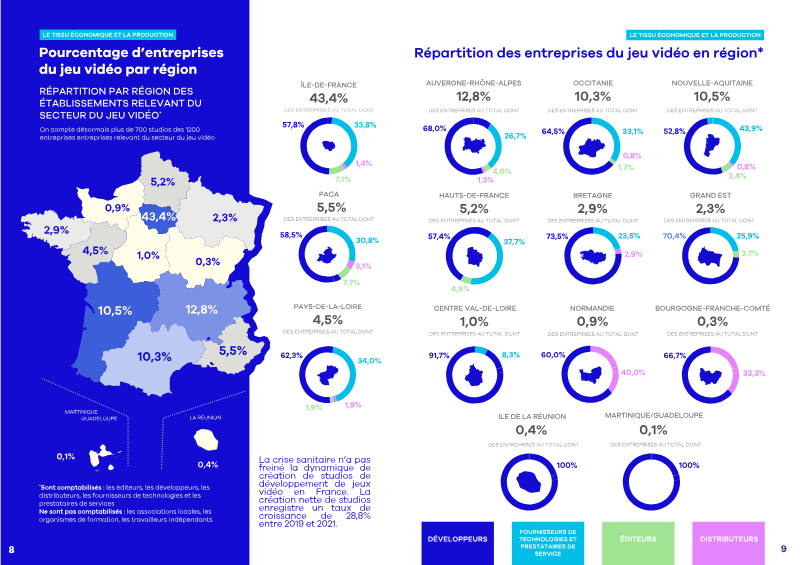
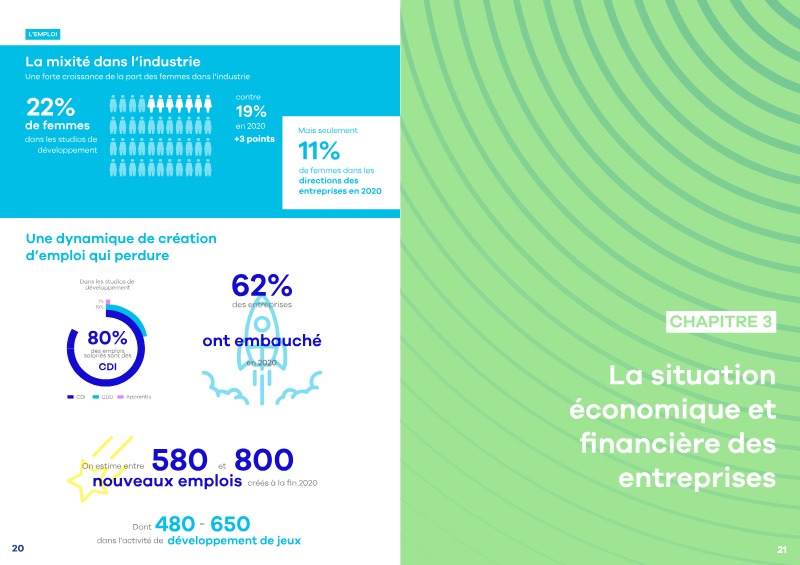
The 2021 Annual Barometer of the Video Game Industry in France provides a comprehensive analysis of the sector’s economic health, employment trends, and production landscape.
- France is the second most attractive country globally for video game development, supported by a strong reliance on national tax credits and regional funding utilized by 41% of companies.
- The industry is highly productive with approximately 1,350 games in development during 2021, 92% of which are original intellectual properties.
- Despite high levels of optimism regarding the market, 36.5% of studios reported a financial deficit in 2020, marking the highest rate of insolvency since 2014.
Serbian Gaming Industry Report 2021
In 2021 Serbia’s gaming ecosystem emerged as a rapidly expanding, export-oriented sector that combined a sizable studio base with a vibrant indie community.
- In 2021, Serbia’s gaming sector comprised approximately 130 studios employing 1,548 people, generating $125 million in revenue with 75% to 100% of earnings derived from international exports.
- The industry is heavily reliant on the free-to-play model, which accounts for 64% of all games produced, while the total output reached roughly 2,200 titles.
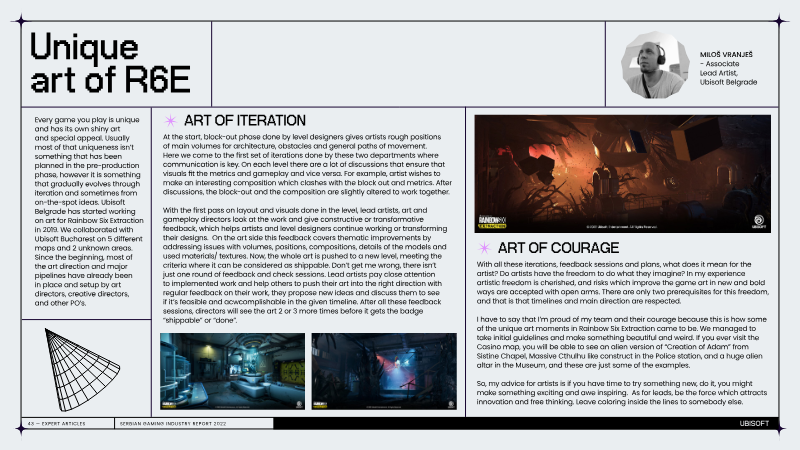
- The ecosystem supports a diverse production scale, ranging from indie developers using high-fidelity tools like MetaHuman Creator to major contributors such as Nordeus, Playrix RS, and Ubisoft Belgrade.