Market Analysis
Documents
Global Games Forecasts 2025-2031
The analysis projects that the worldwide video‑game market has entered a mature phase, with revenue expected to reach $236.9 billion in 2025 and to climb modestly to $280.1 billion by 2031. Growth rates flatten to around 4–5 percent annually, roughly matching global inflation, and the compound annual growth rate through 2031 is low enough that double‑digit expansion is deemed unrealistic. Software sales remain the primary engine, buoyed by premium launches such as the next Grand Theft Auto installment and new Switch titles, while in‑game spending—currently about 68 percent of software revenue—will dip slightly to 67 percent by 2031. Subscription services are forecast to rise from $13.1 billion to $18.5 billion, driven largely by price increases as user bases saturate.
Geographically, the Asia‑Pacific region dominates the player base, comprising roughly 53 percent of the 1.53 billion gamers counted in 2024 and exhibiting the highest penetration at about 13 percent of the regional population. Although software revenues are set to grow modestly across all markets, the analysis warns that live‑service oversaturation is eroding in‑game spend, while premium purchases and subscription models gain traction, particularly in China and other APAC economies.
Strategically, the findings suggest that developers and publishers should shift from a survival‑until‑2025 mindset to a longer‑term “stick‑till‑2026” approach, emphasizing high‑quality premium releases, selective investment in live‑service titles, and cross‑platform integration. The forecasts rely on a proprietary model that combines company financials, survey data, and third‑party sources, and the authors note that the projections reflect their own assumptions and carry no liability for potential losses.
- The global video-game market has entered a mature phase, with revenue projected to grow from $236.9 billion in 2025 to $280.1 billion by 2031 at a modest annual rate of 4–5 percent.
- Asia-Pacific remains the dominant market, accounting for 53 percent of the 1.53 billion global gamers in 2024 and showing the highest regional penetration at 13 percent.
- In-game spending, which currently accounts for 68 percent of software revenue, is expected to experience a slight decline to 67 percent by 2031 due to live-service market oversaturation.
- Subscription service revenue is forecast to grow from $13.1 billion to $18.5 billion by 2031, with growth driven primarily by price increases rather than user base expansion.
- Software sales remain the primary revenue engine, supported by major premium releases such as the upcoming Grand Theft Auto installment and new Nintendo Switch titles.
The 2025 Guide to US Gaming Audiences: From Data to Personas
The 2025 United States gaming landscape reflects a profound demographic shift, moving away from the outdated stereotype of the isolated young male toward a mainstream, diverse population nearly evenly split by gender. Modern gamers are characterized by high levels of education and financial stability, with a significant portion of the audience falling into middle-to-high income brackets ranging from $51,000 to over $250,000 in net worth. This population views gaming as a social and familial cornerstone rather than a solitary pursuit, possessing substantial purchasing power that prioritizes immediate lifestyle quality, premium groceries, and discretionary spending over long-term asset accumulation.
Physical activity and convenience define the daily habits of this audience, as they over-index in gym attendance and outdoor recreation. Consumer behavior remains nuanced across different genres; for instance, Action and Simulation players tend to be more tech-focused and affluent, whereas Casual and Arcade gamers often reside in multi-generational, value-conscious households. Despite these differences, a universal reliance on delivery services, mainstream fast-food brands, and budget-friendly fitness options persists across the entire segment. This suggests a consumer base that values efficiency and digital integration in their physical lives.
The market is further segmented into distinct personas ranging from tech-savvy "Young Lifestyle Explorers" to financially secure "Golden Fans" over the age of 70. High-value opportunities for precision targeting exist within specific niches, such as sports gamers who dominate the highest income tiers or board and trivia enthusiasts who exhibit practical, family-oriented spending patterns. Geographically concentrated in hubs like Iowa and Hawaii, these diverse audiences offer brands a sophisticated landscape of consumers who defy traditional tropes, presenting a high-value target for advertisers across nearly every life stage and socioeconomic category.
- The US gaming audience is now gender-balanced and financially stable, with significant segments earning between $51,000 and over $250,000 in net worth.
- Modern gamers prioritize immediate lifestyle quality and discretionary spending over long-term asset accumulation, frequently investing in premium groceries and convenience services.
- Gaming is primarily a social and familial activity rather than a solitary pursuit, with consumer habits heavily influenced by multi-generational household dynamics.
- Consumer behavior is genre-specific: Action and Simulation players are typically more tech-focused and affluent, while Casual and Arcade gamers are more value-conscious.
- The audience over-indexes in physical activity, including gym attendance and outdoor recreation, while maintaining a universal reliance on delivery services and mainstream fast-food brands.
Mobile Game Market Insights: India 2025
India is the world’s largest mobile gaming market by volume, reaching 8.45 billion downloads in the 2024-25 fiscal year. Despite this massive scale, which is more than double that of Indonesia, the market faces significant monetization hurdles. Total in-app purchase revenue stands at approximately $400 million, reflecting a cost-sensitive consumer base that favors free-to-play models. However, the market shows signs of evolution, with revenue growing 8.5% year-over-year, driven largely by high-value spenders on iOS and the increasing adoption of digital payment systems like UPI.
The player base is predominantly young and male, with 77% of gamers aged 18-34 and 86% identifying as male. While casual subgenres such as driving simulators, platformers, and tabletop games dominate download charts due to their cultural resonance, revenue is concentrated in core competitive genres. Shooters, specifically Battle Royale titles like Garena Free Fire and Battlegrounds Mobile India, command 50% of total market revenue. Strategy and Casino games also represent significant portions of the spending landscape, highlighting a divide between mass-market reach and deep-engagement monetization.
A central fixture of the domestic industry is Ludo King, which has remained the most downloaded game in India since 2017, surpassing 1.25 billion lifetime downloads. Its success is attributed to the digitization of a traditional board game combined with social features like live voice chat. While domestic publishers like Gametion and Dream11 maintain strong local positions, there is a growing trend of India-based firms expanding into overseas markets, such as the United States and Saudi Arabia, to capture higher per-user revenue.
The findings are based on Sensor Tower’s App Performance and Audience Insights data for the period of April 2024 through March 2025. The methodology utilizes estimates from the App Store and Google Play, excluding ad revenue, third-party Android stores, and pre-installs. The scope focuses on the Indian mobile ecosystem while providing comparative context against other major Asian markets.
- India is the world's largest mobile gaming market by volume, recording 8.45 billion downloads in the 2024-25 fiscal year.
- Despite high download volume, in-app purchase revenue is limited to $400 million, though it is growing at 8.5% year-over-year due to increased digital payment adoption and high-value iOS spenders.
- Revenue is heavily concentrated in core competitive genres, with Battle Royale titles like Garena Free Fire and Battlegrounds Mobile India accounting for 50% of total market earnings.
- The player base is predominantly young and male, with 77% of gamers aged 18-34 and 86% identifying as male.
- Ludo King remains the dominant casual title, maintaining its status as the most downloaded game since 2017 with over 1.25 billion lifetime downloads.
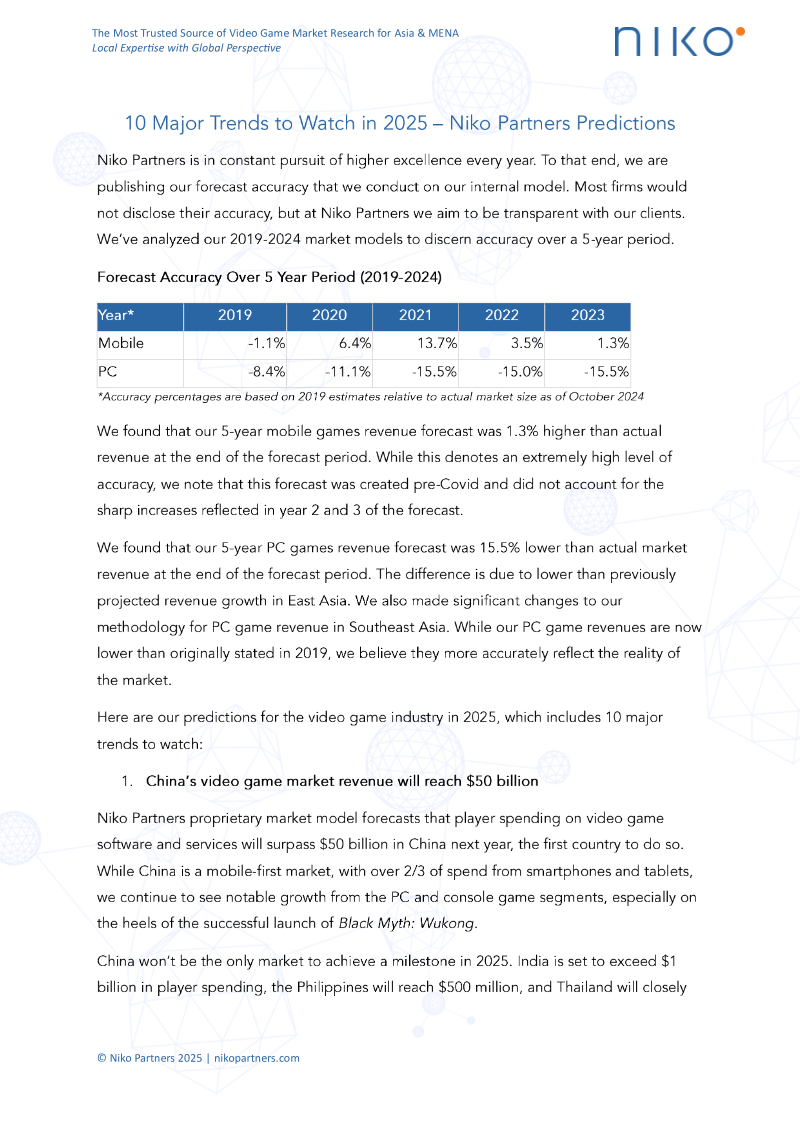
10 Major Trends to Watch in Asia & MENA
The video game industry across Asia and the Middle East and North Africa (MENA) is undergoing a period of significant transformation as of 2025, driven by shifting player demographics and evolving monetization strategies. These regions represent the primary engines of global gaming growth, characterized by a massive mobile-first audience and a rapidly expanding middle class with increasing discretionary income. Market dynamics are increasingly defined by the convergence of social media, competitive gaming, and cross-platform accessibility, which have collectively lowered the barrier to entry for new consumers while deepening engagement among existing enthusiasts.
Strategic focus in these territories has shifted toward hyper-localization and the integration of emerging technologies to enhance user retention. In the MENA region, government-backed initiatives and large-scale investments are accelerating the development of local infrastructure and talent, positioning countries like Saudi Arabia and the United Arab Emirates as central hubs for international esports and game development. Meanwhile, the Asian market continues to lead in the refinement of live-service models and the adoption of innovative payment ecosystems that bypass traditional storefront limitations.
The current landscape emphasizes the necessity of understanding regional regulatory environments and cultural nuances to achieve commercial success. As the industry moves forward, the integration of artificial intelligence in content creation and the rise of niche gaming communities are expected to further diversify the market. Companies that prioritize local expertise and adapt to the unique technological preferences of these diverse populations will be best positioned to capitalize on the sustained upward trajectory of the Asia and MENA gaming sectors.
- Asia and MENA are the primary engines of global gaming growth, driven by a mobile-first audience and a rising middle class with increased discretionary income.
- Government-backed investments in Saudi Arabia and the UAE are rapidly establishing these nations as central hubs for international esports and game development infrastructure.
- Market success in these regions now requires hyper-localization and the adoption of innovative payment ecosystems that bypass traditional storefront limitations.
- The convergence of social media, competitive gaming, and cross-platform accessibility is successfully lowering barriers to entry while deepening user engagement.
- Future market growth will be defined by the integration of artificial intelligence in content creation and the strategic targeting of niche gaming communities.
Mobile App Trends Spotlight Edition: Türkiye 2025
The mobile application economy in Türkiye is entering a high-growth, maturing phase, with total revenue projected to reach $1.65 billion by 2029. Ranking eighth globally for both total downloads and time spent in-app, the market is driven by a young, tech-oriented population and an 87% internet penetration rate. Analysis of data from January 2023 through July 2025 reveals that while the market is scaling globally, it maintains unique local characteristics across the gaming, finance, and e-commerce verticals.
The gaming sector remains a primary driver, with installs growing 12% year-over-year in 2024. Hyper-casual games dominate install shares at 28.6%, yet music and action genres command the highest session engagement. Notably, Turkish users spend an average of 32.8 minutes per gaming session, surpassing both regional and global averages. However, retention rates in Türkiye tend to be lower than global benchmarks, with only 19% of users returning the day after installation compared to 26% globally.
The finance and e-commerce sectors show similar trends of high engagement and rapid adoption of new technologies. Finance app installs surged 30% in the first half of 2025, supported by a high mobile banking adoption rate of 85%. In e-commerce, local developers maintain a strong foothold, creating 80% of the top shopping apps. While session lengths in these categories are gradually declining—potentially indicating more efficient user paths to purchase—retention rates for finance and shopping apps in Türkiye consistently outperform global medians.
A significant emerging trend is the rapid rise of generative AI applications, which saw a 142.5% increase in downloads between 2023 and 2024. This growth is fueled by a strategic pivot of local hyper-casual game studios toward AI-first apps and the development of proprietary Turkish-language models. These findings suggest that Türkiye is transitioning from a regional player to a global powerhouse, characterized by a highly engaged user base and a robust ecosystem of domestic developers.
- The Turkish mobile app market is projected to reach $1.65 billion in revenue by 2029, supported by an 87% internet penetration rate and a global top-ten ranking for downloads and time spent in-app.
- Generative AI applications experienced a 142.5% surge in downloads between 2023 and 2024, driven by local hyper-casual studios pivoting to AI-first development and proprietary Turkish-language models.
- Finance app installs grew by 30% in the first half of 2025, bolstered by an 85% mobile banking adoption rate and retention rates that consistently outperform global medians.
- Gaming remains a primary market driver with 12% year-over-year install growth in 2024, though day-one retention at 19% lags significantly behind the 26% global benchmark.
- Turkish gamers exhibit high engagement, averaging 32.8 minutes per session—surpassing global averages—with hyper-casual titles capturing 28.6% of total install share.
What Does the Monetization Landscape Look Like for Video Games in MENA?
The video game industry in the MENA-3 region—comprising Saudi Arabia (KSA), the United Arab Emirates (UAE), and Egypt—is experiencing rapid expansion driven by a young, tech-savvy population and significant government investment. In 2024, player spending in these markets reached $2 billion, a 4% year-over-year increase, and is projected to exceed $2.7 billion by 2028. While the region is home to 70.3 million gamers, it remains economically diverse: the UAE boasts the highest annual average revenue per user (ARPU) at $84.60, whereas Egypt represents a high-volume market with over five times the player base of the UAE but a much lower ARPU of $3.50.
The monetization landscape is defined by a shift toward multi-platform engagement and a high percentage of unbanked or underbanked consumers. Approximately 67% of the MENA population lacks access to traditional credit or debit cards, creating a significant barrier for standard app store transactions. In Egypt, credit card penetration is as low as 2.8%, leading to the dominance of local digital wallets like Vodafone Cash. Conversely, KSA and the UAE feature high internet penetration and 5G coverage, with players increasingly favoring hybrid free-to-play models, premium titles, and subscription services.
Direct-to-consumer (D2C) payment platforms and web shops are identified as critical tools for navigating these market complexities. By bypassing the traditional 30% commission fees of major app stores, developers can offer localized pricing, regional payment methods, and enhanced loyalty rewards. Findings indicate that 53% of paying mobile and PC gamers in the region have already made purchases through official game websites. Successful market entry requires a tailored approach that includes high-quality Arabic localization, culturalization of content, and the integration of local payment networks such as Mada in Saudi Arabia and Fawry in Egypt.
The analysis is based on a survey of 1,200 gamers, expert interviews, and proprietary market data. It concludes that the MENA-3 region offers a strategic bridge between Eastern and Western markets, providing a gateway to nearly 400 million Arabic speakers worldwide for companies that adopt flexible, region-specific monetization strategies.
- The MENA-3 gaming market (KSA, UAE, Egypt) generated $2 billion in player spending in 2024 and is projected to grow to over $2.7 billion by 2028.
- Payment infrastructure is a major barrier, as 67% of the regional population lacks access to traditional credit or debit cards, necessitating the integration of local payment networks like Mada in Saudi Arabia and Fawry in Egypt.
- Direct-to-consumer (D2C) web shops are essential for bypassing 30% app store fees, with 53% of paying gamers in the region already utilizing official game websites for purchases.
- The region exhibits extreme economic disparity, ranging from the UAE’s high ARPU of $84.60 to Egypt’s high-volume, low-ARPU market where credit card penetration is only 2.8%.
- Successful market entry requires a localized strategy that includes high-quality Arabic content and the adoption of flexible payment solutions to reach the broader market of nearly 400 million Arabic speakers.
Big Games Industry Employment Survey 2025: Salaries, Compensation Trends and State of the Games Sector in Europe
The European games industry entered 2025 in a state of significant distress, characterized by widespread layoffs, stagnant wages, and a sharp decline in employee well-being. Approximately 26% of professionals across the continent experienced layoffs, with junior-level talent bearing the brunt of the instability as 39% exited the sector entirely. This contraction has shifted the labor market from a growth-oriented environment to one focused on cost optimization. Consequently, employee engagement scores have plummeted, and over half of the workforce reports suffering from professional burnout. Financial stability has replaced company mission as the primary motivator for 87% of workers, many of whom are now accepting inferior contract terms or pay cuts to remain employed.
Compensation trends reveal a deepening divide based on geography, seniority, and specialization. While median salaries remain highest in the Fighting and MMO genres, reaching up to €90,000 in the EU and UK, a persistent gender pay gap continues to affect technical and C-level roles. Programmers have seen a downward trend in compensation due to increased competition and the rapid integration of artificial intelligence. AI adoption has surged, with over 60% of professionals now using these tools regularly, particularly in analytics and management. However, creative fields like art and quality assurance remain more resistant to AI integration, even as these specific roles face the highest risks of unemployment and long-term job searches.
Workplace culture is currently defined by a regression in structured support and a rise in management inefficiency. The number of companies lacking dedicated diversity and inclusion specialists has increased to 67%, while nearly one-third of developers report stagnant professional growth. Although remote flexibility remains a high priority, the shift toward pragmatic relocation suggests that workers are increasingly making career decisions based on cost-of-living calculations rather than traditional ambition. This environment of instability has doubled the rate of long-term unemployment, leaving the European games industry with a workforce that is increasingly disillusioned and prioritized toward survival over innovation.
- The European games industry is in a state of contraction, with 26% of professionals experiencing layoffs and 39% of junior-level talent exiting the sector entirely.
- Financial stability has become the primary motivator for 87% of the workforce, leading many to accept pay cuts or inferior contract terms to maintain employment.
- Over 50% of the workforce reports suffering from professional burnout, while 67% of companies now lack dedicated diversity and inclusion specialists.
- AI adoption has reached 60% among professionals, contributing to a downward trend in compensation for programmers, while art and quality assurance roles face the highest risks of unemployment.
- Median salaries for top-tier genres like Fighting and MMOs reach up to €90,000 in the EU and UK, though a persistent gender pay gap remains in technical and C-level positions.
Making Games, Making Future: Inside the Realities of Game Careers
This research examines the professional landscape of the global gaming industry, drawing on a survey of over 160 professionals conducted during Gamescom 2025. The sample represents a diverse geographic spread, with significant participation from Europe and North America, alongside emerging representation from Latin America, Asia-Pacific, and Africa. Demographically, the industry remains male-dominated (65%), though women (30%) and non-binary individuals (6%) constitute a notable portion of the workforce. The data highlights a mid-career-heavy industry, where nearly half of the respondents possess six to ten years of experience, while newcomers are increasingly rare due to slowed recruitment and a preference for senior talent.
The central thesis identifies a stark paradox: while 76% of professionals report high job satisfaction driven by a deep passion for creative expression, trust in the industry as a sustainable career path has collapsed, evidenced by a Net Promoter Score (NPS) of -40. This disillusionment is most pronounced among veterans aged 45 and older. While the "spark of passion" remains the primary motivator for joining and staying in the field, it is increasingly undermined by systemic issues. Key deterrents include low compensation (54%), unstable employment (43%), and burnout (30%).
The findings conclude that the industry is at a critical juncture. Professionals envision a future defined by player-centric design, cross-platform development, and increased diversity. However, they warn that the current model—characterized by "suits" maximizing short-term profits and frequent layoffs—is unsustainable. The research suggests that a "Golden Age" of gaming can only be achieved by shifting from profit-driven exploitation of passion toward structural stability, fair compensation, and genuine collaboration. Without these changes, the industry risks a continuous drain of the talent required to sustain its creative output.
- Despite 76% of professionals reporting high job satisfaction, the industry's Net Promoter Score (NPS) has plummeted to -40, signaling a collapse in trust regarding long-term career sustainability.
- The industry is experiencing a talent bottleneck as recruitment slows and employers prioritize senior staff, leaving nearly half of the workforce concentrated in the 6-to-10-year experience bracket.
- Systemic instability is driving professional disillusionment, with 54% of respondents citing low compensation, 43% citing job insecurity, and 30% citing burnout as primary deterrents.
- The workforce remains male-dominated at 65%, with women comprising 30% and non-binary individuals making up 6% of the surveyed population.
- Industry professionals identify a critical conflict between creative, player-centric goals and a current business model focused on short-term profit maximization and frequent layoffs.
Mobile Casual Benchmarks Report 2025
The 2025 Mobile Casual Benchmarks Report provides a comprehensive analysis of the Android gaming market, focusing on performance metrics across various casual genres and subgenres. Based on data collected from over 10,000 mobile games and billions of installs between June 2024 and January 2025, the findings offer a strategic overview of the United States market. The analysis evaluates key performance indicators including download volume, user retention, session length, and ad monetization efficiency to identify growth opportunities for developers.
Findings indicate a significant shift in the mobile landscape, with a strong recommendation for developers to transition from pure hypercasual models to hybrid casual designs. While hypercasual and simulation games lead in total downloads, they suffer from low 30-day retention rates of approximately 3% and a modest ARPU of $0.79. In contrast, hybrid casual games—which integrate deeper progression systems and meta-elements—demonstrate superior sustainability. Subgenres such as Merge 3, Luck Battle, and Life Simulator emerge as highly profitable outliers, achieving ARPU figures between $11.08 and $14.83.
Engagement data reveals that Strategy and Tabletop genres command the highest user attention, while subgenres like Ludo and Merge 3 lead in session duration, with the latter averaging 656 seconds. Retention is strongest in Sports, Racing, and Tabletop categories, while specific subgenres like Coin Pusher and Management Sim maintain over 50% Day 1 retention. Regarding monetization, Puzzle and Match games are identified as the most effective vehicles for high-frequency ad impressions, whereas Strategy and Tabletop games are better suited for rewarded video formats. Ultimately, the data suggests that long-term profitability in 2025 depends on balancing accessible gameplay with the deeper engagement mechanics characteristic of the hybrid casual segment.
- Hybrid casual games are significantly more profitable than hypercasual models, with top subgenres like Merge 3, Luck Battle, and Life Simulator achieving ARPU figures between $11.08 and $14.83.
- Pure hypercasual and simulation games suffer from poor long-term sustainability, characterized by low 30-day retention rates of approximately 3% and an ARPU of only $0.79.
- Merge 3 games demonstrate high player engagement, leading all subgenres with an average session duration of 656 seconds.
- Coin Pusher and Management Sim subgenres are the most effective for player acquisition, maintaining over 50% Day 1 retention rates.
- Monetization strategy should be genre-specific, with Puzzle and Match games optimized for high-frequency ad impressions, while Strategy and Tabletop games perform best with rewarded video formats.
Mobile Monetization Report 2025
The global mobile gaming market reached $57.1 billion between 2023 and 2025, representing a 3.4% increase driven primarily by the App Store and emerging regions such as LATAM and MENA. While established markets like China and Japan experienced revenue contractions of up to 15%, the Strategy genre surged by over 25%, bolstered by a massive 213% increase in Card Battlers. A pivotal shift in the industry is the rise of direct-to-consumer revenue, which grew by 46% among the top 100 US titles as developers increasingly adopt webshops and alternative payment systems to bypass traditional platform fees.
Monetization trends indicate a widening performance gap between platforms, with the App Store consistently outperforming Google Play in both revenue growth and average revenue per paying user. In the United States, the share of high-value players spending over $100 rose from 22% to 32%, while the App Store’s 90-day ARPPU climbed by 71%. This growth is largely attributed to rising transaction values, including the introduction of $159.99 price caps in top-tier titles. Conversely, Google Play’s growth remains dependent on a higher frequency of smaller, low-priced purchases, particularly as the RPG sector faces a 15% decline and a significant drop in Android spending.
Genre-specific performance reveals a move toward diversification and sophisticated LiveOps. The Puzzle genre grew by 15%, led by a 911% revenue explosion in Block Puzzles, while the Hybridcasual segment saw in-app purchase revenue surge by 84% through the standardization of Season Passes and failure-triggered offers. Despite a 7.5% decline in the Casino market, the Simulation genre successfully increased average purchase values by 52%. Across all segments, developers are prioritizing customizable bundles and high-value special offers to maintain engagement and offset declining purchase frequencies among long-term players.
- Top US mobile titles are increasingly bypassing platform fees, with direct-to-consumer revenue via webshops and alternative payment systems growing by 46%.
- The App Store is significantly outperforming Google Play, evidenced by a 71% increase in 90-day ARPPU and a rise in high-value US players spending over $100 from 22% to 32%.
- The Strategy genre surged over 25% globally, driven by a 213% explosion in Card Battlers, while the Puzzle genre grew 15% behind a 911% revenue spike in Block Puzzles.
- Hybridcasual games are successfully monetizing through IAPs, which surged 84% due to the standardization of Season Passes and failure-triggered offers.
- While the global mobile market grew 3.4% to $57.1 billion, established markets like China and Japan contracted by up to 15%, shifting growth focus to emerging regions like LATAM and MENA.
Reclaiming the Game Distribution Landscape
This analysis examines the shifting dynamics of the mobile game distribution market as of Summer 2025, focusing on the transition from a duopoly dominated by Apple and Google toward a more diverse ecosystem of alternative app stores. The central thesis posits that the industry is at a critical "reset" point where developers are increasingly seeking to reclaim control over their revenue, discoverability, and platform policies. By diversifying distribution strategies, game makers aim to bypass high fees and restrictive environments that have historically stifled commercial and creative potential.
The findings are based on a survey of 304 senior-level mobile game development professionals from the United States and United Kingdom, all of whom work at companies with 250 or more employees. The research was conducted in April 2025 by Atomik Research on behalf of Aptoide. The data reveals significant industry dissatisfaction: 67% of developers are concerned about over-reliance on the two major stores, 51% cite high fees as a primary pain point, and 50% believe the dominant platforms unfairly prioritize their own services.
Despite the current dominance of the major stores—which still account for roughly 87% of revenue for the majority of respondents—there is a clear trend toward adoption of alternative platforms. Approximately 74% of developers expect alternative stores to be a standard part of their distribution mix within five years. Furthermore, 73% of respondents anticipate double-digit revenue growth from these alternative channels. Key perceived benefits include access to new user bases (42.8%), greater policy freedom (42.4%), and improved discoverability through curated content and better marketing support.
The scope of the analysis covers the global mobile gaming industry with specific emphasis on the US and UK markets. It concludes that while the Apple and Google stores remain essential for reach, the rise of alternative stores and direct-to-consumer webshops offers a necessary path for growth, risk reduction, and improved profit margins in an increasingly competitive landscape.
- As of April 2025, 67% of senior mobile game developers express concern over their over-reliance on the Apple and Google app store duopoly.
- While Apple and Google currently command 87% of mobile gaming revenue, 74% of developers expect alternative app stores to become a standard part of their distribution strategy within five years.
- Developers anticipate significant financial upside from diversification, with 73% of respondents projecting double-digit revenue growth from alternative distribution channels.
- High platform fees remain a primary industry pain point for 51% of developers, while 50% believe dominant platforms unfairly prioritize their own internal services.
- The primary drivers for adopting alternative stores include access to new user bases (42.8%), greater policy freedom (42.4%), and improved discoverability through better marketing support.
Retention Radar
The global mobile ecosystem is entering a period of maturation characterized by a 2.3% decline in installs, necessitating a strategic pivot from aggressive user acquisition toward sophisticated retention models. Because a 10% improvement in retention can yield profit increases of up to 90%, the industry is increasingly prioritizing the lifetime value of existing users. This shift is supported by the identification of distinct behavioral patterns between functional apps, which command high initial stickiness, and emotional categories like gaming, which foster long-term loyalty. By analyzing these "app-hopping" behaviors, marketers can identify high-value users who move fluidly between different app categories.
Data across various gaming genres indicates that while retention naturally declines over time, Return on Ad Spend often grows significantly as players deepen their investment in narrative and premium features. For instance, simulation games frequently see a threefold increase in ROAS by the thirtieth day of engagement. Furthermore, significant cross-genre affinities exist, such as RPG players demonstrating a 40.2% engagement rate with non-gaming applications. These insights suggest that targeting "synthesized cohorts"—clusters of interconnected apps based on shared user habits—is more effective than traditional siloed marketing.
To maximize engagement through 2025, the industry must adopt advanced technological frameworks, including deep neural networks and supervised AI, to facilitate surgical ad precision. Utilizing a "Stickiness Index" allows for the quantification of engagement patterns, enabling the deployment of dynamic product ads and automated event-based retargeting. By leveraging real-time post-install data and deep linking, advertisers can create frictionless, hyper-personalized journeys that capture users during high-intent moments. This methodology transforms brief digital interactions into sustained loyalty, ensuring that advertising spend is optimized across both gaming and non-gaming verticals globally.
- A 10% improvement in user retention can drive profit increases of up to 90%, making retention a more critical financial lever than aggressive user acquisition in a market seeing a 2.3% decline in installs.
- Simulation games demonstrate the value of long-term engagement by achieving a threefold increase in Return on Ad Spend (ROAS) by the thirtieth day of player activity.
- Targeting 'synthesized cohorts'—clusters of interconnected apps based on shared user habits—is more effective than siloed marketing, especially given that RPG players show a 40.2% engagement rate with non-gaming applications.
- The industry is shifting toward advanced technological frameworks, including deep neural networks and supervised AI, to facilitate surgical ad precision and real-time, event-based retargeting.
- Quantifying engagement through a 'Stickiness Index' allows advertisers to deploy dynamic product ads and deep linking to create frictionless, hyper-personalized user journeys through 2025.