Key insights
7 slides
The big picture
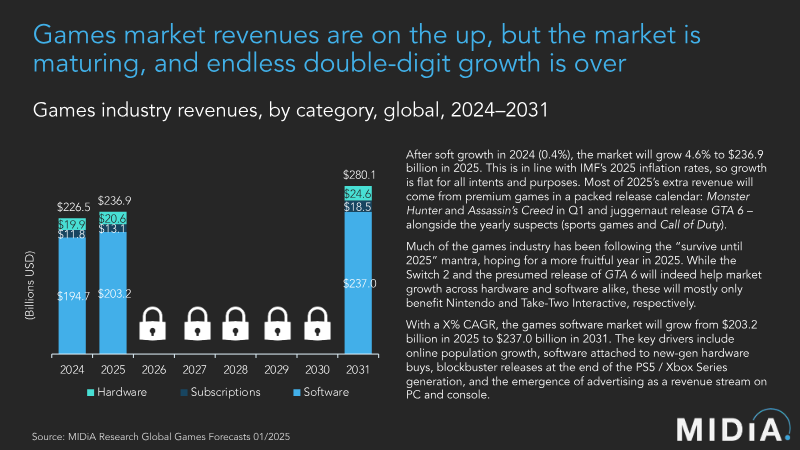
Global game revenue is projected to reach $236.9 billion in 2025.
The worldwide video-game market has entered a mature phase. Revenue is expected to climb modestly to $280.1 billion by 2031.
Player base
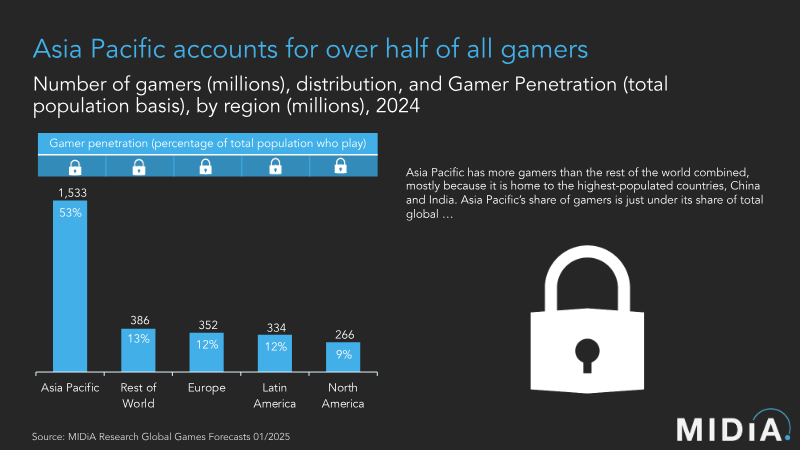
Asia-Pacific comprises roughly 53 percent of the 1.53 billion global gamers.
The region exhibits the highest penetration at about 13 percent of the regional population. Software revenues are set to grow modestly across all markets.
In-game spend
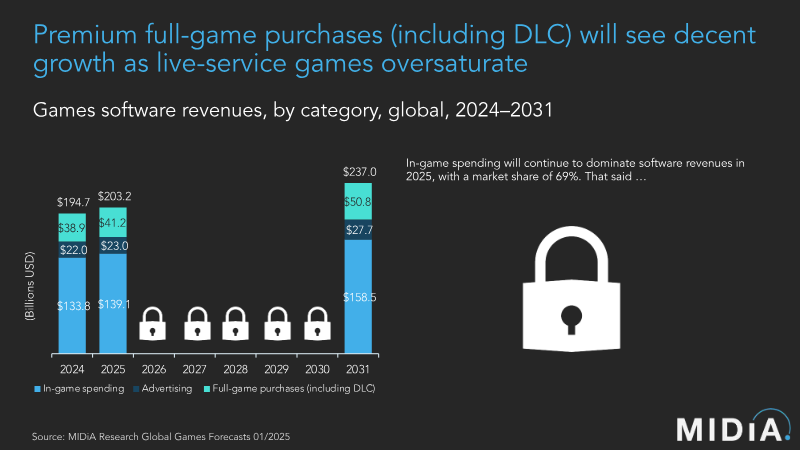
In-game spending is expected to dip slightly to 67 percent by 2031.
In-game spending currently accounts for 68 percent of software revenue. Live-service market oversaturation is eroding in-game spend.
Slight dip. In-game spending is expected to experience a slight decline to 67 percent by 2031.
Subscriptions
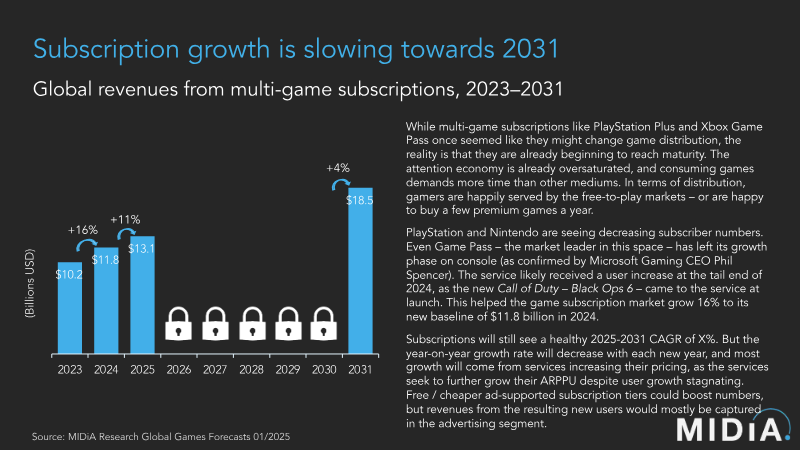
Subscription service revenue is forecast to grow from $13.1 billion to $18.5 billion.
Growth is driven primarily by price increases rather than user base expansion. User bases are saturating.
Software engine
Software sales remain the primary revenue engine for the industry.
Major premium releases support software sales, including the upcoming Grand Theft Auto installment and new Nintendo Switch titles. In-game spending is a large portion of this revenue.
Strategic focus
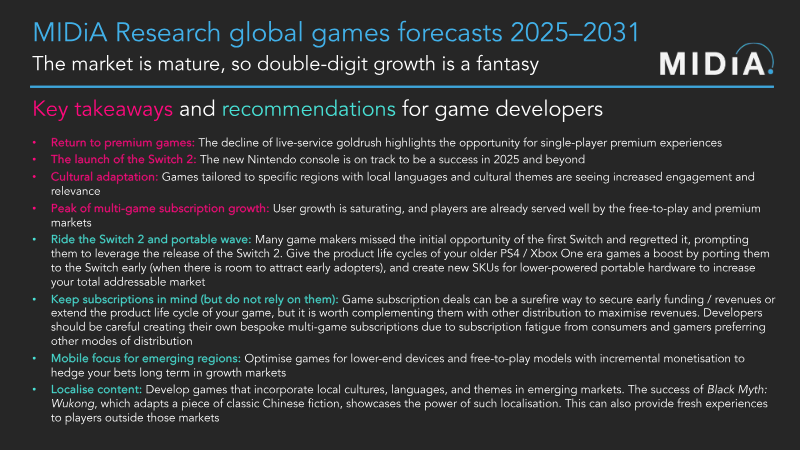
Industry strategy should shift toward a long-term focus on premium releases.
This navigates the current market maturity.
Long-term focus. Industry strategy should shift toward a long-term focus on high-quality premium releases, selective live-service investment, and cross-platform integration.
How it was built
Forecasts rely on a proprietary model combining financials, surveys, and third-party sources.
The authors note that the projections reflect their own assumptions. They carry no liability for potential losses.
Proprietary model. The forecasts rely on a proprietary model that combines company financials, survey data, and third-party sources.
1 / 7
Ask AI about this report
Comments