ReportMarvelous
Results Briefing Materials: Fiscal Year Ending March 2026, First Half
21 pages~9 min full read
Key insights
6 slides
Profit pressure
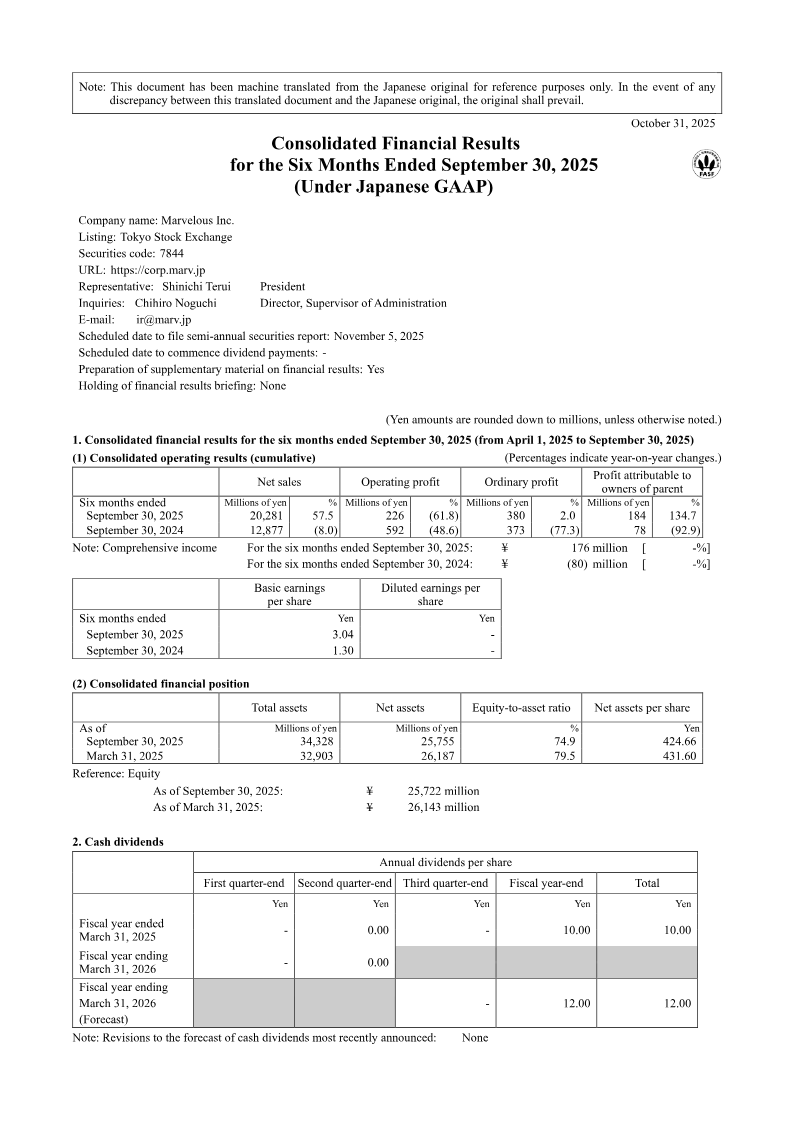
Operating profit fell 38.2% to ¥226 million on higher development costs.
Net income rose 234.7%, largely from a shift to foreign-exchange gains.
Page 4 of the report| Category | 1H FY2025 (April–September 2024) Actual | 1H FY2025 (April–September 2024) Profit ratio | 1H FY2026 (April–September 2025) Actual | 1H FY2026 (April–September 2025) Profit ratio | YoY change Amount | YoY change % |
|---|---|---|---|---|---|---|
| Net sales | 12877 | - | 20281 | - | 7404 | 157.5% |
| Cost of sales | 6588 | - | 14154 | - | 7565 | 214.8% |
| SGA expenses | 5695 | - | 5900 | - | 205 | 103.6% |
| Thereof research and development expenses | 913 | - | 651 | - | -261 | 71.4% |
| Thereof advertising expenses | 886 | - | 1550 | - | 664 | 175.0% |
| Operating profit | 592 | 4.6% | 226 | 1.1% | -366 | 38.2% |
Segment mix
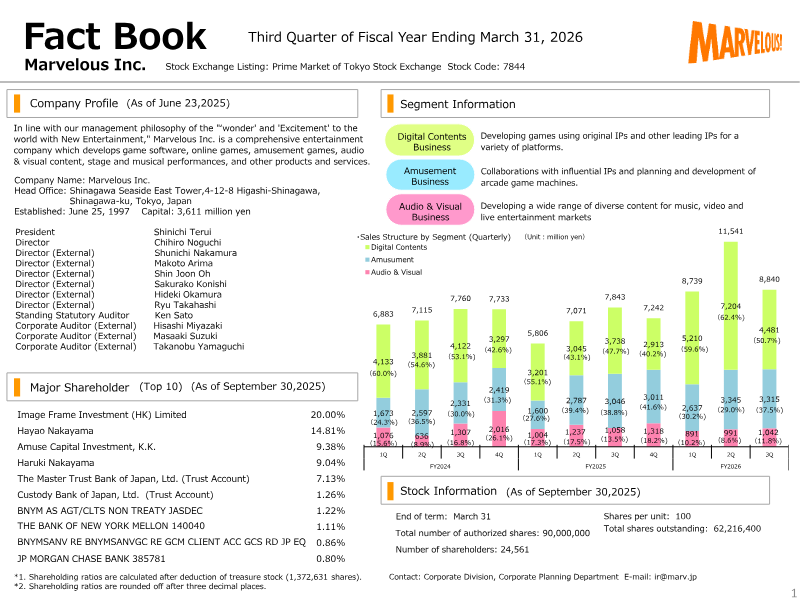
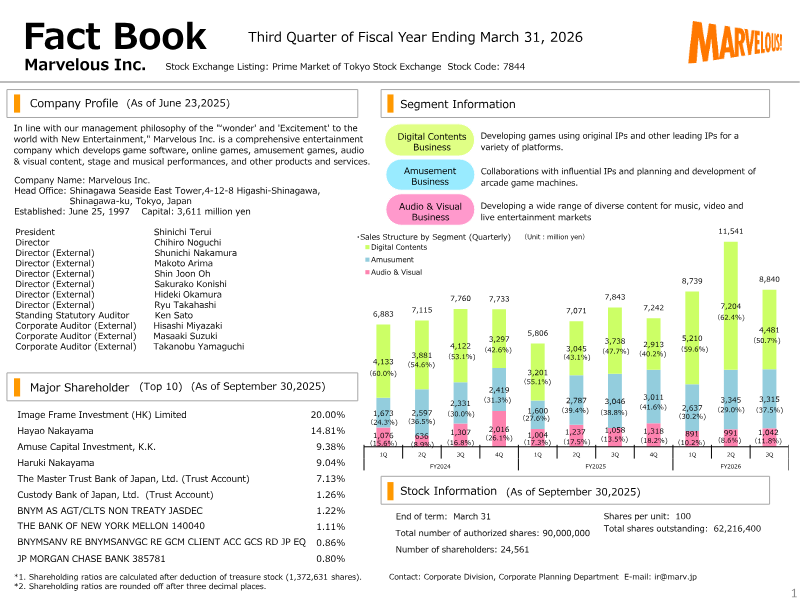
Digital Contents revenue grew 198.7% to ¥12,414 million.
Amusement Business grew 136.3% to ¥5,982 million, offsetting an 84.0% decline in Audio & Visual Business.
Page 6 of the reportFY2024 1Q1,673
FY2024 2Q2,597
FY2024 3Q2,331
FY2024 4Q2,419
FY2025 1Q1,600
FY2025 2Q2,787
FY2025 3Q3,046
FY2025 4Q3,011
Cash flow
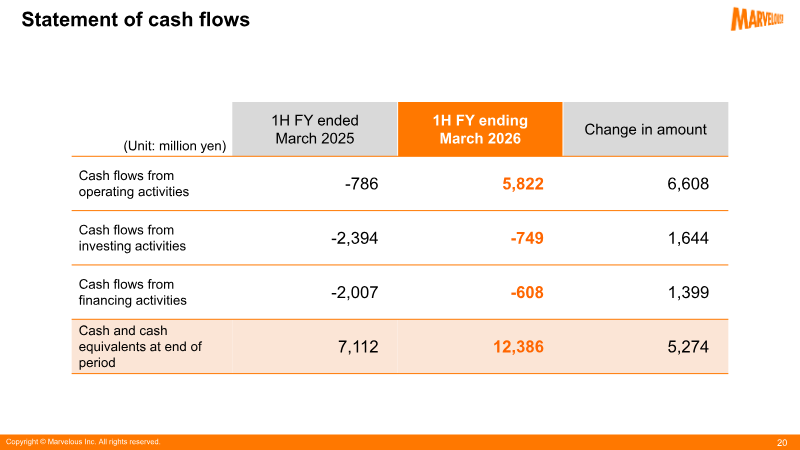
Operating cash flow shifted from negative ¥786 million to positive ¥5,822 million.
Net cash increased by ¥5,274 million to ¥12,386 million.
Forecast
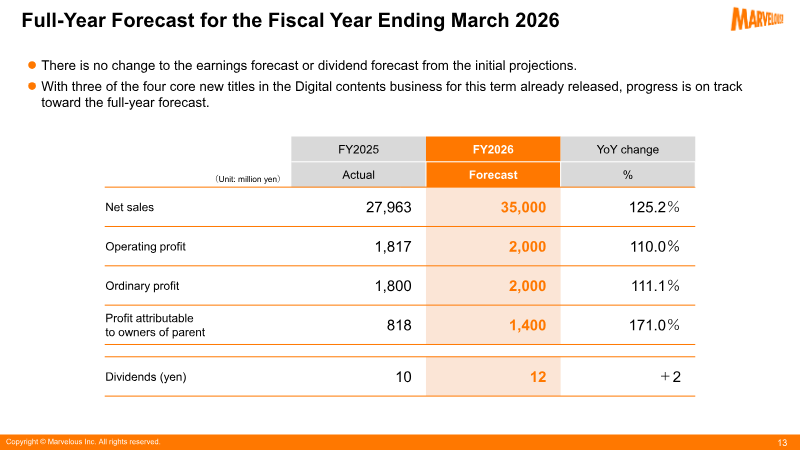
Full-year net sales are forecast at ¥35,000 million, unchanged.
Operating profit is forecast to rise 110.0% to ¥2,000 million, maintaining the initial earnings outlook.
Dividend
Management announced a dividend uplift to ¥12 per share.
The company maintained its initial earnings outlook for the remainder of the fiscal year.
Assets
Total assets rose by ¥1,424 million in the first half.
Net assets slightly declined due to higher liabilities.
| Category | End of March 2025 | End of September 2025 | Change in amount |
|---|---|---|---|
| Current assets | 22636 | 23442 | 806 |
| Non-current assets | 10266 | 10885 | 618 |
| Total assets | 32903 | 34328 | 1424 |
| Current liabilities | 6551 | 8407 | 1856 |
| Non-current liabilities | 165 | 165 | |
| Total liabilities | 6716 | 8572 | 1856 |
1 / 6
Ask AI about this report