Europe
Documents
Video Games in European Schools: Results from the Games in Schools 2023-2024 Research Project
Executive Summary – “Video Games in European Schools” (Based on the 2023‑2024 “Games in Schools” research project and the 25‑section document you provided)
| What we know | Key figures | Implications | |------------------|----------------|------------------| | Teacher attitudes & usage | • 1 474 teachers surveyed in 26 EU countries <br>• 63 % want more training <br>• Only 36 % currently use games; of those, 54 % use them regularly | There is strong demand for professional development, but adoption is still limited. | | Perceived benefits | • Boosts motivation, engagement, and inclusive learning <br>• Improves visuospatial cognition, attention, problem‑solving, creativity, collaborative skills, psychological capital (self‑efficacy, hope, resilience) <br>• Particularly helpful for low‑performing, special‑needs, and female students who play heavily | Games can be a lever for equity and 21st‑century competencies, but the impact varies by design and context. | | Barriers | • Difficulty finding age‑appropriate, curriculum‑aligned titles <br>• Limited teacher expertise & time <br>• Insufficient hardware, licences, and broadband <br>• Parental concerns (screen‑time, data‑privacy, violence) <br>• Lack of clear pedagogical frameworks & assessment tools | Overcoming these obstacles requires coordinated policy, funding, and teacher‑support structures. | | Enablers & best‑practice examples | • Belgium (Flemish) – “Education meets Games” events, strong focus‑group outcomes <br>• Italy – IVIPRO EDU, Maker Camp (Minecraft), Lega Scolastica esports league <br>• Poland – Free national rollout of This War of Mine with teacher guide <br>• Luxembourg – Dedicated “Digital Science” subject, Play Seriously handbook <br>• Sweden – Gamecamp programme (97 % transition to higher‑education pathways) | Nationally coordinated programmes that combine funding, teacher training, and curated game libraries are the most successful. | | Market context | • European video‑game market > €25 bn annually, 115 000 employees <br>• 53 % of Europeans play; ~50 % are women <br>• Industry bodies (Video Games Europe) and EU programmes (Horizon Europe, Creative Europe) are already positioning games as tools for education, inclusion, and wellbeing | A large, growing industry is ready to partner with schools, but alignment on educational goals is still needed. | | Research gaps
- While 53% of Europeans play video games and the industry exceeds €25 billion in annual revenue, only 36% of surveyed teachers currently use games in the classroom, with 63% explicitly requesting more professional training.
- Teachers who do integrate games report significant improvements in student motivation, problem-solving, and psychological capital, noting particular efficacy for special-needs, low-performing, and female students.
- The primary barriers to adoption include a lack of curriculum-aligned titles, insufficient hardware and broadband infrastructure, and parental concerns regarding screen time and data privacy.
- Successful national initiatives, such as Poland's rollout of 'This War of Mine' and Sweden's 'Gamecamp' program, demonstrate that coordinated government funding and curated game libraries are essential for effective classroom integration.
- Only 54% of the teachers who currently use games do so on a regular basis, highlighting a significant gap between initial adoption and sustained pedagogical implementation.
Videojuegos en Aulas Europeas: Resultados del Proyecto de Investigación 'Juegos en las Escuelas 2023-2024'
The study evaluates how video‑games are being integrated into European primary and secondary classrooms and argues that, while games hold clear potential to enhance motivation, cognition and 21st‑century competencies, systematic support is still required to translate research into widespread practice. A 2023‑2024 survey of 1,474 teachers across 26 European nations reveals that 36 % already employ games in lessons, with more than half of those using them regularly and favouring puzzle‑ or narrative‑driven titles. The principal barriers reported are the difficulty of locating age‑appropriate, curriculum‑aligned and GDPR‑compliant games (45 %) and technical constraints such as insufficient hardware or internet access (42 %). Compared with a 2009 baseline, teachers now rate their digital competence higher (7.7 / 10), display more positive attitudes, and receive stronger backing from school leadership, yet further investment in training, infrastructure and coordinated policy is deemed essential.
A comprehensive taxonomy distinguishes action, adventure, RPG, simulation, sport and hybrid genres, and separates commercial‑off‑the‑shelf titles, serious games, gamified tools and game‑based learning approaches. Empirical work from 2009‑2024 consistently shows modest gains in intrinsic motivation, STEM and language achievement, spatial and attentional skills, and collaborative behaviours when games are thoughtfully aligned with learning objectives. Nonetheless, effects on higher‑order cognition remain uneven, and the literature suffers from heterogeneous definitions, limited longitudinal data and a scarcity of rigorous experimental designs.
Country‑level case studies illustrate both promise and obstacles. Inclusive esports programmes in Italy, digital‑science curricula in Luxembourg, and language‑focused game pilots in Poland and Romania demonstrate measurable improvements in communication, critical thinking and resilience, while chronic under‑funding, outdated hardware, parental scepticism, gender gaps and rigid curricula impede broader adoption. Across the region, teachers cite insufficient professional development, lack of time and compensation, and uncertainty about content safety as persistent challenges.
The overarching recommendation is a coordinated European framework that provides an ethically vetted, GDPR‑compliant repository of educational games, systematic teacher training, robust infrastructure funding, and longitudinal research to validate cognitive and health outcomes. By aligning industry partnerships, policy incentives and evidence‑based pedagogy, the initiative seeks to close the gap between game research and classroom practice, fostering inclusive, engaging learning environments throughout Europe.
- 36% of the 1,474 European teachers surveyed currently integrate video games into their lessons, with over half of those users employing them regularly.
- The primary barriers to adoption are the difficulty of finding age-appropriate, curriculum-aligned, and GDPR-compliant games (45%) and technical limitations such as inadequate hardware or internet access (42%).
- Teacher digital competence has risen to a self-reported 7.7/10 since the 2009 baseline, supported by more positive attitudes and increased backing from school leadership.
- Empirical evidence from 2009–2024 confirms that games, when aligned with learning objectives, produce modest gains in intrinsic motivation, STEM and language achievement, and collaborative behaviors.
- Despite positive trends, the field lacks rigorous longitudinal data and suffers from inconsistent definitions, making the effects of gaming on higher-order cognition remain uneven.
Game Development Studie 2024: Die wirtschaftliche Bedeutung der österreichischen Spieleentwicklungsbranche, ihre Dynamiken und Einflüsse auf die Gesamtwirtschaft
The study evaluates the state of Austria’s game‑development sector in the first half of 2024, tracing its evolution since a comparable survey in 2018 and quantifying its economic contribution. By updating the Institute of Industrial Research’s developer database to 149 active firms and collecting completed questionnaires from 80 companies (a 53.7 % response rate), the analysis combines firm‑level survey data with input‑output modelling to assess employment, turnover and multiplier effects.
The industry has expanded rapidly: the number of firms rose 71.3 % to 149, with 81 % classified as micro‑enterprises (≤9 employees) and 54 % located in Vienna. Turnover reached €92.8 million in 2023—a nominal increase of 285 % since 2017—and employment grew from 474 jobs in 2017 to 1 080 in 2024 (128 % rise). Direct, indirect and induced effects generate a total of €188.7 million in revenue and support roughly 2 260 jobs across the Austrian economy, a multiplier of about 2.0 for both revenue and employment.
Product portfolios remain dominated by entertainment titles (85 % of respondents), while serious and educational games have gained prominence (29 % and 30 %). Development focuses on PC and mobile platforms, with Unity used by 55 % of firms. The workforce is young and highly educated—nearly half are aged 25‑34 and 80 % hold tertiary degrees. Export orientation is strong, 82 % of firms sell to the EU‑27/UK and substantial shares reach the Americas and Asia. Financing relies chiefly on internal funds (92 % deem it very important); public subsidies rank second (62 %). One‑third of firms applied for public funding in the past two years, achieving a 65 % success rate.
Looking ahead, respondents anticipate a slowdown in growth; projections suggest 2029 revenues of €149 million and employment of about 1 540, still representing robust expansion. Nevertheless, the sector rates Austria’s location policy poorly, calling for stronger governmental support, clearer financing mechanisms and improved tax conditions
- Austria’s game development sector has experienced rapid growth since 2017, with turnover increasing 285% to €92.8 million in 2023 and employment rising 128% to 1,080 jobs by 2024.
- The industry generates a total economic impact of €188.7 million in revenue and supports approximately 2,260 jobs across the Austrian economy, reflecting a multiplier effect of 2.0.
- The sector consists of 149 active firms, 81% of which are micro-enterprises with nine or fewer employees, and 54% are concentrated in Vienna.
- Development is highly export-oriented, with 82% of firms selling to the EU-27 and UK markets, while financing remains heavily reliant on internal funds (92%) rather than external investment.
- While the workforce is highly educated—with 80% holding tertiary degrees—the industry anticipates a growth slowdown, projecting revenues of €149 million and 1,540 jobs by 2029.
How to Master Europe’s Digital Infrastructure Needs?
Video Games Europe argues that Europe’s digital infrastructure policy should reinforce, rather than reshape, the existing market dynamics that underpin the continent’s thriving video‑game ecosystem. Representing roughly 110 000 employees and a €24.5 billion industry in which 53 percent of Europeans play, the association stresses that the sector’s growth is driven by digital distribution, which already reduces the environmental burden of physical media and, in many cases, relies on cloud delivery to limit data transfer. Typical online gameplay consumes between 60 and 80 megabytes per hour, with even the most data‑intensive titles rarely exceeding 250–300 megabytes, a fraction of the traffic generated by video streaming services.
The response highlights that network operators successfully managed the surge in traffic during the COVID‑19 lockdowns and that game publishers have collaborated with ISPs and content‑delivery networks to smooth peak loads through measures such as off‑peak download scheduling. It refutes claims that content providers “free‑ride” on ISP infrastructure, noting that publishers already pay for enhanced upload capacity and invest in their own CDN and data‑centre assets. Consequently, the relationship between content and application providers and ISPs is portrayed as symbiotic, fostering competition and consumer choice.
Against proposals to impose network fees or extend the European Electronic Communications Code to cloud services, the association warns that such pre‑emptive regulation could undermine net neutrality, increase consumer prices, and jeopardise Europe’s digital competitiveness. It calls for regulatory stability to protect investment security and urges that any infrastructure deployment be guided by concrete market demand rather than aspirational targets. The position draws on industry data, BEREC assessments of network resilience, and the sector’s own mitigation practices, concluding that preserving the current regulatory framework will best support sustainable growth and innovation across Europe’s digital economy.
- Video Games Europe opposes new network fees or expanded regulation of cloud services, arguing these measures would threaten net neutrality, increase consumer costs, and damage European digital competitiveness.
- The European video game industry generates €24.5 billion in annual revenue and employs approximately 110,000 people, with 53 percent of the European population participating in gaming.
- Gaming traffic is significantly lower than video streaming, with typical online gameplay consuming 60–80 megabytes per hour and high-intensity titles rarely exceeding 300 megabytes per hour.
- Game publishers refute 'free-riding' allegations by noting they already invest in their own data centers and content-delivery networks (CDNs) while paying for enhanced upload capacity.
- The industry maintains that existing market dynamics are sufficient, citing the successful management of COVID-19 traffic surges and ongoing collaboration with ISPs to schedule downloads during off-peak hours.
Children’s In-Game Spending 2024
Ipsos’ fifth edition of the In‑Game Spending by Children and Parent Supervision study tracks how European families manage micro‑transactions in video games, focusing on trends from 2018 through 2024. The research aims to gauge the prevalence of child‑initiated spending, the amount of money involved, and the supervisory mechanisms parents employ. The 2024 survey covered the United Kingdom, France, Germany, Spain and Italy, sampling 2,772 adults with children who play games and 10,998 gamers aged 11‑64, using quota‑based online panels weighted to national populations.
Three‑quarters of parents report that their children do not purchase in‑game extras, a proportion that has remained stable since 2020. Among the 26 % who do spend, average monthly outlays fell to €31, down €8 from the previous year, with 73 % of spenders allocating €1‑20 per month. Gameplay‑impacting items such as new weapons or powers attract the most expenditure (38 %), while decorative cosmetics account for 30 % and loot‑box‑type rewards remain the least popular at 21 %. Parental oversight is high: 95 % of spending households have an agreement with their child, and 63 % maintain explicit rules, either requiring permission (49 %) or setting limits (27 %). Permission‑based agreements and two‑factor authentication have risen year‑on‑year, while a minority (5 %) admit to monitoring nothing.
Among all gamers surveyed, only 11 % have ever bought real‑money in‑game currency and 4 % have purchased loot boxes, figures that have shown little change over
- The majority of children (74%) do not make in-game purchases, a stability trend maintained since 2020.
- Among the 26% of children who do spend money in-game, the average monthly expenditure dropped to €31, with 73% of these spenders limiting their costs to €20 or less per month.
- Gameplay-impacting items like weapons or powers are the primary drivers of spending (38%), followed by decorative cosmetics (30%) and loot-box rewards (21%).
- Parental oversight is robust, with 95% of spending households having established agreements and 63% enforcing explicit rules such as mandatory permission (49%) or spending caps (27%).
- Only 11% of all surveyed gamers have purchased real-money in-game currency, and only 4% have purchased loot boxes, with both figures remaining largely stagnant.
Children’s In-Game Spending: Europe
This research analyzes trends in children’s in-game spending and parental oversight across major European markets, including Great Britain, France, Germany, Spain, and Italy. Based on an Ipsos survey conducted between February and April 2024, the study draws on responses from 2,772 parents of children who play video games, as well as a broader sample of nearly 11,000 players aged 11 to 64. The primary thesis is that while in-game monetization is a known element of modern gaming, the vast majority of children do not spend money on extras, and those who do are subject to high levels of parental monitoring and declining average expenditure.
Findings indicate that 76% of parents claim their children do not spend money on in-game extras, a figure that has remained stable since 2020. Among the minority who do spend, the average monthly expenditure dropped significantly from €39 in 2023 to €31 in 2024. The most common purchases are items that impact gameplay, such as new weapons or powers (38%), followed by cosmetic items (30%). Conversely, unknown rewards like loot boxes are the least popular category, with only 21% of spending children engaging with them. Among the general player population aged 11 to 64, only 11% have spent real money on in-game currency and only 4% on loot boxes.
Parental supervision remains a dominant factor in managing these transactions. Approximately 95% of parents whose children spend money in-game have an established agreement regarding expenditure. These agreements are often explicit, with 49% of children required to ask for permission and 27% operating under strict spending limits. The use of technical controls, such as two-factor authentication and spending caps, has seen a year-on-year increase, suggesting that parents are becoming more proactive in utilizing platform tools to regulate digital consumption.
- 76% of children do not spend money on in-game extras, a figure that has remained stable since 2020.
- Average monthly in-game spending among children who do make purchases dropped from €39 in 2023 to €31 in 2024.
- 95% of parents whose children spend money in-game have established formal agreements, with 49% requiring children to ask for permission and 27% enforcing strict spending limits.
- Gameplay-impacting items like weapons or powers are the most common purchases (38%), while loot boxes are the least popular, utilized by only 21% of spending children.
- Parental use of technical controls, such as two-factor authentication and spending caps, has increased year-on-year as a method for regulating digital consumption.
Financial Results Q1 2024
PCF Group S.A. reported its financial results for the first quarter of 2024, highlighting a period of significant revenue growth and improved profitability. The primary thesis of the financial update is the successful execution of the group’s multi-project strategy, supported by both work-for-hire contracts and the development of original intellectual property. Geographically, the group maintains a strong international presence with major studios in Warsaw, Rzeszów, Montreal, and Newcastle, supported by a total workforce of 763 people as of March 31, 2024.
Financial performance in Q1 2024 showed a substantial increase in revenue to 56.9 million PLN, compared to 34.9 million PLN in the same period the previous year. This growth was driven by the release of Bulletstorm VR and ongoing work on Project Maverick. EBITDA rose to 11.0 million PLN, a significant improvement over the 3.0 million PLN recorded in Q1 2023. Net profit also turned positive, reaching 11.0 million PLN compared to a net loss of 0.9 million PLN in the prior year. Management attributed this increased profitability to a high revenue base and a disciplined cost approach, despite increased spending on the publishing team.
The production pipeline remains robust across several segments. In the AAA category, Projects Bifrost and Victoria are progressing according to schedule under a self-publishing model, both having received internal greenlights for 2025-2026 release windows. The VR segment, managed through InCuvo, continues development on Green Hell VR updates and the upcoming Project Bison. Additionally, work-for-hire projects remain stable, with Project Maverick reaching its target developer headcount and negotiations continuing with Square Enix regarding other collaborations. The balance sheet remains healthy, with 138.6 million PLN in cash and bonds and total assets valued at 505.1 million PLN.
- PCF Group achieved a net profit of 11.0 million PLN in Q1 2024, a significant turnaround from the 0.9 million PLN net loss recorded in Q1 2023.
- Quarterly revenue grew to 56.9 million PLN, up from 34.9 million PLN in the prior year, driven by the release of Bulletstorm VR and progress on Project Maverick.
- EBITDA rose to 11.0 million PLN, compared to 3.0 million PLN in Q1 2023, reflecting a disciplined cost approach alongside higher revenue.
- The company maintains a strong liquidity position with 138.6 million PLN in cash and bonds and total assets valued at 505.1 million PLN.
- Self-published AAA titles Projects Bifrost and Victoria are on track for release windows between 2025 and 2026.
Transparent and Fair Purchases of In-Game Content
The initiative seeks to ensure that European players can make informed, transparent decisions when purchasing in‑game content, while safeguarding minors from unintended spending. It builds on the PEGI Age Rating System, now operating in forty countries, and introduces a three‑part policy framework: the PEGI Code of Conduct for purchasable content, additional safeguards focused on younger players, and coordinated information campaigns supported by trusted data.
Statistical evidence shows that 20.8 % of all games receiving a PEGI rating include in‑game purchase options, with 3 % offering paid random items such as loot boxes. An annual Ipsos survey commissioned by Video Games Europe from 2018 to 2024, covering the five largest European consumer‑spend markets, reveals that parental supervision remains high—95 % of Swedish parents monitor spending—and that 76 % of parents report their children do not make in‑game purchases, a figure stable since 2020. Average spend among permitted purchasers fell 21 % in the Netherlands since 2023, and only 11 % of players aged 11‑64 have bought in‑game currency across the surveyed regions.
The PEGI Code of Conduct obliges signatories to display a dedicated icon at the point of purchase, provide receipts, and clearly state the real‑world cost of any virtual currency. For paid random items, it mandates visible notices, confirms that such purchases are optional, and requires transparent probability disclosures in line with data‑protection laws. Additional safeguards include parental tools that default to zero spending for child accounts, separation of transaction interfaces from gameplay, and refund mechanisms for unauthorized purchases. Policies also prohibit the use of in‑game assets for illegal gambling or unauthorised trading, with enforcement powers vested in the PEGI Enforcement Committee.
Information campaigns, such as the Pan‑European “Seize the Controls” effort, aim to raise awareness of these tools and safeguards in national languages, leveraging partnerships with Safer Internet Centres and other stakeholders. The industry welcomes further support from EU institutions and member states to amplify outreach and reinforce responsible spending practices across the European gaming ecosystem.
- The PEGI Code of Conduct mandates that signatories display purchase icons, provide receipts, and disclose real-world costs for virtual currency, while requiring transparent probability disclosures for paid random items like loot boxes.
- Only 20.8% of PEGI-rated games include in-game purchase options, with just 3% of all rated games offering paid random items.
- Parental supervision remains robust, with 76% of parents reporting their children do not make in-game purchases, a figure that has remained stable since 2020.
- Industry safeguards now include parental tools that default child accounts to zero spending, the separation of transaction interfaces from gameplay, and established refund mechanisms for unauthorized purchases.
- Data from 2018–2024 indicates that only 11% of players aged 11–64 have purchased in-game currency across the five largest European markets.
European Key Facts 2024: Video Games
The European video games industry represents a high-growth strategic sector that generated €26.8 billion in revenue in 2024, with digital channels accounting for 90% of all sales. This robust economic activity supports over 116,000 skilled professionals across 6,000 studios and serves a diverse player base comprising 54% of the European population. Mobile gaming remains the dominant platform, utilized by 71% of the region's 127 million players. To manage this vast ecosystem, the industry relies on the PEGI age-rating system across 40 countries, ensuring a standardized approach to consumer protection and responsible gameplay.
Central to the industry’s operational integrity is a rigorous regulatory framework focused on monetization transparency and online safety. Updated standards mandate the disclosure of loot box probabilities and strictly prohibit the exchange of virtual items for real-world currency. Safety protocols are reinforced by comprehensive parental controls, currently adopted by 67% of parents, alongside mandatory age-verification tools and reporting mechanisms for harmful content. Compliance is maintained through a tiered enforcement system, where severe violations of age-rating or safety standards can result in financial penalties of up to €500,000.
Beyond economic and regulatory concerns, the sector is increasingly defined by its commitment to social and environmental responsibility. Major regional initiatives across Spain, the United Kingdom, and Germany are driving diversity and inclusion through measurable policy changes and scholarships aimed at increasing female participation. Simultaneously, the industry is pursuing aggressive decarbonization through the Playing for the Planet Alliance and voluntary agreements that have already yielded significant energy savings in hardware manufacturing. These efforts are complemented by the integration of environmental themes into gameplay and the development of carbon calculators to assist studios in achieving long-term sustainability goals.
- The European video games industry generated €26.8 billion in 2024, with digital channels accounting for 90% of total sales.
- The sector supports 116,000 professionals across 6,000 studios and serves 127 million players, representing 54% of the European population.
- Mobile gaming is the primary platform in the region, utilized by 71% of the total player base.
- Regulatory frameworks now mandate the disclosure of loot box probabilities and prohibit the exchange of virtual items for real-world currency, with non-compliance penalties reaching up to €500,000.
- Consumer safety is supported by parental controls adopted by 67% of parents and the standardized PEGI age-rating system operating across 40 countries.
European Key Facts 2023: Video Games Industry
The European video games industry is a significant cultural and economic driver, characterized by steady growth and a commitment to responsible gameplay. In 2023, the European market reached €25.7 billion in revenue, a 5% year-on-year increase. The sector employs approximately 115,000 people across Europe, with 90,000 based in the EU. This growth is supported by a diverse player base; 53% of the European population aged 6-64 plays video games, with an average player age of 31.4 years. Notably, 75% of players are adults, and women make up 43.5% of the total gaming population.
The industry emphasizes a robust framework for minor protection and consumer transparency through the Pan European Game Information (PEGI) system. Celebrating its 20th anniversary, PEGI has issued nearly 40,000 age rating licenses across 40 countries. Awareness of these labels is high, with 79% of parents whose children play games recognizing the system. Furthermore, the industry actively promotes diversity and inclusion through various regional initiatives and addresses environmental sustainability via the Games Consoles Voluntary Agreement and the Playing for the Planet Alliance.
To maintain global competitiveness, the industry advocates for a strategic EU policy framework. Key priorities include recognizing video games as unique creative works distinct from the audiovisual sector, addressing the digital skills gap through education and STEAM programs, and maintaining a fair regulatory environment that supports small and medium-sized enterprises. The data for these findings is derived from GameTrack and Games Sales Data (GSD) surveys conducted by Ipsos, involving a sample of 60,000 individuals across major European markets to ensure national representation.
- The European video games industry generated €25.7 billion in revenue in 2023, representing a 5% year-on-year growth.
- The sector employs 115,000 people across Europe, with 90,000 of those roles based within the EU.
- Video games reach 53% of the European population aged 6–64, with an average player age of 31.4 years, 75% adult representation, and 43.5% female participation.
- The PEGI age-rating system has issued nearly 40,000 licenses over 20 years, with 79% of parents recognizing the labels.
- Industry advocacy focuses on securing a policy framework that classifies video games as unique creative works distinct from the audiovisual sector.
Netherlands Games Monitor 2024
AUTHORS SPECIAL THANKS TO Manuel Kerssemakers (Abbey Christel van Grinsven APPLIED Games) Arjan Terpstra Bowie Derwort (Game Tailors) Laurens Rutten (CoolGames Matthijs Dierckx Michaël Bas (&ranj) & Dutch Games Association) Roger ter Heide (Improvive) Tuur Hendrikx (Sonic Picnic) RESEARCH CHAPTER 1 ...
- The Dutch games industry employed 4,291 people by the end of 2023, a decline of 269 persons compared to 2021, with employment decreasing by 3% per year between 2021 and 2023, though revenue increased by an average annual rate of 10.5% to €763 million.
- The percentage of female workers in the Dutch games industry is rising, reaching 23.2% currently, aligning with broader European and North American industry averages.
- Applied games studios are adopting generative AI faster than entertainment studios, using or testing it for localization, dialogue, training content, and audio, with clients open to custom AI-enabled solutions, while entertainment studios are more hesitant due to potential player backlash.
- The Greater Amsterdam urban region remains the primary hub for the Dutch games industry, offering nearly 1,800 jobs by the end of 2023, and notably continued to grow employment between 2021 and 2023 despite an overall industry decline.
- There are 41 game education programs in the Netherlands, similar to 2022, primarily focusing on programming or game art, with a majority of courses having around 40% of students stating they will never use AI for finished assets.
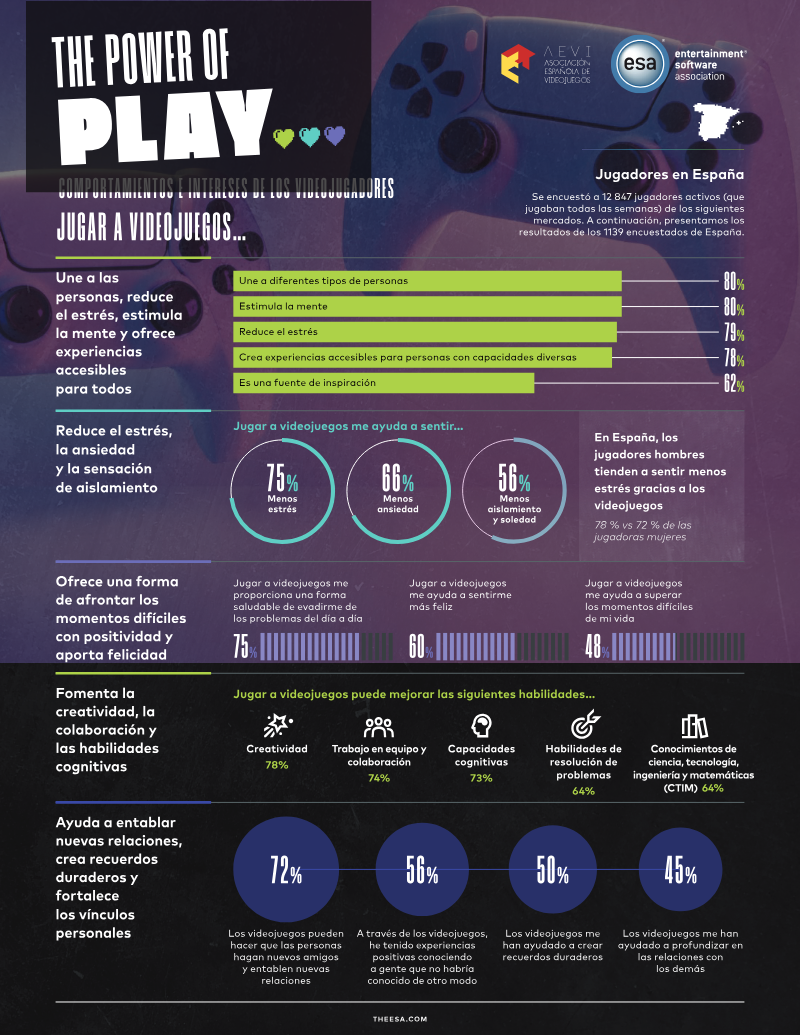
The Power of Play: España
Summary of “The Power of Play: España” (Survey of Spanish Video‑Game Players)
1. Scope & Sample Population surveyed: 12 847 active gamers (play ≥ once a week) across several markets. Spanish subsample: 1 139 respondents (men + women) who answered the questionnaire.
2. Demographic Profile
| Age group (years) | % of Spanish respondents | |-------------------|---------------------------| | 16‑18 | 8 % (men) / 41 % (women) | | 19‑24 | 49 % (men) / 28 % (women) | | 25‑34 | 28 % (men) / 28 % (women) | | 35‑44 | – | | 45‑54 | – | | 55‑64 | – | | 65+ | – |
\The table in the original document mixes gender‑specific percentages; the numbers above reflect the most clearly reported figures.
Gender split (overall): Roughly equal, with a slight male majority in the 19‑24 bracket. Play mode: 8 out of 10 male gamers (≈ 80 %) report playing with other players online. For women, solo play is still the most common, but a sizable minority also play online or in person.
3. Primary Motivations for Playing
| Motivation | % of respondents (overall) | |------------|----------------------------| | Fun / Entertainment | 85 % | | Stress reduction / relaxation | 78 % (men) – 75 % (women) | | Social connection (meeting new people, making friends) | 62 % (men) – 55 % (women) | | Escapism / coping with daily problems | 28 % (men) – 48 % (women) | | Feeling happier / more positive | 75 % (men) – 60 % (women) | | Creating lasting memories | 45 % (men) – 35 % (women) |
Note: The percentages are drawn from multiple overlapping questions (e.g., “Jugar a videojuegos me ayuda a sentir…”, “Reduce el estrés, la ansiedad, el aislamiento”). The highest‑scoring items are fun, stress relief, and social interaction.
4. Perceived Benefits
4.1 Psychological & Emotional Stress & anxiety: 78 % of men and 75 % of women say gaming helps them feel less stressed and less anxious. Isolation: 78 % of men and 72 % of women report a reduction in feelings of loneliness.
- Gaming is primarily used for emotional regulation in Spain, with 78% of men and 75% of women reporting that it effectively reduces stress and anxiety.
- Social connection is a major driver for the Spanish gaming population, with 62% of men and 55% of women citing it as a primary motivation for play.
- Online multiplayer engagement is significantly higher among men, with approximately 80% reporting they play with others online, whereas women show a stronger preference for solo play.
- Gaming serves as a vital tool for combating loneliness, as 78% of men and 72% of women report that playing reduces their feelings of isolation.
- The Spanish gaming demographic is heavily concentrated in younger age brackets, with 49% of male players and 28% of female players falling within the 19–24 age range.