Report22 pages
Global Video Game Investment Activity Report Q1 2021
The first quarter of 2021 marked a historic surge in global video game industry investments, signaling a potential record-breaking year. Total deal value for closed transactions reached $25 billion across 249 deals, representing a twofold increase compared to the first half of 2020. When including announced but unclosed transactions, the total deal value for the quarter climbed to $39 billion. This growth was observed across all primary investment frontiers, including private placements, public offerings, and mergers and acquisitions (M&A).
M&A activity served as the primary engine for this expansion, accounting for $14.3 billion in closed deal value, a nearly sixfold increase year-over-year. This segment was dominated by high-profile "mega-deals," most notably Microsoft’s $7.5 billion acquisition of ZeniMax Media and ByteDance’s $4 billion acquisition of Moonton. Public offerings also saw record activity, generating $8.3 billion in value—a 29-fold increase over the previous year—driven by a tripling of initial public offerings and the rising popularity of Special Purpose Acquisition Companies (SPACs). Private investments reached a segment record of $2.6 billion, with late-stage rounds for companies like Roblox and Dapper Labs accounting for 73% of that total.
Strategic and venture capital activity remained highly concentrated among top-tier players. Tencent maintained its leadership in deal volume, closing 35 transactions with a focus on PC and console developers. Meanwhile, the top five strategic investors—Tencent, Microsoft, Embracer Group, Electronic Arts, and ByteDance—contributed over half of the total announced deal value. Early-stage venture capital also grew significantly, with a 120% increase in capital raised by game developers. Geographically and by segment, mobile and multiplatform studios remained the most attractive targets for investors, while PC and console segments drove the majority of M&A value. This analysis is based on tracked closed transactions in the global video game industry, excluding gambling and betting, utilizing data from public media, business partners, and S&P Capital IQ.
- Global video game investment reached $25 billion in closed deal value during Q1 2021, a twofold increase over the first half of 2020, with total announced deal value hitting $39 billion.
- M&A activity was the primary growth driver, totaling $14.3 billion in closed deals—a nearly sixfold year-over-year increase—led by Microsoft’s $7.5 billion ZeniMax acquisition and ByteDance’s $4 billion Moonton acquisition.
- Public offerings generated $8.3 billion in value, representing a 29-fold increase over the previous year, fueled by a tripling of IPOs and the rise of SPACs.
- Tencent, Microsoft, Embracer Group, Electronic Arts, and ByteDance dominated the landscape, collectively contributing over 50% of the total announced deal value.
- Private investments hit a record $2.6 billion, with 73% of that capital directed toward late-stage rounds for companies such as Roblox and Dapper Labs.
+1
InvestGameJan 2021
Report222 pages
Turkey Game Market 2021 Report
The Turkish gaming market experienced a transformative period of growth and institutionalization in 2021, reaching a total market volume of $1.2 billion. Despite global challenges such as hardware shortages and pandemic-related delays in AAA titles, the local ecosystem expanded to include over 42 million active players. This growth was primarily catalyzed by the mobile segment, which generated $620 million in revenue and solidified Turkey’s position as a global leader in the hyper-casual genre. The year was further defined by record-breaking financial activity, with $266 million invested across 54 startups and the emergence of Dream Games as a new industry "unicorn."
Strategically, the market is shifting toward a "gaming-focused entertainment" model, characterized by the rapid adoption of Web3 technologies, including blockchain, NFTs, and Play-to-Earn (P2E) frameworks. While mobile gaming remains the dominant force, there is a burgeoning esports ecosystem supported by approximately 6 million followers and a national federation overseeing 165 licensed clubs. Turkey’s selection as the host for the Global Esports Games 2022 underscores its rising international profile. However, industry experts note a strategic need to diversify beyond mobile platforms into PC and console development to ensure long-term sustainability.
The regional landscape reveals Turkey as the primary gaming powerhouse in the Middle East, outperforming neighboring markets in both revenue and player engagement. Success for international entrants remains contingent on high-quality localization and cultural adaptation, given the country's low English proficiency and unique consumer preferences for competitive genres and specific musical influences. As the sector transitions into 2022, the focus remains on bridging the talent gap through specialized academic programs and leveraging the return of large-scale physical exhibitions to maintain momentum in the evolving Metaverse and digital advertising spaces.
- The Turkish gaming market reached a total volume of $1.2 billion in 2021, supported by a player base of 42 million active users.
- Mobile gaming generated $620 million in revenue, cementing Turkey's status as a global leader in the hyper-casual genre.
- Financial activity hit record levels in 2021 with $266 million invested across 54 startups, highlighted by the emergence of Dream Games as a unicorn.
- The esports ecosystem is growing rapidly, featuring 6 million followers and 165 licensed clubs overseen by a national federation.
- Turkey is the primary gaming powerhouse in the Middle East, though experts advise diversifying into PC and console development for long-term sustainability.
+2
Gaming in TurkeyJan 2021
Report11 pages
Q1‑Q3 2020: Recap of the Investment Activity in the Video Game Market
The first three quarters of 2020 saw the global gaming industry navigate significant volatility caused by the COVID-19 pandemic, ultimately demonstrating strong resilience and a rapid recovery in deal activity. While private investments dropped sharply in May 2020, the market rebounded by July, closing 100 transactions worth approximately $2.78 billion. This investment activity was heavily concentrated at the later stages, with American companies like Epic Games, Roblox, and Scopely accounting for over 90% of total capital value. Conversely, early-stage venture capital remained more geographically diverse, with U.S. startups representing only 30% of those funds.
Mergers and acquisitions remained robust throughout the period, largely unaffected by macroeconomic instability. The mobile segment led in volume with 41 deals totaling $4.6 billion, while the PC and console segment reached $10.5 billion in value, driven primarily by Microsoft’s $7.5 billion acquisition of ZeniMax. Strategic buyers such as Tencent, Embracer Group, and Stillfront Group continued to consolidate the market. Public offerings followed a similar recovery arc; after a near-total halt in the first half of the year, the market reopened in June with significant IPOs from Asian companies and capital raises by Western firms to fund future acquisitions.
The landscape of financial backers was led by specialized venture funds like Makers Fund, Play Ventures, and BITKRAFT Ventures in terms of deal volume, while KKR and Andreessen Horowitz dominated in total value through large-scale, later-stage investments. Strategic activity was characterized by "mastodons" like Microsoft and Zynga, alongside aggressive consolidation efforts by European holding companies. Analysts expect continued momentum into 2021, driven by the need for content on subscription platforms and the scaling of major mobile publishers ahead of potential public listings.
- The gaming industry demonstrated strong resilience in 2020, with a July rebound leading to 100 transactions worth approximately $2.78 billion in private investment.
- M&A activity was significant, with the PC and console segment reaching $10.5 billion in value, largely driven by Microsoft’s $7.5 billion acquisition of ZeniMax.
- The mobile gaming segment led in deal volume with 41 transactions totaling $4.6 billion, supported by ongoing consolidation from strategic buyers like Tencent, Embracer Group, and Stillfront Group.
- Late-stage private investment was highly concentrated, with American companies such as Epic Games, Roblox, and Scopely accounting for over 90% of the total capital value.
- Early-stage venture capital remained geographically diverse, with U.S. startups representing only 30% of those specific funds.
+1
InvestGameSept 2020
Report82 pages
Annual Report 2020
Games Workshop achieved record-breaking financial results for the 2019/20 fiscal year, demonstrating significant resilience despite the operational disruptions caused by the COVID-19 pandemic. Annual revenue rose 5.1% to £269.7 million, while profit before tax reached £89.4 million. This performance marks the fourth consecutive year of record growth, driven primarily by a robust trade segment—which now accounts for 52% of total revenue—and a substantial increase in royalty income from licensing agreements in the video game and media sectors.
The company’s strategic focus remained on the global expansion of its Warhammer intellectual property and the modernization of its industrial infrastructure. Significant capital investments totaling £18 million were directed toward production and logistics expansions in Nottingham and North America, alongside the implementation of a new ERP system. While physical retail sales declined by 11% due to pandemic-related store closures, digital engagement and online sales saw marked growth. The company also successfully navigated the transition to IFRS 16 accounting standards, which brought £32.1 million in lease liabilities onto the balance sheet.
Geographically, North America remains the company's largest market, contributing £104.8 million to total revenue. Despite the economic uncertainties of the pandemic and Brexit, the Group maintained a strong liquidity position, ending the period with £52.9 million in cash and no utilized borrowing facilities. This financial stability allowed the board to maintain its commitment to shareholders through dividends of 145 pence per share and to support its workforce by providing full pay during shutdowns and distributing profit-share bonuses to all staff. The report concludes with a focus on long-term sustainability, ethical sourcing, and continued IP exploitation to ensure future viability.
- Games Workshop achieved record-breaking financial results for the 2019/20 fiscal year, with revenue rising 5.1% to £269.7 million and profit before tax reaching £89.4 million.
- The trade segment now accounts for 52% of total revenue, supported by a significant increase in royalty income from video game and media licensing.
- North America remains the company's largest market, contributing £104.8 million to total revenue despite pandemic-related operational disruptions.
- The company invested £18 million in capital projects, including production and logistics expansions in Nottingham and North America and the implementation of a new ERP system.
- Physical retail sales declined by 11% due to pandemic-related closures, though this was offset by growth in digital engagement and online sales.
+1
Games Workshop GroupAug 2020
Presentation40 pages
3Q FY2020 Presentation Material
CyberAgent’s performance during the third quarter of fiscal year 2020 remained resilient despite the economic disruptions caused by the COVID-19 pandemic. Consolidated sales reached 112.8 billion yen, a marginal year-over-year decrease of 0.7%, while operating profit stood at 8.2 billion yen. By the end of this period, the company had already achieved between 89% and 102% of its full-year operating profit forecasts. This stability was largely driven by the Internet Advertisement segment, which successfully offset declining demand in certain sectors by pivoting toward advertisers benefiting from stay-at-home trends, and the Game business, which generated 36.7 billion yen in quarterly revenue following major title anniversaries.
The media segment, centered on the streaming platform ABEMA, demonstrated significant growth with a 19.2% year-over-year increase in sales to 13.3 billion yen. This expansion was supported by a record 56 million downloads and a surge in the WINTICKET gambling transaction business, which doubled its volume to 7.2 billion yen. Strategic priorities for this segment include reaching one million ABEMA Premium subscribers by late 2020 and leveraging new virtual production technologies, such as Pay-Per-View systems, to enhance monetization.
Looking forward, the corporate strategy focuses on establishing ABEMA as a long-term financial pillar while maintaining market share in the advertising sector through AI-driven efficiency. In the gaming division, the emphasis remains on the dual approach of developing new intellectual properties and extending the lifecycle of existing titles through robust operational management. These efforts are underpinned by a broader commitment to ESG initiatives and information security, ensuring sustainable value creation across the company’s diverse digital portfolio.
- CyberAgent reported 112.8 billion yen in consolidated sales for 3Q FY2020, achieving 89% to 102% of its full-year operating profit forecast despite a marginal 0.7% year-over-year revenue decline.
- The Game business generated 36.7 billion yen in quarterly revenue, bolstered by major title anniversaries and a strategy focused on both new IP development and lifecycle extension for existing games.
- The media segment, anchored by the ABEMA streaming platform, grew sales by 19.2% year-over-year to 13.3 billion yen, supported by 56 million total downloads.
- WINTICKET gambling transactions doubled in volume to 7.2 billion yen, contributing significantly to the media segment's growth.
- The Internet Advertisement segment maintained stability by pivoting toward advertisers benefiting from stay-at-home trends to offset sector-specific demand declines.
+1
CyberAgentJul 2020
Report7 pages
AI's Ever-Growing Presence in Gaming: $1.8B in VC Investments
Venture capital investment in AI-focused gaming startups has experienced significant growth, totaling $1.8 billion between 2020 and 2024. This influx of capital reflects a strategic shift in investor interest toward verticalized AI tooling designed to enhance scalability and production efficiency within the gaming sector. By 2024, AI-focused startups accounted for approximately 65% of total deal activity in gaming infrastructure, signaling a move away from broader platform bets toward specialized technological solutions.
The investment landscape is categorized into three primary segments: in-game content generation, development infrastructure, and other AI-focused applications. Content generation, which includes tools for creating assets, worlds, and narrative elements, leads the market with $1.2 billion in deal value across 119 deals. Development infrastructure, encompassing productivity tools, testing automation, and backend analytics, secured $0.4 billion across 72 deals. The remaining $0.2 billion was directed toward marketing, influencer tools, and player analytics.
Methodologically, the analysis focuses on startups that received venture financing between 2020 and 2024, specifically excluding studios that utilize AI solely for internal production. The data reveals a robust compound annual growth rate of approximately 35% in deal value from 2022 to 2024. While early-stage rounds dominate the market, the average check size has tripled over the five-year period, rising from $2.6 million in 2020 to $7.3 million by 2024. Andreessen Horowitz, Bitkraft, and Y Combinator emerge as the most active investors, with Andreessen Horowitz leading in both the number of deals and total invested capital.
- Venture capital investment in AI-focused gaming startups reached $1.8 billion between 2020 and 2024, with deal value growing at a 35% compound annual rate from 2022 to 2024.
- AI-focused startups now account for approximately 65% of all gaming infrastructure deal activity, reflecting a strategic pivot toward specialized verticalized tooling over general platform investments.
- In-game content generation tools lead the market with $1.2 billion in funding across 119 deals, followed by $0.4 billion for development infrastructure and $0.2 billion for marketing and analytics.
- Average investment check sizes have tripled over the five-year period, increasing from $2.6 million in 2020 to $7.3 million by 2024.
- Andreessen Horowitz, Bitkraft, and Y Combinator are the most active investors in the space, with Andreessen Horowitz leading in both total deal count and capital deployed.
+2
GDevJan 2020
Report11 pages
Investment Activity Report Q1–Q3 2020
The report documents investment activity in the global gaming industry from January to September 2020, covering mobile, PC & console, multiplatform, VR/AR, cloud‑native and esports segments. Total deal value reached $27.5 billion across 1,000 transactions, with gaming deals accounting for the largest share ($15.3 billion in 211 contracts). Platform & tech deals contributed $4 billion, esports $685 million and other categories $504 million. Public offerings dominated the capital‑raising landscape, generating $9.2 billion from 51 IPOs and PIPEs, while M&A activity totaled $6.6 billion across 132 deals and private venture investments added $4.7 billion from 254 rounds.
Early‑stage VC activity fell sharply after the COVID‑19 outbreak in May, dropping to 5–7 deals per month, but later‑stage and corporate funding remained relatively stable at 1–2 deals monthly until July. The period saw $2.7 billion raised by developers and publishers, with 69 pre‑seed/seed/Series A rounds and 9 Series B+ deals. U.S. firms dominated later‑stage funding (over 90% of value), whereas only 30% of early‑stage capital went to U.S. startups. Three high‑profile transactions—Scopely ($200 m), Roblox ($150 m), and Epic Games ($1.78 b)—accounted for 78% of total capital inflows.
M&A activity remained resilient, with major deals such as Zynga’s acquisition of Peak Games ($2 billion) and Microsoft’s purchase of ZeniMax ($7.5 billion). Tencent, Zynga, and Microsoft were the top strategic acquirers, collectively exceeding $11 billion in announced deals. Public market activity stalled early in the year but rebounded in June with IPOs from Archosaur Games ($280 m) and Kakao Games ($330 m). The report highlights a shift toward mobile acquisitions, sustained corporate investment despite pandemic disruptions, and a growing trend of large‑scale consolidations in the gaming sector.
- The global gaming industry saw $27.5 billion in total deal value across 1,000 transactions during the first nine months of 2020, with gaming-specific deals accounting for $15.3 billion.
- M&A activity was defined by large-scale consolidation, led by Microsoft’s $7.5 billion acquisition of ZeniMax and Zynga’s $2 billion purchase of Peak Games, with Tencent, Zynga, and Microsoft collectively exceeding $11 billion in deal value.
- Public offerings were the primary driver of capital, generating $9.2 billion from 51 IPOs and PIPEs, while private venture investments contributed $4.7 billion across 254 rounds.
- Three high-profile transactions—Epic Games ($1.78 billion), Scopely ($200 million), and Roblox ($150 million)—accounted for 78% of total venture capital inflows.
- Early-stage venture capital activity experienced a sharp decline following the May 2020 COVID-19 outbreak, dropping to 5–7 deals per month, while later-stage and corporate funding remained more resilient.
+2
InvestGameJan 2020
Report29 pages
The Most Exciting Time in the Gaming Industry: 2020–2022
The analysis demonstrates that the gaming sector experienced a pronounced surge in deal activity between 2020 and 2022, with private equity investments peaking at $12 billion in 2021 before receding to $10.1 billion the following year. Mergers and acquisitions reached a high of $41 billion in 2021, cooling to $27.3 billion in 2022, while public offerings peaked at $24.5 billion and collapsed to $4.6 billion amid a macro‑economic slowdown projected to continue into 2023. Despite this contraction, strategic investors such as Microsoft, Sony, and Netflix maintained studio acquisitions, and early‑stage venture capital remained resilient with substantial dry powder poised for future rounds.
Late‑stage transactions contracted sharply in early 2023, with only sixteen deals versus thirty‑one in 2022 and a four‑and‑a‑half‑fold decline in disclosed value from $4.2 billion to $0.9 billion. The top fifteen M&A deals over the period accounted for roughly eighty percent of announced value, dominated by public takeovers—including Microsoft’s purchases of Activision Blizzard and ZeniMax—and characterized by high EV/EBITDA multiples, reaching up to 55×. Venture capital activity stayed robust, led by Makers Fund and BITKRAFT Ventures in both deal count and value. Corporate investments slowed in 2022 but are expected to rebound as regulatory scrutiny eases and large cash reserves, such as Epic’s $2 billion, become available.
The report is framed within a global context, covering all major gaming markets from 2020 through 2022, with particular emphasis on the United States, Europe, and Asia. It focuses on public, private, and venture capital transactions across the industry’s core segments—game development studios, publishing platforms, and emerging technology providers. The findings underscore a transition from high‑volume, high‑valuation deals toward a more cautious investment climate, while highlighting the enduring appeal of strategic acquisitions and venture funding as engines for future growth.
- The gaming industry experienced a massive investment peak in 2021, with M&A reaching $41 billion, private equity hitting $12 billion, and public offerings peaking at $24.5 billion.
- Market activity cooled significantly by 2022, with public offerings collapsing to $4.6 billion and late-stage transaction values dropping four-and-a-half-fold to $0.9 billion in early 2023.
- Strategic acquisitions remain a primary driver of industry value, with the top 15 M&A deals—led by Microsoft’s purchases of Activision Blizzard and ZeniMax—accounting for approximately 80% of total announced deal value.
- High-valuation trends characterized the peak period, with M&A deals achieving EV/EBITDA multiples as high as 55×.
- Early-stage venture capital remains resilient, with firms like Makers Fund and BITKRAFT Ventures continuing to lead in both deal count and total value despite broader market contractions.
InvestGameJan 2020

Report28 pages
InvestGame Deals Report 2020 – Game M&A
The 2020 Game M&A landscape reached a record $33.6 billion in transaction value across 664 deals, with public offerings contributing 45% of the volume and $15.1 billion in 2020 alone, while M&A activity totaled $12.6 billion (potentially $22.2 billion when including recent mega‑deals). The United States dominated the market, accounting for 36% of deal value and hosting four of the top‑10 transactions. Tencent, Embracer, Stillfront, and Zynga were the leading acquirers, together representing 60% of total value. Swedish firms, particularly Embracer and Stillfront, led a domestic acquisition boom that captured 31% of all announced gaming M&A deals.
Investment trends reflected the low‑interest‑rate environment and robust public‑market valuations. Venture capital and corporate funding surged to $5.9 billion, with 363 private deals (55% of transactions) and a pronounced late‑stage focus on multiplatform, mobile, and PC/console titles. Early‑stage VC funding reached $333 million across 82 deals, while late‑stage rounds were concentrated in a handful of large transactions. IPO activity rose to 18 deals ($2.8 billion), led by Asian firms such as Kakao Games and Archosaur, and public PIPE funding exceeded $95 million in the Esports & Other segment.
The Esports & Other sector saw 37 M&A deals totaling $500 million, with control‑type acquisitions dominating (35 of 37). Majority stake takeovers were common, and the segment attracted significant public PIPE funding. Two hardware firms—NACON and Corsair Gaming—raised $350 million through IPOs, while Skillz leveraged a SPAC to achieve a $9 billion market cap. These findings underscore a 2020 environment of heightened M&A activity, concentrated investment in key geographic hubs, and a strategic shift toward multiplatform and esports opportunities.
- The 2020 gaming market hit a record $33.6 billion in total transaction value across 664 deals, driven by $15.1 billion in public offerings and $12.6 billion in M&A activity.
- Tencent, Embracer, Stillfront, and Zynga emerged as the dominant market forces, collectively accounting for 60% of the total M&A value.
- The United States led the global market by capturing 36% of total deal value and hosting four of the year's top-10 largest transactions.
- Swedish firms, specifically Embracer and Stillfront, drove a domestic acquisition boom that accounted for 31% of all announced gaming M&A deals.
- Venture capital and corporate funding reached $5.9 billion across 363 private deals, with a clear strategic focus on late-stage investments in multiplatform, mobile, and PC/console titles.
+1
InvestGameJan 2020
Whitepaper73 pages
Model Scheme and Manual for Game Incubation Programming and Financing: Baltic Games Industry
VENTSPILS HIGH TECHNOLOGY PARK ERHVERVSAKADEMI DANIA TECHNOLOGY PARK This model scheme illustrates “how to run” an incubation programme for game development companies, drafted in form of a manual for business support providers and intermediaries working with Dania University of Applied Sciences Kaunas Science and Technology Park Ventspils High Technology Park für internationale Zusammenarbeit mbH Title page: © iStock.com-bedya, 1.
- Most game incubators in Europe, especially those for game creators, are primarily funded by public sources, with private initiatives being a minority.
- Establishing a sustainable game incubator often takes over 5 years to break even, with only 40.8% of business incubators aiming to break even as part of their business plan.
- Game incubation programs can be structured in various ways, including long-term incubation (1 year+ for medium-maturity startups) and short-term acceleration (3-4 months for high-maturity startups, often involving equity exchange for funding).
- Effective communication strategies for recruiting incubator participants include leveraging social media platforms like Facebook, Twitter, Instagram, and LinkedIn, and partnering with industry job portals like Skillshot.pl.
- The Ventspils High Technology Park GameDev Incubator, operating since 2018, offers free support tools like co-working spaces, coaching, workshops, and grants, focusing on PC, mobile, VR/AR platforms, and collaborates with Ventspils Digital Centre and University of Applied Sciences.
+2
Ventspils High Technology ParkJan 2020
Whitepaper87 pages
Guideline for Set-Up and Maintenance of a Mentoring System for Game Business Incubation
The guideline provides hands-on support regarding the whole process of set-up and maintenance of a mentor system (search for mentors, get in contact, motivate them to get engaged, integrate them in the programme, monitor their work and give feedback, promote their engagement, keep them on board, support further Metropolia University of Applied Sciences Swedish Games Industry (Association of Swedish Game Developers) – Dataspelsbranschen Ventspils High Technology Park für internationale Zusammenar...
- The game industry is highly competitive and unique, with revenues exceeding three times that of the movie industry, requiring specialized incubation support distinct from generic tech incubators.
- Effective game incubation systems need to tailor their offerings based on the local startup ecosystem, considering factors like founders' experience (e.g., fresh graduates vs. industry veterans) and community focus (e.g., hobby developers needing business skills).
- Mentoring in game incubation involves a continuous, supportive relationship with experienced industry professionals, ideally based on a flexible long-term development plan, and requires mentors with strong communication, listening, and industry understanding.
- Incubators like VHTP GameDev Incubator operate both on-site and remotely, leveraging external experts and national support networks (e.g., Latvian Game Developers Association) to provide services like free co-working spaces, legal/accounting advice, and conference opportunities.
- Feedback collection through surveys, interviews, and discussions is crucial for iterating and restructuring incubator offerings, as demonstrated by Farm League's shift to the Living Game Intelligence Network (LGIN).
+1
BGI ProjectJan 2020
Presentation1 pages
Slovak Game Industry Infographic
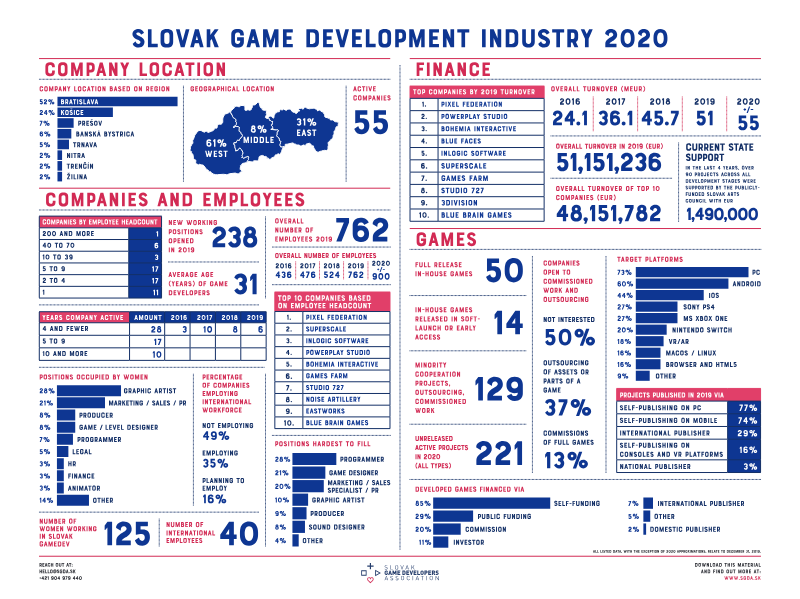
The Slovak game industry demonstrates consistent growth and professional maturation, characterized by a robust increase in both turnover and workforce capacity. As of the end of 2019, the sector comprised 55 active companies, with a significant geographic concentration in Bratislava, which hosts 52 percent of all firms, followed by Košice at 24 percent. The industry’s economic footprint is substantial, with the top ten companies generating over 48 million euros in annual turnover. Workforce development has kept pace with this expansion, as the total number of employees rose from 436 in 2016 to 762 by 2019, supported by the creation of 238 new positions in the final year of the reporting period.
Development activity remains diverse, with a strong emphasis on PC and mobile platforms. PC development leads the market at 73 percent, followed closely by Android and iOS at 60 percent and 44 percent, respectively. While self-publishing remains the dominant business model—utilized by 77 percent of companies for PC and 74 percent for mobile—the industry also leverages a mix of public funding, which supports 29 percent of projects, and commissioned work. Despite this growth, the sector faces talent acquisition challenges, particularly in filling roles for programmers, game designers, and marketing specialists.
The industry maintains a global outlook, with 40 international employees and a significant portion of the workforce engaged in outsourcing and international collaboration. Women represent a notable segment of the industry, occupying 129 positions, primarily within graphic arts, marketing, and production roles. With 221 active projects reported in 2020 and ongoing support from the Slovak Arts Council, the industry is positioned for continued development, balancing in-house creative output with strategic international partnerships and a diversified platform strategy.
- The Slovak game industry experienced significant workforce expansion between 2016 and 2019, growing from 436 to 762 employees.
- The top ten companies in the sector generated over 48 million euros in annual turnover as of 2019.
- The industry is geographically concentrated, with 52 percent of the 55 active companies based in Bratislava and 24 percent in Košice.
- PC development is the primary focus for 73 percent of companies, followed by Android at 60 percent and iOS at 44 percent.
- Self-publishing is the dominant business model, utilized by 77 percent of PC developers and 74 percent of mobile developers.
+1
Slovak Game Developers AssociationJan 2020
Whitepaper26 pages
White Paper on Spanish Video Game Development 2020
Promoted by: With support from: Promoted by: With support from: LÍNEA Covid-19<sub>CULTURA</sub> One more year, DEV, the Spanish Association of Video Games and Entertainment Software Producers and Development Companies, keeps its commitment to the sector it represents by publishing the White Paper on Spanish Video Game Development, the leading report that makes an in-depth analysis of the video game industry in our The White Paper, this year celebrating its seventh edition, is aimed at dev...
- The Spanish video game industry billed 920 million euros in 2019, a 13% increase from 2018, and is projected to exceed 1.7 billion euros by 2023 with an annual growth rate of 17%.
- Employment in the sector grew by 6.1% in 2019, reaching 7,320 professionals, and is estimated to reach 8,500 direct jobs by 2023.
- Despite being the fifth European and tenth global market, 86% of Spanish studios bill below 2 million euros annually, with 61% billing under 200,000 euros, indicating a prevalence of small companies.
- Catalonia leads in both billing (51%) and employment (46%) within the Spanish video game industry, followed by Madrid (28% billing, 26% employment).
- A significant 66% of the industry's revenue comes from international markets, highlighting its export-oriented nature.
+1
DEV - Spanish Association of Video Games and Entertainment Software Producers and Development CompaniesJan 2020
Report29 pages
2020–2022: The Most Exciting Time in the Gaming Industry
This analysis examines global investment and merger and acquisition (M&A) activity within the video game industry from 2020 through 2022. The primary thesis posits that the industry has passed a historic peak of deal-making and is now entering a "Great Reset" characterized by market cooling, lower valuations, and a shift in investor priorities. While the era of massive public offerings and late-stage venture capital (VC) surges has slowed due to macroeconomic headwinds like inflation and rising interest rates, the industry remains fundamentally strong with significant "dry powder" available for early-stage startups and strategic consolidations.
The data reveals a volatile three-year cycle. M&A activity reached a zenith in 2022 with $37.7 billion in closed deals—a 199% increase in value from 2021—driven by massive consolidations such as Take-Two’s acquisition of Zynga. Conversely, public offerings plummeted by 82% in 2022 as the IPO and SPAC windows effectively closed. Private investments also saw a 16% decline in value in 2022 after doubling the previous year. Despite these drops, early-stage VC remained resilient, with over $6.2 billion raised by gaming-focused funds ready for deployment.
Geographically and segmentally, the scope is global, with specific attention paid to the decline of mobile gaming hype post-IDFA and the rising interest in PC, console, and AI-driven startups. The report highlights a stark cooling in Web3 gaming, where investor "FOMO" has been replaced by a focus on fundamental gameplay and infrastructure. Gender diversity remains a challenge in the sector; 89% of funded or acquired companies were led by men in 2022, a negligible change from 90% in 2021.
Methodologically, the findings are based on tracked closed transactions across video game publishers, developers, and hardware providers. Data was aggregated from public media, S&P Capital IQ, and partner insights, utilizing a weighted ranking system to identify the most active investors. The analysis concludes that while the "peak wave" has passed, the industry is transitioning into a more disciplined phase of the investment cycle.
- M&A activity reached a historic peak in 2022 with $37.7 billion in closed deals, representing a 199% increase over 2021, largely driven by major consolidations like Take-Two’s acquisition of Zynga.
- Public offerings for gaming companies collapsed in 2022, with an 82% decline in value as IPO and SPAC windows effectively closed due to macroeconomic headwinds.
- Private investment value fell by 16% in 2022 following a doubling of investment the previous year, signaling a shift toward a more disciplined, cooling market.
- Despite the broader market slowdown, early-stage venture capital remains robust, with over $6.2 billion in dry powder currently available for deployment into new startups.
- Investor interest has shifted away from Web3 gaming and mobile gaming—the latter impacted by post-IDFA challenges—toward PC, console, and AI-driven development.
+1
InvestGameJan 2020
Report28 pages
Global Video Game Deals Report 2020
The 2020 fiscal year marked a historic period of consolidation and capital infusion for the global video game industry, largely catalyzed by the COVID-19 pandemic and the resulting surge in at-home entertainment. Total deal value reached $33.6 billion across 664 transactions, encompassing mergers and acquisitions, private investments, and public offerings. The United States and China emerged as the primary geographical drivers, collectively representing 63% of the total deal value. The market demonstrated significant resilience, recovering from a stagnant first quarter to reach record-breaking activity levels in the second half of the year.
M&A activity was a primary pillar of this growth, totaling $12.6 billion across 219 deals. This sector was dominated by public strategic acquirers such as Tencent, Embracer Group, Stillfront, and Zynga, who accounted for 60% of the total M&A value. Private investment also reached new heights, with $5.9 billion raised through venture capital and corporate rounds, specifically targeting multiplatform developers and mobile studios. Public markets followed a similar trajectory; after a quiet start to the year, public offerings surpassed $15.1 billion, supported by high-profile IPOs from companies like Unity Software and Kakao Games, as well as significant fixed-income activity as firms moved to refinance debt at lower interest rates.
The analysis segments the industry into gaming, platform technology, and esports. While gaming remained the most active sector, platform and tech saw substantial late-stage investments in companies like Roblox and Epic Games. Looking forward, the industry is expected to see continued consolidation led by Nordic and Chinese firms, increased competition between traditional venture capital and large strategic investors, and a robust pipeline of IPO candidates. This data was compiled by tracking closed transactions across public media and financial databases, excluding pure gambling and betting entities to focus on the core video game ecosystem.
- The global video game industry reached a record $33.6 billion in total deal value across 664 transactions in 2020, driven by pandemic-induced demand for at-home entertainment.
- Public offerings were the largest financial contributor at $15.1 billion, bolstered by high-profile IPOs from Unity Software and Kakao Games alongside corporate debt refinancing.
- Mergers and acquisitions totaled $12.6 billion across 219 deals, with Tencent, Embracer Group, Stillfront, and Zynga accounting for 60% of that value.
- The United States and China served as the primary market drivers, collectively representing 63% of the total global deal value.
- Private investment reached $5.9 billion, with venture capital and corporate funding rounds specifically targeting mobile studios and multiplatform developers.
+1
InvestGameJan 2020
Report43 pages
Games Industry 2019/20
Germany stands as Europe’s largest video‑game market and the world’s fifth‑largest, a position reinforced by a robust developer community, flagship events and a policy framework that actively subsidises production. Federal funding of €50 million per year, allocated as non‑repayable grants covering a quarter to half of project costs, is complemented by regional programmes and a business climate that benefits from a sizable domestic audience and a highly skilled workforce.
The market generated a record €4.4 billion in 2018, expanding 9 percent year‑on‑year, while the sector’s organisational base grew to roughly 524 game‑related firms that year. These include 368 development studios, 38 pure publishers and a further 118 hybrid entities, employing about 11 000 staff directly in development and nearly 28 000 when ancillary roles are counted. More than 50 higher‑education institutions now deliver dedicated curricula in game design, computer science, art and virtual reality, concentrating talent pipelines in Berlin and Hamburg.
Mid‑size studios such as Deep Silver, Kolibri Games and Mimimi have produced internationally recognised titles, and the annual gamescom exhibition in Cologne underscores the industry’s global reach. In 2023 the event attracted 31 300 trade professionals, delivered over 500 000 concurrent viewers for its Opening Night Live broadcast and amassed more than 100 million video hits, prompting the launch of a gamescom Asia edition in Singapore to capture growth in the Asia‑Pacific region.
A dense network of over 200 development and publishing firms and more than 150 specialist service providers—spanning localisation, cloud infrastructure, legal counsel, marketing and middleware—covers virtually every German city. This comprehensive, SME‑driven ecosystem, supported by mature ancillary services, positions Germany for sustained expansion and reinforces its role as a central hub for both domestic creation and international distribution of video‑games.
- Germany is the largest video-game market in Europe and the fifth-largest globally, generating a record €4.4 billion in 2018 with a 9 percent year-on-year growth rate.
- The German government supports the industry with €50 million in annual non-repayable grants, which cover 25 to 50 percent of project costs for developers.
- The sector comprises approximately 524 game-related firms, including 368 development studios, employing 11,000 staff directly and nearly 28,000 when including ancillary roles.
- The industry is supported by a robust talent pipeline from over 50 higher-education institutions, with development hubs concentrated primarily in Berlin and Hamburg.
- The annual gamescom exhibition in Cologne is a major international industry driver, attracting 31,300 trade professionals and over 100 million video hits in 2023.
+1
game – Verband der deutschen Games-Branche e. V.Jan 2020
Report14 pages
Tencent Games Strategy 2019
Tencent’s strategic pivot in 2019 marks a recovery from the previous year’s regulatory freeze on game licenses, which had triggered the company’s first-ever profit decline. By early 2019, gaming revenue rebounded to $5.2 billion, driven largely by the successful transition of 150 million monthly active users from the unmonetized PUBG Mobile to the compliant, self-developed Peacekeeper Elite. This maneuver underscores a broader commitment to navigating strict domestic regulations while maintaining market dominance through the integration of the WeChat and QQ social ecosystems, which serve as the primary distribution channels for both internal and third-party titles.
The company is simultaneously pursuing aggressive international expansion and portfolio diversification to mitigate domestic risks. This global strategy involves high-profile intellectual property licensing, such as Call of Duty and Street Fighter, alongside strategic acquisitions of Western studios like Sharkmob. Within China, the expansion of the WeGame platform to 70 million monthly active users and a partnership to serve as the exclusive distributor for the Nintendo Switch signal a move beyond traditional free-to-play mobile models into the PC and console markets.
Future growth is anchored in emerging technologies and infrastructure, specifically cloud gaming and esports. Leveraging a cloud network that already supports 75% of China’s top mobile games, Tencent is positioned to lead the domestic market in the absence of major international competitors. With a $1 billion commitment to esports infrastructure and a pipeline of over 20 new titles, the strategy emphasizes long-term dominance through a combination of massive capital investment, mergers and acquisitions, and the development of next-generation technologies including augmented reality and blockchain-integrated gaming.
- Tencent successfully recovered from a 2018 regulatory freeze by migrating 150 million monthly active users from PUBG Mobile to the compliant, self-developed title Peacekeeper Elite, resulting in $5.2 billion in quarterly gaming revenue.
- The company is mitigating domestic regulatory risks through aggressive international expansion, including the acquisition of Western studios like Sharkmob and licensing major IP such as Call of Duty and Street Fighter.
- Tencent is diversifying beyond mobile free-to-play models by growing its WeGame platform to 70 million monthly active users and securing an exclusive partnership to distribute the Nintendo Switch in China.
- Tencent is leveraging its existing cloud infrastructure, which currently supports 75% of China’s top mobile games, to establish a dominant position in the emerging cloud gaming market.
- The company has committed $1 billion to esports infrastructure and is developing a pipeline of over 20 new titles to maintain market leadership.
Niko PartnersJan 2019
Report42 pages
Serbian Gaming Industry Report 2018
The inaugural Serbian Games Association report maps a rapidly expanding national gaming ecosystem that now comprises more than 60 members across indie development, esports, visual‑effects houses and internationally linked studios, employing over 1,500 skilled professionals. Funding is diversified, with roughly 40 % of capital sourced from angel investors, 30 % from crowdfunding and 20 % from venture capital, and the largest single infusion recorded at €650 k. Flagship entities such as 3Lateral (recently integrated into Epic Games), Nordeus with its 200 million‑user “Top Eleven” platform, and Ubisoft Belgrade’s 107‑person team working on major AAA titles illustrate the sector’s growing global relevance.
A vibrant indie segment is driven by small, highly creative teams—often one to three developers—producing titles ranging from cyber‑punk point‑and‑click adventures to hyper‑casual mobile games. Studios like Munzesky Games, Oraharo Entertainment, PWN.RS, Stargazer, Superverse Industries, Tummy Games and Zero Gravity showcase cross‑border collaborations and distinctive artistic approaches, while highlighting the need for stronger B2B networking, regular industry events and formalized game‑art education to sustain momentum.
Technical education underpins this growth, with approximately 30 000 university students enrolled in IT‑related programs and programming introduced at the primary‑school level. Government incentives, EU grants and private investment have bolstered studio formation, yet most companies still rely on organic installs and limited ad‑network usage for user acquisition. Community initiatives—including frequent association meet‑ups, two industry‑backed GameJams, the annual GameUp expo attracting over 2 500 participants, and the Nordeus Hub co‑working space offering a six‑month mentorship—are actively closing knowledge gaps and fostering collaboration.
Media outlets such as Svet kompjutera, JVC Gamer and the online PLAY! Zine maintain visibility for Serbian developers both domestically and abroad. Surveyed stakeholders anticipate a rise in paid user‑acquisition capabilities and an increase in successful Serbian titles, positioning the country to become a more prominent player in the regional and global gaming market.
- The Serbian gaming industry comprises over 60 member entities and employs more than 1,500 professionals, anchored by major players like Nordeus, Ubisoft Belgrade, and 3Lateral.
- Funding for the sector is diversified, with 40% sourced from angel investors, 30% from crowdfunding, and 20% from venture capital, with the largest single investment reaching €650,000.
- A robust pipeline of technical talent is supported by approximately 30,000 university students in IT-related programs and the integration of programming into primary-school curricula.
- The indie segment is characterized by small, highly creative teams of one to three developers, though these studios currently rely heavily on organic installs rather than paid user-acquisition strategies.
- Industry growth is bolstered by community-led initiatives such as the GameUp expo, which attracts over 2,500 participants, and mentorship programs like the Nordeus Hub.
+1
SGAJan 2019
Report69 pages
Annual Report 2018
Games Workshop achieved record-breaking financial performance during the 2017/18 fiscal year, characterized by a 39% increase in revenue to £219.9 million and a near doubling of operating profit to £74.6 million. This growth, which propelled the company into the FTSE 250, was primarily driven by the global success of the Warhammer brand and a 54% surge in the trade segment. With 76% of sales generated internationally, the company significantly expanded its Nottingham-based manufacturing and R&D facilities, doubling plastic injection molding capacity and increasing inventory levels to £20.2 million to meet rising global demand.
Strategic priorities focused on long-term infrastructure and digital engagement, including the implementation of a new ERP system and a successful relaunch of Warhammer 40,000 that drove 70 million digital community page views. Financial stability remained robust, with the company maintaining a debt-free position and increasing cash reserves to £28.5 million. While management monitored risks related to Brexit and supply chain interruptions, the return on capital rose from 72% to 120%. Governance remained stable, with the board defending the tenure of long-serving directors based on their deep industry expertise, while also implementing a revised remuneration policy to align executive pay with market rates following the year’s exceptional performance.
The company’s commitment to sustainability and compliance was evidenced by a reduction in greenhouse gas emissions through solar energy investments and the achievement of full GDPR compliance. Looking forward, the company remains focused on multi-channel retail growth and IP licensing opportunities. Independent auditors confirmed the integrity of the financial statements, noting that while inventory valuation and development costs require significant management judgment, the group remains a strong going concern with high liquidity and a clear trajectory for continued global expansion.
- Games Workshop achieved record financial performance in the 2017/18 fiscal year, with revenue increasing 39% to £219.9 million and operating profit nearly doubling to £74.6 million.
- The company’s growth was driven by a 54% surge in the trade segment and the global success of the Warhammer brand, which helped propel the firm into the FTSE 250.
- To support international demand, which accounted for 76% of total sales, the company doubled its plastic injection molding capacity and increased inventory levels to £20.2 million.
- Operational efficiency and capital allocation were highly effective, with the return on capital rising from 72% to 120% while maintaining a debt-free balance sheet with £28.5 million in cash reserves.
- Digital engagement initiatives, highlighted by the relaunch of Warhammer 40,000, generated 70 million page views on the company's community platform.
Games Workshop GroupAug 2018
Whitepaper84 pages
Libro Blanco del Desarrollo Español de los Videojuegos
LIBRO CENTRO UNIVERSITARIO Fando Eurapeo de DE TECNOLOGIA Y ARTE DIGITAL Ung manere de hacer Eurapa Asociación Española de Empresas Productoras y Desarrolladoras de Videojuegos y Software de Entretenimiento 1 . INTRODUCCIÓN 05 2. CADENA DE VALOR DE LA INDUSTRIA DEL VIDEOJUEGO 07 2.1. Cadena de valor tradicional de la industria de videojuegos 08 2.2.
- The global gaming market had 1.231 billion active players by the end of 2013, representing over half of the world's internet-connected population and 17.5% of the total global population.
- The gamification business is projected for exponential growth, with Markets And Markets estimating a potential business of $5.5 trillion USD by 2018, growing at a 67.1% annual rate between 2013 and 2018.
- The Spanish video game sector increased employment by 29% in 2013, with 65% of contracts being permanent, making it a significant job creator for highly qualified young professionals.
- In 2012, the Russian video game industry generated $1.3 billion, a 30% increase from 2011, and its market is expected to double in the next three years to reach $1.5 billion.
- The UK offers R&D tax deductions for video game companies, with SMEs receiving a 225% enhanced deduction on their R&D investment.
+2
DEV – Asociacion Espanola de Empresas Productoras y Desarrolladoras de VideojuegosJan 2018