1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticle Niko Partners
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticleNiko Partners
Long-term forecasts estimate the market will expand to $54.8 billion by 2029.
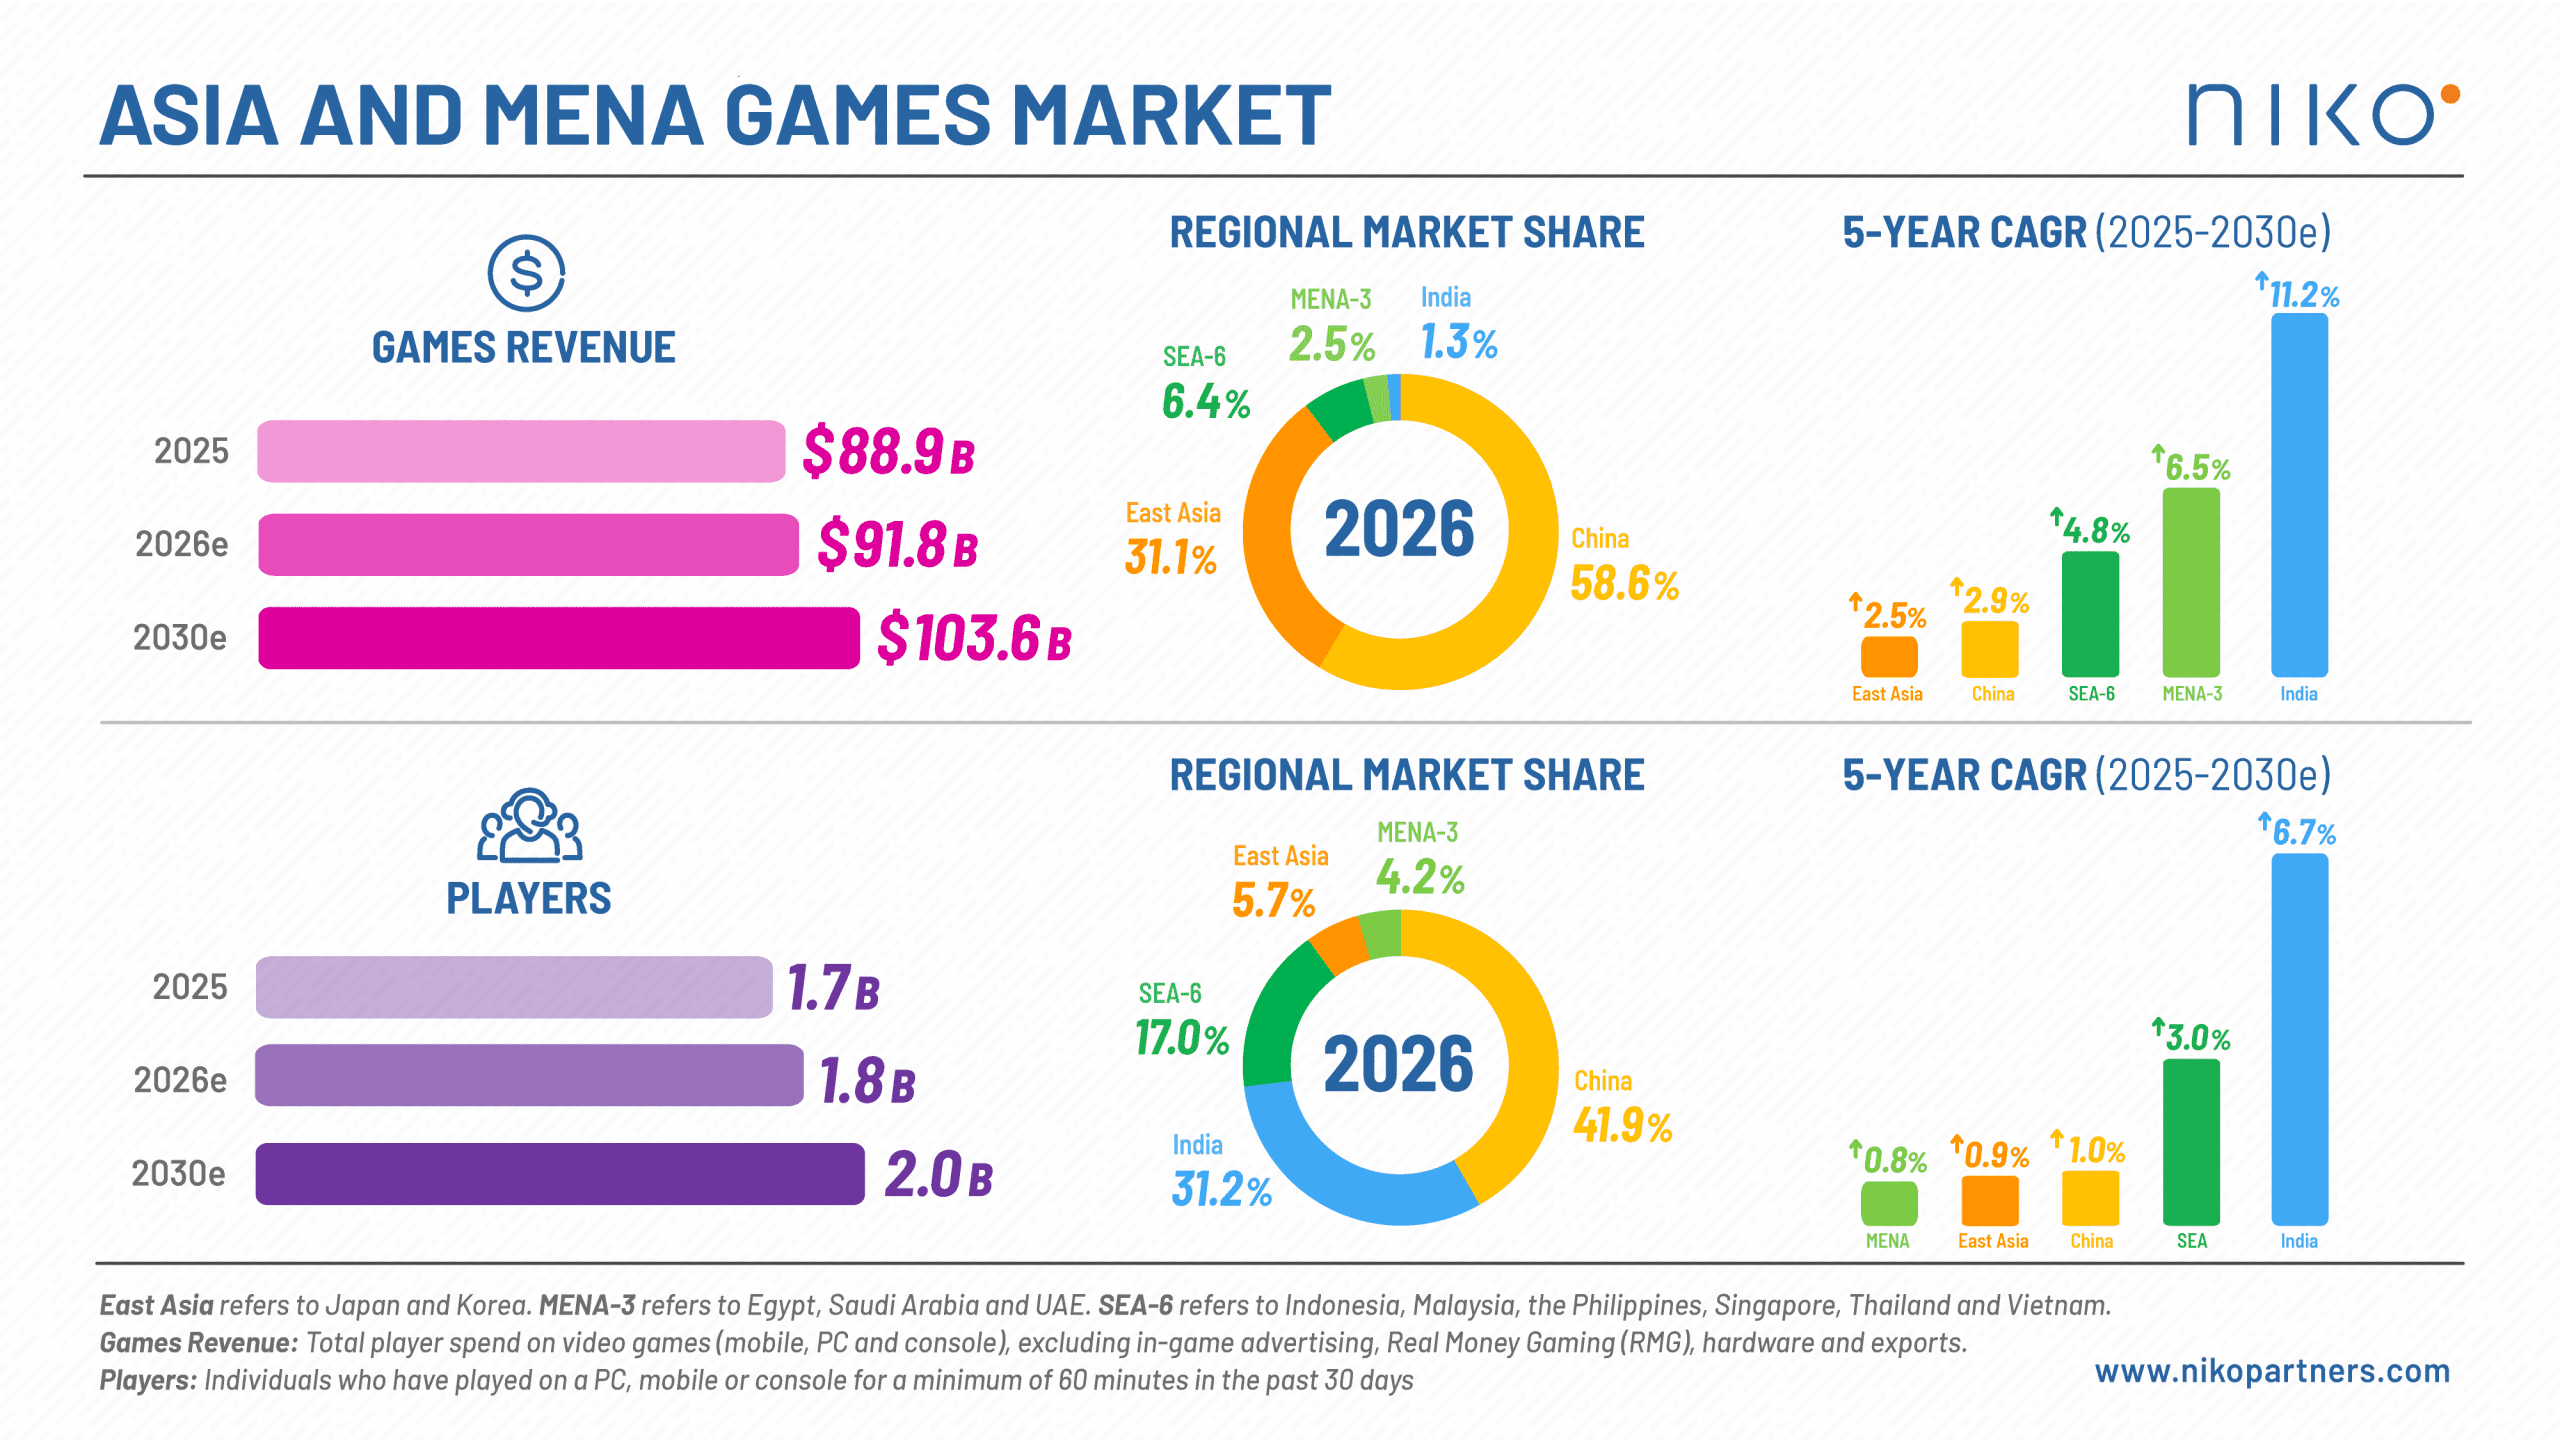
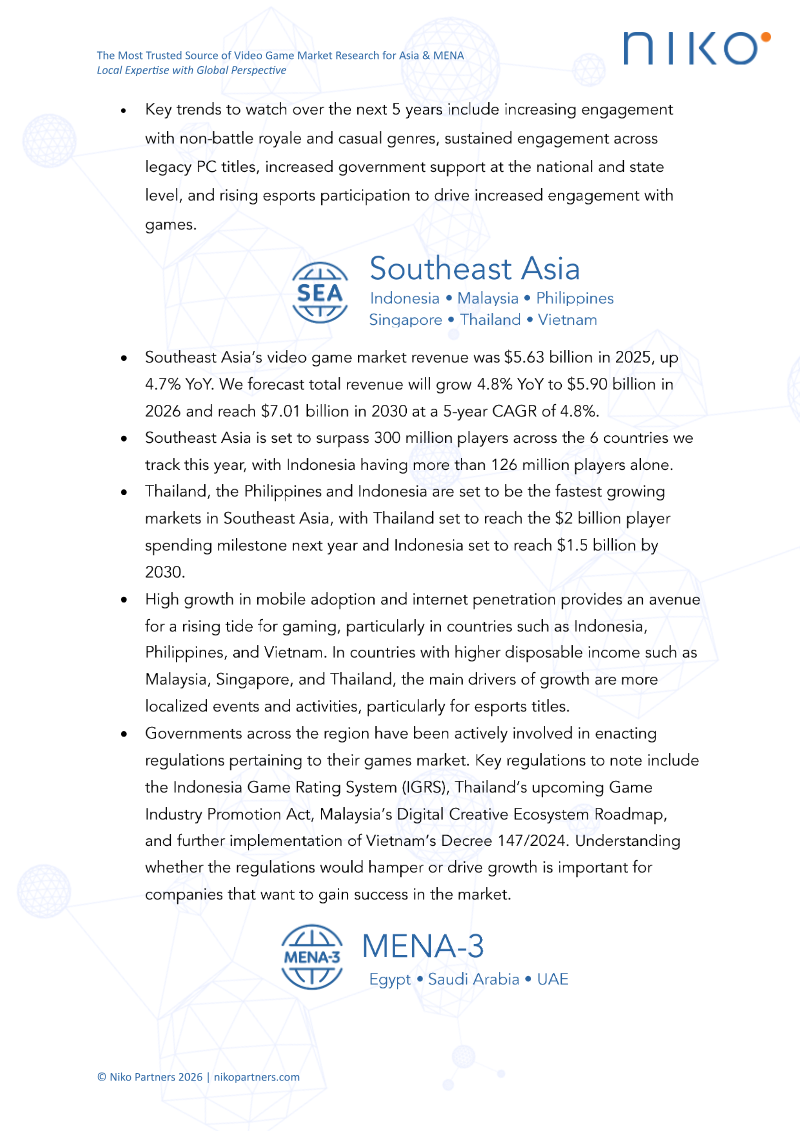
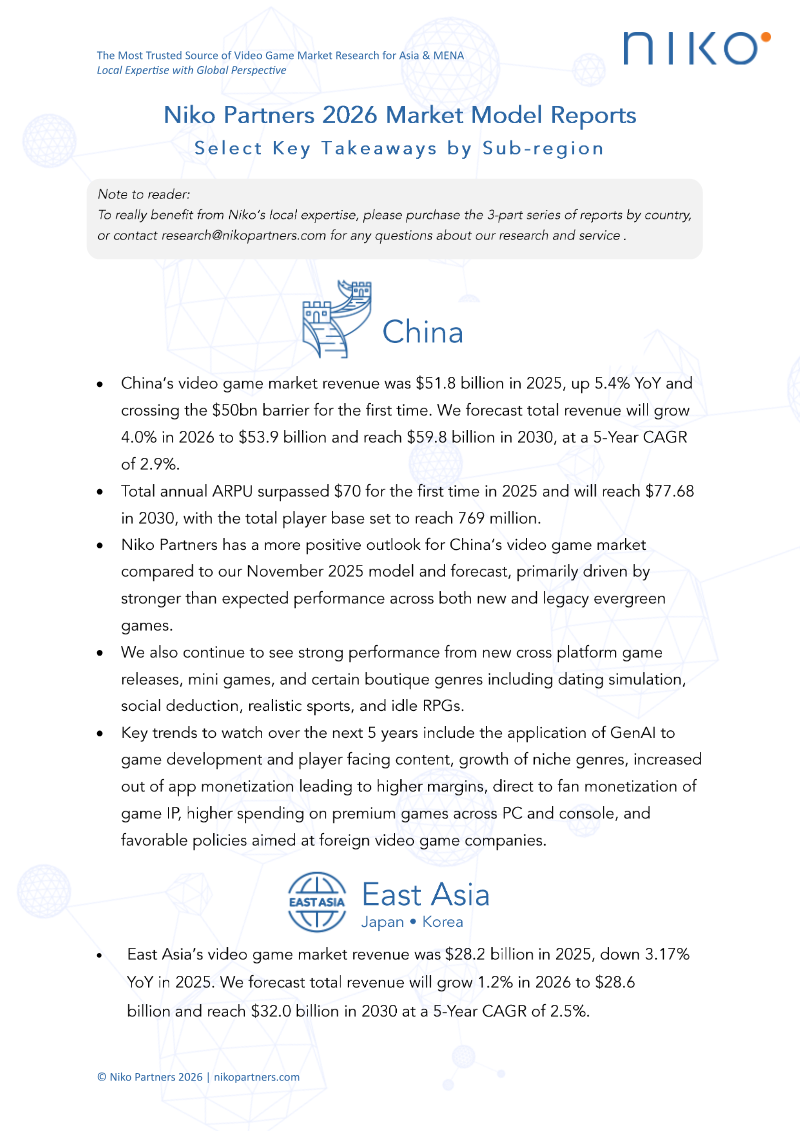
The Chinese video game market is projected to reach $50.7 billion in revenue in 2025, continuing a steady growth trajectory that saw player spending hit $49.2 billion in 2024. Long-term forecasts estimate the market will expand to $54.8 billion by 2029, representing a 5-year compound annual growth rate of 2.2%. This expansion is supported by a massive user base of 722 million gamers as of late 2024, a figure expected to climb to 753.7 million by 2029.
Market growth is driven by a combination of evergreen mobile and PC titles, the emergence of mini-games, and increasing interest in premium console gaming. Government policy remains a significant catalyst, with the National Press and Publication Administration approving 1,119 titles in the first eight months of 2025, a 21% year-over-year increase. Despite this, the industry faces headwinds including a maturing player population, rising operational costs, and geopolitical tensions affecting hardware supply chains.
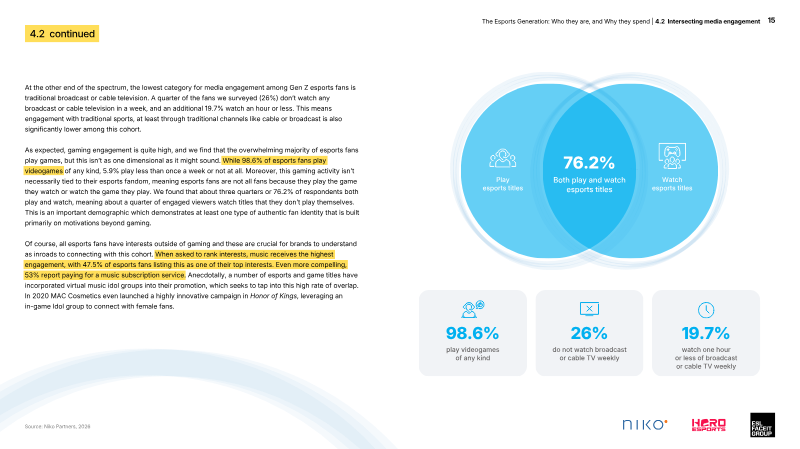
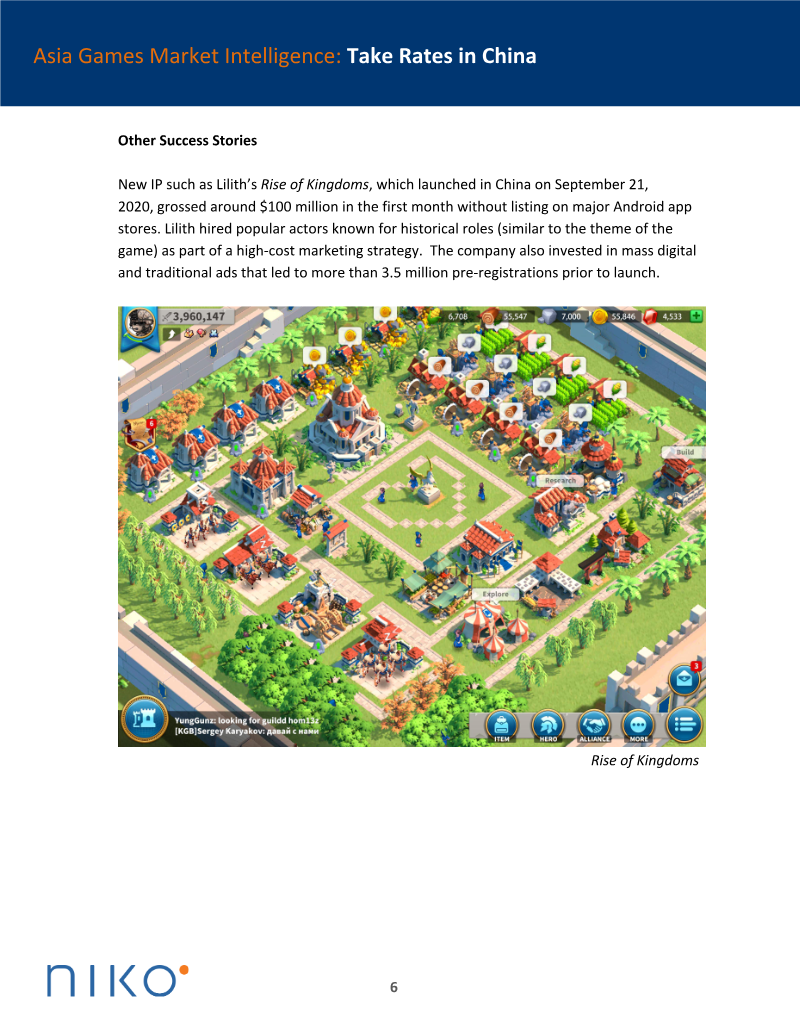
Methodologically, these insights are derived from a comprehensive market model, five-year forecasts, and a survey of 1,058 gamers. Key consumer trends highlight a high adoption of generative AI, with 60% of domestic studios integrating the technology into development pipelines. Additionally, short-video platforms like Douyin have become the primary marketing channel for game discovery, while mini-games—playable without downloads—now account for nearly 10% of total player spending. Esports and livestreaming remain critical engagement verticals, with MOBA and shooter genres dominating viewership on major platforms. International developers continue to maintain a strong presence, as evidenced by the high performance of global intellectual property within the Chinese market.
Niko Partners · 2026
Niko Partners · 2026
Niko Partners · 2026
Niko Partners · 2026
Niko Partners · 2026
Niko Partners · 2026
Deconstructor of Fun · 2026
Niko Partners · 2026
Niko Partners · 2026
Niko Partners · 2025
Niko Partners · 2025
Niko Partners · 2025
Two & a Half Gamers · 2026