Sensor Tower
Research137 documents
Documents
Report47 pages
How to Prepare Your Live Ops for the Holiday Season
A well‑designed Live Ops strategy is essential for capitalising on the heightened player activity that occurs during the holiday period. Analysis of hundreds of mobile games worldwide demonstrates that a coherent Live Ops framework can produce a substantial uplift in sessions, revenue and player retention throughout the season. The core argument is that developers should treat the holidays as a series of tightly integrated, short‑term experiences that reinforce the game’s everyday loop while delivering clear, time‑bound incentives.
Short‑term events that run for one to three days are most effective for generating quick spikes in engagement. These events focus on immediate objectives—such as a burst of sessions, a specific resource collection, or a limited‑time reward—while employing a “soft‑sawtooth” difficulty curve that eases players in, ramps up challenge, offers a brief respite, and then escalates again. By keeping the event mechanics a natural extension of the main gameplay loop, developers avoid disrupting player expectations and maintain momentum.
For the broader holiday window, the most successful structures combine a single, clearly defined Battle‑Pass progression path with social‑cooperation events that reward group performance through prestige items like avatars, badges and leaderboard positions. Layering weekly quests, long‑term collection albums, and brief “bonus amplifier” events creates cumulative engagement loops. Linking these components through shared currencies and diversified motivations systematically drives both retention and monetisation, particularly for mature titles that benefit from community‑driven competition.
Overall, the guidance applies to the global mobile gaming sector during the Q4 holiday season and emphasizes that incremental, interconnected events—anchored by transparent progression and social incentives—are the key levers for maximising holiday‑season performance.
- Implement a series of short-term, 1-to-3-day events to generate immediate spikes in player engagement and session frequency.
- Structure holiday content as a 'soft-sawtooth' difficulty curve that alternates between periods of challenge and respite to maintain player momentum.
- Integrate holiday events directly into the core gameplay loop to ensure they feel like natural extensions of the existing experience rather than disruptive additions.
- Combine a single, clear Battle-Pass progression path with social-cooperation events to drive both retention and monetization through group-based prestige rewards.
- Layer weekly quests, long-term collection albums, and brief 'bonus amplifier' events to create cumulative engagement loops.
+2
Sensor TowerJan 2025
Report20 pages
The Importance of Wishlists in 2025
Executive Summary – “The Importance of Wishlists” (VGI Report, 2025)
1. What the Data Shows | Metric | Key Figure | Insight | |--------|------------|---------| | Games surpassing 100 k wishlists at launch | ~9 % (141/1 500) | Only a small minority achieve the “break‑out” threshold. | | Correlation (wishlists ↔ Month‑1 sales) | r ≈ 0.70 (RSQ ≈ 0.49) | Strong overall link, but it spikes to r ≈ 0.71 for games with > 100 k wishlists. | | Top‑heavy distribution | 1–2 % of titles > 1 M wishlists; > 90 % < 10 k | Success is heavily skewed toward a few blockbuster titles. | | Genre performance | Action/Adventure & RPG/Strategy → highest medians (≈ 180‑190 k) | Casual & MMO titles lag (median ≈ 70‑80 k) and rely more on post‑launch tactics. | | Wishlist momentum | Games that hit 100 k+ before launch have a 71 % chance of strong month‑1 sales vs. 17 % for < 100 k. | Momentum is a “crystal ball” for launch success. | | Steam page creation timing | 40 % of top performers publish 0.5‑1 yr before launch; 35 % publish > 1 yr early. | Early page creation gives sustained visibility and higher wishlist growth. | | Pre‑launch wishlist accumulation | 85 % of wishlists are collected ≥ 4 months before launch. | The bulk of audience commitment happens well before the final countdown. |
2. Why Wishlists Matter
1. Predictive Power – Once a title crosses the 100 k‑wishlist threshold, its first‑month sales become far more predictable (≈ 71 % correlation). 2. Marketing Leverage – High wishlist counts signal strong community interest, making it easier to secure press coverage, influencer partnerships, and paid‑media spend. 3. Resource Allocation – Studios can prioritize titles with early wishlist momentum for larger launch budgets and store‑front promotion. 4. Risk Management – Low‑wishlist titles (≤ 10 k) have a 50 % chance of under‑performing, suggesting a need for contingency plans (e.g., extended beta, community events).
3. How Games Accumulate Wishlists
| Tactic | Effectiveness (based on VGI data) | |--------|-----------------------------------| | Early Steam page (≥ 6 months pre‑launch) | +30 % average wishlist growth vs. late‑launch pages | | Regular content drops (trailers, dev logs, screenshots) | Each major trailer ≈ 10‑15 % spike in wishlist count (case: Kingdom Come Deliverance 2 added ~0.2 M per trailer) | | Early Access / Demo releases | Boosts momentum for “core” genres; median increase ≈ 12 % | | Community engagement (Discord, Reddit AMAs) | Stronger post‑launch
- Crossing the 100,000 wishlist threshold is the primary indicator of success, as these titles have a 71% probability of strong first-month sales compared to only 17% for those with fewer than 100,000.
- Wishlist accumulation is highly top-heavy, with only 9% of games reaching the 100,000-wishlist milestone and over 90% of all titles failing to exceed 10,000.
- 85% of total pre-launch wishlists are collected at least four months before a game's release, emphasizing that audience commitment must be secured well in advance of launch.
- Publishing a Steam page at least six months prior to launch increases wishlist growth by an average of 30% compared to pages created closer to the release date.
- Major content drops, such as trailers, consistently drive significant engagement, with each release triggering a 10–15% spike in wishlist counts.
Sensor TowerJan 2025
Report29 pages
Souls‑likes: From Niche to Mainstay
The analysis charts the evolution of the souls‑like subgenre from a niche curiosity to a mainstream pillar of the video‑game market, emphasizing the decisive role of APAC developers and Chinese players in shaping its commercial trajectory. By tracking titles released between January 2015 and early 2025, the study demonstrates that while indie studios supplied the bulk of new releases, AAA and AA publishers now dominate revenue, accounting for over 70 % of estimated units sold on Steam.
Sales data reveal a rapid escalation in both volume and concentration. Black Myth: Wukong leads with roughly 20 million units, followed by Elden Ring at 15.6 million, Monster Hunter World at 13 million, Dark Souls III at 9.1 million, and Hades with 8.4 million YTD. The shift in publisher composition is evident: AA releases peaked at 90 % of titles in 2017 but fell to around 30 % by 2023, while AAA output rose to nearly two‑thirds of the market, reflecting a transition from experimental indie projects to large‑scale investments.
Geographically, APAC’s influence surged, reaching roughly 80 % of development share by 2025, with Japan providing a historic foundation and China and Korea expanding both creation and consumption. Chinese gamers now represent close to half of the global souls‑like audience (≈47 %), eclipsing the United States (≈15 %) and Germany (≈5 %). This demographic weight makes success in China a critical determinant for high‑budget releases.
Methodologically, the findings rely on Video Game Insights’ estimations derived from Steam tagging, publisher classification, and sales‑estimation algorithms applied to all souls‑like titles launched from 2015 onward across Steam, PlayStation and Xbox platforms. The overarching conclusion is that the genre’s challenging, skill‑based design continues to attract investment and player engagement, with APAC innovation and the Chinese market ensuring its long‑term viability as a global mainstay.
- The souls-like genre has shifted from indie-dominated to AAA-led, with AAA and AA publishers now accounting for over 70% of estimated units sold on Steam.
- Chinese gamers represent approximately 47% of the global souls-like audience, significantly outpacing the United States at 15% and Germany at 5%.
- APAC developers have surged to control roughly 80% of the genre's development share as of 2025, building on a foundation established by Japanese studios.
- Top-performing titles demonstrate massive commercial scale, led by Black Myth: Wukong (20 million units), Elden Ring (15.6 million), and Monster Hunter World (13 million).
- The market composition has inverted since 2017, when AA titles comprised 90% of releases; by 2023, AAA output had risen to account for nearly two-thirds of the market.
Sensor TowerJan 2025
Report41 pages
PC/Console Gaming Index: A Look at the Top Games, Publishers, and Platforms in 2025 So Far
The 2025 PC and console landscape is dominated by Steam, which recorded 450 million downloads and is projected to achieve a record $12 billion in premium revenue, reflecting a 15 percent year‑to‑date increase. PlayStation and Xbox follow with 376 million and 283 million downloads respectively, underscoring Steam’s clear lead in both user acquisition and monetisation. Across the combined market, action titles command the highest demand at 262 million downloads, while shooters and role‑playing games attract 189 million and 131 million downloads, indicating a strong preference for high‑intensity, narrative‑driven experiences among gamers.
Premium revenue accounts for the majority of earnings on the leading platforms, with Steam generating 79 percent of its income from premium sales and PlayStation reaching 83 percent, highlighting the continued viability of upfront purchase models despite the growth of free‑to‑play alternatives. The data suggest that while free‑to‑play titles remain a significant segment, the premium‑heavy ecosystem retains a decisive advantage in revenue generation.
Overall, the findings illustrate a globally integrated market in 2025 where PC distribution via Steam outpaces console rivals, genre preferences skew toward action‑oriented titles, and premium monetisation continues to dominate the financial structure of the industry.
- Steam leads the 2025 PC and console market with 450 million downloads and a projected $12 billion in premium revenue, representing a 15 percent year-to-date increase.
- Premium purchase models remain the primary revenue driver, accounting for 79 percent of Steam's income and 83 percent of PlayStation's earnings.
- Steam outperforms console competitors in user acquisition, recording 450 million downloads compared to 376 million for PlayStation and 283 million for Xbox.
- Action titles are the most popular genre in 2025, generating 262 million downloads across the combined market.
- Shooters and role-playing games follow action titles in popularity, attracting 189 million and 131 million downloads respectively.
+1
Sensor TowerJan 2025
Report34 pages
Cross-Platform Gaming: Bridging Mobile and PC/Console
The 2025 gaming landscape is defined by the convergence of mobile accessibility and PC/console depth. The primary thesis suggests that while mobile serves as a global discovery engine and a source of steady growth, PC and console platforms anchor brand prestige and high-value engagement. To maximize franchise value, publishers must strategically bridge these ecosystems through purposeful cross-platform design, turning mobile’s vast reach into lasting loyalty.
Data highlights a significant scale disparity between platforms: mobile is projected to reach 52 billion downloads and $82 billion in in-app purchase revenue in 2025, while the PC and console segment generates over $12 billion from 1 billion units sold. Mobile leaders like Roblox and Garena Free Fire drive mass acquisition, whereas premium titles such as EA SPORTS FC 25 and Marvel Rivals dominate engagement on Steam, PlayStation, and Xbox. The findings indicate that unified ecosystems, such as those used by Delta Force and Genshin Impact, strengthen retention by allowing players to switch devices without losing progress.
The scope of the analysis is global, covering over 100 markets with specific digital advertising data from 14 major regions, including the United States, Japan, and the United Kingdom. It focuses on the first three quarters of 2025, utilizing Sensor Tower’s proprietary App Performance, Video Game, and Pathmatics Advertising Insights. Methodology involves statistical sampling of digital ad placements and estimated revenue from the App Store and Google Play, excluding third-party Android stores and direct web payments.
Four strategic models for expansion are identified: companion apps for engagement, "lite" versions for mass discovery, adapted standalone experiences for genre diversification, and full cross-play models for community unification. The conclusion emphasizes that a resilient portfolio must balance high-volume mobile genres, such as Simulation and Puzzle, with high-depth PC genres like RPGs and Shooters to maximize monetization efficiency and franchise longevity.
- Mobile remains the primary driver of scale with 52 billion projected downloads and $82 billion in in-app purchase revenue for 2025, while PC and console segments generate over $12 billion from 1 billion units sold.
- Unified cross-platform ecosystems, exemplified by titles like Genshin Impact and Delta Force, significantly improve player retention by enabling seamless progress synchronization across devices.
- Publishers should adopt one of four strategic models—companion apps, 'lite' discovery versions, adapted standalone experiences, or full cross-play—to bridge the gap between mobile reach and PC/console engagement.
- A resilient gaming portfolio requires balancing high-volume mobile genres like Simulation and Puzzle with high-depth PC/console genres such as RPGs and Shooters to optimize monetization and franchise longevity.
- Mobile platforms currently function as global discovery engines for mass acquisition, whereas premium titles like EA SPORTS FC 25 and Marvel Rivals anchor high-value engagement on Steam, PlayStation, and Xbox.
+1
Sensor TowerJan 2025
Report6 pages
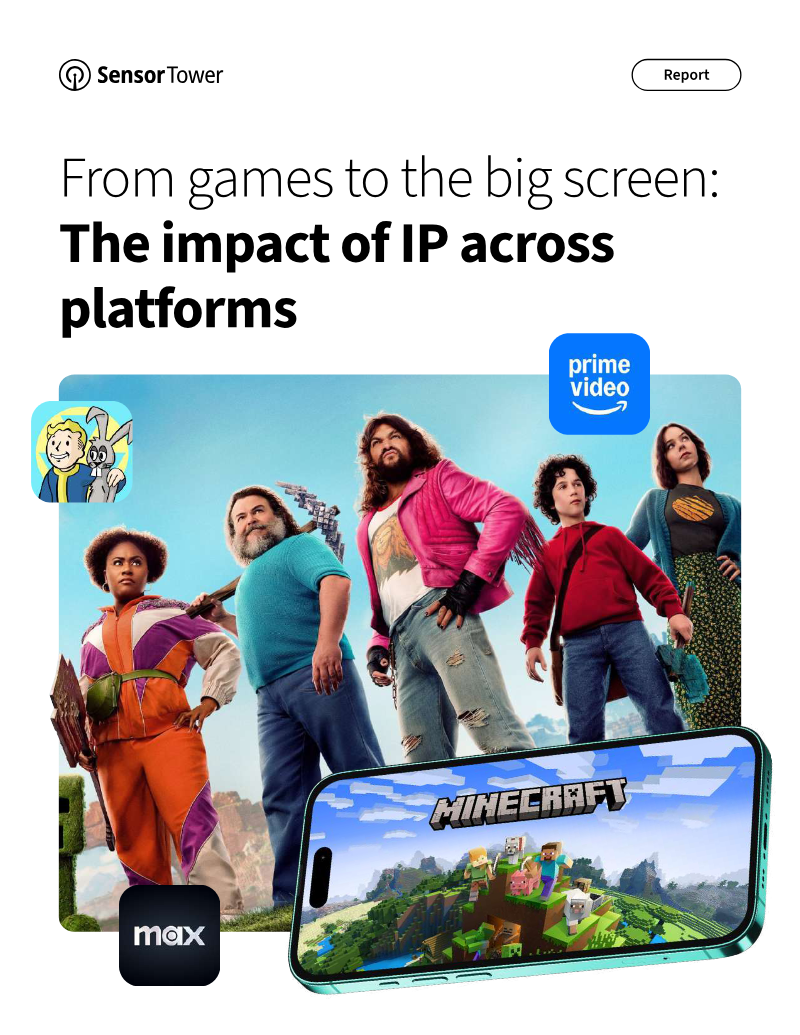
From Games to the Big Screen: The Impact of IP Across Platforms
The entertainment industry is increasingly leveraging a transmedia strategy where video game intellectual property serves as the foundation for high-budget scripted content. This approach creates a symbiotic relationship between platforms, where the release of films and television series triggers a boomerang effect that revitalizes interest in the original games. Data indicates that these adaptations drive significant growth across multiple metrics, including active users, digital downloads, and in-app purchases, while simultaneously boosting the performance of the streaming services hosting the content.
The scope of this analysis covers major cross-platform releases between 2024 and 2025, focusing on global mobile, PC, and console gaming segments alongside digital advertising and streaming app performance. Key findings highlight the success of the Minecraft movie, which grossed over $900 million and led to a 44% spike in mobile in-app revenue and a 36% increase in console sales. Similarly, the Fallout television series drove a 23% increase in Amazon Prime Video downloads and a massive 410% surge in daily sales for Fallout 4 on PC. The longevity of this impact is notable, with daily active users for legacy Fallout titles remaining 225% higher for up to 20 weeks following the show's premiere.
Methodology relies on proprietary data from Sensor Tower, tracking digital market insights, app usage, and advertising spend. The data reveals that strategic marketing is essential to this success; for instance, Amazon increased its desktop video ad spend twentyfold to promote Fallout, specifically targeting gaming-focused platforms like Twitch and IGN. While results vary based on the faithfulness of the adaptation and the monetization model of the game, the overarching trend suggests that transmedia releases are a powerful tool for re-engaging historical players and attracting new audiences to established gaming franchises.
- The Fallout television series triggered a 410% surge in daily PC sales for Fallout 4 and sustained a 225% increase in daily active users for legacy titles for up to 20 weeks post-premiere.
- The Minecraft film grossed over $900 million while driving a 44% spike in mobile in-app revenue and a 36% increase in console sales.
- Transmedia adaptations create a symbiotic growth loop that simultaneously boosts gaming metrics and streaming platform performance, such as the 23% increase in Amazon Prime Video downloads following the Fallout series launch.
- Strategic marketing is a critical success factor, evidenced by Amazon increasing its desktop video ad spend twentyfold on gaming-centric platforms like Twitch and IGN to support the Fallout release.
- Video game IP is increasingly serving as a foundation for high-budget scripted content to re-engage historical players and attract new audiences across mobile, PC, and console segments.
+2
Sensor TowerJan 2025
Report46 pages
Digital Market Index: Q4 2024
Global digital markets reached a significant milestone in the final quarter of 2024, with in-app purchase revenue hitting a record $39.4 billion. This growth was primarily fueled by a 28.2% year-over-year surge in non-game applications, exemplified by TikTok becoming the first app to surpass $6 billion in annual revenue. While the iOS ecosystem remains the primary driver of monetization by capturing 70% of total revenue, Google Play maintains its dominance in scale, facilitating nearly three-quarters of the 34.1 billion global downloads recorded during the period.
The mobile gaming landscape underwent a notable structural shift as consumer preferences migrated from traditional RPGs toward Strategy and Puzzle titles. Strategy games experienced a 26% year-over-year increase in downloads, helping to offset regional revenue declines in major markets like Japan and South Korea. Despite these shifts, Japan’s mobile sector showed signs of overall recovery, while emerging Android markets in Indonesia and Pakistan continued to expand rapidly. The successful launch of high-profile titles like Pokémon TCG Pocket further stabilized the gaming sector during this transition.
Advertising and retail media also reached unprecedented levels, with U.S. digital ad spend hitting $34 billion. Social media channels dominated this space, accounting for 77% of total expenditures as major retailers like Amazon and Walmart increased holiday investments. Retail media specifically generated a record 75.4 billion impressions, driven by high demand in consumer electronics and personal care. Strategic co-branded partnerships, such as the collaboration between Best Buy and Samsung, emerged as critical drivers of visibility, cementing the role of retail platforms as essential components of the broader digital advertising ecosystem.
- Global in-app purchase revenue reached a record $39.4 billion in Q4 2024, bolstered by a 28.2% year-over-year surge in non-game application spending.
- TikTok became the first application to surpass $6 billion in annual revenue, highlighting the massive monetization potential of non-game platforms.
- The iOS ecosystem captured 70% of total revenue, while Google Play maintained its dominance in scale by facilitating nearly 75% of the 34.1 billion global downloads.
- U.S. digital ad spend hit $34 billion in Q4 2024, with social media channels accounting for 77% of total expenditures.
- Mobile gaming preferences shifted toward Strategy and Puzzle titles, with Strategy games seeing a 26% year-over-year increase in downloads to help offset regional revenue declines in Japan and South Korea.
+1
Sensor TowerDec 2024
Report35 pages
Gaming Spotlight H1 2024
Mobile gaming solidifies its position as the leading segment of the global video‑game market, with revenue projected to reach $83 billion in 2024, reflecting a 6 percent year‑over‑year increase. In contrast, home‑console spending is expected to decline by 1 percent to $42 billion, while handheld revenues are slated to fall 2 percent to just under $2.5 billion. The upward trajectory of mobile is driven primarily by rapid expansion in emerging regions such as India and Indonesia, where user acquisition and spending are accelerating faster than in mature markets. Within mobile, fast‑growing sub‑genres—particularly simulators and multiplayer online battle arenas—accounted for $2.34 billion, representing 5.8 percent of total mobile revenue, and achieved a modest 0.4‑point rise in download share during the latest reporting period.
In the United States, monetisation patterns among mobile players continue to favour rewarded‑video advertisements. These ads recorded the highest net‑sentiment score of +20 points and were the most frequently encountered format in the third quarter of 2023. Other ad formats, including playable, native, banner/display, and standard video, lagged behind both in visibility and user sentiment, indicating a clear preference hierarchy that shapes publisher revenue strategies.
Overall, the data underscore a market increasingly centred on mobile platforms, propelled by growth in developing economies and reinforced by user‑friendly ad experiences. Console and handheld segments face modest contractions, suggesting that future investment and innovation will likely concentrate on mobile‑first titles, emerging‑region outreach, and optimisation of rewarded‑video ad ecosystems to sustain growth.
- Mobile gaming remains the dominant market segment with projected 2024 revenues of $83 billion, representing a 6 percent year-over-year increase.
- Home-console and handheld gaming segments are experiencing a decline, with projected revenues of $42 billion (down 1 percent) and $2.5 billion (down 2 percent) respectively.
- Growth in the mobile sector is primarily driven by rapid user acquisition and spending expansion in emerging markets, specifically India and Indonesia.
- Mobile simulators and multiplayer online battle arenas generated $2.34 billion in revenue, accounting for 5.8 percent of total mobile earnings and a 0.4-point increase in download share.
- Rewarded-video advertisements are the most effective monetization format in the U.S. market, achieving the highest net-sentiment score of +20 points during Q3 2023.
+2
Sensor TowerJun 2024
Report45 pages
Digital Market Index: Q2 2024
Global consumer spending reached a record $36.2 billion in the second quarter of 2024, representing an 11.7% year-over-year increase. This growth was primarily propelled by non-gaming applications, which now constitute 46% of total market expenditure. While iOS strengthened its revenue leadership with 13% growth, global download trends remained bifurcated; mature markets like the United States and India experienced stabilization or decline, whereas emerging regions such as Indonesia and Nigeria demonstrated significant expansion. Within the mobile gaming sector, the Strategy genre underwent a major shift, surpassing RPGs as the top-grossing category for the first time since 2017, largely due to the performance of titles like Last War and the successful launch of Squad Busters.
The digital advertising landscape saw United States expenditure exceed $27 billion, with social media channels capturing 76% of that total. TikTok maintained its market dominance, breaking records with over $1.3 billion in quarterly consumer spend while reclaiming the top position for global downloads. Advertising strategies became increasingly aggressive, as evidenced by Tencent’s massive YouTube-centric campaign for Squad Busters. In the retail media space, Walmart maintained a commanding lead with 11.7 billion impressions, though specialized retailers like Best Buy dominated specific niches, such as consumer electronics.
Strategic diversification and co-branded partnerships defined the retail media environment during this period. While Walmart and Target maintained broad influence, brands like L'Oreal successfully scaled advertising efforts across multiple major retailers simultaneously. High-performing collaborations, such as those between Chewy and Purina or Walmart’s partnerships with Kraft Heinz and PepsiCo, underscore a shift toward integrated, multi-platform marketing strategies. These trends indicate a maturing digital economy where non-gaming utility and sophisticated retail media placements are becoming the primary engines of financial growth.
- Global consumer spending reached $36.2 billion in Q2 2024, an 11.7% year-over-year increase driven largely by non-gaming applications, which now account for 46% of total expenditure.
- Strategy games surpassed RPGs as the top-grossing mobile gaming genre for the first time since 2017, bolstered by the performance of titles like Last War and Squad Busters.
- U.S. digital advertising expenditure exceeded $27 billion in Q2 2024, with social media platforms capturing 76% of that total spend.
- TikTok reclaimed the top position for global downloads and set a record with over $1.3 billion in quarterly consumer spending.
- Global download trends are bifurcated, with mature markets like the U.S. and India seeing stabilization or decline, while emerging regions like Indonesia and Nigeria show significant expansion.
Sensor TowerJun 2024
Report31 pages
AI Apps Market Insights 2024
The 2024 AI Apps Market Insights report provides a comprehensive analysis of the global mobile artificial intelligence sector, focusing on download and revenue trends across the App Store and Google Play. Covering the period from January to August 2024, the study examines market distribution, sub-genre performance, and user engagement metrics. Data is derived from Sensor Tower’s proprietary intelligence platforms, excluding advertising revenue and third-party Android store sales.
Global adoption of AI applications has accelerated significantly, with downloads reaching 2.2 billion in the first eight months of 2024 and projected to hit 3.3 billion by year-end. In-app purchase revenue is expected to grow 51% year-over-year to $3.3 billion. While India leads in total downloads with a 21% market share, North America and Europe remain the primary financial drivers, accounting for 68% of total global revenue.
The market is segmented into several high-performing categories, with AI Art Generators emerging as the most profitable sub-genre, capturing 53% of total industry revenue. AI Chatbots follow at 29%, having already surpassed their total 2023 revenue by 1.5 times. A notable trend is the rise of companion AI apps like Character AI and Talkie AI, which boast high user retention; Character AI users average over 1.5 hours of daily use, with a heavy concentration among the 18-24 age demographic.
ChatGPT maintains a dominant position as the leading AI application, reaching a record $45 million in monthly revenue in August 2024 following the launch of GPT-4o. With over 190 million monthly active users and $270 million in cumulative revenue, it serves as the industry benchmark. Beyond general assistants, AI technology is increasingly integrated into specialized fields including education, dating, and music, signaling a broader diversification of the mobile AI ecosystem.
- Global AI app downloads are projected to reach 3.3 billion by the end of 2024, with in-app purchase revenue expected to grow 51% year-over-year to $3.3 billion.
- AI Art Generators dominate the market as the most profitable sub-genre, capturing 53% of total industry revenue, followed by AI Chatbots at 29%.
- ChatGPT remains the industry benchmark with 190 million monthly active users and a record $45 million in monthly revenue as of August 2024.
- North America and Europe generate 68% of total global revenue, while India leads in volume with a 21% share of total downloads.
- AI Chatbot revenue has grown rapidly, already surpassing its total 2023 performance by 1.5 times within the first eight months of 2024.
+1
Sensor TowerMar 2024
Report35 pages
Store Intelligence Data Digest: Q4 2023
Global mobile app performance in the final quarter of 2023 reflected a complex landscape of shifting platform dynamics and regional market evolution. Total worldwide downloads reached 33.4 billion, representing a 6% year-over-year decline primarily attributed to an 8% drop in Google Play installs. Conversely, iOS downloads grew by 1.3%, a trend particularly visible in India. Despite a 13% decline in Google Play installs, India remained the world’s largest mobile market with 6.1 billion downloads, while its growing middle class drove increased iOS adoption. Emerging markets like Nigeria showed the strongest absolute growth on Google Play, while Japan demonstrated exceptional monetization efficiency, leading the world with a revenue-per-download ratio of $23.61 in the manga category.
The competitive landscape was defined by a tension between aggressive user acquisition and long-term retention. TikTok reclaimed its position as the most downloaded app globally, fueled by an 80% surge in China, while the shopping platform Temu dominated Western markets. However, high-growth apps like Temu struggled with user stickiness, maintaining daily engagement rates below 20%. In contrast, established platforms like WhatsApp and Google Chrome proved the most resilient, with WhatsApp achieving a 91% daily engagement rate among its monthly active users. Meta and Google maintained their corporate dominance, bolstered by the launch of Threads and a 38% year-over-year increase in YouTube Kids downloads.
In the gaming sector, Garena Free Fire and Roblox led global downloads with 56 million installs each, while Ludo King remained a powerhouse in the Asian market. The U.S. market saw continued success for Monopoly Go and a significant expansion of Netflix’s gaming portfolio, highlighted by the launch of GTA San Andreas. These trends underscore a maturing global industry where market leaders must balance massive scale in emerging regions with the high-value monetization and retention found in established digital economies.
- Global mobile app downloads fell 6% year-over-year in Q4 2023 to 33.4 billion, driven by an 8% decline in Google Play installs despite a 1.3% increase in iOS downloads.
- India remains the world's largest mobile market with 6.1 billion downloads, though Google Play installs in the region declined by 13% while iOS adoption grew.
- TikTok reclaimed the top spot for global downloads following an 80% surge in China, while Temu dominated Western markets but struggled with user stickiness, maintaining daily engagement rates below 20%.
- Established platforms maintain superior retention, with WhatsApp achieving a 91% daily engagement rate among its monthly active users.
- Japan leads the world in monetization efficiency, recording a revenue-per-download ratio of $23.61 within the manga category.
+1
Sensor TowerMar 2024
Report44 pages
Q1 2024 Digital Market Index
In the first quarter of 2024, the mobile gaming market showed a clear shift away from hyper‑casual titles, which experienced a year‑over‑year decline of more than ten percent across all major platforms. At the same time, niche sub‑genres—particularly those emphasizing deeper mechanics, social interaction, and regional cultural themes—registered modest growth, indicating that players are gravitating toward more differentiated experiences. Revenue concentration continued to favor the top‑tier publishers, whose combined share of global digital game sales rose to just over 45 percent, while mid‑size and indie developers struggled to maintain market visibility amid rising user acquisition costs.
Geographically, North America and Western Europe together accounted for roughly 38 percent of total spend, but the fastest growth rates were observed in Southeast Asia and Latin America, where mobile penetration and improved payment infrastructure drove double‑digit increases in both downloads and in‑app purchases. The overall market size reached $23.7 billion in Q1, representing a 4.2 percent increase from the same period a year earlier, with the majority of the uplift coming from subscription‑based models and live‑ops monetisation strategies.
The data also highlighted a maturing ad‑tech ecosystem: programmatic video ads delivered higher eCPMs than traditional interstitials, while rewarded ads maintained the strongest user retention metrics. However, ad fraud remained a concern, with industry‑wide estimates suggesting that up to 7 percent of ad impressions were non‑genuine, prompting publishers to invest more heavily in verification tools. These trends suggest that the digital gaming landscape is moving toward higher‑value, more engaged user bases, with regional diversification and sophisticated monetisation approaches shaping the next phase of growth.
- The global digital gaming market reached $23.7 billion in Q1 2024, a 4.2% year-over-year increase driven primarily by subscription models and live-ops monetization.
- Top-tier publishers consolidated their market position, capturing over 45% of global digital game sales as mid-size and indie developers faced increased pressure from rising user acquisition costs.
- Mobile gaming trends shifted away from hyper-casual titles, which saw a decline of over 10% year-over-year, in favor of niche sub-genres offering deeper mechanics and social interaction.
- While North America and Western Europe represent 38% of total spend, Southeast Asia and Latin America emerged as the fastest-growing regions with double-digit increases in downloads and in-app purchases.
- Ad-tech performance favored programmatic video for higher eCPMs and rewarded ads for user retention, though 7% of industry-wide ad impressions were identified as non-genuine fraud.
+1
Sensor TowerMar 2024