Mergers & Acquisitions reports and market data
Documents
Corporate Overhaul: Why Does CVC Play a Bigger Role Than Ever?
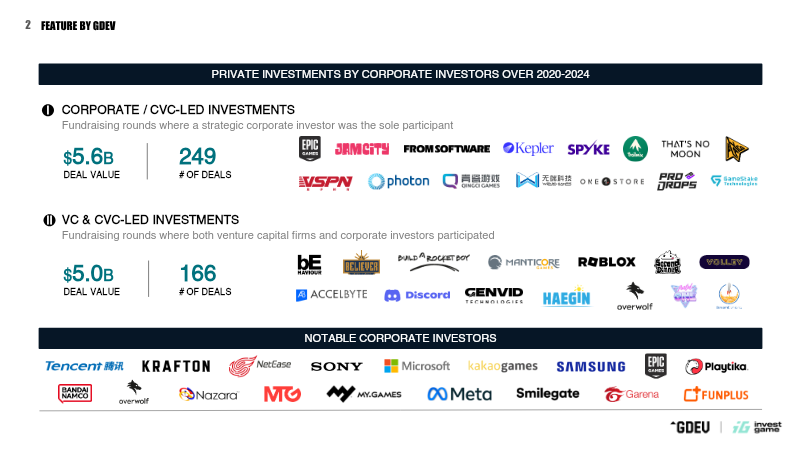
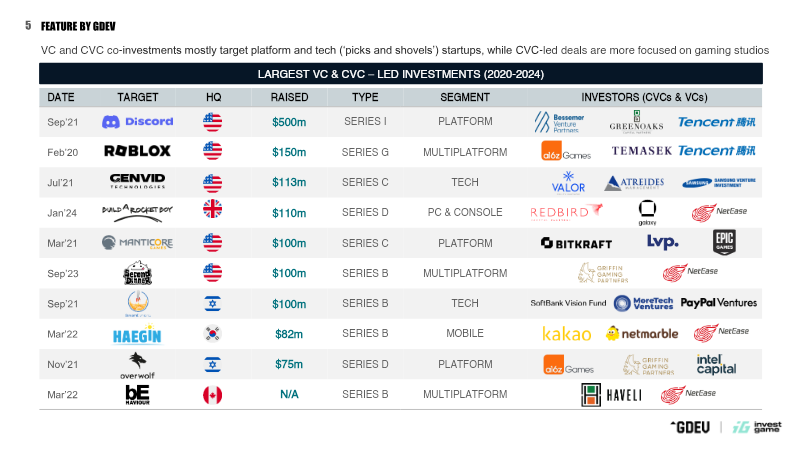
The analysis demonstrates that corporate venture capital (CVC) has become the dominant force in gaming investment from 2020 to 2024, accounting for more than half of all capital raised in the sector.
- Corporate venture capital (CVC) has become the dominant force in gaming investment from 2020 to 2024, accounting for over half of all capital raised with $4.0 billion across 93 CVC-led deals.
- Investment strategies have shifted toward co-investment models between CVCs and traditional VCs, which collectively raised $3.5 billion across 80 deals to spread risk and access high-profile startups.
- Asian firms, specifically from South Korea and Japan, are the most active investors, completing 105 deals worth $1.8 billion and surpassing Western peers in total deal volume.
Week in Mobile Games E42: Brawl Stars' highs, Squad Busters' struggle, & AppLovin's $900m games sale
Supercell has achieved a significant financial turnaround in 2024, reporting €2.78 billion in non-GAAP revenue as every title in its portfolio experienced year-over-year growth for the first time in a decade.
- Supercell reported €2.78 billion in 2024 non-GAAP revenue, marking the first time in a decade that every title in its portfolio achieved year-over-year growth.
- AppLovin is divesting its apps business for $900 million to focus exclusively on its high-growth advertising division, signaling a strategic retreat from direct game development.
- DeNA experienced an 8,000% quarterly profit surge driven by the strong market reception and high player retention of Pokémon Trading Card Game Pocket.
TWIG #318 Supercell’s Records, Unity’s Chaos & AppLovin’s Fire Sale
The global gaming industry is currently navigating a period of profound structural adjustment, characterized by market saturation, declining revenue per user, and a strategic pivot away from high-risk, mega-budget projects.
- AppLovin has exited game development by divesting its studio portfolio for $900 million, a sharp decline from its previous $2.4 billion valuation, to focus exclusively on high-margin, AI-driven ad-tech.
- Supercell generated a record €2.8 billion in revenue, driven by aggressive live-ops and marketing for titles like Brawl Stars, though the strategy faces concerns regarding rising user acquisition costs and long-term sustainability.
- The gaming industry is shifting away from high-risk, mega-budget projects toward sustainable, cash-flow-focused models as founders increasingly prioritize long-term ownership over acquisition-led growth.
Speed Panel: Investment Restart – What Will The M&A Landscape Look Like In 2025?
The gaming industry is poised for a significant resurgence in merger and acquisition activity throughout 2025, marking a departure from the speculative, high-growth environment of the pandemic era.
- M&A activity is expected to increase across all deal sizes in 2025 as founder valuation expectations have become more realistic compared to the inflated levels seen during the COVID-19 pandemic.
- Acquirers are prioritizing companies with approximately $10 million in trailing revenue and credible growth forecasts, shifting away from the previous 'growth at all costs' mentality toward a focus on EBITDA and profitability.
- Private equity firms outside the traditional gaming sector are showing significant interest in the industry, with the expectation that once these firms complete their first acquisition, they will likely pursue multiple follow-on deals.
Session: Investor’s Perspective – What Matters While Considering An Investment Within Mobile...
Acquinox Capital, a Luxembourg-based private equity firm, evaluates investment opportunities in the mobile gaming sector through a dual-fund strategy.
- Acquinox Capital employs a dual-fund strategy, utilizing a deal-by-deal co-investment model alongside the Quantum Tech Growth Fund to target vertical integration across the gaming value chain.
- The firm targets a broad investment scope ranging from early-stage growth ventures to mature buyouts, with initial ticket sizes starting at 250,000 Euro.
- Investment evaluation is driven by a six-pillar framework that assesses leadership, business model viability, intellectual property, financial health, historical capital usage, and cap table structure.
The State of Video Game Financing in 2025
The gaming industry is currently navigating a profound market correction, characterized by a 14 percent year-over-year decline in deal volume and a significant contraction in Series A graduation rates to 11.5 percent.
- The gaming industry is experiencing a market correction marked by a 14 percent year-over-year decline in deal volume and a contraction in Series A graduation rates to 11.5 percent.
- Venture capital firms are shifting investment focus away from content creation toward infrastructure, creating a structural funding crisis for mid-to-late-stage studios.
- The industry is transitioning from a high-growth, speculative model to a disciplined environment that prioritizes capital efficiency, fiscal restraint, and proven execution over rapid scaling.
TWIG #317: Big Dream, Bigger Battlefield, and the Biggest Roblox M&A deal EVER
The gaming industry is currently navigating a period of significant structural recalibration, marked by a shift away from speculative metaverse narratives toward more pragmatic, platform-specific growth strategies.
- The gaming industry is pivoting from speculative metaverse narratives toward pragmatic growth within established ecosystems like Roblox and Epic Games.
- Roblox faces significant financial challenges, specifically low monetization per user and persistent unprofitability when accounting for stock-based compensation.
- Dream Games is seeking a $5 billion valuation, reflecting a broader industry tension between high private valuations and the diminishing availability of lucrative exit opportunities.
2025 Gaming Industry Report: M&A and Fundraising Update
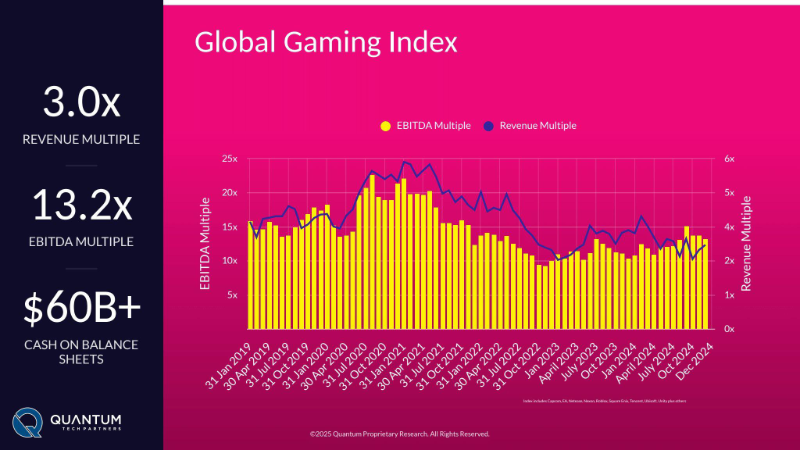
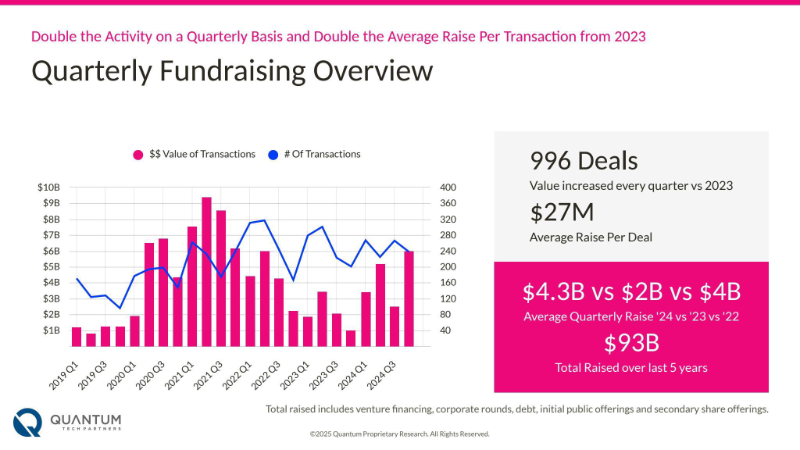
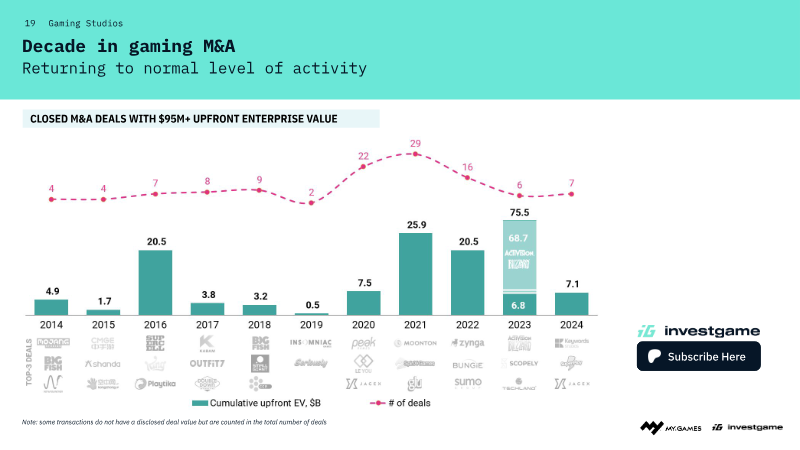
The gaming industry has entered a period of stabilization, with merger and acquisition activity settling at $11.5 billion.
- Fundraising reached $17.2 billion in 2024, a 102% year-over-year increase that reflects a trend toward larger, more concentrated capital investments.
- Merger and acquisition activity has stabilized at $11.5 billion, marking a return to pre-pandemic valuation norms following post-2022 market corrections.
- Investor capital is increasingly shifting toward artificial intelligence and Web3 technologies, while the eSports sector faces a 66% decline in funding.
Gaming CEO Survey: 2024 in Review
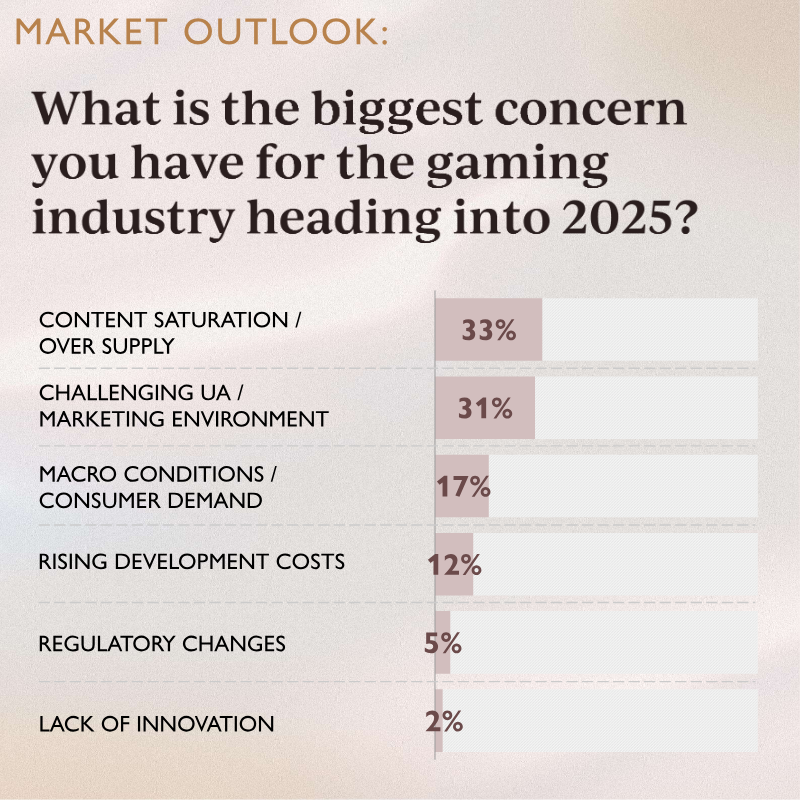
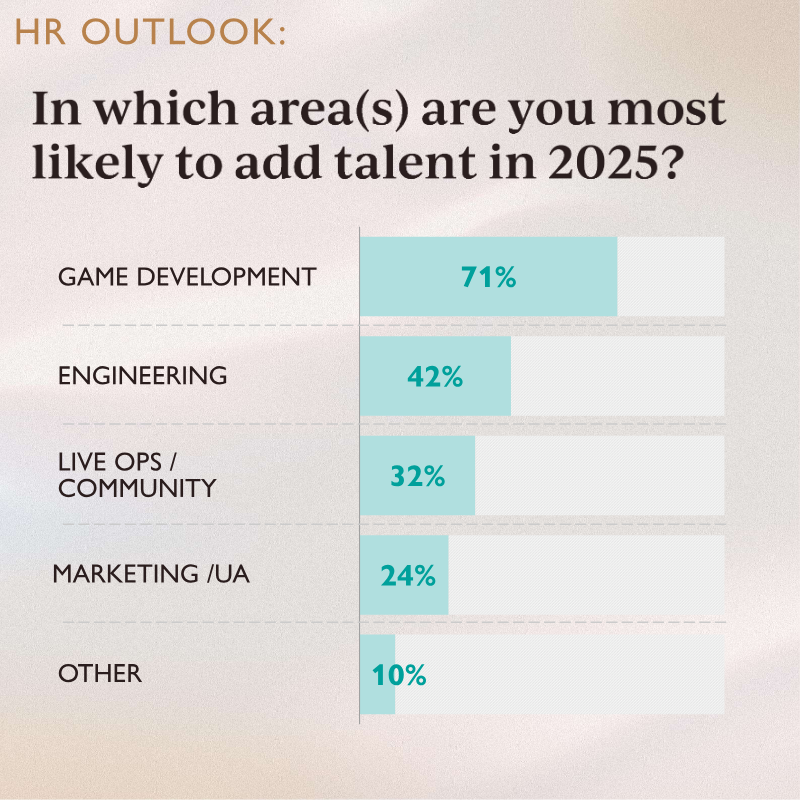
The 2024 gaming industry executive survey reveals a landscape defined by cautious optimism and strategic expansion.
- Industry leadership is optimistic for 2025, with 98% of executives expecting consumer spending to increase or remain stable.
- AI adoption is widespread, with 84% of companies already implementing the technology across functions like art, game design, and engineering.
- The M&A landscape is expected to intensify, as 71% of executives anticipate more deal-making opportunities in 2025 compared to the previous year.


Mobile Gaming M&A Playbook: How to Identify and Target High‑Growth Gaming Companies
The playbook outlines a systematic approach for mobile gaming publishers and investors to identify, evaluate, and acquire high-growth developers.
- The mobile gaming market is projected to reach $138 billion by 2025, driving significant M&A activity as publishers seek to diversify portfolios and acquire new talent and intellectual property.
- High-profile acquisitions demonstrate the scale of industry consolidation, including Zynga’s $2 billion purchase of Peak Games and EA’s $2.1 billion acquisition of Glu Mobile.
- Effective target identification requires a data-driven approach using platforms like Sensor Tower to track specific genre trends, revenue trajectories, and regional market share.
InvestGame Q4'24 Report (Unknown Time)
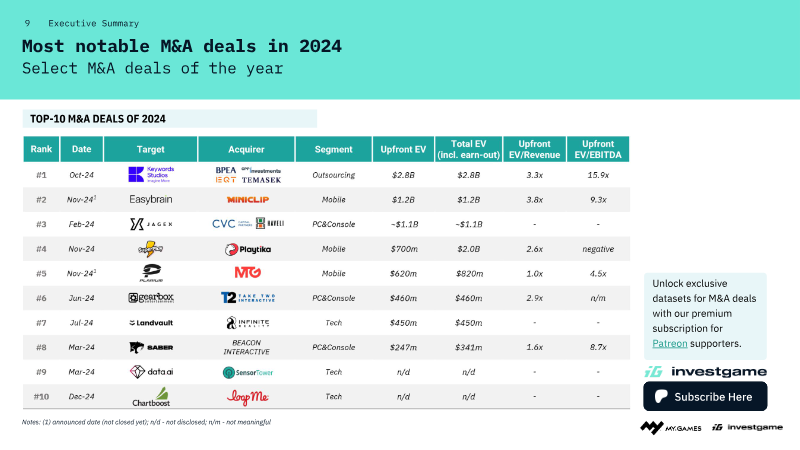
The gaming industry experienced a strategic shift in 2024, moving away from short-term financial arbitrage toward long-term, objective-driven transactions.
- The gaming industry is shifting toward long-term, objective-driven transactions, evidenced by a strong Q4 2024 M&A market and a 22% year-over-year increase in private investment funding.
- Venture capital is pivoting away from game development studios in favor of platform and technology startups, forcing corporate venture arms to become the primary source of studio financing.
- The work-for-hire sector is seeing major consolidation, underscored by the $2.8 billion buyout of Keywords.
Interview with Frank Kang, Associate Partner at Antler: Malaysia
Korean content and entertainment startups are being urged to treat Southeast Asia as a primary growth engine rather than a peripheral market.
- Korean entertainment and content startups must treat Southeast Asia as a primary growth engine rather than a peripheral market to achieve sustainable expansion.
- Success requires deep localisation through local 'co-pilots' to navigate fragmented linguistic, regulatory, and payment landscapes in key hubs like Jakarta, Manila, and Bangkok.
- Revenue models should shift toward mobile-wallet-driven micro-transactions, live-commerce, and hybrid free-plus-premium structures to align with local consumption habits.