Key insights
5 slides
Market Correction
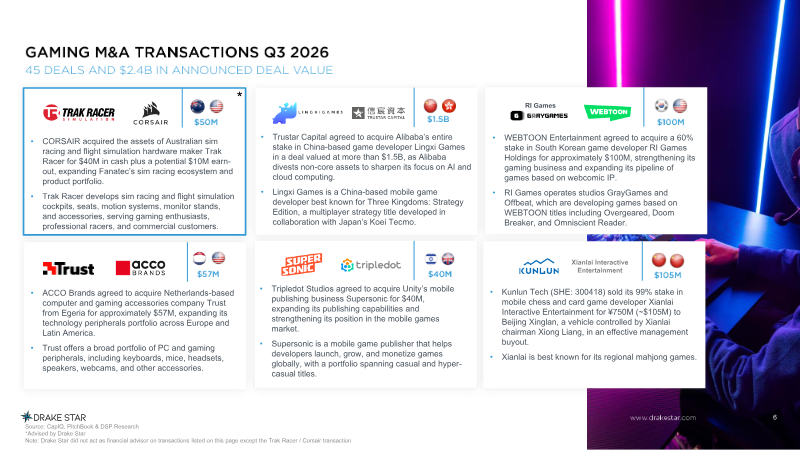
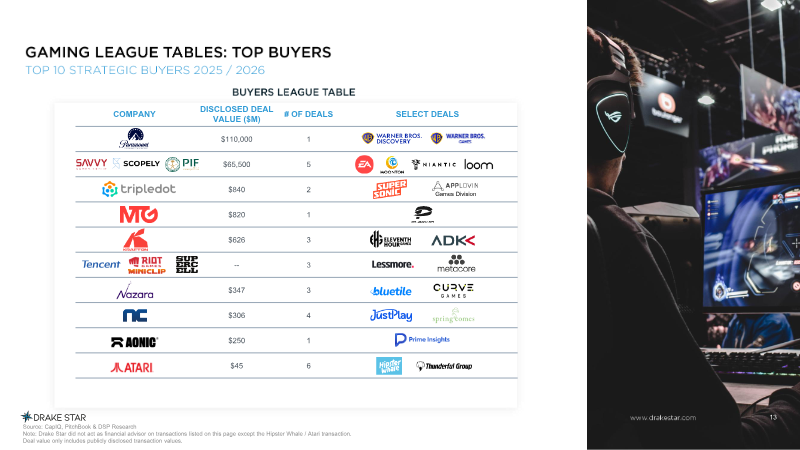
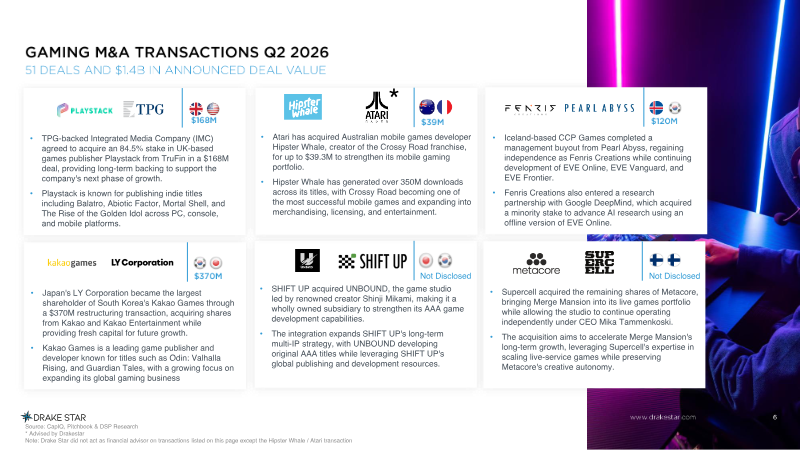
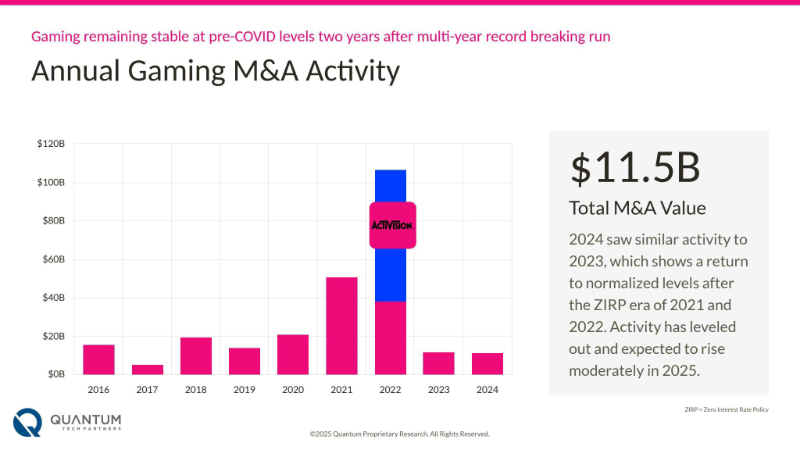
Merger and acquisition activity has stabilized at $11.5 billion.
This valuation reflects a return to pre-pandemic norms. This follows market corrections observed after 2022.
1 / 5
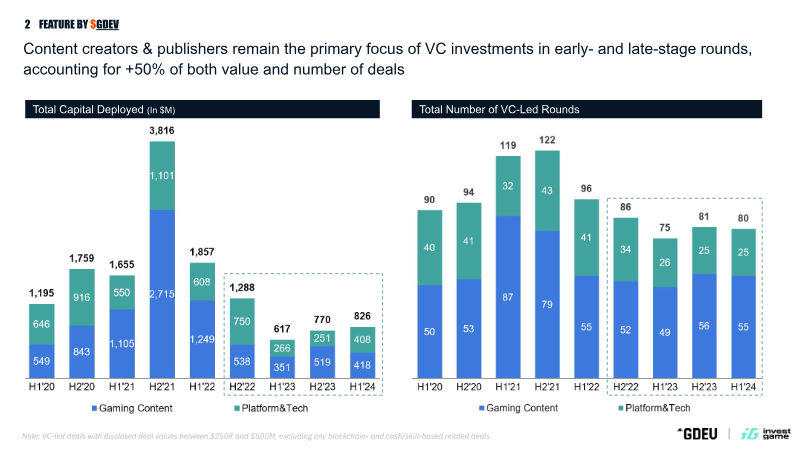
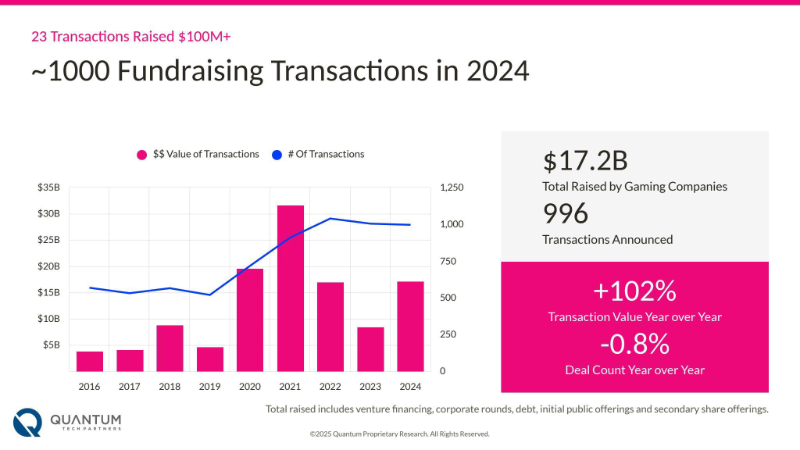
- 01Fundraising reached $17.2 billion in 2024, a 102% year-over-year increase that reflects a trend toward larger, more concentrated capital investments.See it on page 22
- 02Merger and acquisition activity has stabilized at $11.5 billion, marking a return to pre-pandemic valuation norms following post-2022 market corrections.See it on page 13
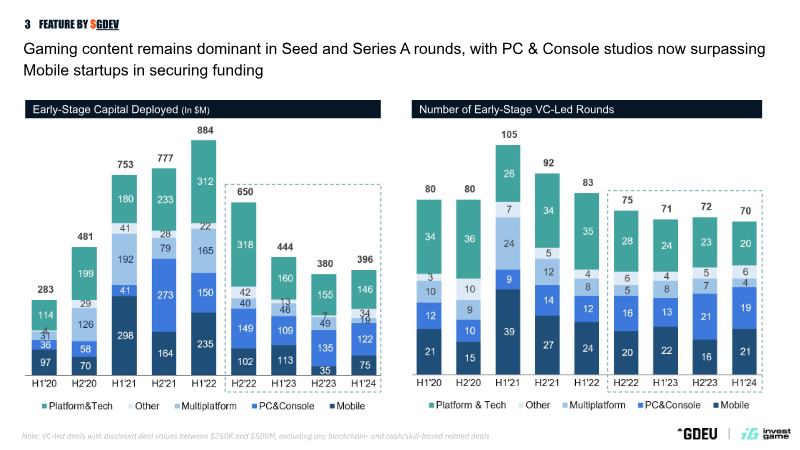
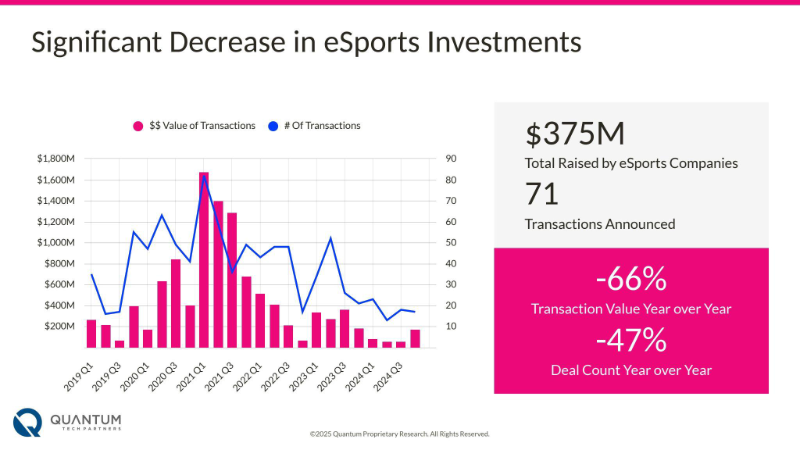
- 03Investor capital is increasingly shifting toward artificial intelligence and Web3 technologies, while the eSports sector faces a 66% decline in funding.See it on page 30
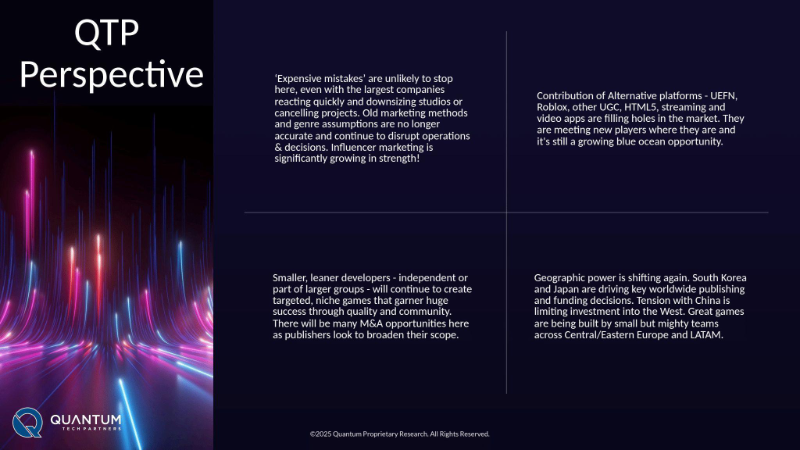
- 04Growth drivers are migrating away from traditional models toward smaller, agile independent developers and emerging platforms like Roblox and UEFN.See it on page 5
- 05Despite a 102% increase in total capital raised, the total number of fundraising deals remained flat throughout 2024.See it on page 22
Ask AI about this report
Summary
The gaming industry has entered a period of stabilization, with merger and acquisition activity settling at $11.5 billion. This valuation reflects a return to pre-pandemic norms following the market corrections observed after 2022. While total deal volume remains modest, the sector is undergoing a structural shift as growth drivers migrate away from traditional models toward smaller, agile independent developers and emerging platforms such as Roblox and UEFN. These alternative ecosystems are increasingly capturing market share and defining the new trajectory for industry revenue.
Fundraising efforts experienced a robust recovery throughout 2024, with total capital reaching $17.2 billion. This represents a 102% year-over-year increase, even as the total number of deals remained flat, indicating a trend toward larger, more concentrated investments. Strategic capital allocation is currently favoring artificial intelligence and Web3 technologies, which have emerged as the primary focal points for investors. Conversely, the eSports sector has faced significant headwinds, evidenced by a 66% decline in funding as capital flows away from traditional competitive gaming models.
These trends underscore a broader transition toward specialized, high-growth segments within the global gaming market. As strategic acquisitions and divestments continue to reshape the competitive landscape, the necessity for expert advisory services has become paramount for firms seeking to navigate complex deal structures and capital acquisition. By prioritizing strategic preparation and aligning with evolving technological trends, stakeholders are better positioned to capitalize on the industry’s current phase of disciplined growth and structural realignment.