Market Analysis
Documents
An Analysis of the Card Battler Sub‑Genre 2021
The card battler mobile sub-genre experienced significant growth and market shifts during the first half of 2021. While representing five percent of player spending within the broader strategy genre, card battlers reached a new revenue baseline exceeding $55 million per month. This growth was punctuated by a 17 percent quarterly revenue increase in early 2021, driven largely by established "forever franchises" and the successful mobile launch of legacy intellectual properties.
The geographic landscape of the sub-genre is diversifying. Although Asian markets like Japan and China historically dominated the space, the United States emerged as a critical growth region, accounting for 27 percent of player spending in the first half of 2021. The U.S. market also demonstrated the highest growth in revenue per download among strategy sub-genres, rising 53 percent. This trend suggests the market is maturing and becoming increasingly lucrative for developers targeting Western audiences.
Market leadership remains concentrated among titles leveraging powerful intellectual properties. Yu-Gi-Oh! Duel Links and Hearthstone continue to lead in lifetime earnings, while Magic: The Gathering Arena rapidly ascended to the top ten following its March 2021 release. The success of these titles, alongside niche performers like WWE SuperCard and the high download volume of Mighty Party, indicates a healthy appetite for both established tabletop conversions and new gameplay concepts.
The analysis utilizes data from Sensor Tower’s Game Intelligence and Store Intelligence platforms, covering global App Store and Google Play performance. Findings highlight that while the sub-genre is smaller than 4X strategy or MOBA categories, its increasing average revenue per user and the success of aggressive user acquisition strategies by new contenders point to significant ongoing opportunities for expansion.
- The card battler sub-genre reached a new revenue baseline exceeding $55 million per month in the first half of 2021, driven by a 17 percent quarterly revenue increase.
- The United States has become a critical market, accounting for 27 percent of global player spending and experiencing a 53 percent increase in revenue per download during the first half of 2021.
- Market leadership is dominated by established intellectual properties, with Yu-Gi-Oh! Duel Links and Hearthstone leading in lifetime earnings and Magic: The Gathering Arena entering the top ten shortly after its March 2021 launch.
- While card battlers represent five percent of total strategy genre spending, the sub-genre shows significant expansion potential due to rising average revenue per user and effective user acquisition strategies.
- The sub-genre demonstrates a healthy appetite for diverse gameplay, ranging from tabletop-to-mobile conversions like Magic: The Gathering Arena to high-volume download titles like Mighty Party and niche performers like WWE SuperCard.
Newzoo Metaverse Report 2021
The metaverse represents the evolution of gaming from a service into a persistent, infinitely scaling platform characterized by social interaction, user-generated content, and functioning economies. Driven by technological advancements and the social shifts of the COVID-19 era, virtual spaces now host non-gaming activities like concerts and brand activations that attract tens of millions of participants. This transition is supported by a highly receptive consumer base, with 70% of gamers expecting these social hubs to increase their playtime. The industry is moving toward a direct-to-avatar economy where digital identity and creator-led markets are central to engagement across platforms like Roblox, Fortnite, and Avakin Life.
Blockchain technology serves as a primary catalyst for this shift, enabling decentralized economies and play-to-earn models that provide players with true digital ownership. While current hurdles include high transaction fees and environmental concerns associated with early NFT models, the sector is transitioning toward scalable, green solutions like Layer 2 protocols. Establishing interoperable digital identities and seamless marketplaces is essential for aligning the economic interests of developers and creators. Furthermore, the move toward Web 3.0 requires a shift in the digital supply chain toward player-owned assets and open standards, such as Pixar’s Universal Scene Description, to ensure cross-platform collaboration.
Despite this momentum, significant structural and technical challenges remain. Achieving massive concurrency—moving beyond sharded instances to thousands of users in a single persistent world—requires cloud-native infrastructure and radical improvements in network protocols. Additionally, the industry must navigate regional fragmentation caused by government regulations and the need for modernized IP laws. Ethical risks, including deepfakes, unmoderated content, and identity theft, necessitate a focus on safety and open standards. Ultimately, the games industry is positioned to lead the development of a mobile-accessible, community-driven metaverse that complements physical reality through democratized monetization and high-fidelity digital twins.
- The metaverse is evolving gaming into a persistent, scalable platform for social interaction and non-gaming activities, with 70% of gamers anticipating increased playtime in these virtual hubs.
- The industry is shifting toward a direct-to-avatar economy where digital identity and creator-led markets drive engagement on platforms such as Roblox, Fortnite, and Avakin Life.
- Blockchain technology is facilitating decentralized economies and play-to-earn models, with the sector currently transitioning toward scalable, green Layer 2 protocols to address transaction costs and environmental concerns.
- Achieving a true metaverse requires overcoming technical barriers to massive concurrency, specifically moving beyond sharded instances to support thousands of simultaneous users through cloud-native infrastructure.
- Cross-platform collaboration and the Web 3.0 digital supply chain depend on the adoption of open standards, such as Pixar’s Universal Scene Description, to enable interoperable digital identities and player-owned assets.
Video Games – a Force for Good (2021)
The 2021 Key Facts report, a joint publication by ISFE and EGDF, provides a comprehensive analysis of the European video game industry’s market performance, player demographics, and social impact. Covering the 2021 calendar year with comparative data from 2020, the report focuses on the European Union and broader European markets, including the United Kingdom. Data is derived from Ipsos, GameTrack, and Games Sales Data (GSD), utilizing surveys and retail tracking across more than 20 European nations.
The findings indicate a stable market valued at €23.3 billion, maintaining the significant revenue gains achieved during the 2020 pandemic lockdowns. While the total number of players grew by 6% to reach 52% of the European population, average weekly playtime decreased to 9 hours, returning to pre-pandemic levels. The digital ecosystem dominates the sector, accounting for 81% of total revenue, driven largely by app-based gaming and in-game extras. Demographically, the average player age is 31.3 years, and women represent nearly 48% of the total player base.
Beyond economic metrics, the report emphasizes the industry’s commitment to social responsibility and sustainability. It highlights the widespread adoption of the PEGI age rating system and the effectiveness of parental control tools, noting a significant decrease in unauthorized in-game spending by minors. The document also outlines industry-wide initiatives to improve workforce diversity, where women currently make up 22% of employees, and details environmental efforts such as the Green Game Jam and the Games Consoles Voluntary Agreement to reduce energy consumption. Finally, the report identifies esports as a high-growth segment, with global revenues surpassing $1 billion in 2021.
- The European video game market maintained a stable valuation of €23.3 billion in 2021, successfully sustaining the revenue gains achieved during the 2020 pandemic.
- Digital sales dominate the industry, accounting for 81% of total revenue, with growth primarily driven by app-based gaming and in-game purchases.
- The European player base grew by 6% in 2021 to encompass 52% of the total population, with an average player age of 31.3 years and a gender split of 48% women.
- Average weekly playtime dropped to 9 hours in 2021, signaling a return to pre-pandemic engagement levels despite the increase in total player count.
- Esports emerged as a high-growth sector, with global revenues exceeding $1 billion during the 2021 calendar year.
Match3 Genre Snapshot Report May 2021 (2021)
The Match3 subgenre represents the largest segment of the US iOS mobile gaming market, accounting for approximately 16% of total revenue as of mid-2021. While established titles have dominated the charts for years, the landscape is evolving through the integration of complex meta-layers and sophisticated monetization strategies. Notably, every new Match3 title that entered the top 500 grossing rankings between late 2019 and early 2021 utilized traditional swapping mechanics, signaling a preference for familiar core gameplay enhanced by modern secondary features.
Meta-elements, particularly customization and decoration, have become essential components of modern Match3 success. Recent megahits like Royal Match and Project Makeover demonstrate this trend by blending core puzzle mechanics with narrative progression and aesthetic choices. Beyond gameplay, monetization has shifted toward loss aversion mechanics and diverse live operations. Data indicates that recurring live events, special event rewards, and limited-time in-app purchase offers have the highest impact on revenue. Social features, including guild mechanics and "send/ask help" systems, further bolster engagement and retention within the subgenre.
Player motivation analysis, based on a survey of over 7,000 mobile gamers across major English-speaking markets, reveals distinct psychological drivers. While traditional titles like Candy Crush Saga rely heavily on the "Thinking & Solving" and "Completing Milestones" drivers, the broader Match3 market is increasingly leaning into "Customization & Decoration." This shift highlights a move away from pure puzzle-solving toward a more expressive and multi-layered player experience. The findings suggest that future growth in the category depends on balancing core puzzle mastery with social competition and deep meta-progression.
- As of mid-2021, the Match3 subgenre is the largest segment of the US iOS mobile gaming market, generating approximately 16% of total revenue.
- Every new Match3 title that entered the top 500 grossing rankings between late 2019 and early 2021 retained traditional swapping mechanics, confirming that core gameplay innovation is less critical than secondary feature integration.
- Success in the modern market is driven by meta-layers like customization and decoration, as evidenced by the performance of titles such as Royal Match and Project Makeover.
- Revenue optimization in the subgenre is currently driven by loss aversion mechanics, recurring live events, special event rewards, and limited-time in-app purchase offers.
- Player motivation has shifted from pure puzzle-solving toward expressive experiences, with 'Customization & Decoration' now serving as a primary psychological driver alongside traditional 'Thinking & Solving' and 'Completing Milestones' goals.
Newzoo Trends to Watch 2021
This analysis outlines the primary trends shaping the global games, esports, and mobile markets for 2021. The central thesis posits that while the COVID-19 pandemic accelerated engagement and spending, these behaviors have become permanent habits that will sustain market growth even as lockdowns ease. By the end of 2021, the global games market is projected to reach $189.3 billion in revenue, supported by a player base of 2.8 billion people, with significant growth emerging from Southeast Asia and the Middle East.
The scope of the findings covers PC, console, and mobile segments across major global regions, including North America, Europe, China, and emerging markets. Key data points include the rise of cloud gaming, which is expected to surpass $1 billion in annual revenue for the first time, and the rapid expansion of 5G technology, with 5G-ready active smartphones forecasted to grow from 5% in 2020 to 16% (700 million units) by the end of 2021. In the esports sector, mobile titles like PUBG Mobile and Garena Free Fire are now challenging traditional PC giants in viewership, signaling a shift toward mobile-first competitive gaming.
Methodologically, the findings are derived from proprietary market models and consumer research. The analysis highlights several structural shifts: the evolution of games into "metaverse" social platforms for non-gaming events, the disruption of mobile marketing due to the removal of Apple’s Identifier for Advertisers (IDFA), and the increasing pressure on traditional app store revenue-share models. Furthermore, the industry is noted to be prioritizing diversity, inclusion, and reduced toxicity in response to social movements and player demand. Ultimately, the convergence of platforms and the expansion of gaming IP into broader entertainment media are identified as the defining characteristics of the industry's trajectory.
- The global games market is projected to reach $189.3 billion in revenue by the end of 2021, supported by a permanent shift in consumer spending habits and a total player base of 2.8 billion people.
- Cloud gaming is expected to surpass $1 billion in annual revenue for the first time in 2021, while 5G-ready active smartphones are forecasted to grow from 5% in 2020 to 16% (700 million units) by year-end.
- Mobile titles such as PUBG Mobile and Garena Free Fire are increasingly challenging traditional PC giants in esports viewership, marking a significant shift toward mobile-first competitive gaming.
- The removal of Apple’s Identifier for Advertisers (IDFA) is disrupting mobile marketing strategies and intensifying industry pressure on traditional app store revenue-share models.
- Gaming platforms are evolving into 'metaverse' social hubs for non-gaming events, while industry leaders are increasingly prioritizing diversity, inclusion, and reduced toxicity in response to player demand.
Innovate to Win on the Next Level with Hybrid Genre Games
The global mobile gaming landscape has entered a period of sustained growth following the pandemic, with overseas consumer spending reaching $36 billion in the first half of 2021. This represents a 73% increase since 2018, a trend largely spearheaded by China-based publishers who now command a 23% share of the international market. To sustain this trajectory, the industry is shifting toward hybridization, a strategy that blends core mechanics from disparate subgenres to broaden player demographics and optimize revenue streams. By integrating casual elements like farming or social multiplayer features into hardcore frameworks, developers are successfully diversifying their monetization models beyond traditional structures.
Market performance in early 2021 reveals that while Strategy, RPG, and Match subgenres remain the primary revenue drivers, high-growth categories such as Luck Battle and Merge-Saga are emerging as significant leaders. The 4X March-Battle subgenre, in particular, saw a 51% year-over-year increase in consumer spend, fueled by strong performance in the United States, Japan, and Germany. Additionally, the Idol Training subgenre experienced an explosive 129% surge in spending, highlighting the rising influence of Asian cultural themes and "Nijigen" aesthetics in the global market.
Despite these gains, the industry faces challenges from evolving user privacy policies, which contributed to a 12% contraction in Puzzle RPG spending. In response, successful developers are increasingly utilizing hybrid tactics such as Gacha monetization, home design meta-layers, and social connectivity to maintain engagement. The transition toward these multifaceted game designs suggests that the future of mobile gaming lies in the ability to merge deep, mid-core progression systems with accessible, casual mechanics to capture a more diverse and resilient global audience.
- Mobile gaming consumer spending reached $36 billion in H1 2021, marking a 73% increase since 2018, with China-based publishers now capturing 23% of the international market.
- The industry is pivoting toward hybrid game design, which integrates casual mechanics like farming or social features into hardcore frameworks to diversify monetization and broaden demographics.
- The Idol Training subgenre saw a 129% surge in consumer spending, signaling the growing global influence of Asian cultural themes and 'Nijigen' aesthetics.
- The 4X March-Battle subgenre experienced a 51% year-over-year increase in spending, driven by strong performance in the United States, Japan, and Germany.
- Evolving user privacy policies have negatively impacted specific categories, evidenced by a 12% contraction in Puzzle RPG spending.
Hyper-Casual Games – Industry Snapshot
The 2020 Hyper-Casual Sub-Genre Snapshot provides a detailed analysis of the hyper-casual mobile gaming market, focusing on performance benchmarks and sub-genre classification. Utilizing data from a network of over 140,000 integrated games and 2 billion monthly players, the analysis categorizes the industry into distinct mechanics: Timing, Traversal, Physics, Shooting, Spatial, Crafting, and Matching. The primary objective is to establish actionable KPIs for developers to optimize game development and monetization strategies.
Geographic data reveals significant variations in player engagement and retention. European markets, specifically France, Germany, Italy, and the Netherlands, lead in Day 1 retention at 49%. However, Japan emerges as a dominant market for deep engagement, boasting the highest Day 7 retention at 19% and a leading average playtime of 63 minutes. In contrast, the United States shows moderate performance with 43% Day 1 retention and 43 minutes of playtime, while China lags behind in these specific engagement metrics.
The findings highlight the dominance of specific titles launched in 2020, such as High Heels! and Slap Kings, which achieved high performance scores through simple, portrait-oriented, and advertising-focused business models. Successful games in this category are characterized by short, satisfying gameplay loops and forgiving mechanics. A critical benchmark for developers is the 40% Day 1 retention threshold; titles falling below this mark are generally considered unpromising, necessitating either rapid iterative sprints or project termination to maintain development efficiency.
- A 40% Day 1 retention rate serves as the critical performance benchmark for hyper-casual titles; games falling below this threshold should be iterated upon immediately or terminated.
- European markets lead in short-term engagement with a 49% Day 1 retention rate, while Japan excels in long-term retention at 19% and average session lengths of 63 minutes.
- The United States market shows moderate engagement metrics, recording a 43% Day 1 retention rate and an average playtime of 43 minutes.
- Successful 2020 titles like High Heels! and Slap Kings demonstrate that high performance is driven by portrait-oriented design, short gameplay loops, and advertising-focused monetization.
- The hyper-casual industry is categorized into seven core mechanics: Timing, Traversal, Physics, Shooting, Spatial, Crafting, and Matching.
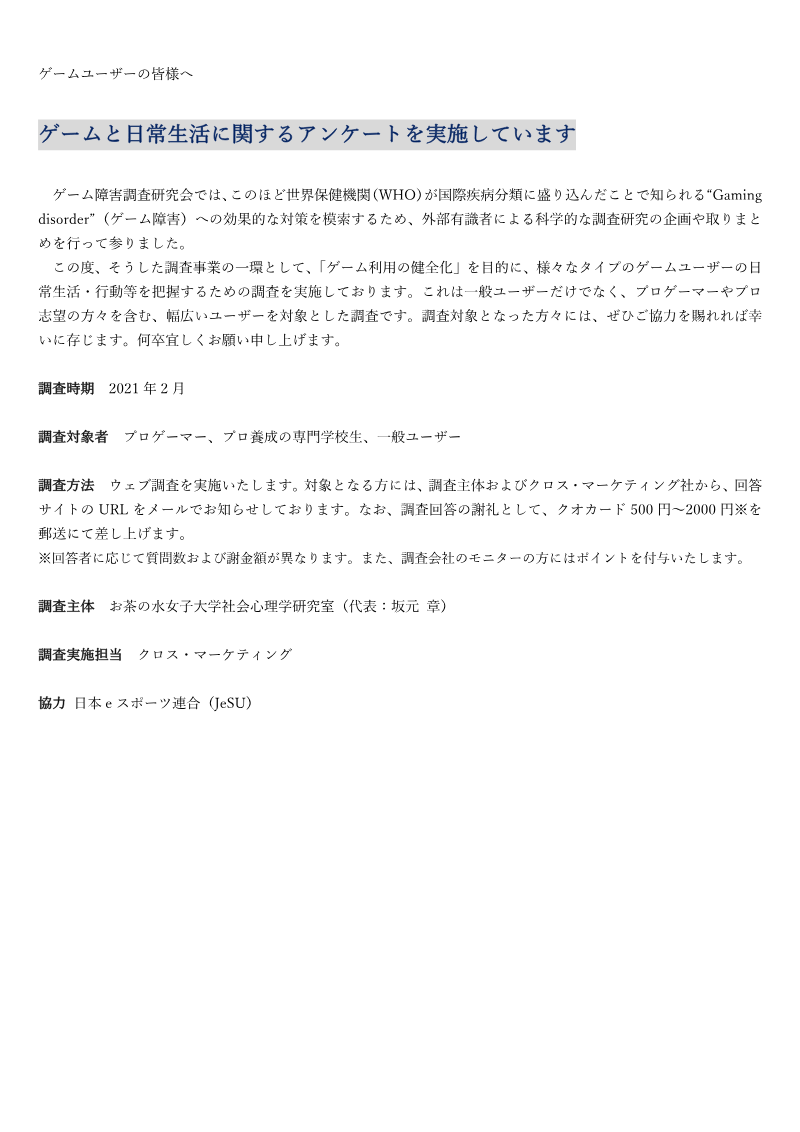
Survey on Games and Daily Life: Japan
The survey was launched to deepen understanding of how gaming activities intersect with everyday life in Japan and to inform strategies for mitigating “gaming disorder,” a condition recently classified by the World Health Organization. Its overarching aim is to promote healthier gaming habits across a broad spectrum of participants, ranging from casual players to professional gamers and students enrolled in specialized esports training programs.
Fieldwork took place in February 2021 and targeted three distinct groups: active professional gamers, individuals attending dedicated esports academies, and the general gaming public. Data were collected through an online questionnaire distributed via email by the research team and Cross‑Marketing, with respondents directed to a secure response site. To encourage participation, incentives varied from ¥500 to ¥2,000 Quo‑card vouchers, supplemented by point awards for panel members of the survey firm.
The investigation was coordinated by the Social Psychology Laboratory at Ochanomizu University, under the leadership of Professor Akira Sakamoto, with operational support from Cross‑Marketing and endorsement from the Japan eSports Union (JeSU). Although specific results are not disclosed in the excerpt, the study’s design reflects a comprehensive, mixed‑audience approach intended to generate actionable insights for policy makers, health professionals, and the esports industry regarding responsible gaming practices in Japan.
- The study, conducted in February 2021, aimed to analyze the intersection of gaming and daily life to inform strategies for mitigating gaming disorder.
- Research was led by Professor Akira Sakamoto of the Social Psychology Laboratory at Ochanomizu University with endorsement from the Japan eSports Union (JeSU).
- The survey targeted three distinct demographics: active professional gamers, students in specialized esports academies, and the general gaming public.
- Data collection was facilitated through an online questionnaire managed in partnership with the research firm Cross-Marketing.
- Participation was incentivized through a combination of point awards and Quo-card vouchers ranging in value from ¥500 to ¥2,000.
Serbian Gaming Industry Report 2021
In 2021 Serbia’s gaming ecosystem emerged as a rapidly expanding, export‑oriented sector that combined a sizable studio base with a vibrant indie community. Roughly 130 development studios employed 1,548 people, of whom 30 % were women, and produced about 2,200 titles that generated an estimated US$125 million in revenue. The majority of earnings—between 75 % and 100 %—derived from markets outside the country, and 64 % of games relied on a free‑to‑play model supplemented by advertising.
Mid‑sized studios such as Nordeus and Playrix RS demonstrated strong user bases, while larger contributors including Ubisoft Belgrade and the VFX house Bunker underscored Serbia’s capacity to support AAA‑level production and international client work. The esports landscape, led by Fortuna’s Balkan League, attracted roughly half a million viewers and distributed €220 k in prize money, highlighting the sector’s growing competitive dimension. Indie developers, ranging from solo creators to teams of forty, pursued diverse platforms—PC, mobile, VR/AR—and increasingly leveraged tools like Epic’s MetaHuman Creator, signalling a shift toward high‑fidelity, narrative‑driven experiences.
Policy initiatives reinforced this momentum. The “Serbia Innovates” super‑cluster, backed by U.S. assistance, positioned gaming, VR, and Web3 technologies as a multidisciplinary hub, while tax‑incentive reforms such as the IP‑Box and double R&D deductions attracted capital and talent. Educational collaborations, exemplified by new university programs and industry‑led training platforms, created a pipeline that bridges skill gaps and sustains growth.
Sustainable development is viewed as dependent on three pillars: compelling IP, robust publishing partnerships, and cross‑sector cooperation, suggesting that continued alignment of studio capabilities, policy support, and talent development will cement Serbia’s role as a notable exporter in the global games market.
- In 2021, Serbia’s gaming sector comprised approximately 130 studios employing 1,548 people, generating $125 million in revenue with 75% to 100% of earnings derived from international exports.
- The industry is heavily reliant on the free-to-play model, which accounts for 64% of all games produced, while the total output reached roughly 2,200 titles.
- The ecosystem supports a diverse production scale, ranging from indie developers using high-fidelity tools like MetaHuman Creator to major contributors such as Nordeus, Playrix RS, and Ubisoft Belgrade.
- Government policy has actively fostered growth through tax incentives like the IP-Box and double R&D deductions, alongside the 'Serbia Innovates' super-cluster initiative.
- The esports sector is a significant competitive pillar, with the Fortuna-led Balkan League attracting 500,000 viewers and distributing €220,000 in prize money.
Romanian Game Development Industry Report: 2020
The Romanian game‑development sector has emerged as a rapidly expanding component of the national digital economy, delivering €218.5 million in revenue in 2020—a 19.1 % year‑on‑year increase that pushed total earnings beyond the €200 million threshold. This growth builds on a foundation laid in the late‑1990s by early publishers such as AMC and Fun Labs and accelerated by a wave of indie activity that has diversified the market across hyper‑casual, mid‑core and AAA support segments.
Policy measures have been pivotal: a tax‑exempt status for developers introduced in 2004, a state‑aid scheme for large IT investments in 2012, and the “Startup Nation” programme of 2016 have collectively fostered an IT sector employing over 113 000 people and contributing roughly 6.8 % of GDP in 2020. The exemption, however, applies only to technical staff, leaving creative roles under‑supported and prompting the Romanian Game Developers Association to propose dedicated incentives.
The ecosystem now includes hyper‑casual studios that have amassed more than 10 million downloads, mid‑core and AAA support firms such as EA Romania, Ubisoft Romania and Gameloft that together employ around 750 developers and work on franchises like FIFA and Assassin’s Creed, and independent studios such as Ovilex, whose simulators have exceeded 500 million installs.
Case studies illustrate the sector’s breadth: Whyttest operates a cross‑border QA‑outsourcing service with senior and junior testers in Bucharest and Belgrade, while XSA, an indie start‑up focused on Android/iOS car games, reaches over one million players each month. The analysis draws on multiple European industry sources, including ISFE‑EGDF, EGDF, Goldstein Research, and regional surveys, providing a comprehensive view of Romania’s game‑development landscape during the 2020 period.
- The Romanian game development industry generated €218.5 million in revenue in 2020, marking a 19.1% year-on-year growth rate.
- The broader IT sector, bolstered by state-aid schemes and tax exemptions, employed over 113,000 people and contributed approximately 6.8% of Romania's GDP in 2020.
- Major AAA support studios including EA Romania, Ubisoft, and Gameloft employ roughly 750 developers in the country, contributing to global franchises like FIFA and Assassin’s Creed.
- Independent studios have achieved significant scale, with firms like Ovilex recording over 500 million installs for their simulator titles.
- Current tax-exempt status for developers is limited to technical staff, leading the Romanian Game Developers Association to lobby for new incentives to support creative roles.
La Guía de los Esports
Resumen ejecutivo de “La Guía de los Esports” (Basado en los ocho apartados que aparecen en el material proporcionado)
1. Contexto macro‑económico del sector Tamaño del mercado: US $947.1 M en 2020; proyectado a superar el billón de dólares en los próximos años. Audiencia global: > 215 millones de “entusiastas” (personas que ven competiciones al menos una vez al mes). Motor de crecimiento: Broadband rápido y fiable. Las regiones con mejor conectividad (Este de Asia, Norte de Europa y Norteamérica) concentran la mayor parte del potencial de mercado.
2. Evolución de géneros y penetración regional Nuevos géneros híbridos: Battle‑royale (desde 2017) – p.ej. Fortnite, PUBG. Auto‑battlers (desde 2019) – p.ej. Teamfight Tactics, Dota Auto‑Chess. Penetración de audiencia (por población): | Región | % de población | Fans estimados | |--------|----------------|----------------| | China | 6.09 % | 88 M | | Norteamérica | 4.93 % | 18.2 M | | Europa | 3.90 % | 29.2 M | | Latinoamérica | (dato incompleto) | — | La distribución es muy desigual; los mercados emergentes aún presentan gran margen de expansión.
3. Arquitectura del ecosistema Propiedad intelectual: Los publishers (editores) son dueños del IP, financian el desarrollo y establecen las reglas competitivas. Actores interdependientes: Desarrolladores → crean el juego. Plataformas (Steam, Epic, consolas) → distribución y hosting. Organizadores de torneos → eventos y ligas. Equipos profesionales → gestión de jugadores y marcas. Jugadores (pro y amateur) → contenido y rendimiento. Creadores de contenido (streamers, youtubers) → comunidad y monetización. Profesionalización: Programas de becas multimillonarios, ligas estructuradas (ej. LCS, LEC, Overwatch League) y contratos con cláusulas de exclusividad y derechos de imagen.
4. Crecimiento de audiencia y de ingresos Audiencia total: 435.9 M (2021) → 577.2 M (estimado 2024) – CAGR +7.7 %. Ingresos: < $1.1 B (2021) → proyección > $1.5 B para 2024 (
- The esports market is projected to grow from under $1.1 billion in 2021 to over $1.5 billion by 2024, maintaining a compound annual growth rate (CAGR) of 7.7%.
- Global esports viewership is expected to reach 577.2 million people by 2024, up from 435.9 million in 2021.
- Market potential is heavily concentrated in regions with high-speed broadband infrastructure, specifically East Asia, Northern Europe, and North America.
- China leads global market penetration with 88 million fans, representing 6.09% of its population, significantly outpacing North America (4.93%) and Europe (3.90%).
- The ecosystem is defined by publisher-controlled intellectual property, where developers dictate competitive rules and league structures like the LCS, LEC, and Overwatch League.
Rapport Annuel 2021
The 2021 annual review underscores the emergence of video‑games as a pivotal social and economic force within Canada, where roughly 61 % of the population—about 23 million people—engage in regular play. Pandemic‑era surveys reveal that 58 % of adult gamers and 80 % of adolescents increased their gaming time, while disposable income previously allocated to cinema and travel was redirected toward interactive entertainment, positioning gaming as the dominant medium in the national leisure landscape.
Advocacy and industry support intensified throughout the year. The association shifted to virtual engagement with parliamentarians, deployed a paid Globe and Mail advertisement, and produced a targeted video message to maintain policy visibility during COVID‑19. A new content‑manager bolstered digital capacity, and coordinated outreach—including bi‑weekly provincial briefings, a monthly liaison call with provincial bodies, and a legally vetted return‑to‑work guide—facilitated the successful exclusion of video‑game developers and console manufacturers from the revised Canadian Broadcasting Act, averting potential royalties amounting to tens of millions of dollars and avoiding additional regulatory burdens.
Operational resilience was demonstrated as approximately 30 000 industry employees transitioned to remote work without disrupting the majority of scheduled releases. Financial stewardship met all set objectives, remaining within budget while expanding strategic initiatives. The sixth‑year student competition attracted 20 entries, awarding a $6,000 prize, reflecting ongoing investment in talent development and community engagement across the Canadian gaming sector.
- The Canadian video game industry successfully lobbied to be excluded from the revised Canadian Broadcasting Act, avoiding tens of millions of dollars in potential royalties and regulatory burdens.
- Approximately 23 million Canadians—61% of the population—are regular gamers, with 58% of adults and 80% of adolescents increasing their playtime during the pandemic.
- The industry maintained operational continuity during 2021 as 30,000 employees transitioned to remote work without disrupting the majority of scheduled game releases.
- Consumer spending shifted during the pandemic, with disposable income previously allocated to cinema and travel redirected toward interactive entertainment.
- Industry advocacy efforts in 2021 included virtual parliamentary engagement, targeted media campaigns in The Globe and Mail, and the implementation of a legally vetted return-to-work guide.