Global
Documents
State of Free to Play on Steam in 2024
The analysis evaluates the free‑to‑play (FtP) segment on Steam, highlighting its dominant share of player engagement and the increasing difficulty for new titles to break through. In 2023, FtP games accounted for 51 % of total hours played on the platform, despite premium titles comprising the majority of releases. Engagement is highly concentrated: the top 25 FtP titles generate 88 % of all FtP activity, the top 10 capture roughly 70 %, and the top five hold nearly 60 % of concurrent users (CCU). Counter‑Strike 2 and Dota 2 continue to lead the charts, with eight of the ten highest‑CCU games in 2023 being FtP, while only one premium title (Rust) appears in the list.
The market shows signs of compression as high‑quality premium and paid‑live‑service games erode FtP share. Between 2021 and 2024, premium titles priced $10‑$50 grew from 31 % to 37 % of total playtime, and flagship releases such as Elden Ring and Hogwarts have boosted the over‑$50 segment. Nonetheless, FtP titles remain older on average; the top ten FtP games have a mean age of seven years, and only two new entries (Call of Duty Warzone and Naraka: Bladepoint) have entered the top‑ten
- Free-to-play (FtP) games dominate Steam engagement, accounting for 51% of total hours played in 2023 despite being outnumbered by premium releases.
- Market engagement is highly concentrated, with the top 25 FtP titles capturing 88% of all FtP activity and the top five titles holding nearly 60% of concurrent users.
- The FtP sector is stagnant for new entrants, as the top ten FtP games have a mean age of seven years and only two new titles have broken into that tier since 2021.
- FtP titles maintain a massive presence in the top-tier charts, occupying eight of the ten highest concurrent-user spots in 2023, with Counter-Strike 2 and Dota 2 leading the segment.
- Premium titles are successfully eroding FtP market share, with games priced between $10 and $50 increasing their share of total playtime from 31% to 37% between 2021 and 2024.
Behind the Screens: The Salary Stats in Gamedev
This research, conducted by 80 Level in January 2024, examines the global compensation landscape and financial well-being of professionals within the video game development industry. Based on a survey of over 1,000 respondents from the 80 Level Research panel and reader base, the study analyzes how geography, years of experience, and specific job roles influence annual income and purchasing power.
The findings reveal a highly stratified industry where nearly 40% of developers earn less than $40,000 annually, while only 11% exceed the $150,000 mark. Geographic location serves as a primary driver of these disparities; for instance, 36% of U.S.-based professionals earn over $150,000, whereas 54% of surveyed developers in India earn under $9,999. In Europe, the majority of professionals in the UK, Germany, and Sweden fall within the $30,000 to $79,999 range. The data also highlights a significant "cost of living" gap, noting that while 16.6% of the workforce can afford all discretionary purchases, 24.4% earn enough for a car but remain unable to afford a residence.
Experience levels further dictate earning potential, with 74% of interns earning under $9,999, while 24% of Directors and Leads exceed $150,000. The analysis of specific roles shows that Creative Directors and Software Developers generally occupy higher salary segments compared to Artists and Game Designers. Notably, the study identifies a segment of "struggling" C-level executives (19%), likely representing founders of small indie studios who face financial instability despite their titles. The research concludes that while the industry offers high-earning potential at senior levels in Western hubs, a substantial portion of the global workforce operates under significant financial constraints.
- The game development industry is highly stratified, with nearly 40% of professionals earning under $40,000 annually and only 11% earning more than $150,000.
- Geography is a primary driver of income disparity, evidenced by 36% of U.S.-based professionals earning over $150,000 compared to 54% of developers in India earning under $9,999.
- Financial instability is prevalent, as 24.4% of the workforce can afford a car but cannot afford a residence, while only 16.6% can afford all discretionary purchases.
- Experience correlates strongly with compensation, as 74% of interns earn under $9,999, whereas 24% of Directors and Leads earn over $150,000.
- Creative Directors and Software Developers generally command higher salaries than Artists and Game Designers.
Mobile Growth and Monetization Report 2024
The 2024 mobile gaming landscape is defined by a strategic transition from volume-based user acquisition toward high-value retention and diversified monetization. While only 1.83% of users convert to in-app purchases, nearly 29% of those individuals become repeat buyers, with the vast majority of transactions occurring within the first 30 days of installation. To capitalize on this window, developers are increasingly mapping specific products to game stages, utilizing starter bundles for early engagement and limited-time events to sustain mid-to-late-game revenue. This shift reflects a broader industry move away from traditional cost-per-install models in favor of return-on-ad-spend and event-based optimizations.
Monetization strategies are becoming more sophisticated through the integration of rewarded video and offerwalls. Rewarded video engagement is particularly high in Word, RPG, and Casual genres, especially when placements are context-sensitive, such as offering additional moves or resources during critical gameplay moments. However, offerwalls represent a superior revenue driver for non-paying users, generating a monthly ad revenue of $4.04 per converter compared to just $0.15 for rewarded video. Users acquired through offerwalls, specifically via Multi-Reward CPE campaigns with multiple engagement steps, demonstrate significantly higher long-term value and retention.
Advertisers are further diversifying acquisition through Daily Reward CPE to engage casual users with low-friction tasks, which see near-total conversion rates for early milestones like tutorials. On the publishing side, maximizing performance requires prominent UI placements and the strategic use of monthly currency sales, which can increase conversions by up to 46%. These findings, derived from Unity Cloud, Unity Ads, Tapjoy, and ironSource data, cover global markets categorized by purchasing power and English proficiency, providing a comprehensive view of the current mobile ecosystem across Tier 1, Tier 2, and emerging regions.
- Offerwalls significantly outperform rewarded video for non-paying users, generating $4.04 in monthly ad revenue per converter compared to $0.15 for rewarded video.
- Only 1.83% of mobile users convert to in-app purchases, but 29% of those converters become repeat buyers, with most transactions occurring within the first 30 days of installation.
- Strategic use of monthly currency sales can increase in-app purchase conversion rates by up to 46%.
- Multi-Reward CPE campaigns on offerwalls drive higher long-term value and retention compared to traditional acquisition methods.
- Developers are shifting from volume-based user acquisition toward return-on-ad-spend models, utilizing starter bundles for early engagement and limited-time events for late-game revenue.
Games Market Trends to Watch in 2024
The global games market in 2024 is characterized by a period of stabilization and strategic restructuring following the post-pandemic correction. While the industry saw a revenue decline in 2022, recovery began in 2023 and is expected to continue through 2024, driven largely by the expanding install base of current-generation consoles like the PlayStation 5 and Xbox Series X|S. Despite this growth, the year is defined as a lean period for many companies as they navigate high interest rates, reduced investment capital, and a highly competitive landscape where a small number of titles dominate the majority of player engagement.
Key findings indicate a significant shift in business models and platform strategies. While live-service games remain the primary revenue drivers, the market is experiencing oversaturation, leading many developers to return to premium, finite gaming experiences. Growth in multi-game subscription services is expected to slow as they face competition from free-to-play social platforms like Fortnite and Roblox. Additionally, mobile developers are increasingly diversifying by bringing their titles to PC to combat rising user acquisition costs and stricter privacy regulations. Major hardware and distribution shifts are also anticipated, including the launch of a new Nintendo console and the introduction of an Xbox mobile store on Android.
The scope of this analysis covers global market trends across PC, console, and mobile segments, with revenue forecasting extending through 2026. The methodology combines internal market data and analyst perspectives with a survey of gaming executives and industry experts from companies such as Ubisoft, Iron Galaxy Studios, and Savvy Games Group. Emerging technologies like generative AI are identified as tools for increasing production efficiency, though they are not expected to transform game development at scale within the immediate calendar year. Overall, the industry is moving toward risk-reduction strategies, focusing on established intellectual properties and cross-platform accessibility to maintain stability.
- The global games market is in a period of stabilization and recovery throughout 2024, supported by the growing install base of current-generation consoles like the PlayStation 5 and Xbox Series X|S.
- Developers are increasingly pivoting back to premium, finite gaming experiences to counter the oversaturation of the live-service market.
- Mobile developers are expanding to PC platforms to mitigate the impact of rising user acquisition costs and stricter privacy regulations.
- Growth in multi-game subscription services is expected to decelerate as they face direct competition from free-to-play social platforms such as Fortnite and Roblox.
- The industry is preparing for significant infrastructure shifts, including the anticipated launch of a new Nintendo console and the introduction of an Xbox mobile store on Android.
The State of Gaming 2024: An Analysis of the Current Mobile Gaming Market Trends
The global mobile gaming market underwent a significant correction in 2023, characterized by a 10% decline in worldwide downloads and a 2% drop in total revenue. This downturn was primarily fueled by escalating user acquisition costs and a post-pandemic stabilization of consumer habits. While the broader market contracted, a distinct shift toward casualization occurred, evidenced by an 8% increase in Casual game revenue and a 30% surge in the Hybridcasual segment. Conversely, Mid-core titles faced a 9% revenue decline, signaling a transition in player preferences toward more accessible experiences.
Geographic performance diverged sharply as publishers pivoted toward emerging markets to mitigate rising costs in established territories. While the Asian market saw a 6% revenue contraction, the Middle East, Europe, and Latin America experienced revenue growth of 8%, 7%, and 4% respectively, despite falling download numbers. This regional resilience was often driven by high-profile intellectual properties, such as the success of Monopoly GO! in Europe and the expansion of Netflix’s gaming portfolio, which saw a 194% increase in downloads through the integration of major franchises like Grand Theft Auto.
Strategic adaptations in 2023 focused on maximizing player lifetime value through Live Ops events and transmedia collaborations. Mobile gaming now commands 67% of global digital advertising spend, with marketing strategies increasingly segmented by platform; YouTube and TikTok serve as primary hubs for core gamers, while Facebook and Pinterest remain vital for reaching casual female audiences. To combat the challenges of the current landscape, the industry has embraced low-cost user-generated content and external subscription models, leveraging recognizable IP to bridge the gap between gaming and broader entertainment media.
- The global mobile gaming market contracted in 2023, with a 10% decline in downloads and a 2% drop in total revenue due to rising user acquisition costs and post-pandemic habit stabilization.
- Player preferences shifted toward accessibility, resulting in an 8% revenue increase for Casual games and a 30% surge in the Hybridcasual segment, while Mid-core titles saw a 9% revenue decline.
- Publishers are pivoting to emerging markets to offset costs, with the Middle East, Europe, and Latin America seeing revenue growth of 8%, 7%, and 4% respectively.
- High-profile intellectual property is a primary growth driver, evidenced by the success of Monopoly GO! in Europe and a 194% surge in Netflix gaming downloads following the integration of franchises like Grand Theft Auto.
- Mobile gaming now accounts for 67% of global digital advertising spend, with marketing strategies increasingly segmented by platform, such as using YouTube and TikTok for core gamers and Facebook and Pinterest for casual female audiences.
Art Direction in Game Remakes: An Analysis of 7 Case Studies
The pursuit of a successful game remake requires a delicate equilibrium between honoring the original creative spirit and meeting the heightened technical expectations of modern audiences. Analysis of high-profile titles released through 2024, including Metroid Prime Remastered and Resident Evil 4, indicates that critical and fan reception serves as the primary metric for quality, often superseding raw financial performance. Developers find the most success when they rebuild visual assets from scratch, leveraging contemporary lighting and 3D environments to recreate the atmospheric immersion that original technical constraints once limited.
Modernization strategies vary based on the age and mechanical relevance of the source material. While some titles benefit from subtle control refinements, others require a total overhaul of core systems to remain viable. Capcom’s approach to the Resident Evil series exemplifies this by replacing dated tank controls and fixed cameras with fluid 3D movement and strategic lighting. Similarly, Square Enix transitioned the static backgrounds and turn-based combat of Final Fantasy VII into expansive environments and action-oriented hybrid systems. These shifts demonstrate that adhering to the "pillars of experience" is more vital than preserving obsolete functional elements.
Ultimately, the most effective remakes prioritize the recreation of a specific feeling or "spirit" over mere resolution increases. While visual fidelity must be modernized to maintain immersion, gameplay adjustments should be handled selectively to avoid alienating the core fanbase. Industry leaders like Nintendo and specialized external development partners emphasize that leveraging modern hardware to amplify a game's original intent is the most reliable path to critical acclaim. By focusing on atmospheric depth and evolved control schemes, developers can ensure that classic titles resonate with both nostalgic players and new audiences within the current AAA landscape.
- Successful remakes prioritize the recreation of a game's original 'spirit' and atmospheric intent over simple increases in visual resolution.
- Critical and fan reception serves as the primary metric for quality in modern remakes, often outweighing raw financial performance.
- Developers achieve the highest success by rebuilding visual assets from scratch to leverage contemporary lighting and 3D environments, overcoming the technical constraints of original releases.
- Modernization strategies must distinguish between preserving 'pillars of experience' and replacing obsolete functional elements, such as Capcom’s transition from fixed cameras to fluid 3D movement in Resident Evil 4.
- Square Enix’s approach to Final Fantasy VII demonstrates that transitioning from static backgrounds and turn-based combat to expansive, action-oriented systems can effectively modernize legacy titles.
Xsolla Report: State of Play – Winter 2024 Edition
The global gaming industry is currently navigating a period of stabilization following a massive 26% growth surge between 2019 and 2021. While the rapid pandemic-era expansion has moderated, the sector reached $106.8 billion in 2023 and is on a trajectory to hit $205.7 billion by 2026. This growth is underpinned by a global player base expanding to 3.79 billion people, with mobile gaming remaining the dominant force, accounting for nearly half of all consumer spending. Despite a downward revision in year-over-year growth forecasts to 0.6%, mobile spending is expected to reach $111.4 billion in 2024, led by strong performance in the United States and Japan.
The industry is undergoing a significant structural transformation driven by technological shifts and regulatory changes. The transition toward digital-only monetization, cloud-based services, and the metaverse—projected to reach $996 billion by 2030—reflects a broader convergence with the entertainment landscape. Furthermore, the implementation of the Digital Markets Act is opening doors for alternative billing systems and direct-to-consumer web stores. These shifts occur alongside a demographic evolution where women now represent nearly 50% of the player base, though they remain underrepresented in executive and professional roles.
Financial dynamics within the sector show a complex landscape of consolidation and rising costs. While AAA development budgets have tripled over the last five years, the investment market has faced volatility, characterized by a cooling M&A environment and significant layoffs. Despite a drop in deal volume, strategic investment value surged by 577% in mid-2023, reaching $7 billion in a single quarter. To counter high user acquisition costs and stricter privacy regulations, developers are increasingly adopting generative AI for efficiency and pivoting toward community-focused organic reach, early access models, and influencer partnerships to ensure long-term sustainability.
- The global gaming industry is projected to grow from $106.8 billion in 2023 to $205.7 billion by 2026, supported by a total player base of 3.79 billion people.
- Mobile gaming remains the industry's primary revenue driver, accounting for nearly 50% of total consumer spending and reaching a projected $111.4 billion in 2024.
- Strategic investment value saw a massive 577% surge in mid-2023 to reach $7 billion in a single quarter, despite an overall cooling in M&A activity and a volatile investment climate.
- The metaverse is projected to reach a valuation of $996 billion by 2030 as the industry shifts toward digital-only monetization and cloud-based services.
- Regulatory changes like the Digital Markets Act are forcing a structural shift toward alternative billing systems and direct-to-consumer web stores to bypass traditional platform constraints.
The Alumni Effect: A Deep Dive into Studios Founded by Ex-Rioters
The emergence of startups founded by former Riot Games employees represents a significant sub-sector of the venture capital landscape in gaming. Since 2020, investors have funneled nearly $500 million into 27 startups led by these alumni across 38 funding rounds. These founders command a substantial premium in the market, with an average round size of $11 million, which is 53% higher than the $7 million average seen across the broader gaming startup ecosystem.
The investment data reveals a high level of confidence from specialized venture capital firms, with Andreessen Horowitz (a16z Games) and Bitkraft Ventures leading the activity. These firms have participated in deals valued at $339.3 million and $236.3 million respectively. Furthermore, ex-Riot teams demonstrate superior fundraising momentum compared to the general market. A significantly higher percentage of these studios successfully secure follow-on financing within two to three years of their initial rounds, whereas the broader gaming market sees a much sharper decline in subsequent funding success over the same period.
While capital infusion is high, the majority of these ventures are currently in the pre-release phase. Out of 27 identified startups, only six have released products to date. The most well-funded projects include Theorycraft’s Supervoke, Believer’s unannounced AAA title, and Singularity 6’s Palia. The scope of these projects primarily focuses on high-ambition genres such as multiplayer RPGs, extraction MOBAs, and backend infrastructure. This trend underscores a strategic focus on complex, scalable platforms that mirror the live-service expertise associated with the founders' professional origins.
- Startups founded by former Riot Games employees have raised nearly $500 million across 27 companies since 2020.
- Ex-Riot founders command a 53% premium in average round size, securing $11 million per round compared to the $7 million industry average.
- Venture capital firms Andreessen Horowitz and Bitkraft Ventures are the primary backers, participating in deals worth $339.3 million and $236.3 million respectively.
- Alumni-led studios demonstrate superior fundraising momentum, with a higher rate of success in securing follow-on financing within two to three years compared to the broader gaming market.
- Despite significant capital infusion, only six of the 27 identified startups have released products to date.
Interactive Entertainment 2025: Global Market Sizing & Forecast
The interactive entertainment market is projected to reach $250.2 billion in consumer spending by 2025, representing a 4.6% year-over-year growth. This recovery follows a period of transition characterized by a significant cyclical downturn in console hardware, which is expected to decline by 31% in 2024 as the industry prepares for next-generation devices. The analysis covers global consumer spending across software publishing, hardware, emerging technology, and live-streaming segments for the period spanning 2023 through 2025.
Software publishing remains the primary market driver, with mobile gaming leading as the largest category, forecasted to reach $115.7 billion in 2025. While PC gaming shows the strongest growth rate at 8.1% for 2025, console software spending is also expected to rise in anticipation of new hardware cycles. In contrast, the esports and live-streaming sectors face ongoing profitability challenges; esports revenue is projected to decline by 8.3% in 2025, while streaming platforms struggle with high operational costs despite modest growth in user engagement.
Emerging technologies, including virtual reality and blockchain gaming, are identified as latent disruptors fueled by venture capital and platform investments. Virtual reality is expected to grow by 11% in 2025, supported by new hardware like the Apple Vision Pro. Additionally, the market is seeing a strategic shift as major entertainment firms like Sony and Disney evolve into all-round media conglomerates, leveraging established intellectual property across games, film, and virtual storefronts in platforms like Roblox to reach new audiences. Data for these findings is derived from company financials and a proprietary partner network tracking over 200 consumer brands.
- The global interactive entertainment market is projected to reach $250.2 billion in consumer spending by 2025, marking a 4.6% year-over-year growth.
- Mobile gaming remains the industry's largest segment, with forecasted consumer spending of $115.7 billion in 2025.
- Console hardware is experiencing a significant cyclical downturn, with spending expected to decline by 31% in 2024 ahead of next-generation device launches.
- PC gaming is the fastest-growing software segment, projected to achieve an 8.1% growth rate in 2025.
- Esports revenue is facing a downturn, with a projected decline of 8.3% in 2025 due to ongoing profitability challenges.
Annual Universe of Positive Gaming Experiences 2024
Stillfront Group’s 2024 fiscal year marks a pivotal transition into a synergy-driven operational phase, characterized by a major geographic reorganization into Europe, North America, and MENA & APAC business areas. This strategic shift aims to drive efficiency and mitigate a 2% organic revenue decline, which resulted in total net revenues of 6,737 MSEK. The financial year was defined by a significant net loss of 7,378 MSEK, primarily driven by a 6.9 billion SEK goodwill impairment in the North American segment due to lower-than-expected growth. Despite these non-cash charges, the group maintained a resilient financial foundation, generating over 1 billion SEK in free cash flow and improving gross margins to 80% through successful direct-to-consumer initiatives.
The group’s portfolio remains focused on free-to-play franchises, with North America and Europe accounting for 71% of player bookings. To reduce dependency on third-party platforms, which still facilitate 54% of revenue, management is prioritizing its internal payment systems and the "Stillops" platform for cost optimization. A comprehensive cost-savings program is underway, targeting up to 250 MSEK in annual savings by late 2025. Leadership has also stabilized under a new CEO and a board that remains fully compliant with the Swedish Code of Corporate Governance, focusing on organic growth and franchise scaling over dividend distributions.
Sustainability and governance have been deeply integrated into the corporate strategy in preparation for the EU’s Corporate Sustainability Reporting Directive. The group achieved Science Based Targets initiative validation, reducing market-based greenhouse gas emissions by 7% and more than doubling its renewable energy share to 37%. While social metrics show a stable workforce with improved turnover rates and high data security standards, challenges remain in gender diversity at the executive level. Executive remuneration is now tied to long-term sustainability targets, including employee satisfaction and data privacy, ensuring that environmental and social governance remains central to the group’s long-term value creation.
- Stillfront Group reported a net loss of 7,378 MSEK for fiscal year 2024, largely driven by a 6.9 billion SEK goodwill impairment in its North American segment.
- Total net revenues reached 6,737 MSEK, reflecting a 2% organic revenue decline that prompted a major geographic reorganization into Europe, North America, and MENA & APAC.
- Despite the net loss, the company generated over 1 billion SEK in free cash flow and improved gross margins to 80% through direct-to-consumer initiatives.
- Management is executing a cost-savings program targeting 250 MSEK in annual savings by late 2025 while prioritizing internal payment systems to reduce reliance on third-party platforms, which currently account for 54% of revenue.
- The company is shifting focus toward organic growth and franchise scaling, with 71% of player bookings currently concentrated in North America and Europe.
The Power of Play: España
Summary of “The Power of Play: España” (Survey of Spanish Video‑Game Players)
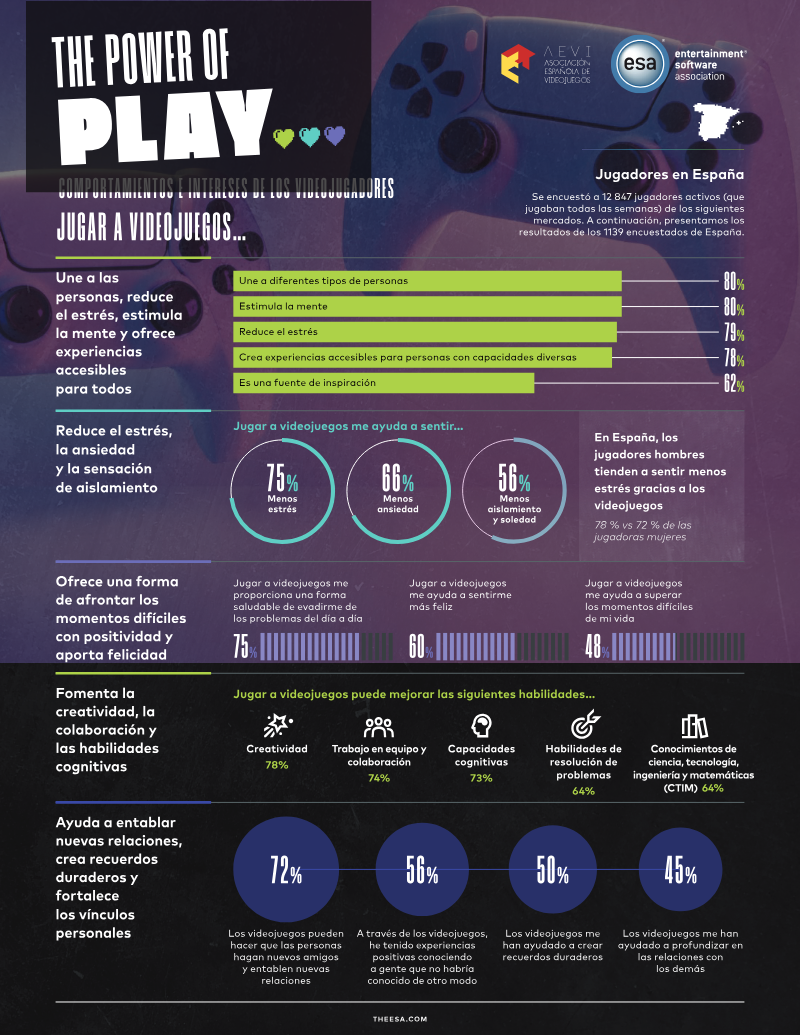
1. Scope & Sample Population surveyed: 12 847 active gamers (play ≥ once a week) across several markets. Spanish subsample: 1 139 respondents (men + women) who answered the questionnaire.
2. Demographic Profile
| Age group (years) | % of Spanish respondents | |-------------------|---------------------------| | 16‑18 | 8 % (men) / 41 % (women) | | 19‑24 | 49 % (men) / 28 % (women) | | 25‑34 | 28 % (men) / 28 % (women) | | 35‑44 | – | | 45‑54 | – | | 55‑64 | – | | 65+ | – |
\The table in the original document mixes gender‑specific percentages; the numbers above reflect the most clearly reported figures.
Gender split (overall): Roughly equal, with a slight male majority in the 19‑24 bracket. Play mode: 8 out of 10 male gamers (≈ 80 %) report playing with other players online. For women, solo play is still the most common, but a sizable minority also play online or in person.
3. Primary Motivations for Playing
| Motivation | % of respondents (overall) | |------------|----------------------------| | Fun / Entertainment | 85 % | | Stress reduction / relaxation | 78 % (men) – 75 % (women) | | Social connection (meeting new people, making friends) | 62 % (men) – 55 % (women) | | Escapism / coping with daily problems | 28 % (men) – 48 % (women) | | Feeling happier / more positive | 75 % (men) – 60 % (women) | | Creating lasting memories | 45 % (men) – 35 % (women) |
Note: The percentages are drawn from multiple overlapping questions (e.g., “Jugar a videojuegos me ayuda a sentir…”, “Reduce el estrés, la ansiedad, el aislamiento”). The highest‑scoring items are fun, stress relief, and social interaction.
4. Perceived Benefits
4.1 Psychological & Emotional Stress & anxiety: 78 % of men and 75 % of women say gaming helps them feel less stressed and less anxious. Isolation: 78 % of men and 72 % of women report a reduction in feelings of loneliness.
- Gaming is primarily used for emotional regulation in Spain, with 78% of men and 75% of women reporting that it effectively reduces stress and anxiety.
- Social connection is a major driver for the Spanish gaming population, with 62% of men and 55% of women citing it as a primary motivation for play.
- Online multiplayer engagement is significantly higher among men, with approximately 80% reporting they play with others online, whereas women show a stronger preference for solo play.
- Gaming serves as a vital tool for combating loneliness, as 78% of men and 72% of women report that playing reduces their feelings of isolation.
- The Spanish gaming demographic is heavily concentrated in younger age brackets, with 49% of male players and 28% of female players falling within the 19–24 age range.
Live Streaming Trends Annual Report 2024
The live streaming landscape in 2024 reflects a maturing industry characterized by the stabilization of viewership hours and a strategic shift toward platform diversification. Following the volatile growth cycles of previous years, the current market demonstrates a consolidated ecosystem where Twitch, YouTube Gaming, and Kick represent the primary pillars of audience engagement. While Twitch maintains its dominance in the non-gaming and community-driven sectors, YouTube Gaming has leveraged its integrated VOD ecosystem to capture a larger share of the competitive esports market. Emerging platforms like Kick have successfully disrupted traditional market shares by offering aggressive revenue splits, leading to a more fragmented but competitive talent landscape.
Technological integration serves as a primary driver for growth, with mobile streaming accounting for nearly half of all global viewership. This trend is particularly pronounced in Southeast Asia and Latin America, where mobile-first infrastructure has allowed platforms like TikTok Live to challenge established desktop-centric services. Data indicates that short-form video integration acts as a critical discovery funnel, with creators who utilize cross-platform promotional strategies seeing a twenty percent higher retention rate compared to those relying solely on live broadcasts. Furthermore, the rise of "VTubing" and AI-enhanced avatars has expanded the creator economy, allowing for new forms of interactive entertainment that bypass traditional physical production constraints.
Monetization strategies have evolved beyond simple ad-revenue models to prioritize direct fan support and brand integrations. Virtual gifting and subscription tiers remain the most reliable revenue streams, though sponsored content and affiliate commerce are becoming increasingly sophisticated. The industry is also witnessing a significant push toward "shoppable" live streams, mirroring successful e-commerce trends in Asian markets. As the industry moves forward, the focus remains on enhancing low-latency infrastructure and developing more robust moderation tools to ensure brand safety and community longevity in an increasingly crowded digital marketplace.
- Mobile streaming now accounts for nearly 50% of global viewership, driven by mobile-first infrastructure in Southeast Asia and Latin America.
- Creators using cross-platform promotional strategies that integrate short-form video content achieve a 20% higher audience retention rate than those relying exclusively on live broadcasts.
- Twitch remains the leader in community-driven content, while YouTube Gaming is capturing significant market share in competitive esports through its integrated VOD ecosystem.
- The platform landscape is becoming increasingly fragmented as Kick disrupts traditional market shares by offering aggressive revenue splits to attract talent.
- Monetization is shifting away from simple ad-revenue toward direct fan support, subscription tiers, and the adoption of 'shoppable' live streams for e-commerce.