Global
Documents
Digital Market Index: Q4 2024
Global digital markets reached a significant milestone in the final quarter of 2024, with in-app purchase revenue hitting a record $39.4 billion. This growth was primarily fueled by a 28.2% year-over-year surge in non-game applications, exemplified by TikTok becoming the first app to surpass $6 billion in annual revenue. While the iOS ecosystem remains the primary driver of monetization by capturing 70% of total revenue, Google Play maintains its dominance in scale, facilitating nearly three-quarters of the 34.1 billion global downloads recorded during the period.
The mobile gaming landscape underwent a notable structural shift as consumer preferences migrated from traditional RPGs toward Strategy and Puzzle titles. Strategy games experienced a 26% year-over-year increase in downloads, helping to offset regional revenue declines in major markets like Japan and South Korea. Despite these shifts, Japan’s mobile sector showed signs of overall recovery, while emerging Android markets in Indonesia and Pakistan continued to expand rapidly. The successful launch of high-profile titles like Pokémon TCG Pocket further stabilized the gaming sector during this transition.
Advertising and retail media also reached unprecedented levels, with U.S. digital ad spend hitting $34 billion. Social media channels dominated this space, accounting for 77% of total expenditures as major retailers like Amazon and Walmart increased holiday investments. Retail media specifically generated a record 75.4 billion impressions, driven by high demand in consumer electronics and personal care. Strategic co-branded partnerships, such as the collaboration between Best Buy and Samsung, emerged as critical drivers of visibility, cementing the role of retail platforms as essential components of the broader digital advertising ecosystem.
- Global in-app purchase revenue reached a record $39.4 billion in Q4 2024, bolstered by a 28.2% year-over-year surge in non-game application spending.
- TikTok became the first application to surpass $6 billion in annual revenue, highlighting the massive monetization potential of non-game platforms.
- The iOS ecosystem captured 70% of total revenue, while Google Play maintained its dominance in scale by facilitating nearly 75% of the 34.1 billion global downloads.
- U.S. digital ad spend hit $34 billion in Q4 2024, with social media channels accounting for 77% of total expenditures.
- Mobile gaming preferences shifted toward Strategy and Puzzle titles, with Strategy games seeing a 26% year-over-year increase in downloads to help offset regional revenue declines in Japan and South Korea.
2024 Global Mobile Games Marketing Trends & Insights
The global mobile gaming industry is currently defined by extreme market concentration and a fundamental shift in monetization and marketing strategies. With the top 50 publishers generating 70% of total revenue, the sector is moving toward hybrid-casual models that blend ad-based revenue with in-app purchases to offset rising user acquisition costs. Strategic priorities for 2025 include the expansion of Direct-to-Consumer platforms to preserve margins and a resurgence in HTML5 web games. This evolution is occurring alongside a surge in marketing volume; in 2024, the industry saw over 250,000 advertisers and 46.2 million creative assets, representing a 60% year-over-year increase in advertising activity despite a declining rate of new market entrants.
Geographically, the landscape is marked by rapid growth in Southeast Asia and Latin America, while the United States remains a dominant but maturing market. High-production, cross-platform free-to-play titles, particularly from Chinese developers, are raising consumer expectations and challenging traditional premium pricing models. To navigate privacy-related data limitations, marketers are increasingly adopting creative-level attribution and generative AI for both content production and data analysis. Short-form video has become the primary driver of engagement, accounting for up to 81% of impressions in genres like Puzzle and Simulation, often utilizing AI-generated imagery and demographic-specific hooks to capture niche audiences.
Tactical trends reveal a widespread reliance on intellectual property and the integration of casual mini-game mechanics to market hardcore RPG and Strategy titles. Successful campaigns frequently leverage localized content and specialized creative formats, such as "stomp" transitions for social media or long-form puzzles to attract RPG players. This data, synthesized from over 1.6 billion ad records across 80 countries, underscores a transition toward high-volume, AI-enhanced marketing where deep user segmentation and creative variety are essential for maintaining player lifetime value in an increasingly competitive global environment.
- The top 50 publishers now control 70% of total global mobile gaming revenue, driving a market-wide shift toward hybrid-casual models that combine ad-based revenue with in-app purchases.
- Advertising activity surged by 60% year-over-year in 2024, with 250,000 advertisers deploying 46.2 million creative assets despite a decline in new market entrants.
- Short-form video has become the dominant engagement driver, accounting for up to 81% of impressions in the Puzzle and Simulation genres.
- Marketers are increasingly bypassing platform limitations by adopting creative-level attribution and leveraging generative AI for both content production and data analysis.
- Growth is accelerating in Southeast Asia and Latin America, while high-production, cross-platform free-to-play titles from Chinese developers are successfully challenging traditional premium pricing models.
Crypto on Live Streaming Mini‑Report
This analysis examines the intersection of cryptocurrency and live streaming, tracking the rapid growth of digital asset content across Twitch, YouTube, and Kick. The primary thesis identifies a significant surge in crypto-related broadcasting driven by market speculation, memecoin popularity, and political events. The scope covers global data from July 2023 through June 2025, utilizing a methodology that tracks unique channels with at least 30 hours of monthly airtime while excluding bots and suspicious accounts to ensure data integrity.
Findings reveal that the number of unique channels streaming crypto content doubled in the six months leading into late 2024. YouTube experienced the most dramatic growth, rising from 31 channels in July 2024 to over 200 by June 2025. Viewership peaked across platforms in early 2025, with Twitch reaching its height in February and YouTube seeing major spikes in January and June. While Bitcoin remains the most discussed asset with over 500,000 chat mentions in the first half of 2025, Solana has emerged as a dominant secondary interest, recording 171,000 mentions—triple that of Cardano.
The geographic reach of this content is notably diverse, with India emerging as a major hub; four of the top ten crypto creators are based there and stream primarily on YouTube. K1m6a is identified as the leading creator with 6.7 million hours watched. Beyond dedicated finance streams, crypto discourse has permeated gaming communities. Just Chatting is the top category for crypto mentions, but Escape from Tarkov and Fortnite lead among gaming titles. Furthermore, crypto integration is deepening in professional gaming, evidenced by high-viewership esports events like the 2025 Mid-Season Invitational, which secured major crypto-related sponsorships.
- The number of unique crypto-focused streaming channels doubled in the six months leading to late 2024, with YouTube channels surging from 31 in July 2024 to over 200 by June 2025.
- India has become a primary hub for crypto content, hosting four of the top ten global creators who stream primarily on YouTube.
- Bitcoin remains the most discussed asset with over 500,000 chat mentions in the first half of 2025, while Solana has emerged as the dominant secondary interest with 171,000 mentions.
- Creator K1m6a leads the sector with 6.7 million hours watched, highlighting the significant audience reach of top-tier crypto broadcasters.
- Crypto discourse has expanded beyond finance into gaming, with 'Just Chatting' as the top category and 'Escape from Tarkov' and 'Fortnite' leading among gaming titles.
Game Developer Collective Survey Results: November 2024
The November 2024 Game Developer Collective Survey examines how game developers allocate resources to software tools and services, focusing on the adoption of game engines, cloud platforms, and ancillary technologies. The central thesis is that while the market now offers a broader array of solutions than ever before, studios face divergent realities: many are eager to leverage these options to boost efficiency and output, yet a substantial portion confronts tightening budgets that limit further investment. This tension is reflected in the “Industry Conditions and Performance” findings, which portray a challenging commercial environment for the sector.
Key observations indicate that developers increasingly view diversified toolsets as pathways to improved productivity, but cost pressures are intensifying across regions. The survey highlights a split between studios that can expand their technology stack and those that must defer additional spending, underscoring a growing disparity in capability to innovate. The analysis also signals that forthcoming research on “Working Environments,” slated for release in January 2025, will delve deeper into how these financial constraints intersect with workplace dynamics and talent management.
The study spans a global developer base, encompassing respondents from the Americas, Europe‑Middle East‑Africa, and Asia‑Pacific, and captures sentiment as of November 2024. Although specific sample sizes and data sources are not disclosed in the excerpt, the findings are presented under the Omdia research umbrella, with standard disclaimer language indicating that the material is provided “as‑is” and reflects the original publication date. The survey’s conclusions serve as a barometer of current investment trends and the fiscal pressures shaping the game development landscape.
- As of November 2024, the game development sector is defined by a growing disparity between studios capable of expanding their technology stacks and those forced to defer spending due to tightening budgets.
- Developers increasingly view the adoption of diversified software tools, cloud platforms, and ancillary technologies as the primary pathway to improving productivity and output.
- Intensifying cost pressures across global regions are creating a challenging commercial environment that limits the ability of many studios to invest in new innovation.
- The current market offers a broader array of software solutions than ever before, yet these options are being met with fiscal constraints that restrict widespread adoption.
- Future industry analysis, scheduled for release in January 2025, will examine how these ongoing financial constraints specifically impact workplace dynamics and talent management.
Tools & Services Survey: November 2024
This analysis examines the evolving landscape of game development tools and services amidst a period of significant market volatility. Based on a November 2024 survey of the Game Developer Collective, the findings track shifts in engine preference, cloud infrastructure, and overall industry sentiment. The survey includes a global sample of developers, with 48% based in North America and 39% in Europe, primarily representing roles in programming, management, and game design.
A primary focus is the game engine market, which continues to react to Unity’s 2023 "runtime fee" controversy. Despite Unity eventually scrapping the fee, the company has steadily lost market share to Unreal Engine. While the percentage of Unity users planning to switch engines dropped from a peak of 70% in late 2023 to 36% in late 2024, this remains significantly higher than the 14% switch rate seen among users of competing engines. Sentiment toward Unity has moderated, but only 30% of developers report being happy with the company, suggesting a lasting impact on brand trust.
The broader industry environment is characterized by increasing financial pressure and underperformance. Approximately 55% of developers now describe market conditions as "bad," a notable increase from 47% six months prior. Business performance has also declined, with 41% of studios reporting they are underperforming against expectations. Consequently, while investment in tools remains steady for most, there is a growing emphasis on productivity and efficiency as the primary drivers for new purchases. AI-powered tools are a rare area of growth, with studios more likely to increase spending in this category compared to traditional services.
In specialized segments, Blender has emerged as the leading 3D modeling tool, used by 50% of studios. Cloud platform usage is at an all-time high, led by AWS and non-hyperscaler options, though these services remain highly "sticky" with low intent to switch providers. Conversely, specialist backend platforms struggle with low penetration, as only 38% of studios currently utilize these centralized solutions. Overall, the findings depict a cautious industry prioritizing efficiency and stability while navigating a difficult commercial climate.
- Market sentiment is increasingly negative, with 55% of developers describing current conditions as 'bad' and 41% of studios reporting underperformance against expectations.
- Unity continues to lose market share following its 2023 runtime fee controversy, with 36% of its users still planning to switch engines compared to only 14% for competitors.
- Brand trust in Unity remains damaged, as only 30% of developers report being happy with the company despite the reversal of its controversial fee policy.
- Studios are prioritizing efficiency and productivity in their purchasing decisions, with AI-powered tools being the only category seeing increased spending compared to traditional services.
- Blender has become the dominant 3D modeling tool, currently utilized by 50% of surveyed studios.
Gaming Industry Report: Q3 2024
• 2024 market size: $188bn (+2.1% YoY) Total gamers in 2024 by region (millions): • Public markets: leading public gaming ETFs up 22- • 36% YTD (vs S&P 500 = 21%) Middle East & Africa Venture funding in Q3‘ 24: $517m across 92 deals 559 (funding +1% QoQ, number of deals -14% QoQ) (16%) • Epic sidesteps Apple in the EU, sues Google Europe (454 3,422m • Discord launches Activities ...
- The gaming market size in 2024 is $188 billion, showing a 2.1% year-over-year growth. Asia-Pacific accounts for the largest share of gamers with 1,809 million (53%), followed by Europe with 454 million (13%).
- Venture funding in Q3 2024 reached $517 million across 92 deals, marking a 1% increase in funding quarter-over-quarter but a 14% decrease in the number of deals. Total private market funding for 2024 is $3,739 million, with a 15% QoQ increase in Q3.
- Public market gaming ETFs are significantly outperforming the S&P 500, with leading ETFs up 22-36% year-to-date compared to the S&P 500's 21%.
- Unity has fully removed its Runtime Fee, reverting to a seat-based subscription model with increased revenue and funding ceilings for Unity Personal (up to $200k) and price increases for Unity Pro (+8%) and Unity Enterprise (+25%).
- Epic Games is actively challenging platform policies, launching its own iOS app store in the EU with a maximum 12% commission and suing Google and Samsung over anti-competitive practices related to app distribution on Android.
Live Streaming Trend Report: Q3 2024
The analysis of live‑streaming activity in the third quarter of 2024 demonstrates a robust rebound in overall viewership, with total hours watched rising 12 percent year‑over‑year to reach 8.5 billion. Growth is concentrated on emerging services, most notably Kick, which expanded its audience by 103 percent, delivering 534 million hours of content and securing a 6.3 percent share of the market. Its peak week recorded 45 million hours watched, positioning Kick as the third‑largest platform despite Twitch’s modest 4 percent decline in the same period. The surge extends to Spanish‑language streams on Kick, where viewership accelerated sharply, underscoring the platform’s expanding appeal in non‑English markets.
Subscriber dynamics also reached new heights. VTuber ironmouse achieved an all‑time high of roughly 320 thousand followers on Twitch during the “SUBtember” marathon, while FaZe Clan’s 30‑day joint subathon generated 99.5 thousand and 73.7 thousand new subscribers for members jasontheween and plaqueboymax respectively. These figures illustrate a growing willingness among audiences to convert viewership into direct financial support for creators.
Esports viewership contributed a historic peak, with the LCK Grand Final between T1 and GEN drawing an estimated two million concurrent viewers, reinforcing the continued draw of high‑stakes competitive events. Collectively, the data reveal a diversifying ecosystem in which emerging platforms and regional language streams are reshaping audience distribution, while monetization through subscriptions and esports remains a powerful driver of engagement across the global live‑streaming landscape.
- Total live-streaming viewership reached 8.5 billion hours in Q3 2024, marking a 12 percent year-over-year increase.
- Kick emerged as the third-largest streaming platform with 534 million hours watched, representing a 103 percent growth rate and a 6.3 percent market share.
- Twitch experienced a 4 percent decline in viewership during Q3 2024, even as it hosted record-breaking subscriber events like ironmouse’s 320,000-follower marathon.
- Esports remains a primary engagement driver, evidenced by the LCK Grand Final between T1 and GEN drawing a peak of two million concurrent viewers.
- The live-streaming ecosystem is diversifying through the rapid expansion of non-English markets, particularly Spanish-language streams on the Kick platform.
Console/PC Games Investment Report September 2024
The analysis presents a comprehensive review of investment and merger‑and‑acquisition activity within the console and PC video‑game sector for the 2023 fiscal year, positioning 2023 as an outlier driven primarily by Microsoft’s $68.7 billion acquisition of Activision Blizzard. Total deal value reached $69.5 billion across 200 transactions, a 612 % increase in value yet a 25 % decline in transaction count compared with 2022, and twice the combined value of the preceding five‑year period (2018‑2022). Investment volume fell to $627.8 million across 161 deals, while M&A volume surged to $68.8 billion in 39 deals, accounting for more than 99 % of North American M&A value. IPO activity contracted sharply, with six offerings generating $46 million in market capitalisation, down 85 % from the prior year.
Geographically, North America and Europe dominated private investment, contributing $184.7 million (29 % of volume) and $358.8 million (57 % of volume) respectively, while Australia and New Zealand saw limited activity aside from a government grant program. Investors favored micro‑studios (median six employees), whereas acquirers targeted slightly larger teams (median 39 employees). Blockchain‑related deals comprised 15 % of investment value but only 13 % of transaction count, highlighted by Mythic Protocol’s $6.5 million seed round.
Methodologically, the review counts only closed transactions, excluding announced deals, and treats SPAC proceeds as the investment amount rather than post‑transaction valuation. Data are drawn from a proprietary, sixteen‑year‑old database that tracks Western‑focused game‑industry deals across development, publishing, and technology, ensuring consistency and comparability across quarters. The findings underscore a market concentrated around a few mega‑deals, with modest activity elsewhere and a clear shift toward larger, strategic acquisitions.
- The 2023 fiscal year saw total deal value reach $69.5 billion, a 612% increase driven almost entirely by Microsoft’s $68.7 billion acquisition of Activision Blizzard.
- While total deal value surged, the actual number of transactions fell by 25% compared to 2022, and investment volume dropped to $627.8 million across 161 deals.
- M&A activity dominated the market with $68.8 billion across 39 deals, accounting for more than 99% of North American M&A value.
- IPO activity contracted significantly in 2023, with only six offerings generating $46 million in market capitalization, an 85% decline from the previous year.
- Private investment was concentrated in Europe and North America, which contributed 57% ($358.8 million) and 29% ($184.7 million) of investment volume, respectively.
Live Streaming Trends Report: Q2 2024
The global live streaming industry experienced a significant resurgence in the second quarter of 2024, with total viewership reaching 8.5 billion hours. This 10% year-over-year increase represents the first substantial growth period since the pandemic-era peak. While Twitch maintains its position as the primary market leader, its dominance has softened from 70% to 60% of total hours watched. This shift reflects a diversifying landscape where YouTube Gaming and Kick have captured 23.4% and 5.5% of the market, respectively, and Rumble has established itself as a top-ten platform by leveraging political content and debate-related viewership.
Content trends during this period were heavily influenced by major software releases and political events. The launch of downloadable content for Elden Ring triggered a 331% surge in viewership for the title, driving a 30% increase in the broader Action genre. Conversely, traditional pillars such as First-Person Shooters and MOBAs saw slight declines in market share. The VTuber segment remains a high-growth area, particularly within the Grand Theft Auto V category, where individual creators saw viewership spikes exceeding 300%. Esports also reached new heights, evidenced by the LCK Grand Final achieving a record 2.7 million concurrent viewers.
A critical structural shift is occurring in creator demographics, characterized by the decentralization of viewership. The market share held by the top 5% of streamers fell to 86% from a 2019 high of 98%, while the share held by the top 0.01% of channels dropped from 45% to 33%. This trend suggests a maturing ecosystem where visibility is increasingly distributed among a broader range of mid-tier creators rather than being concentrated exclusively at the top. These findings indicate a healthy, diversifying industry that is successfully transitioning from pandemic-driven volatility to sustainable, multi-platform growth.
- The live streaming industry saw a 10% year-over-year growth in Q2 2024, reaching 8.5 billion total hours watched.
- Twitch's market share dropped from 70% to 60%, while YouTube Gaming and Kick captured 23.4% and 5.5% of the market, respectively.
- Viewership is decentralizing, with the top 5% of streamers now holding 86% of the market share, down from 98% in 2019.
- The top 0.01% of channels saw their market share decline from 45% to 33%, indicating a shift toward mid-tier creator visibility.
- Major software releases significantly impact genre performance, evidenced by Elden Ring's DLC launch driving a 331% surge in its viewership and a 30% increase in the broader Action genre.
Project & Studio Financing Snapshot July 2024
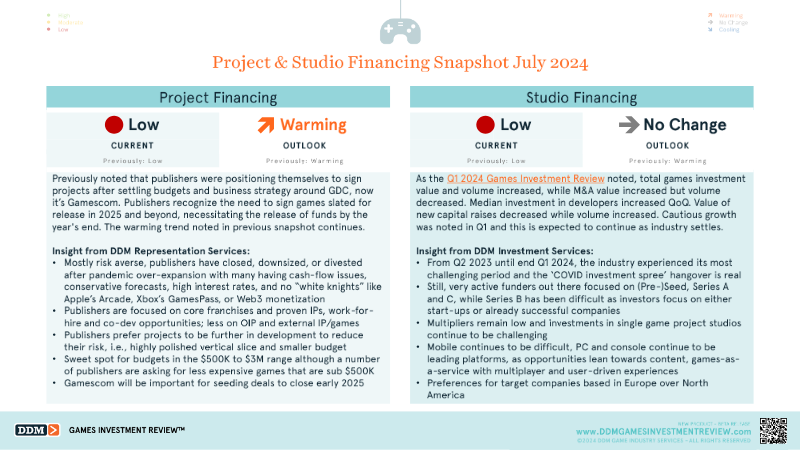
The snapshot evaluates financing conditions for game projects and development studios as of mid‑2024, highlighting a persistently constrained capital environment while noting modest signs of warming in project funding. Publishers remain risk‑averse after pandemic‑driven over‑expansion, with many having reduced staff, divested assets, and facing cash‑flow pressures compounded by high interest rates and the absence of large platform backers. Consequently, they prioritize core franchises, proven IP and work‑for‑hire arrangements, demanding projects that are further along in development, feature polished vertical slices, and fall within a budget sweet spot of roughly $500 k to $3 million, though an emerging demand for sub‑$500 k titles is evident. The upcoming Gamescom event is expected to catalyze deal flow for releases slated for 2025 and beyond.
Studio financing remains low with no change in outlook, reflecting cautious growth after a volatile Q1 2024 period in which total investment value and volume rose, M&A value increased while deal count fell, and median developer investment grew quarter‑over‑quarter. New capital raises saw a decline in total value but an increase in deal count, underscoring a shift toward smaller, more frequent funding rounds. Investors continue to focus on early‑stage (pre‑seed, Series A) and later‑stage (Series C) opportunities, while Series B financing proves scarce as capital gravitates toward either nascent start‑ups or already successful entities.
Geographically, funders exhibit a preference for European‑based studios over North American counterparts, and platform trends show mobile projects facing heightened difficulty, whereas PC and console titles dominate, especially those built around games‑as‑a‑service, multiplayer, and user‑generated content models. Overall, the financing landscape is characterized by conservative publisher behavior, modest but steady studio investment, and a strategic emphasis on later‑stage, lower‑risk projects as the industry settles post‑pandemic.
- Publishers are prioritizing low-risk projects with budgets between $500k and $3 million, though there is an emerging demand for titles under $500k.
- Investment is heavily skewed toward early-stage (pre-seed/Series A) and late-stage (Series C) rounds, leaving Series B financing scarce.
- Funding trends show a shift toward smaller, more frequent capital raises, evidenced by a decline in total new capital value despite an increase in deal count.
- PC and console titles—specifically those featuring games-as-a-service, multiplayer, or user-generated content—are currently prioritized over mobile projects.
- Investors are showing a geographic preference for European-based studios over North American counterparts.
Global Gamer Study 2024: How Consumers Engage with Games Today
This analysis examines global consumer engagement with video games, drawing on data from over 73,000 surveyed individuals across 36 markets. The findings reveal that gaming has become a dominant pillar of modern entertainment, with 80% of the total online population playing games and 85% engaging with the medium through playing, viewing content, or participating in social communities. Engagement is highest among younger demographics; over 90% of Gen Alpha and Gen Z consumers are game enthusiasts, with Gen Alpha notably spending more time on gaming (5.2 hours per week) than on social media.
The data highlights a significant shift in how different generations and genders interact with the medium. While Adventure is the top genre for Gen Alpha, Gen Z, and Millennials, younger female players are increasingly likely to invest in pay-to-play titles, challenging traditional industry stereotypes. On PC and console platforms, players are motivated primarily by vast open worlds and deep storytelling. These platforms also attract higher-spending audiences compared to mobile; 22% of console players spend more than $25 per month, and over half are classified as medium-to-high spenders.
Despite a market where a small number of established franchises capture the majority of playtime, a vital segment of "new game seekers" remains. Approximately 31% of PC and console players actively hunt for trending titles. This cohort is highly valuable, as 80% of them spend money on games monthly and they are 50% more engaged than the average player. Geographically, this appetite for new experiences is strongest in emerging markets like China, India, and Saudi Arabia, while more mature markets like Japan and Western Europe show more conservative play patterns. The findings suggest that success in a competitive landscape requires moving beyond playable experiences to engage consumers across multiple dimensions, including social media, creator content, and transmedia brands.
- Gaming is a primary entertainment pillar, with 80% of the global online population playing games and 85% engaging through play, viewing, or social communities.
- Gen Alpha and Gen Z are the most active demographics, with over 90% engagement and Gen Alpha spending 5.2 hours per week on gaming, surpassing their time spent on social media.
- A high-value segment of 'new game seekers' makes up 31% of PC and console players; these users are 50% more engaged than average players and 80% of them spend money on games monthly.
- PC and console platforms command higher spending than mobile, with 22% of console players spending over $25 per month and more than half classified as medium-to-high spenders.
- Emerging markets including China, India, and Saudi Arabia show the strongest appetite for new titles, contrasting with more conservative play patterns in Japan and Western Europe.
Mobile Games Annual Investment Report
The mobile gaming investment landscape in 2023 was characterized by a strong concentration of capital within early-stage ventures, with a significant emphasis on blockchain integration and infrastructure. Venture capital activity was led by prominent firms such as Andreessen Horowitz, which deployed 63 million dollars across eight investments, including a notable 33 million dollar seed round for Proof of Play. This trend highlights a strategic pivot toward developers who combine traditional mobile gameplay with decentralized technologies and infrastructure solutions.
Investment patterns reveal a diverse range of sub-sectors receiving capital, including social gaming, AI-driven development, and fantasy sports. For instance, Lumikai focused heavily on the Indian market and social platforms, leading a 22 million dollar round for Eloelo. Meanwhile, firms like BITKRAFT Ventures and Animoca Brands continued to bridge the gap between mobile and web3, funding projects like Redemption Games and Upland. While early-stage seed and Series A rounds dominated the volume of transactions, late-stage funding remained selective, as evidenced by Animoca Brands’ 11.9 million dollar raise.
Geographically and operationally, the sector shows a global distribution of capital, targeting both established publishers and niche studios. Total round values for top investors ranged from approximately 15 million to over 60 million dollars, signaling a cautious but steady flow of capital into the mobile ecosystem. The data suggests that while the broader gaming market faced economic headwinds, investors remained committed to high-growth areas such as blockchain-enabled rewards platforms, mid-core mobile development, and innovative monetization models through digital ownership.
- Venture capital in 2023 prioritized early-stage mobile gaming ventures, specifically those integrating blockchain technology and decentralized infrastructure.
- Andreessen Horowitz led investment activity by deploying 63 million dollars across eight deals, including a 33 million dollar seed round for Proof of Play.
- Investment focus remained diverse, spanning social gaming, AI-driven development, and fantasy sports, exemplified by Lumikai’s 22 million dollar investment in Eloelo.
- Firms such as BITKRAFT Ventures and Animoca Brands actively funded projects like Redemption Games and Upland to bridge the gap between traditional mobile gaming and Web3.
- While early-stage seed and Series A rounds dominated transaction volume, late-stage funding remained highly selective, highlighted by Animoca Brands’ 11.9 million dollar raise.