Global
Documents
How Developers Are Using Generative AI to Create a New Generation of Games
This research, conducted by Google Cloud and The Harris Poll in mid-2025, examines the transformative role of generative AI within the global games industry. Based on a survey of 615 developers across the United States, South Korea, Norway, Finland, and Sweden, the study finds that 97% of professionals believe generative AI is actively reshaping the sector. The primary thesis suggests that while the industry faces rising development costs and market saturation, AI serves as a critical tool for innovation, democratization, and operational efficiency.
Key findings indicate that 90% of developers have already integrated AI into their workflows, primarily to automate repetitive tasks and accelerate playtesting, localization, and coding. A significant trend is the rise of AI agents—autonomous systems capable of reasoning and planning—which 44% of respondents use for content optimization and 34% for advanced NPC behavior. These technologies are shifting player expectations, with 89% of developers noting that gamers now demand more lifelike, responsive, and personalized experiences. Furthermore, 94% of developers anticipate that AI will lead to long-term reductions in development costs over the next three years.
Despite this optimism, the industry faces notable hurdles regarding legal and ethical standards. Approximately 63% of developers expressed concerns over data ownership and intellectual property, while 35% cited worries regarding player data privacy. To navigate these challenges, the study recommends that studios start with small-scale pilots, align AI use with their core creative visions, and invest in staff upskilling. Ultimately, the data portrays AI not just as a productivity booster, but as a fundamental shift in game design that enables smaller studios to compete more effectively while fostering new levels of player immersion.
- 97% of game developers believe generative AI is actively reshaping the industry, with 90% already integrating the technology into their workflows to automate tasks like coding, localization, and playtesting.
- 94% of developers anticipate that the adoption of generative AI will lead to long-term reductions in game development costs over the next three years.
- AI agents are increasingly used for advanced game mechanics, with 44% of developers utilizing them for content optimization and 34% for creating more responsive NPC behaviors.
- 89% of developers report that player expectations have shifted, with gamers now demanding higher levels of personalization and lifelike interactivity in their experiences.
- Legal and ethical concerns remain a primary barrier to adoption, as 63% of developers cite worries regarding intellectual property and data ownership, while 35% express concerns over player data privacy.
The Global State of Game Publishing & Marketing 2025 Industry Report
The global game publishing market is entering a period of significant expansion, with revenues projected to rise from $117.4 billion in 2025 to $150.5 billion by 2030. This growth is underpinned by a fundamental shift toward digital distribution, which already accounted for 95% of industry revenue in 2023. While traditional publishers maintain a competitive edge through high-budget user acquisition and advanced analytics, the democratization of the industry via platforms like Steam and the Epic Games Store has enabled self-published titles to achieve massive commercial success. Consequently, the industry is moving toward a hybrid landscape where multiplatform launches have increased by 40% to maximize player engagement and revenue potential.
Strategic success in the current market relies heavily on closed-loop marketing and data-driven publishing. Developers are increasingly utilizing real-time telemetry and AI analytics to optimize player retention and monetization strategies. This is particularly evident in the rise of Live Service Games, with 95% of studios now developing titles designed for recurring revenue. However, community management and influencer marketing have emerged as equally vital pillars; approximately 40% of gamers now make purchases based on creator recommendations, and social touchpoints drive over 54% of player motivation to continue gameplay. Furthermore, transmedia collaborations, such as television adaptations of gaming franchises, have doubled their share of box office revenues, illustrating the power of cross-media synergy.
The monetization landscape is further diversifying through the growth of subscription services and the esports sector. Subscriptions are expected to reach 318 million active users and a $21.6 billion valuation by 2030, while the esports market is projected to hit $87.7 billion in the same timeframe. To navigate this complexity, many developers are adopting publishing-as-a-service models and leveraging AI to manage diverse revenue streams across platforms. Ultimately, the integration of cross-platform development, which can boost revenue by up to 40%, combined with sophisticated digital marketing and community-focused strategies, defines the modern trajectory of the global gaming industry.
- The global game publishing market is projected to grow from $117.4 billion in 2025 to $150.5 billion by 2030, driven by a market where 95% of revenue is already generated through digital distribution.
- Multiplatform launches have increased by 40% as developers prioritize cross-platform strategies, which can boost total revenue by up to 40%.
- Live Service Games have become the industry standard, with 95% of studios now developing titles specifically designed for recurring revenue models.
- Community-driven marketing is critical, as 40% of gamers make purchases based on creator recommendations and social touchpoints drive 54% of player retention.
- Subscription services are forecast to reach 318 million active users and a $21.6 billion valuation by 2030, while the esports market is expected to hit $87.7 billion in the same period.
Games Industry in 2025
The global games content and services market reached a record $199.4 billion in 2024, a 3.5% year-on-year increase that surpassed pandemic-era peaks. Despite this financial milestone, the industry faces significant structural challenges, including widespread layoffs, studio closures, and a shift toward de-risking strategies. Growth is expected to slow to 0.9% in 2025, largely due to the delay of Grand Theft Auto VI into 2026, which is projected to remove $2.7 billion from the 2025 console market. However, the industry is forecast to surpass the $200 billion threshold for the first time in 2025, with growth accelerating to 2.2% in 2026.
Key growth opportunities center on new hardware and emerging markets. The anticipated launch of the Nintendo Switch 2 in 2025 represents a $7-8 billion content opportunity, with significant potential for increased in-game monetization. Geographically, the Middle East, Africa, and Southeast Asia are expected to outperform Western markets, with the Middle East and Africa projected to grow by 6.3% in 2025. Additionally, significant headroom exists in mature markets like the U.S. by targeting underserved cohorts, specifically females aged 16-24 and adults over 55.
The industry is navigating a transition in monetization and platform dynamics. In-game spending accounts for 77% of total revenue, while physical media is expected to dwindle to just 2% of the market by 2026. To combat escalating AAA development costs, publishers are increasingly utilizing remakes, remasters, and transmedia franchise strategies. While mobile gaming remains the largest segment at 58% market share, PC gaming showed the strongest growth in 2024 at 5.7%. The analysis utilizes proprietary market modeling, financial KPIs, and quantitative consumer research across global regions to provide a comprehensive outlook through 2026.
- The global games market reached $199.4 billion in 2024, but growth is projected to slow to 0.9% in 2025 due to the delay of Grand Theft Auto VI into 2026.
- In-game spending now drives 77% of total industry revenue, while physical media is expected to decline to just 2% of the market by 2026.
- The launch of the Nintendo Switch 2 in 2025 is expected to create a $7–8 billion content opportunity with significant potential for increased in-game monetization.
- Mobile gaming maintains the largest market share at 58%, though PC gaming recorded the strongest growth in 2024 at 5.7%.
- Emerging markets in the Middle East and Africa are projected to grow by 6.3% in 2025, significantly outpacing growth in Western regions.
Gaming’s Cheating Crisis Report: The Impact on Players and Profit
The gaming industry is currently facing a significant integrity crisis, with 80% of players reporting encounters with cheaters in online environments. This prevalence has transformed cheating from a fringe issue into a routine experience for the majority of the community, with over half of gamers encountering unfair play at least several times a month. The widespread availability of cheating tutorials on social media platforms like YouTube and TikTok has further exacerbated the problem, creating a cycle where 62% of players admit to feeling tempted to cheat themselves.
The impact of this crisis extends beyond player frustration to significant financial and operational risks for developers. Approximately 42% of gamers have considered quitting specific titles due to cheaters, and 55% have either reduced or stopped their in-game spending entirely. This trend is particularly pronounced among high-value players, threatening the core revenue models of modern live-service games. Despite these challenges, there remains a high level of trust in developers to solve the issue, with 94% of players believing studios can effectively address the problem.
Data suggests a strong appetite for robust, industry-wide solutions. Approximately 73% of gamers are willing to undergo identity verification to ensure cheat-free matchmaking, and 79% support cross-game penalties where bans follow a player across multiple titles. Furthermore, 83% of respondents indicated they would be more likely to play a game credibly marketed as "cheat-free." These findings suggest that implementing verified identity systems could restore accountability, protect revenue streams, and improve player retention.
The research was conducted by Atomik Research on behalf of PlaySafe ID, surveying 2,013 adult PC gamers across the United Kingdom and the United States in July 2023. The sample consisted of active players, 82% of whom play multiple times per week, primarily focusing on first-person shooters, sports games, and casual titles.
- Cheating is a pervasive issue, with 80% of online players reporting encounters and over half experiencing unfair play at least several times a month.
- Financial stability is at risk, as 55% of gamers have reduced or stopped in-game spending and 42% have considered quitting specific titles due to cheating.
- Players are highly receptive to stringent security measures, with 73% willing to undergo identity verification and 79% supporting cross-game bans to ensure fair play.
- Marketability is directly tied to integrity, as 83% of players are more likely to engage with titles explicitly marketed as 'cheat-free'.
- Social media platforms like YouTube and TikTok are fueling the crisis by providing widespread access to cheating tutorials, leading 62% of players to feel tempted to cheat.
Cross-Platform Gaming: Bridging Mobile and PC/Console
The 2025 gaming landscape is defined by the convergence of mobile accessibility and PC/console depth. The primary thesis suggests that while mobile serves as a global discovery engine and a source of steady growth, PC and console platforms anchor brand prestige and high-value engagement. To maximize franchise value, publishers must strategically bridge these ecosystems through purposeful cross-platform design, turning mobile’s vast reach into lasting loyalty.
Data highlights a significant scale disparity between platforms: mobile is projected to reach 52 billion downloads and $82 billion in in-app purchase revenue in 2025, while the PC and console segment generates over $12 billion from 1 billion units sold. Mobile leaders like Roblox and Garena Free Fire drive mass acquisition, whereas premium titles such as EA SPORTS FC 25 and Marvel Rivals dominate engagement on Steam, PlayStation, and Xbox. The findings indicate that unified ecosystems, such as those used by Delta Force and Genshin Impact, strengthen retention by allowing players to switch devices without losing progress.
The scope of the analysis is global, covering over 100 markets with specific digital advertising data from 14 major regions, including the United States, Japan, and the United Kingdom. It focuses on the first three quarters of 2025, utilizing Sensor Tower’s proprietary App Performance, Video Game, and Pathmatics Advertising Insights. Methodology involves statistical sampling of digital ad placements and estimated revenue from the App Store and Google Play, excluding third-party Android stores and direct web payments.
Four strategic models for expansion are identified: companion apps for engagement, "lite" versions for mass discovery, adapted standalone experiences for genre diversification, and full cross-play models for community unification. The conclusion emphasizes that a resilient portfolio must balance high-volume mobile genres, such as Simulation and Puzzle, with high-depth PC genres like RPGs and Shooters to maximize monetization efficiency and franchise longevity.
- Mobile remains the primary driver of scale with 52 billion projected downloads and $82 billion in in-app purchase revenue for 2025, while PC and console segments generate over $12 billion from 1 billion units sold.
- Unified cross-platform ecosystems, exemplified by titles like Genshin Impact and Delta Force, significantly improve player retention by enabling seamless progress synchronization across devices.
- Publishers should adopt one of four strategic models—companion apps, 'lite' discovery versions, adapted standalone experiences, or full cross-play—to bridge the gap between mobile reach and PC/console engagement.
- A resilient gaming portfolio requires balancing high-volume mobile genres like Simulation and Puzzle with high-depth PC/console genres such as RPGs and Shooters to optimize monetization and franchise longevity.
- Mobile platforms currently function as global discovery engines for mass acquisition, whereas premium titles like EA SPORTS FC 25 and Marvel Rivals anchor high-value engagement on Steam, PlayStation, and Xbox.
From Games to the Big Screen: The Impact of IP Across Platforms
The entertainment industry is increasingly leveraging a transmedia strategy where video game intellectual property serves as the foundation for high-budget scripted content. This approach creates a symbiotic relationship between platforms, where the release of films and television series triggers a boomerang effect that revitalizes interest in the original games. Data indicates that these adaptations drive significant growth across multiple metrics, including active users, digital downloads, and in-app purchases, while simultaneously boosting the performance of the streaming services hosting the content.
The scope of this analysis covers major cross-platform releases between 2024 and 2025, focusing on global mobile, PC, and console gaming segments alongside digital advertising and streaming app performance. Key findings highlight the success of the Minecraft movie, which grossed over $900 million and led to a 44% spike in mobile in-app revenue and a 36% increase in console sales. Similarly, the Fallout television series drove a 23% increase in Amazon Prime Video downloads and a massive 410% surge in daily sales for Fallout 4 on PC. The longevity of this impact is notable, with daily active users for legacy Fallout titles remaining 225% higher for up to 20 weeks following the show's premiere.
Methodology relies on proprietary data from Sensor Tower, tracking digital market insights, app usage, and advertising spend. The data reveals that strategic marketing is essential to this success; for instance, Amazon increased its desktop video ad spend twentyfold to promote Fallout, specifically targeting gaming-focused platforms like Twitch and IGN. While results vary based on the faithfulness of the adaptation and the monetization model of the game, the overarching trend suggests that transmedia releases are a powerful tool for re-engaging historical players and attracting new audiences to established gaming franchises.
- The Fallout television series triggered a 410% surge in daily PC sales for Fallout 4 and sustained a 225% increase in daily active users for legacy titles for up to 20 weeks post-premiere.
- The Minecraft film grossed over $900 million while driving a 44% spike in mobile in-app revenue and a 36% increase in console sales.
- Transmedia adaptations create a symbiotic growth loop that simultaneously boosts gaming metrics and streaming platform performance, such as the 23% increase in Amazon Prime Video downloads following the Fallout series launch.
- Strategic marketing is a critical success factor, evidenced by Amazon increasing its desktop video ad spend twentyfold on gaming-centric platforms like Twitch and IGN to support the Fallout release.
- Video game IP is increasingly serving as a foundation for high-budget scripted content to re-engage historical players and attract new audiences across mobile, PC, and console segments.
Mapping IP fandom with the Global Gamer Study
This analysis explores the intersection of intellectual property (IP) fandom and player engagement within the global gaming industry. The primary thesis is that while transmedia collaborations are essential for driving player acquisition and retention in a live-service landscape, the effectiveness of an IP is heavily dictated by regional awareness and cultural sentiment. Success in global gaming requires a move away from one-size-fits-all licensing toward market-specific strategies that align with local fanbases.
The findings are based on the 2025 Global Gamer Study, which surveyed over 73,000 consumers across 36 markets, tracking awareness and attitudes toward 42 popular entertainment IPs. Data indicates that a majority of gamers in 24 of the 36 countries are more likely to play a game featuring their favorite IP. This influence is strongest in South Asia (74%) and Latin America (64%), while Western Europe and Oceania show more reserved engagement levels (45%).
The research categorizes IPs into four quadrants based on the relationship between awareness and favorability. Global Favorites, such as Harry Potter and Disney, maintain near-universal recognition (90%) and high sentiment. Familiar Faces like Star Wars and Barbie possess high awareness but suffer from polarizing or lower favorability in specific regions. Hidden Gems, including Studio Ghibli and various anime titles, maintain niche global awareness but command intense loyalty in specific markets like Japan or Vietnam. Finally, IPs with Limited Appeal, such as Doctor Who or Percy Jackson, struggle with both low recognition and lukewarm sentiment outside their core territories.
Geographic variations are stark; for instance, anime franchises like Dragon Ball achieve 85–90% awareness in Latin America and Southeast Asia, nearly double their recognition in the West. Conversely, Western staples like DC Comics see high awareness in the U.S. (70%) but significantly lower traction in Japan (21%). The study concludes that cultural resonance, linguistic accessibility, and historical distribution patterns are the primary drivers of IP success in the gaming sector.
- In 24 of 36 surveyed markets, gamers are more likely to play a title featuring an IP they favor, confirming that transmedia collaborations are a primary driver for acquisition and retention.
- IP influence on player engagement varies significantly by region, peaking in South Asia (74%) and Latin America (64%) compared to more reserved engagement in Western Europe and Oceania (45%).
- Global Favorites like Harry Potter and Disney maintain 90% recognition with high sentiment, whereas IPs like DC Comics show extreme regional variance, with 70% awareness in the U.S. versus only 21% in Japan.
- Anime franchises like Dragon Ball demonstrate the importance of market-specific strategies, achieving 85–90% awareness in Latin America and Southeast Asia—nearly double their recognition in Western markets.
- The 2025 Global Gamer Study, which tracked 42 entertainment IPs across 73,000 consumers, identifies cultural resonance, linguistic accessibility, and historical distribution as the primary determinants of IP success.
Roblox as a Strategic Growth Platform: What Developers Need to Know
Roblox has evolved from a youth-centric gaming site into a massive entertainment ecosystem and creator economy, boasting nearly 112 million daily active users and distributing over $300 million to creators in a single quarter. While the platform shares structural similarities with mobile gaming—such as an 80% mobile user base and monetization driven by cosmetics and gacha—it functions more like a social media platform such as TikTok or YouTube. Success is dictated by cultural fluency, rapid iteration, and social momentum rather than high graphical fidelity or traditional production cycles.
The platform’s audience is maturing, with the 13+ demographic growing at 54% year-over-year, significantly outpacing younger cohorts. This shift brings higher spending power and more sophisticated expectations to the ecosystem. Data indicates that Roblox is not a siloed experience; only 24% of players engage exclusively on mobile, with significant playtime occurring on PlayStation and PC. The genre landscape is dominated by Roleplay, Simulation, and Platformers, characterized by low-friction, social, and trend-driven mechanics that prioritize accessibility over complex skill sets.
For traditional developers, the platform serves as a strategic testing ground for intellectual property and audience cultivation among Gen Z and Gen Alpha. Because the discovery algorithm rewards speed and native platform knowledge, established studios are increasingly partnering with Roblox-native creators to navigate the unique development rhythm. The most effective strategies treat the platform as a long-term engagement tool rather than a standard publishing channel, focusing on branded activations and collaborative IP experiences to build brand affinity with the next generation of gamers.
- Roblox has scaled to 112 million daily active users and distributed over $300 million to creators in a single quarter, functioning more like a social media platform than a traditional gaming engine.
- The 13+ demographic is the platform's fastest-growing segment, increasing by 54% year-over-year and bringing higher spending power to the ecosystem.
- Success on the platform is driven by cultural fluency and rapid iteration rather than graphical fidelity, with discovery algorithms favoring native platform knowledge over traditional production cycles.
- Only 24% of players are mobile-exclusive, with significant engagement occurring across PlayStation and PC, necessitating a cross-platform approach to user retention.
- Established studios are increasingly partnering with Roblox-native creators to navigate the platform's unique development rhythm and trend-driven mechanics.
Gaming: Your Marketing Cheatcode
Gaming has evolved into a horizontal cultural layer encompassing 3.4 billion global players who utilize interactive platforms to build identity and community. Despite this massive reach, the sector currently receives less than 5% of global media investment, representing a significant disconnect between consumer attention and advertising spend. The industry is increasingly defined by transmedia expansion and social connectivity, particularly among Gen Z audiences who prioritize platforms like Roblox and Discord for brand discovery and social interaction. Success in this landscape requires a strategic shift from isolated sponsorships toward full-funnel integrations that align with specific player motivations, including relaxation, achievement, and immersion.
The shift toward non-intrusive brand integration utilizes high-impact formats such as rewarded video and custom in-game partnerships to secure superior video completion rates and brand recall. Immersive strategies drive substantial consumer consideration, with 55% of players expressing interest in branded virtual items. Furthermore, custom experiences within gaming environments can yield up to 100x higher attention levels than traditional social media. Case studies involving major titles like Genshin Impact demonstrate that blending digital fandom with real-world value can result in triple-digit sales growth and heightened community engagement.
As a full-funnel engine, gaming integrations now produce measurable lifts in awareness and consideration through interactive campaigns. Data indicates that gamified loyalty programs can increase purchase rates by 12% and guest spend by 64%, while in-game commerce on platforms like Roblox generates significant revenue for developers. Looking ahead, the industry trajectory is shaped by the expansion of cloud gaming and highly anticipated hardware and software launches, such as the Nintendo Switch 2 and Grand Theft Auto VI. These developments reinforce gaming's role as a primary driver of modern media consumption and commercial conversion.
- Gaming commands 3.4 billion players globally, yet receives less than 5% of total media investment, indicating a significant misalignment between consumer attention and advertising spend.
- Custom in-game experiences can generate up to 100x higher attention levels compared to traditional social media platforms.
- Immersive brand strategies are highly effective, with 55% of players expressing interest in acquiring branded virtual items.
- Gamified loyalty programs are proven to drive commercial performance, increasing purchase rates by 12% and guest spend by 64%.
- Strategic integration in titles like Genshin Impact demonstrates that blending digital fandom with real-world value can trigger triple-digit sales growth.
Video Gaming Report: How Platforms Are Colliding and Why This Will Spark the Next Era of Growth
The video gaming industry is transitioning into a new era of growth following a post-pandemic stabilization period. While the sector is unlikely to replicate the rapid doubling of the 2010s, a convergence of technological and structural shifts is expected to revitalize the market. This evolution is driven by four primary strategic trends: the integration of Generative AI, the expansion of the user-generated content (UGC) creator economy, the mainstream adoption of cloud gaming, and the regulatory opening of mobile app stores.
Key findings indicate that Generative AI is already being utilized by approximately 50% of studios to improve development efficiency and create adaptive gameplay, with 20% of new Steam games disclosing AI use by mid-2025. Simultaneously, the creator economy is surging; payouts from platforms like Roblox and Fortnite are projected to exceed $1.5 billion in 2025. Cloud gaming is also positioned for a massive scale-up, with revenues forecasted to grow from $1.4 billion in 2025 to $18.3 billion by 2030. This shift toward hardware-agnostic play is mirrored in distribution, where 33% of adult gamers have already purchased titles directly from developer web stores to bypass traditional platform fees.
The scope of this analysis is global, with a particular focus on major markets including the US, China, Germany, Japan, and South Korea. It covers the industry from late 2025 through projections for 2030, spanning mobile, console, and PC segments. Data is derived from the Global Gaming Survey of approximately 3,000 gamers, metadata analysis of the Steam platform, and interviews with industry leaders and developers.
The industry concludes that success in this new landscape requires a departure from traditional "console war" mentalities in favor of ecosystem-based strategies. Developers must master new monetization models, such as tiered pricing and windowing, to protect the value of premium content while navigating a market increasingly defined by infinite digital shelf space and algorithmic discovery.
- Cloud gaming revenue is projected to scale from $1.4 billion in 2025 to $18.3 billion by 2030, marking a transition toward hardware-agnostic play.
- The creator economy is expanding rapidly, with payouts to creators on platforms like Roblox and Fortnite projected to exceed $1.5 billion in 2025.
- Generative AI is currently used by 50% of studios to enhance development efficiency, with 20% of new Steam games expected to disclose AI usage by mid-2025.
- Direct-to-consumer distribution is gaining traction, as 33% of adult gamers have already purchased titles via developer web stores to circumvent traditional platform fees.
- Industry success now requires shifting from console-centric competition to ecosystem-based strategies that utilize tiered pricing and windowing to manage content value.
Insights into Global Mobile Game Marketing Trends for H1 2025
The first half of 2025 reveals a rapid shift in mobile‑game user‑acquisition toward AI‑driven creative production, with short‑form video, live‑action clips and in‑game audio ads now accounting for the majority of impressions. Generative‑AI tools and AI‑enhanced playable ads compress development cycles to under a week, allowing marketers to test multiple concepts at low cost while retaining retargeting as a core pillar of acquisition strategy.
Genre competition intensifies, especially for role‑playing games, which generate an average of 224 new creatives per advertiser each month. Casino titles expand their share by 14.5 % year‑over‑year, becoming the second‑largest spend category. Europe hosts the largest pool of advertisers—over 43 000 monthly, a rise of 10 000 from the previous year—while North America exhibits the highest creative density, with roughly 119 assets per advertiser. In casual games, AI‑generated vertical video now consumes about 40 % of media spend, underscoring the dominance of automated formats across regions.
Key operational challenges include limited reach to high‑value users, protracted creative rollout times, and declining engagement as mature audiences become ad‑fatigued. Lengthy or fragmented landing‑page experiences further erode trust, suppressing download conversion and long‑term retention.
To counter these pressures, firms are advised to institute rapid‑iteration pipelines that move concepts to live within seven days, maintain a refresh cadence of two to three creative updates per month, and prioritize concise, transparent messaging that streamlines the post‑click flow. Embracing these practices is projected to improve acquisition efficiency and sustain user interest amid an increasingly saturated global mobile‑gaming market.
- AI-driven creative production has become the industry standard, with generative tools and AI-enhanced playable ads compressing development cycles to under one week.
- Europe leads in market participation with over 43,000 monthly advertisers, while North America maintains the highest creative density at approximately 119 assets per advertiser.
- Casino games have emerged as the second-largest spending category, recording a 14.5% year-over-year increase in market share.
- Role-playing games are the most competitive segment, requiring an average of 224 new creatives per advertiser each month to maintain visibility.
- In the casual gaming sector, AI-generated vertical video now accounts for 40% of total media spend.
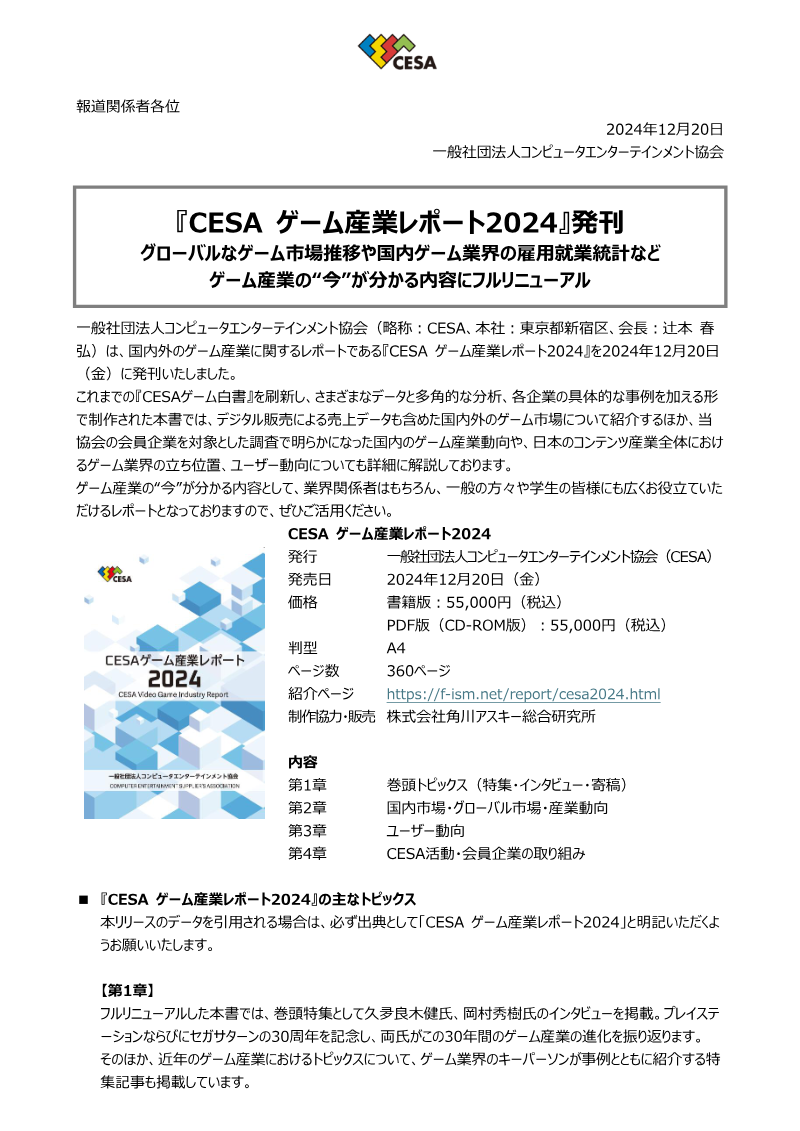
CESA Game Industry Report 2024
CESA Game Industry Report 2024 – Executive Summary (English)
1. Publication Details | Item | Information | |------|--------------| | Title | CESA ゲーム産業レポート 2024 (CESA Game Industry Report 2024) | | Publisher | 一般社団法人コンピュータエンターテインメント協会 (Computer Entertainment Supplier’s Association, CESA) | | Release date | 20 December 2024 (Friday) | | Price | ¥55,000 (incl. tax) – both printed book and PDF/CD‑ROM versions | | Format | A4, 360 pages | | ISBN / Catalog | CESAJ‑LV‑ (internal code) | | Production partner | 株式会社角川アスキー総合研究所 (Kadokawa ASCII Research Institute) | | Official page | <https://f-ism.net/report/cesa2024.html> | | Contact | [email protected] |
> Citation note – When quoting any data from the report, cite it as “CESA ゲーム産業レポート 2024”.
2. Report Structure
| Chapter | Focus | |---------|-------| | Chapter 1 – Front‑matter (Topics, Interviews, Contributions) | Interviews with industry veterans (久夛良木健, 岡村秀樹) reflecting on 30 years of PlayStation & Sega Saturn; other key‑person case studies. | | Chapter 2 – Market & Industry Trends (Domestic & Global) | Macro‑level market size, platform breakdown, development costs, employment, cross‑media context. | | Chapter 3 – User Trends | Player demographics, platform usage, esports, multi‑platform activity. | | Chapter 4 – CESA Activities & Member Initiatives | Overview of CESA‑hosted events (Tokyo Game Show, CEDEC) and member‑company projects. |
3. Key Findings
3.1 Global Game‑Content Market Size (2020‑2024) – Approximately ¥30 trillion in 2024, nearly double the 2020 level (¥20 trillion). Growth drivers – Strong yen‑depreciation effect post‑2022, continued expansion of mobile gaming, and rising PC‑gaming share (thanks to Steam). Platform share (2024) – Mobile: dominant share (≈ 60 % of global revenue). Console: ~ 20 % of revenue. PC: ~ 20 % (growing steadily).
3.2 Japan’s Content Industry & Game Share Total overseas export of Japanese content: ¥4.7 trillion (on par with semiconductor & steel sectors). Games’ contribution: ≈ 60 % of that export value → games are the primary driver of foreign‑exchange earnings within the broader content sector.
3.3 Domestic Game‑Industry Employment & Compensation Total industry employment: ≈ 200,000 workers (including peripheral sectors). Average annual salary: ¥7.08 million – markedly higher than the average across
- The global game-content market reached approximately ¥30 trillion in 2024, nearly doubling from the ¥20 trillion recorded in 2020.
- Mobile gaming remains the dominant global platform, accounting for approximately 60% of total revenue, while console and PC sectors each hold roughly 20% shares.
- Japanese game exports generate approximately ¥2.82 trillion, representing about 60% of the country's total ¥4.7 trillion content industry exports.
- The Japanese game industry's export value is now on par with major industrial sectors such as semiconductors and steel.
- The domestic game industry employs approximately 200,000 workers, including those in peripheral sectors.