Global
Documents
Target. Connect. Engage: Driving Profitable App Growth with Revenue-Boosting Strategies
The primary purpose of the analysis is to demonstrate how a strategic partnership between a mobile measurement partner (MMP) and TikTok’s advertising ecosystem can unlock profitable growth for app marketers. By integrating real‑time attribution, privacy‑preserving measurement, and value‑based optimization, brands can accurately credit campaigns, reduce fraud, and maximize return on ad spend (ROAS) across the entire customer journey.
Key findings show that cross‑platform visibility is essential for identifying high‑value users and optimizing acquisition budgets, especially amid tightening privacy regulations on iOS and Android. AppsFlyer’s comprehensive measurement suite, combined with TikTok’s SKAdNetwork tools and self‑reporting network, delivers precise audience targeting and cost‑effective user acquisition. Case studies from Burger King, Casas Bahia, and Carrefour illustrate tangible results: a 7× ROI for coupon activations, a 44 % lift in conversion rates with a 55 % ROI gain, and a 29 % increase in in‑app revenue with triple the return compared to other channels.
The document outlines best practices for app install and retargeting campaigns, recommending the use of App Event Optimization (AEO) and Value‑Based Optimization (VBO) to focus spend on high‑value actions. Automated Smart Performance Campaigns and real‑time ROAS measurement via AppsFlyer integrations further enhance efficiency and lifetime value.
Geographically, the insights apply globally across major mobile markets, with a focus on the U.S., Europe, and emerging regions where TikTok’s user base is rapidly expanding. The time frame covers current privacy‑driven advertising environments and anticipates ongoing downturns, positioning the partnership as a resilient growth strategy for 2024‑2026.
- Integrating AppsFlyer’s measurement suite with TikTok’s advertising ecosystem enables brands to maximize ROAS through real-time attribution and privacy-compliant user acquisition.
- Case studies demonstrate significant performance gains, including a 7x ROI for Burger King, a 44% conversion lift for Casas Bahia, and a 29% increase in in-app revenue for Carrefour.
- App marketers should prioritize App Event Optimization (AEO) and Value-Based Optimization (VBO) to focus advertising spend on high-value user actions.
- Automated Smart Performance Campaigns and real-time ROAS measurement are recommended strategies to maintain growth and efficiency through 2026 despite tightening privacy regulations.
- Cross-platform visibility is essential for identifying high-value users and optimizing acquisition budgets across both iOS and Android environments.
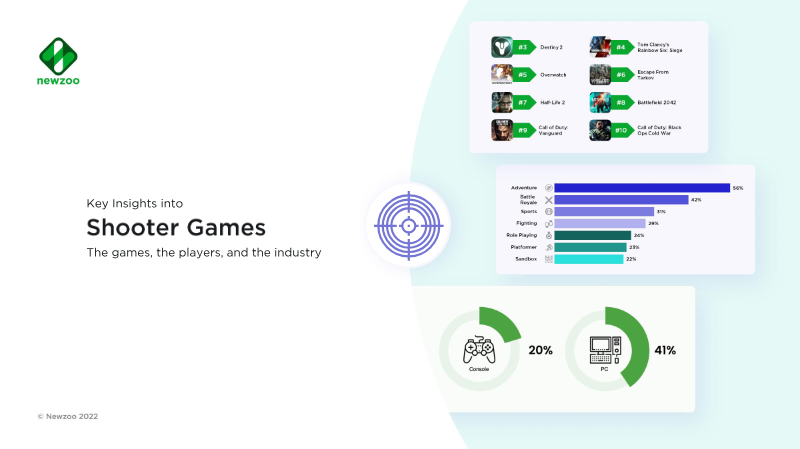
Key Insights into Shooter Games
Shooter games represent the fifth highest‑earning genre worldwide, generating approximately $2.24 billion in 2022 across all platforms. The report focuses on the genre’s popularity, player demographics, engagement patterns, and monetization strategies within a global context that excludes China and India. Data derive from Newzoo’s Global Games Market, Consumer Insights – Games & Esports 2022, and the Newzoo Expert platform, covering 37 markets with a sample of 19,544 recent shooter players and 60,020 broader gamers.
Key findings show that shooters dominate PC and console play, with 68 % of monthly active users (MAU) on these platforms also engaging in shooter titles. Player overlap with other genres is high: 56 % of shooter players also play adventure games, while strategy and simulation overlap remains low. The contemporary war theme and level‑based mechanics are the most common in shooter titles. Monetization is overwhelmingly pay‑to‑play; 97 % of shooter players experience in‑app purchases, and advertising is the least used model.
Demographically, core personas—Ultimate Gamers and All‑Round Enthusiasts—account for the largest shooter player base, yet nearly all persona groups play shooters. Motivations to spend include social interaction and access to special offers, with 13,659 of the 19,544 shooter players identified as payers. Live‑streaming data indicate that shooters rank highly on Twitch and Facebook Gaming, reinforcing the genre’s strong community presence. The report underscores shooters’ robust revenue streams, broad demographic appeal, and central role in competitive online play.
- Shooter games generated approximately $2.24 billion in 2022 across 37 global markets, excluding China and India.
- Shooters are a dominant force on PC and console platforms, capturing 68% of monthly active users.
- Monetization in the genre is heavily driven by in-app purchases, which are experienced by 97% of shooter players, while advertising remains the least utilized revenue model.
- Shooter players exhibit high cross-genre engagement, with 56% of the player base also participating in adventure games.
- The genre maintains a strong community presence and competitive profile, consistently ranking highly on streaming platforms like Twitch and Facebook Gaming.

Newzoo's Generations Report: How Different Generations Engage with Games
The report examines how gaming engagement varies across generational cohorts, drawing on a representative online sample of 72,068 respondents from 33 global markets (North America, EMEA, APAC). Data were collected via Computer Assisted Web Interviewing between January and April 2021. Findings show that younger generations devote a larger share of leisure time to gaming, with Gen Z and Millennials spending 11–12% of their free time on games versus 18% for Baby Boomers. Weekly playtime averages 7 hours and 20 minutes for Gen Z, 6 hours and 30 minutes for Millennials, dropping to just over 2 hours for Baby Boomers. Gaming remains the dominant entertainment medium across all ages, though motivations shift: younger players cite competition, socializing and achievement, while older players prioritize relaxation.
Platform preferences differ markedly; Gen Z spends 77% of gaming spend on mobile, whereas Baby Boomers allocate 73% to PC. Younger gamers also engage more with game‑related content, with 71–67% of Gen Z and Millennials both playing and watching games, compared to 44–51% for older cohorts. Persona segmentation reveals that “Ultimate Gamers” and “Community Gamers” dominate among Gen Z, whereas older groups are more likely to be “Time‑Fillers” or “Bargain Buyers.”
The report highlights the metaverse as a growing trend, with 70% of Gen Z and 63% of Millennials expecting to spend more time in virtual worlds. Overall, the study underscores a generational shift toward immersive, social gaming experiences and signals expanding opportunities for brands to reach diverse gamer audiences.
- Gen Z and Millennials spend significantly more time gaming weekly, averaging 7 hours 20 minutes and 6 hours 30 minutes respectively, compared to just over 2 hours for Baby Boomers.
- Platform spending habits are polarized by generation, with Gen Z allocating 77% of their gaming budget to mobile while Baby Boomers direct 73% of their spend toward PC.
- Engagement with game-related content is higher among younger cohorts, as 67–71% of Gen Z and Millennials both play and watch games, compared to 44–51% for older generations.
- Motivations for gaming diverge by age, with younger players prioritizing competition, socializing, and achievement, while older players primarily seek relaxation.
- The metaverse is a significant growth area, with 70% of Gen Z and 63% of Millennials anticipating increased time spent in virtual worlds.

Mobile Gaming M&A Playbook: How to Identify and Target High‑Growth Gaming Companies
The playbook outlines a systematic approach for mobile gaming publishers and investors to identify, evaluate, and acquire high‑growth developers. It argues that the mobile gaming market—projected to reach $138 billion in 2025—has become a prime arena for mergers and acquisitions, citing recent deals such as Zynga’s $2 billion purchase of Peak Games, EA’s $2.1 billion acquisition of Glu Mobile, and Embracer Group’s multi‑year funding round for future buys. The document stresses that M&A serves dual purposes: portfolio diversification and the acquisition of talent, expertise, and new IPs that can accelerate growth beyond a publisher’s core genres.
Key findings highlight the importance of data‑driven target selection. Sensor Tower’s Game Intelligence platform is promoted as a tool for tracking genre trends, revenue trajectories, and market share across regions. The playbook recommends establishing clear acquisition criteria—budget limits, company size, geographic focus—and using custom alerts and taxonomy filters to surface promising titles. It also advises building structured lead‑tracking workflows, labeling qualified versus unqualified prospects, and continuously monitoring portfolio performance to spot strategic shifts or revenue declines that may signal acquisition opportunities.
The scope covers the global mobile gaming industry, with particular emphasis on North America and Southeast Asia, over a recent five‑year period marked by accelerated M&A activity. Methodologically, the playbook relies on Sensor Tower’s proprietary analytics, supplemented by industry news feeds from outlets such as Pocket Gamer, VentureBeat, and Crunchbase. The conclusion urges publishers to leverage analytics, maintain rigorous criteria, and stay alert to market movements in order to secure advantageous acquisitions that align with long‑term growth objectives.
- The mobile gaming market is projected to reach $138 billion by 2025, driving significant M&A activity as publishers seek to diversify portfolios and acquire new talent and intellectual property.
- High-profile acquisitions demonstrate the scale of industry consolidation, including Zynga’s $2 billion purchase of Peak Games and EA’s $2.1 billion acquisition of Glu Mobile.
- Effective target identification requires a data-driven approach using platforms like Sensor Tower to track specific genre trends, revenue trajectories, and regional market share.
- Publishers should establish rigorous acquisition criteria—including defined budget limits, company size, and geographic focus—to systematically filter potential targets.
- Strategic lead-tracking workflows are essential for distinguishing qualified prospects from unqualified ones and monitoring existing targets for revenue declines or shifts that signal an acquisition opportunity.
Global Gaming Industry Takes Center Stage
The provided text does not contain the content of the document titled Global Gaming Industry Takes Center Stage, as the source link is restricted and inaccessible. Consequently, it is impossible to extract the main thesis, key findings, or methodological details required for an analytical summary. The available information consists solely of a server-side error message indicating a lack of authorization to view the requested file.
To provide a professional and accurate summary, the full text of the report must be made available. Once the content is accessible, the analysis will focus on identifying the primary industry trends, geographic scope, and statistical data points presented by the authors. Please provide the complete text or a functional link to the document to facilitate a comprehensive review of the gaming industry's current market position and future outlook.
- The provided report content is currently inaccessible due to a server-side authorization error.
- No factual data, market statistics, or industry trends are available for analysis from the provided source text.
- The document failed to load, preventing the extraction of any concrete insights regarding the global gaming industry.
- A comprehensive summary cannot be generated until the full text of the report is provided.
- The current input contains only an error message rather than the intended industry research.
Games 2025: The Industry Quest for Growth
The global games market reached a record $199.4 billion in 2024, cementing its status as the preeminent force in the entertainment sector. Despite this scale, the industry faces a period of moderated growth, with projections for 2025 hovering at approximately 1%. This deceleration stems from a combination of high-profile release delays, such as the postponement of major titles, and a tightening early-stage funding environment. To navigate this landscape, firms are shifting their focus from aggressive expansion toward operational efficiency, lean development cycles, and the optimization of existing intellectual property.
Strategic growth in 2025 will rely heavily on geographic diversification and demographic expansion. Emerging markets in the Middle East and Southeast Asia represent significant frontiers, while developers are increasingly targeting underserved cohorts, including older gamers and young adult females. Furthermore, the industry is leveraging user-generated content platforms like Roblox to maintain engagement among younger audiences. Hardware cycles, particularly the anticipated launch of the Nintendo Switch 2, remain a critical catalyst for consumer spending, providing a necessary boost to the broader market ecosystem.
To combat the dual pressures of escalating AAA development costs and fragmented consumer attention, publishers are adopting more conservative financial models. This includes a heavy reliance on remakes, remasters, and multi-platform porting to extract maximum value from established assets. Simultaneously, companies are pursuing margin expansion through diversified monetization strategies, such as hybrid mobile models and direct-to-consumer web shops that bypass traditional app store fees. By transitioning toward holistic franchise management that spans licensing, subscription services, and cross-media integration, the industry aims to stabilize revenue streams and ensure long-term sustainability in an increasingly competitive global environment.
- The global games market reached $199.4 billion in 2024, but growth is projected to decelerate to approximately 1% in 2025 due to release delays and reduced early-stage funding.
- Publishers are prioritizing operational efficiency and asset optimization, focusing on remakes, remasters, and multi-platform porting to mitigate the rising costs of AAA development.
- Strategic growth is shifting toward geographic expansion in the Middle East and Southeast Asia, alongside targeting underserved demographics like older gamers and young adult females.
- Companies are pursuing margin expansion by implementing hybrid mobile monetization models and direct-to-consumer web shops to bypass traditional app store fees.
- The industry is leveraging user-generated content platforms like Roblox to maintain engagement among younger audiences while managing fragmented consumer attention.
The Mobile App Growth Report: 2025 Edition
Global mobile app growth remains resilient in 2025, characterized by an 11% year-over-year increase in installs and a 10% rise in user sessions. This expansion is increasingly defined by a shift from pure volume-based acquisition toward a value-driven model that balances cost efficiency, engagement, and long-term retention. The Asia-Pacific region has emerged as the primary engine of this global momentum, achieving the highest regional growth score of 45, with India specifically leading all individual nations with a score of 49. While established markets like North America show more modest growth metrics, they remain critical hubs for high-value user monetization and sophisticated optimization strategies.
Gaming continues to be the dominant vertical worldwide, particularly within the hyper-casual and hybrid-casual subgenres. This sector is especially potent in emerging markets; India’s gaming growth score of 52.2 underscores its status as a premier expansion target, while the Latin American and Middle Eastern markets are projected to reach significant revenue milestones of $35.9 billion and $3.73 billion respectively by 2030. Beyond gaming, the publications and utilities sectors have demonstrated consistent strength across Western markets, indicating a diversified landscape where functional and content-driven apps maintain high engagement levels.
The current mobile ecosystem requires a strategic pivot toward sophisticated analytics and retention-focused operations. In regions like North America, where user acquisition costs are higher, success depends on maximizing average revenue per user and leveraging artificial intelligence to refine marketing spend. Meanwhile, specific regional opportunities, such as the rise of card and arcade games in Türkiye, highlight the importance of localized content strategies. Ultimately, the global market is transitioning into a phase where sustainable growth is achieved through the integration of high-quality user experiences and data-driven efficiency rather than simple install volume.
- Global mobile app installs grew 11% year-over-year in 2025, with user sessions increasing by 10% as the industry shifts from volume-based acquisition to value-driven retention.
- The Asia-Pacific region is the primary driver of global growth with a score of 45, led by India, which holds a national growth score of 49 and a gaming-specific growth score of 52.2.
- Gaming remains the dominant global vertical, with Latin American and Middle Eastern markets projected to reach revenue milestones of $35.9 billion and $3.73 billion respectively by 2030.
- In high-cost markets like North America, profitability now relies on maximizing average revenue per user and utilizing AI-driven analytics to optimize marketing spend.
- Hyper-casual and hybrid-casual subgenres are the most potent gaming categories, particularly within emerging markets.
Playing to Win: 2025 Digital Game Advertising Report
The 2025 digital gaming market is defined by a strategic pivot toward user quality and high-velocity creative iteration, with global advertising expenditure reaching $8.7 billion. Despite a year-over-year decline in total mobile and PC downloads, the industry remains robust through the resurgence of the shooter genre and the continued dominance of 4X Strategy and Casual titles. Geographically, growth is concentrated in North American and Asian markets, fueled by high-profile releases such as Battlefield 6 and Valorant Mobile. This landscape reflects a shift where major publishers like Microsoft and Dream Games utilize aggressive spending to maintain market share in an increasingly competitive environment.
Advertising strategies have evolved to prioritize "instantly legible" gameplay and the rapid deployment of creative assets to combat audience fatigue. Static image ads remain a resilient tool due to their cost-effectiveness, while generative AI is increasingly employed to test and iterate high volumes of creative concepts. Intellectual property collaborations, featuring franchises like Naruto and Teenage Mutant Ninja Turtles, serve as a primary mechanism for lowering acquisition costs. Furthermore, platforms like YouTube have become essential for reaching PC and console audiences, while Apple Search Ads are leveraged tactically to capture competitor keywords and dominate search visibility.
The digital ecosystem also highlights the growing influence of internal discovery and content creators. Roblox maintains a massive web presence with over 187 billion visits, driven largely by organic traffic and internal discovery mechanisms rather than traditional external advertising. Meanwhile, viral indie titles and major releases like Marvel Rivals achieve commercial success by leveraging creator-led marketing. Ultimately, the industry in 2025 is characterized by a sophisticated blend of data-driven acquisition, aggressive platform-specific tactics, and a reliance on established IPs to navigate a market where engagement quality has surpassed sheer scale as the primary metric for success.
- Global digital gaming advertising expenditure reached $8.7 billion in 2025, with major publishers like Microsoft and Dream Games utilizing aggressive spending to maintain market share.
- The industry has shifted its primary success metric from sheer download scale to engagement quality, despite a year-over-year decline in total mobile and PC downloads.
- Roblox continues to bypass traditional external advertising, generating 187 billion visits through organic traffic and internal discovery mechanisms.
- Advertising strategies now prioritize 'instantly legible' gameplay and the use of generative AI to rapidly iterate high volumes of creative assets.
- Intellectual property collaborations, such as those featuring Naruto and Teenage Mutant Ninja Turtles, are being used as a primary mechanism to lower user acquisition costs.
Mobile Game Genre Report: Comparing and Contrasting Eastern and Western Markets
This analysis explores the hypercasual mobile gaming landscape, comparing market dynamics between Western regions, such as the United States and United Kingdom, and Eastern markets, specifically Japan and South Korea. Utilizing 2021 download data and consumer insights from Newzoo and Pangle, the findings reveal that hypercasual games accounted for 36 of the top 100 most-downloaded mobile games globally. While the genre dominates Western charts—representing nearly half of the top 100 downloads in the U.S. and U.K.—it maintains a smaller footprint in Japan and South Korea, where it comprises approximately 20% of top downloads.
The sector is characterized by rapid evolution and high competition, with only eight of the top 36 hypercasual titles from 2020 remaining in the 2021 rankings. A significant shift in subgenre popularity occurred during this period, as runner and racing mechanics overtook simulation and ASMR themes. Demographically, hypercasual players across all four key markets skew male and are younger than the general mobile gaming population, with an average age below 30. These players often engage with midcore and hardcore genres, such as RPGs and strategy games, making them a valuable audience for cross-genre user acquisition.
To combat historically low retention rates—often falling below 10% by day seven—developers are increasingly adopting "hybrid-casual" strategies. This involves integrating lite meta features, progressive difficulty, and live operations to deepen engagement. Monetization remains heavily reliant on in-game advertising, with interstitial videos being the most prevalent format. However, the rise of hybrid models has introduced new revenue streams, including "remove ad" IAPs and battle passes. Success in Eastern markets specifically requires deep localization, including busier user interfaces and culturally specific live events, to effectively scale and improve lifetime value.
- Hypercasual games represent 36% of the top 100 global mobile downloads, though they command nearly 50% of top charts in the U.S. and U.K. compared to only 20% in Japan and South Korea.
- The hypercasual sector suffers from high volatility, with only eight of the top 36 titles from 2020 maintaining their positions in the 2021 rankings.
- Developers are shifting toward 'hybrid-casual' models—incorporating lite meta features and live operations—to address retention rates that typically drop below 10% by day seven.
- Runner and racing mechanics have overtaken simulation and ASMR themes as the dominant subgenres in the hypercasual market.
- Hypercasual players skew male and under 30 years old, frequently engaging with midcore and hardcore titles like RPGs and strategy games.
State of Mobile 2025: TikTok Edition
The mobile industry reached a significant milestone in 2024, generating a record $150 billion in in-app purchase revenue, representing a 12.5% year-over-year increase. While global downloads experienced a marginal 1% decline to 136 billion, user engagement reached an all-time high of 4.2 trillion total hours. This growth was primarily fueled by non-gaming sectors, specifically Entertainment, Productivity, and Photo & Video, alongside a recovering mobile gaming market where eleven titles surpassed $1 billion in annual revenue. Geographically, North America and Europe remain the strongest monetization hubs, though nearly 80% of total consumer spend now occurs outside an app’s home country, signaling a highly globalized marketplace.
Artificial Intelligence has emerged as the primary catalyst for industry transformation, with AI chatbots recording a 200% revenue surge and generative AI apps reaching $1.3 billion in annual spend. This technology is being integrated across diverse verticals, from productivity tools to dating apps like Tinder and Grindr, which are utilizing AI to streamline user experiences and facilitate real-world connections. The Productivity and Utility sector specifically benefited from this trend, seeing a 35% revenue increase to $15 billion. Furthermore, niche categories such as short-form drama apps and fitness reward platforms are gaining significant traction, with the latter benefiting from a shift toward social "run clubs" and outdoor exercise.
The 2024 landscape also highlights a shift in monetization strategies and user behavior. In the dating sector, revenue grew by 14% despite a decrease in time spent, suggesting that users are prioritizing efficient, high-value interactions over passive scrolling. Meanwhile, the Health and Fitness category continues to see strong seasonal surges and global expansion in markets like Germany and Australia. Across all sectors, the industry is moving toward community-focused retention and sophisticated subscription models, leveraging AI to maintain high per-user monetization even as traditional download growth stabilizes in mature markets.
- The mobile industry generated a record $150 billion in in-app purchase revenue in 2024, marking a 12.5% year-over-year increase despite a 1% decline in global downloads.
- Artificial Intelligence is the primary industry catalyst, evidenced by a 200% revenue surge for AI chatbots and $1.3 billion in annual spend on generative AI applications.
- The Productivity and Utility sector grew 35% to reach $15 billion in revenue, driven largely by the integration of AI tools.
- The mobile gaming market is recovering, with eleven individual titles surpassing $1 billion in annual revenue during 2024.
- The marketplace is increasingly globalized, with nearly 80% of total consumer spend now occurring outside of an app’s home country.
Impact Report 2025
The FY 2025 impact analysis presents Electronic Arts’ comprehensive ESG strategy, arguing that responsible stewardship of people, planet, and data is integral to sustainable growth in the interactive‑entertainment sector. By quantifying progress across talent, climate, privacy and security, the report demonstrates how the company translates corporate responsibility into measurable outcomes while maintaining its global market position.
Across a workforce of more than 6,000 employees worldwide, 83 % now have access to internal AI tools, and 17 % of new hires are returning staff, contributing to an industry‑leading attrition rate of –0.1 %. Expanded benefits—including paid parental leave and bereavement support—paired with a balanced gender composition, underpin the talent‑focused results. Community engagement generated 18,000 volunteer hours and $5.9 million in investments, reinforcing the social dimension of the strategy. Environmental performance shows a clear downward trajectory: total operational emissions fell to 6.6 Mt CO₂e in FY25, down from 7.3 Mt in FY24 and 10.6 Mt in FY23, with Scope 1 emissions at 2.98 Mt and Scope 2 (market‑based) comprising the remainder, while energy consumption reached 380,859 GJ, fully sourced from office operations. The company’s carbon‑neutral status and renewable‑energy initiatives address identified climate risks such as acute physical events, volatile energy prices, rising carbon costs and emerging reporting regulations.
Data‑privacy and security are governed by a privacy‑by‑design framework overseen by the Audit Committee, delivering explicit player notice, consent and control, data‑minimisation, and partner‑risk contracts. The security management system aligns with ISO, NIST and CIS standards, undergoes annual independent validation, operates a 24‑hour SOC and mandates annual training for all staff. An articulated AI governance model completes the governance pillar, ensuring responsible deployment of emerging technologies. Collectively, these initiatives illustrate a holistic, globally scoped commitment to ESG excellence throughout FY 2025.
- Electronic Arts achieved a net-zero attrition rate of -0.1% in FY2025, supported by a workforce of over 6,000 employees and a 17% rate of returning staff among new hires.
- Operational carbon emissions decreased to 6.6 Mt CO2e in FY2025, down from 7.3 Mt in FY2024 and 10.6 Mt in FY2023, maintaining the company's carbon-neutral status.
- 83% of the global workforce now has access to internal AI tools, supported by a formal AI governance model to ensure responsible technology deployment.
- The company invested $5.9 million and logged 18,000 volunteer hours in community engagement initiatives during the 2025 fiscal year.
- Total energy consumption reached 380,859 GJ in FY2025, with all office operations fully sourced from renewable energy.
Plan Your Chart-Topping Game Launch: Monster Hunter Case Study
The case study demonstrates how Capcom leveraged Stream Hatchet’s campaign platform and Sideqik’s influencer‑management tools to create a viral cultural moment for the launch of Monster Hunter Wilds. The core strategy combined a 12‑hour marathon live stream hosted by high‑profile YouTube creator iShowSpeed, bespoke in‑game weapon and armor designs from cosplay influencers, and a DLC‑code giveaway that directed viewers to a custom landing page. Data‑driven planning, contract coordination, and cross‑team communication were used to ensure seamless execution and to maximize both paid and earned reach across YouTube, TikTok, Instagram and Twitch.
Performance metrics show the initiative generated 5.03 million earned‑media views, placing iShowSpeed at the fifth‑most‑watched Monster Hunter Wilds streamer on launch day, and achieved a 7.1 percent engagement rate on earned media. Seventy‑two earned‑media posts contributed to the view total, while platform‑level analysis recorded earned‑view shares of roughly 3.8 percent and paid‑view shares of 3.7 percent, with an overall engagement rate of 3.2 percent. Overlap analysis identified a low‑overlap, large‑audience segment of approximately 7.2 million Twitch users, informing future audience‑targeting decisions.
The methodology relied on Stream Hatchet and Sideqik SaaS platforms to capture real‑time chat sentiment, viewer overlap, benchmark comparisons, and code‑distribution analytics. A dedicated team of data analysts produced a comprehensive post‑campaign report that highlighted strengths, weaknesses, and actionable modifications for subsequent launches. The campaign’s geographic scope was global, focusing on the major streaming ecosystems active in early 2025, and targeted the core gaming and esports audience segments associated with action‑RPG titles.
- Capcom’s Monster Hunter Wilds launch campaign generated 5.03 million earned-media views and achieved a 7.1 percent engagement rate on earned content.
- A 12-hour marathon stream featuring iShowSpeed positioned him as the fifth-most-watched creator for the game on launch day.
- The campaign utilized a multi-platform strategy across YouTube, TikTok, Instagram, and Twitch, resulting in an overall engagement rate of 3.2 percent.
- Audience overlap analysis identified a distinct, low-overlap segment of 7.2 million Twitch users, providing a data-backed foundation for future targeting.
- The initiative combined high-profile influencer partnerships with bespoke in-game content and DLC-code giveaways to drive traffic to a custom landing page.