Showing 30 of 156 results · 0.28s
Jan 2022
Games India Plays!: A Look into the Gaming Habits of Indian Mobile Gamers and How to Reach Them
Newzoo
with 91% playing on mobile devices. Revenue for 2022 reached $2.2 billion, with RMG contributing over 50% of the total industry revenue in the preceding year. Demographic data
Report24 pages
Jan 2021
Video Game Streaming Trends Report: 2021 Yearly Report
Stream Hatchet
highlights 10 peak moments that drew record concurrent viewership, underscoring the influence of esports and mobile‑game tournaments. Demographic analysis shows a persistent gender imbalance: only
Report28 pages
Jan 2025
Asian & MENA Markets: 2025 Half-Year Report
Niko Partners
recalibrated growth, with total revenues across key sub-regions projected to reach significant milestones by 2025. China remains the dominant force, with revenues expected to hit $51.2 billion
Report3 pages
Jan 2020
The Past, Present and Future of Games: Global and Local Opportunities
Newzoo
accounting for 49% of global consumer revenues. Furthermore, the rise of cloud gaming is expected to generate $4.8 billion in revenue by 2023, supported by major infrastructure plays
Report33 pages
Mar 2024
Turkey Game Market 2023 Report
Gaming in Turkey
The Turkish gaming market demonstrated significant resilience and maturation throughout 2023, maintaining its status as
Report351 pages
Consolidated Financial Results: Six Months Ended September 30, 2022
Konami Group Corporation
year fiscal forecast of ¥320,000 million in revenue and ¥76,500 million in operating profit. Despite these revenue gains, profitability faced significant downward pressure during the first
Financial19 pages
Consolidated Financial Results: Nine Months Ended December 31, 2022
Konami Group Corporation
company’s continued reliance on its Digital Entertainment division as a primary revenue engine, even as it diversifies its international footprint. Despite these gains, profitability faced substantial headwinds
Financial18 pages
Jan 2022
Newzoo’s Games, Esports, Live Streaming, Cloud and the Metaverse
Newzoo
The analysis examines how emerging technologies and shifting consumer behaviors are reshaping the global gaming
Report30 pages
Apr 2021
GameStop's Midlife Crisis
SuperJoost
The gaming industry is currently navigating a period of significant structural transition, characterized by legal
Article
2015 Interim Report
Tencent
Tencent Holdings Limited demonstrated robust financial growth during the first half of 2015, characterized by
Financial90 pages
Jan 2025
German Games Industry: 2025
game – Verband der deutschen Games-Branche e. V.
The German games industry navigated a period of significant contraction in 2024, with total market
Report39 pages
For the Game: Data Fusion Sheds a New Light on Players
InvestGame
Gaming is projected to reach 3.5 billion players and generate over US$225 billion in
Report42 pages
Annual Report of the German Games Industry 2024
game – Verband der deutschen Games-Branche e. V.
The German games industry reached a total revenue of 9.97 billion euros in 2023, marking
Report41 pages
Consolidated Financial Results: Year Ended March 31, 2026
Konami Group Corporation
Konami Group Corporation achieved record-breaking financial performance for the fiscal year ending March 31
Financial20 pages
Jan 2019
Tencent Games Strategy 2019
Niko Partners
Tencent’s strategic pivot in 2019 marks a recovery from the previous year’s regulatory
Report14 pages
Jan 2024
Türkiye Game Market Report: 2024
Gaming in Turkey
daily. While mobile gaming remains the dominant segment—accounting for $490 million in revenue—the industry is currently undergoing a strategic pivot. Developers are shifting focus from hyper
Report372 pages
Jan 2024
Levelling Up: State of India Interactive Media and Gaming Research FY24
Lumikai
which experienced a 53% year-on-year revenue increase. In-app purchases remain the primary growth driver, with the average revenue per paying user rising
Report15 pages
Nov 2020
Corsair Gaming, Inc. Form 10‑Q for the quarter ended September 30, 2020
Corsair Gaming
Warranty provisions and non‑cancelable purchase commitments increased modestly, reflecting higher product shipments. Revenue concentration remains a key risk: roughly half of sales come from a handful
Article1 pages
Sep 2023
Gaming Industry Report: Q3 2023
Konvoy
The global gaming industry experienced a period of stabilization and strategic realignment during the third
Report31 pages
Report of the German Games Industry: 2026
game – Verband der deutschen Games-Branche e. V.
The German video games market solidified its status as Europe’s largest in 2025, achieving
Report37 pages
Jan 2023
Video Game Streaming Trends Report: Q2 2023
Stream Hatchet
watched platform. Kick’s growth was driven by a creator-friendly 95-5 revenue split and high-profile signings like xQc and Amouranth, leading to a 204% increase
Report24 pages
Jan 2022
Games: India Plays!
EA
The report examines the rapidly expanding Indian mobile gaming market, highlighting a projected 91 % share
Report24 pages
Apr 2026
VCT 2027: New Tournament Model, Open Qualifiers, and Unified System
Esports Charts
The 2027 VALORANT Champions Tour marks a fundamental shift in competitive structure, moving away from
Article1 pages
Jul 2026
Motorsport Games Builds Control Defenses as Red Oak Stake Reaches 11%
The Esports Advocate
Motorsport Games has implemented a series of defensive governance measures, including a one-year poison
Article1 pages
Jan 2022
2022 Global White Paper on Mobile Advertising & Marketing Game
SocialPeta
advertising landscape by volume, yet RPGs and strategy titles commanded the highest revenue and advertising spend. A notable trend involved mid-core developers utilizing "lightweight" or drama-based
Whitepaper191 pages
State of the Polish Video Game Industry: 2017
Polish Games Association, Indie Games Poland Foundation, Kraków Technology Park, Grupa Onet, Gry-Online
The Polish video game industry has matured into a globally recognized sector, characterized by a
Report104 pages
Jan 2019
Friendly Fraud: Facebook's Unwillingness to Err on the Side of the Consumer
SuperJoost
The primary thesis of this analysis is that Facebook’s historical handling of in-game
Article
FY26/3 Earnings Summary and Mid- to Long-Term Growth Strategies
Capcom
multi‑channel IP exploitation model that includes character licensing, media tie‑ins, eSports, and mobile extensions, with particular emphasis on emerging markets to push long‑term unit volumes
Financial41 pages
Jun 2019
Amazon Gaming Has Hit a Rough Patch
SuperJoost
Amazon’s internal video game development efforts are currently facing significant challenges, contrasting sharply with
Article
The Rise and Reset of Sweden's $19B Gaming Capital Machine
InvestGame
The analysis demonstrates that Sweden’s gaming sector has evolved into a $19 billion capital
Report12 pages
Games India Plays!: A Look into the Gaming Habits of Indian Mobile Gamers and How to Reach Them
Jan 202224 pages3k words
Summary
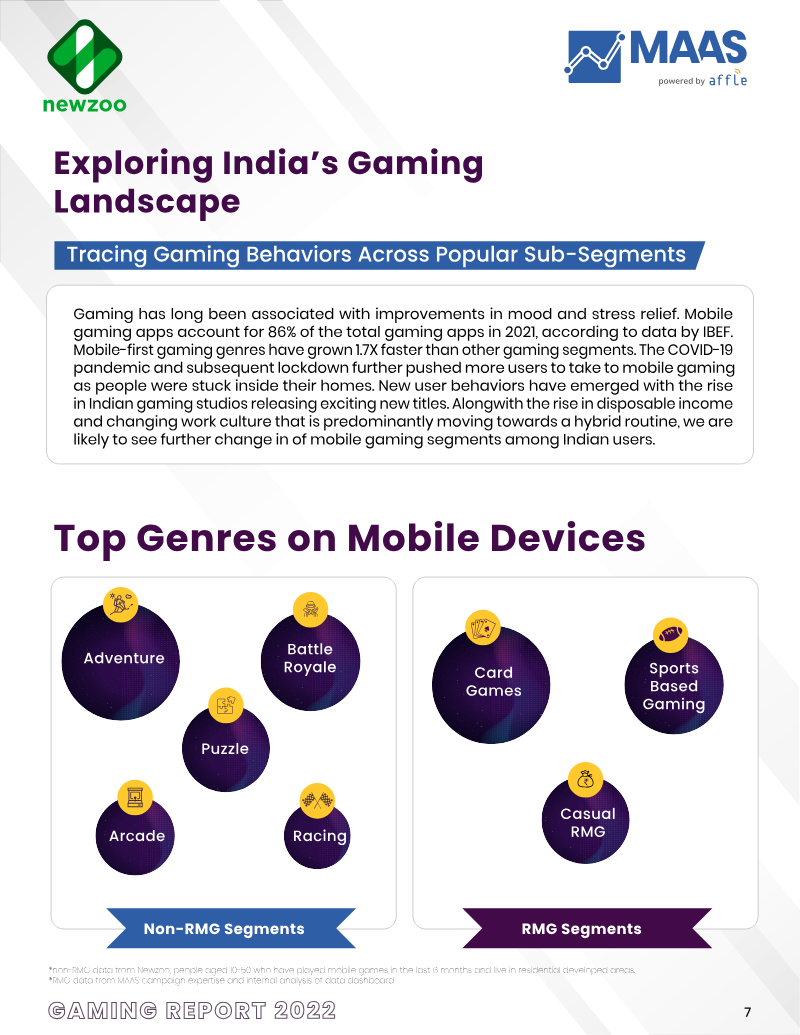
The Indian mobile gaming industry is undergoing a significant transformation, driven by affordable data, increased smartphone penetration, and a shift toward digital entertainment. This analysis, covering the 2022-2027 period, segments the market into Real Money Gaming (RMG)—including card-based and fantasy sports—and non-RMG categories like adventure, battle royale, and puzzles. Utilizing data from Newzoo and Affle MAAS, the findings highlight a market of 373 million online gamers as of 2022, with 91% playing on mobile devices. Revenue for 2022 reached $2.2 billion, with RMG contributing over 50% of the total industry revenue in the preceding year.
Demographic data reveals a young, male-skewing audience, particularly in the adventure and battle royale genres, where 55% of players are aged 13-27. While non-RMG players are motivated by stress relief and time-filling, RMG players are driven by seasonal events and the opportunity to earn rewards. Fantasy sports see massive spikes during major cricket tournaments, while card-based RMG peaks during festive seasons. Engagement is exceptionally high, with over 80% of mobile gamers consuming gaming video content and 44% engaging with esports.
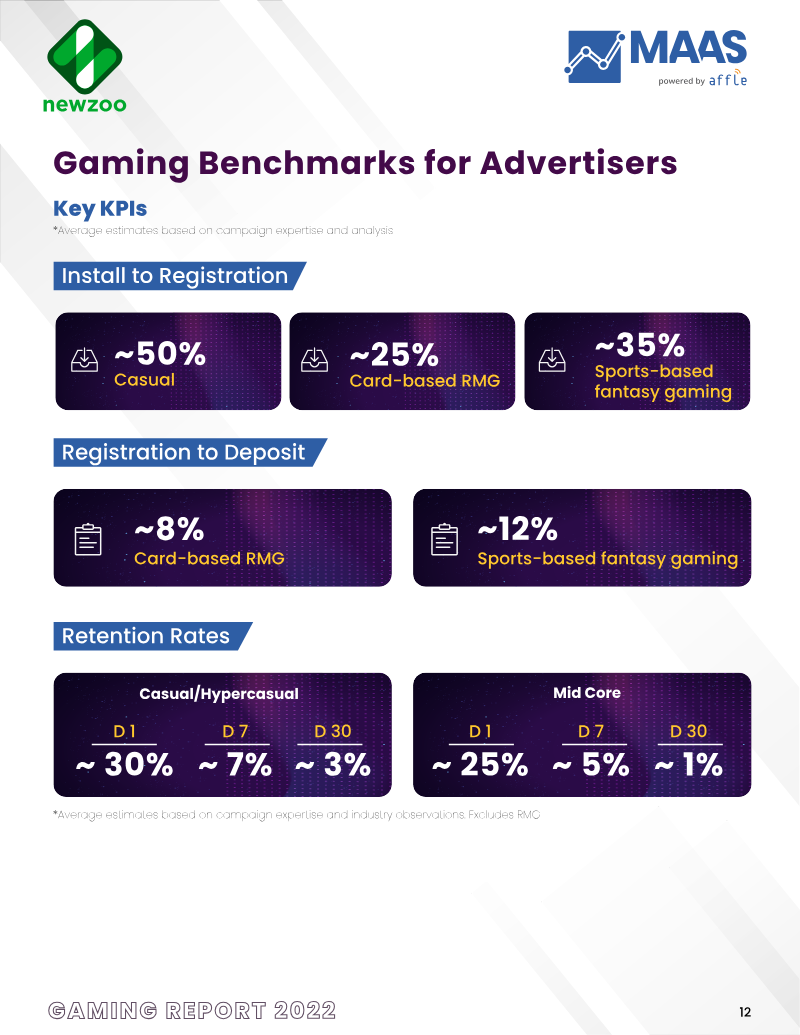
For advertisers, the report establishes critical benchmarks and growth strategies. Successful user acquisition relies on navigating a complex funnel where install-to-registration rates hover around 25-50% depending on the sub-genre. Experts suggest that growth is increasingly driven by Tier 2 and Tier 3 cities, facilitated by UPI-based micro-payments. To maximize return on ad spend, marketers are encouraged to use vernacular creatives, programmatic targeting to reduce audience overlap, and a mix of ad formats like playable and short-video ads. The industry is poised for further disruption through the integration of Web3 technologies, blockchain-based play-to-earn models, and the rise of "gaming malls" or super-apps.
Pages
Insights
- The Indian mobile gaming market reached $2.2 billion in 2022, driven by a base of 373 million online gamers where 91% play exclusively on mobile devices.
- Real Money Gaming (RMG), including fantasy sports and card games, accounts for over 50% of total industry revenue.
- The core demographic for adventure and battle royale genres is young and male-skewing, with 55% of players falling within the 13-27 age bracket.
- User acquisition in the mobile gaming sector faces a 25-50% install-to-registration rate, with future growth increasingly concentrated in Tier 2 and Tier 3 cities.
- High engagement levels are evidenced by 80% of mobile gamers consuming gaming video content and 44% participating in esports.
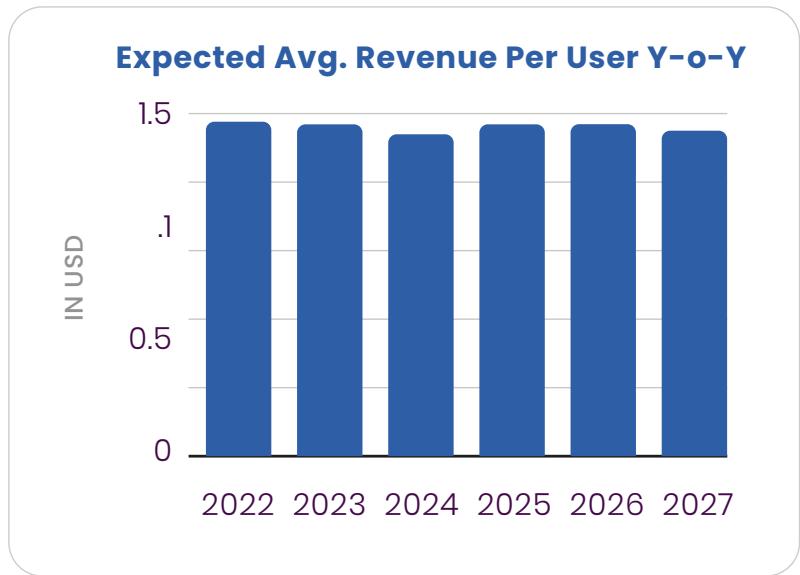
This bar chart from a game industry report displays the expected average revenue per user (ARPU) year-over-year from 2022 to 2027, showing values consistently around 1.4-1.5 USD.