Report11 pages
Crypto on Live Streaming Mini‑Report
This analysis examines the intersection of cryptocurrency and live streaming, tracking the rapid growth of digital asset content across Twitch, YouTube, and Kick. The primary thesis identifies a significant surge in crypto-related broadcasting driven by market speculation, memecoin popularity, and political events. The scope covers global data from July 2023 through June 2025, utilizing a methodology that tracks unique channels with at least 30 hours of monthly airtime while excluding bots and suspicious accounts to ensure data integrity.
Findings reveal that the number of unique channels streaming crypto content doubled in the six months leading into late 2024. YouTube experienced the most dramatic growth, rising from 31 channels in July 2024 to over 200 by June 2025. Viewership peaked across platforms in early 2025, with Twitch reaching its height in February and YouTube seeing major spikes in January and June. While Bitcoin remains the most discussed asset with over 500,000 chat mentions in the first half of 2025, Solana has emerged as a dominant secondary interest, recording 171,000 mentions—triple that of Cardano.
The geographic reach of this content is notably diverse, with India emerging as a major hub; four of the top ten crypto creators are based there and stream primarily on YouTube. K1m6a is identified as the leading creator with 6.7 million hours watched. Beyond dedicated finance streams, crypto discourse has permeated gaming communities. Just Chatting is the top category for crypto mentions, but Escape from Tarkov and Fortnite lead among gaming titles. Furthermore, crypto integration is deepening in professional gaming, evidenced by high-viewership esports events like the 2025 Mid-Season Invitational, which secured major crypto-related sponsorships.
- The number of unique crypto-focused streaming channels doubled in the six months leading to late 2024, with YouTube channels surging from 31 in July 2024 to over 200 by June 2025.
- India has become a primary hub for crypto content, hosting four of the top ten global creators who stream primarily on YouTube.
- Bitcoin remains the most discussed asset with over 500,000 chat mentions in the first half of 2025, while Solana has emerged as the dominant secondary interest with 171,000 mentions.
- Creator K1m6a leads the sector with 6.7 million hours watched, highlighting the significant audience reach of top-tier crypto broadcasters.
- Crypto discourse has expanded beyond finance into gaming, with 'Just Chatting' as the top category and 'Escape from Tarkov' and 'Fortnite' leading among gaming titles.
+3
Stream HatchetNov 2024
Report21 pages
Game Developer Collective Survey Results: November 2024
The November 2024 Game Developer Collective Survey examines how game developers allocate resources to software tools and services, focusing on the adoption of game engines, cloud platforms, and ancillary technologies. The central thesis is that while the market now offers a broader array of solutions than ever before, studios face divergent realities: many are eager to leverage these options to boost efficiency and output, yet a substantial portion confronts tightening budgets that limit further investment. This tension is reflected in the “Industry Conditions and Performance” findings, which portray a challenging commercial environment for the sector.
Key observations indicate that developers increasingly view diversified toolsets as pathways to improved productivity, but cost pressures are intensifying across regions. The survey highlights a split between studios that can expand their technology stack and those that must defer additional spending, underscoring a growing disparity in capability to innovate. The analysis also signals that forthcoming research on “Working Environments,” slated for release in January 2025, will delve deeper into how these financial constraints intersect with workplace dynamics and talent management.
The study spans a global developer base, encompassing respondents from the Americas, Europe‑Middle East‑Africa, and Asia‑Pacific, and captures sentiment as of November 2024. Although specific sample sizes and data sources are not disclosed in the excerpt, the findings are presented under the Omdia research umbrella, with standard disclaimer language indicating that the material is provided “as‑is” and reflects the original publication date. The survey’s conclusions serve as a barometer of current investment trends and the fiscal pressures shaping the game development landscape.
- As of November 2024, the game development sector is defined by a growing disparity between studios capable of expanding their technology stacks and those forced to defer spending due to tightening budgets.
- Developers increasingly view the adoption of diversified software tools, cloud platforms, and ancillary technologies as the primary pathway to improving productivity and output.
- Intensifying cost pressures across global regions are creating a challenging commercial environment that limits the ability of many studios to invest in new innovation.
- The current market offers a broader array of software solutions than ever before, yet these options are being met with fiscal constraints that restrict widespread adoption.
- Future industry analysis, scheduled for release in January 2025, will examine how these ongoing financial constraints specifically impact workplace dynamics and talent management.
+1
Game Developer CollectiveNov 2024
Report15 pages
Levelling Up: State of India Interactive Media & Gaming Research FY'24
The Indian interactive media and gaming market reached a valuation of $3.8 billion in FY24, representing a significant 30% share of the country’s broader $12.5 billion new media sector. Growth is characterized by a 20% five-year projected CAGR, with expectations to exceed $9.2 billion by FY29. This expansion is primarily driven by a 41% year-on-year increase in in-app purchase revenue, particularly within the midcore segment, which grew by 53%. While Real Money Gaming (RMG) remains a major contributor, recent changes to the GST regime have led to margin compression and increased user acquisition costs for operators in that sub-sector.
The player base in India has expanded to 590 million gamers, with 148 million identified as paying users. Engagement metrics show a 30% increase in average weekly time spent, rising from 10 to 13 hours. Demographic data reveals a diversifying landscape where 44% of gamers are women and 66% reside in non-metro cities. Notably, there is a high degree of overlap between gaming categories, as over 60% of RMG paying users also spend money on midcore titles. Payment behaviors are heavily modernized, with 83% of users utilizing UPI or digital wallets for transactions.
The regulatory environment is shifting toward formal recognition and support, with the government identifying gaming as a "sunrise sector." New frameworks distinguish between RMG and Free-to-Play (F2P) games for taxation purposes, while esports has been officially integrated under the Ministry of Youth Affairs and Sports. These findings are based on a mixed-methods research design conducted between May and October 2024, incorporating a primary survey of 2,269 smartphone users across 16 Indian cities alongside secondary analysis of financial statements and proprietary industry data.
- The Indian interactive media and gaming market reached a $3.8 billion valuation in FY24 and is projected to grow at a 20% CAGR to exceed $9.2 billion by FY29.
- In-app purchase revenue grew 41% year-on-year, with the midcore segment serving as a primary growth driver after experiencing a 53% increase.
- India’s gaming population has reached 590 million, including 148 million paying users who now spend an average of 13 hours per week gaming, a 30% increase from previous metrics.
- The player demographic is increasingly diverse, with 44% of gamers being women and 66% residing in non-metro cities.
- Real Money Gaming (RMG) faces margin compression and rising user acquisition costs due to recent GST regime changes, though 60% of RMG payers also spend money on midcore titles.
+1
LumikaiNov 2024
Report21 pages
Tools & Services Survey: November 2024
This analysis examines the evolving landscape of game development tools and services amidst a period of significant market volatility. Based on a November 2024 survey of the Game Developer Collective, the findings track shifts in engine preference, cloud infrastructure, and overall industry sentiment. The survey includes a global sample of developers, with 48% based in North America and 39% in Europe, primarily representing roles in programming, management, and game design.
A primary focus is the game engine market, which continues to react to Unity’s 2023 "runtime fee" controversy. Despite Unity eventually scrapping the fee, the company has steadily lost market share to Unreal Engine. While the percentage of Unity users planning to switch engines dropped from a peak of 70% in late 2023 to 36% in late 2024, this remains significantly higher than the 14% switch rate seen among users of competing engines. Sentiment toward Unity has moderated, but only 30% of developers report being happy with the company, suggesting a lasting impact on brand trust.
The broader industry environment is characterized by increasing financial pressure and underperformance. Approximately 55% of developers now describe market conditions as "bad," a notable increase from 47% six months prior. Business performance has also declined, with 41% of studios reporting they are underperforming against expectations. Consequently, while investment in tools remains steady for most, there is a growing emphasis on productivity and efficiency as the primary drivers for new purchases. AI-powered tools are a rare area of growth, with studios more likely to increase spending in this category compared to traditional services.
In specialized segments, Blender has emerged as the leading 3D modeling tool, used by 50% of studios. Cloud platform usage is at an all-time high, led by AWS and non-hyperscaler options, though these services remain highly "sticky" with low intent to switch providers. Conversely, specialist backend platforms struggle with low penetration, as only 38% of studios currently utilize these centralized solutions. Overall, the findings depict a cautious industry prioritizing efficiency and stability while navigating a difficult commercial climate.
- Market sentiment is increasingly negative, with 55% of developers describing current conditions as 'bad' and 41% of studios reporting underperformance against expectations.
- Unity continues to lose market share following its 2023 runtime fee controversy, with 36% of its users still planning to switch engines compared to only 14% for competitors.
- Brand trust in Unity remains damaged, as only 30% of developers report being happy with the company despite the reversal of its controversial fee policy.
- Studios are prioritizing efficiency and productivity in their purchasing decisions, with AI-powered tools being the only category seeing increased spending compared to traditional services.
- Blender has become the dominant 3D modeling tool, currently utilized by 50% of surveyed studios.
+1
Game Developer CollectiveNov 2024
Report68 pages
Game Development and the Green Transition: Code, Climate, Creativity
Executive Summary – “Code, Climate, Creativity: Game Development and the Green Transition”
1. Rapid Industry Growth, Low Relative Carbon Footprint Turnover: €427 M (2012) → €3.1 B (2023) – a ≈ 900 % increase. Employment: > 9 000 people across 1 000+ firms; 87 % are micro‑enterprises (≤10 staff). Carbon Profile: Despite the boom, the Swedish games sector’s emissions remain modest compared with other Swedish industries. Electricity & travel: only a slight rise. Scope 3 (down‑stream) emissions dominate, mainly from the energy used while players are gaming.
Key Insight: The sector’s carbon intensity is low, but the sheer scale of downstream use means total emissions can still be significant.
2. A Dense, Emerging Climate‑Action Network Handbooks & Alliances: Nordic PlayCreateGreen guide, UN‑backed Playing for the Planet Alliance, European Sustainable Games Alliance. Industry Footprint: Global gaming ≈ 14 Mt CO₂e (≈ Sweden’s total industrial emissions). Swedish Share: 2.3 kt CO₂e (2022) – 0.015 % of national industry output. Emission Distribution: 90‑99 % of Swedish games‑sector emissions are Scope 3.
Take‑away: A well‑connected ecosystem of NGOs, academia, and industry is already mobilising around measurement, best‑practice sharing, and player engagement.
3. Scope 3 Dominance & Regulatory Pressure Average Intensity: ≈ 99 t CO₂e per MEUR of turnover → ≈ 302 kt CO₂e total for Swedish firms. Potential Reduction: Up to 90 % cut if all players switch to fossil‑free electricity. Policy Landscape: Science‑Based Targets initiative (SBTi): Requires Scope 3 reduction targets for developers. EU Corporate Sustainability Reporting Directive (CSRD): Will soon mandate detailed Scope 1‑3 disclosures.
Implication: Companies must embed Scope 3 accounting into strategy now, not later.
4. Where Scope 3 Emissions Come From Primary Sources: Production & use of consoles and PCs. Emerging Mitigation: Cloud‑gaming and thin‑client streaming can lower the energy needed for high‑performance gaming, but the net impact depends on data‑center efficiency and network load.
5. Sweden’s R&D Strength – A Launchpad for Green Tech Opportunities: Strong certification schemes and a culture of open innovation. Existing digital‑tool stack (game engines, GPUs, XR platforms,
- The Swedish games industry grew nearly 900% in turnover between 2012 and 2023, reaching €3.1 billion while maintaining a relatively low carbon footprint compared to other industrial sectors.
- Scope 3 emissions—primarily generated by energy consumption during player use—account for 90–99% of the Swedish games sector's total carbon footprint.
- Global gaming emissions are estimated at 14 Mt CO₂e annually, roughly equivalent to the total industrial emissions of Sweden.
- Regulatory pressure is mounting, as the EU Corporate Sustainability Reporting Directive (CSRD) and Science-Based Targets initiative (SBTi) will soon mandate detailed Scope 1–3 disclosures and reduction targets for developers.
- Transitioning players to fossil-free electricity could reduce the sector's total carbon impact by up to 90%.
+1
Swedish Games IndustryOct 2024
Report24 pages
Insights into Marketing Trends in Southeast Asian Mobile Games in 2024
The Southeast Asian mobile gaming market in 2024 is characterized by high advertiser activity and a strategic shift toward video-centric marketing. Data collected between January and August 2024 reveals a monthly average of over 20,000 active advertisers in the region, representing a 9.5% year-over-year increase. While the proportion of new advertisers remained stable at approximately 3.7%, a significant surge occurred in June, where new game advertisers reached 8.5% of the total market.
Geographically, Indonesia leads the region in the volume of monthly advertisers with 12.3K, surpassing major markets like Japan and South Korea. However, Thailand remains the most intensive in terms of content volume, serving as the only country in the region to exceed 100 monthly creatives per advertiser. From a platform perspective, Android dominates the landscape, accounting for over 70% of advertisers in markets like Indonesia, though iOS users see a higher proportion of image-based creatives.
Genre analysis indicates that while casual games maintain the largest share of advertisers at 28.4%, Role-Playing Games (RPGs) are the most aggressive marketers. RPGs account for 16% of total creatives, a figure significantly higher than the global average. Strategy games (SLGs) lead in format innovation, with 76.5% of their ads utilizing video. Across all genres, video is the dominant medium, making up nearly 70% of all creatives, with a growing trend toward using local influencers, live-action footage, and "mini-game" playables to drive engagement.
The findings are based on sampling from SocialPeta’s database of 1.6 billion ad creatives across 70 global channels. The methodology combines statistical forecasting with desk research to track advertising intelligence across Indonesia, Thailand, Singapore, Malaysia, Vietnam, the Philippines, and Cambodia. Findings suggest that successful regional campaigns increasingly rely on localized content, such as Thai celebrity endorsements and TikTok-inspired audio synchronization, to navigate the fierce competition in the Southeast Asian media-buying landscape.
- Video-centric marketing is the dominant strategy in Southeast Asia, accounting for nearly 70% of all ad creatives across all mobile game genres.
- Indonesia is the region's largest market by advertiser volume with 12.3K monthly advertisers, while Thailand leads in content intensity with over 100 creatives per advertiser.
- The Southeast Asian mobile gaming market saw a 9.5% year-over-year increase in active advertisers, averaging over 20,000 per month between January and August 2024.
- Casual games hold the largest market share at 28.4% of advertisers, but RPGs are the most aggressive marketers, contributing 16% of total creatives.
- Strategy games (SLGs) are the leaders in format innovation, with 76.5% of their advertisements utilizing video.
+1
SocialPetaOct 2024
Report36 pages
Gaming Industry Report: Q3 2024
• 2024 market size: $188bn (+2.1% YoY) Total gamers in 2024 by region (millions): • Public markets: leading public gaming ETFs up 22- • 36% YTD (vs S&P 500 = 21%) Middle East & Africa Venture funding in Q3‘ 24: $517m across 92 deals 559 (funding +1% QoQ, number of deals -14% QoQ) (16%) • Epic sidesteps Apple in the EU, sues Google Europe (454 3,422m • Discord launches Activities ...
- The gaming market size in 2024 is $188 billion, showing a 2.1% year-over-year growth. Asia-Pacific accounts for the largest share of gamers with 1,809 million (53%), followed by Europe with 454 million (13%).
- Venture funding in Q3 2024 reached $517 million across 92 deals, marking a 1% increase in funding quarter-over-quarter but a 14% decrease in the number of deals. Total private market funding for 2024 is $3,739 million, with a 15% QoQ increase in Q3.
- Public market gaming ETFs are significantly outperforming the S&P 500, with leading ETFs up 22-36% year-to-date compared to the S&P 500's 21%.
- Unity has fully removed its Runtime Fee, reverting to a seat-based subscription model with increased revenue and funding ceilings for Unity Personal (up to $200k) and price increases for Unity Pro (+8%) and Unity Enterprise (+25%).
- Epic Games is actively challenging platform policies, launching its own iOS app store in the EU with a maximum 12% commission and suing Google and Samsung over anti-competitive practices related to app distribution on Android.
+5
KonvoyOct 2024
Report23 pages
UKIE Annual Review 2024
Ukie’s 2024 annual review presents a comprehensive account of the UK video‑games sector’s performance, strategic direction and advocacy work over the past twelve months. The central thesis is that the industry, now a £6 billion economic engine supporting 76 000 jobs, must be “supercharged” through coordinated efforts to energise businesses, empower talent and elevate games as cultural and educational assets. The review outlines the new five‑year “Supercharged” strategy, which frames Ukie’s campaigning and support programmes for the next decade.
Key findings highlight robust economic contributions: consumer spending on games rose 4 % to £7.82 billion, while a joint analysis with FTI Consulting estimated video‑game technology spill‑overs added up to £760 million to UK GDP and created nearly 10 000 jobs in 2021. International trade activities at Gamescom and GDC generated over £70 million in business wins and attracted more than £150 million of foreign direct investment for 180 UK companies. Policy influence is demonstrated by over 100 engagements with MPs, successful submissions to Ofcom on online safety, and a manifesto that secured inclusion of the sector in major party election platforms. Education initiatives reached 299 470 learners through the Digital Schoolhouse programme, and IP protection actions removed 1.5 million infringing links and prevented £100 million of illicit digital sales.
The review’s scope covers the UK video‑games ecosystem from indie studios to multinational publishers, spanning 2023‑24 and encompassing economic, cultural and regulatory dimensions. Methodologically, the analysis combines internal data on events, memberships and media coverage with external research collaborations, consultation responses and round‑table workshops to produce evidence‑based recommendations. The narrative underscores a commitment to diversity, with a newly approved five‑year EDI strategy and over 20 inclusion‑focused events, positioning the sector for sustained growth and global competitiveness.
- The UK video games sector is a £6 billion economic engine supporting 76,000 jobs, with consumer spending rising 4% to £7.82 billion in the 2023-24 period.
- Video game technology spill-overs contributed £760 million to UK GDP and created nearly 10,000 jobs as of 2021.
- International trade activities at events like Gamescom and GDC generated over £70 million in business wins and attracted more than £150 million in foreign direct investment for 180 UK companies.
- Ukie’s IP protection efforts successfully removed 1.5 million infringing links, preventing an estimated £100 million in illicit digital sales.
- The Digital Schoolhouse education programme reached 299,470 learners, supporting the industry's focus on talent development.
UkieOct 2024
Report13 pages
Game Development Studie 2024: Die wirtschaftliche Bedeutung der österreichischen Spieleentwicklungsbranche, ihre Dynamiken und Einflüsse auf die Gesamtwirtschaft
The study evaluates the state of Austria’s game‑development sector in the first half of 2024, tracing its evolution since a comparable survey in 2018 and quantifying its economic contribution. By updating the Institute of Industrial Research’s developer database to 149 active firms and collecting completed questionnaires from 80 companies (a 53.7 % response rate), the analysis combines firm‑level survey data with input‑output modelling to assess employment, turnover and multiplier effects.
The industry has expanded rapidly: the number of firms rose 71.3 % to 149, with 81 % classified as micro‑enterprises (≤9 employees) and 54 % located in Vienna. Turnover reached €92.8 million in 2023—a nominal increase of 285 % since 2017—and employment grew from 474 jobs in 2017 to 1 080 in 2024 (128 % rise). Direct, indirect and induced effects generate a total of €188.7 million in revenue and support roughly 2 260 jobs across the Austrian economy, a multiplier of about 2.0 for both revenue and employment.
Product portfolios remain dominated by entertainment titles (85 % of respondents), while serious and educational games have gained prominence (29 % and 30 %). Development focuses on PC and mobile platforms, with Unity used by 55 % of firms. The workforce is young and highly educated—nearly half are aged 25‑34 and 80 % hold tertiary degrees. Export orientation is strong, 82 % of firms sell to the EU‑27/UK and substantial shares reach the Americas and Asia. Financing relies chiefly on internal funds (92 % deem it very important); public subsidies rank second (62 %). One‑third of firms applied for public funding in the past two years, achieving a 65 % success rate.
Looking ahead, respondents anticipate a slowdown in growth; projections suggest 2029 revenues of €149 million and employment of about 1 540, still representing robust expansion. Nevertheless, the sector rates Austria’s location policy poorly, calling for stronger governmental support, clearer financing mechanisms and improved tax conditions
- Austria’s game development sector has experienced rapid growth since 2017, with turnover increasing 285% to €92.8 million in 2023 and employment rising 128% to 1,080 jobs by 2024.
- The industry generates a total economic impact of €188.7 million in revenue and supports approximately 2,260 jobs across the Austrian economy, reflecting a multiplier effect of 2.0.
- The sector consists of 149 active firms, 81% of which are micro-enterprises with nine or fewer employees, and 54% are concentrated in Vienna.
- Development is highly export-oriented, with 82% of firms selling to the EU-27 and UK markets, while financing remains heavily reliant on internal funds (92%) rather than external investment.
- While the workforce is highly educated—with 80% holding tertiary degrees—the industry anticipates a growth slowdown, projecting revenues of €149 million and 1,540 jobs by 2029.
+1
PGDA – Pioneers of Game Development AustriaOct 2024
Report20 pages
Live Streaming Trend Report: Q3 2024
The analysis of live‑streaming activity in the third quarter of 2024 demonstrates a robust rebound in overall viewership, with total hours watched rising 12 percent year‑over‑year to reach 8.5 billion. Growth is concentrated on emerging services, most notably Kick, which expanded its audience by 103 percent, delivering 534 million hours of content and securing a 6.3 percent share of the market. Its peak week recorded 45 million hours watched, positioning Kick as the third‑largest platform despite Twitch’s modest 4 percent decline in the same period. The surge extends to Spanish‑language streams on Kick, where viewership accelerated sharply, underscoring the platform’s expanding appeal in non‑English markets.
Subscriber dynamics also reached new heights. VTuber ironmouse achieved an all‑time high of roughly 320 thousand followers on Twitch during the “SUBtember” marathon, while FaZe Clan’s 30‑day joint subathon generated 99.5 thousand and 73.7 thousand new subscribers for members jasontheween and plaqueboymax respectively. These figures illustrate a growing willingness among audiences to convert viewership into direct financial support for creators.
Esports viewership contributed a historic peak, with the LCK Grand Final between T1 and GEN drawing an estimated two million concurrent viewers, reinforcing the continued draw of high‑stakes competitive events. Collectively, the data reveal a diversifying ecosystem in which emerging platforms and regional language streams are reshaping audience distribution, while monetization through subscriptions and esports remains a powerful driver of engagement across the global live‑streaming landscape.
- Total live-streaming viewership reached 8.5 billion hours in Q3 2024, marking a 12 percent year-over-year increase.
- Kick emerged as the third-largest streaming platform with 534 million hours watched, representing a 103 percent growth rate and a 6.3 percent market share.
- Twitch experienced a 4 percent decline in viewership during Q3 2024, even as it hosted record-breaking subscriber events like ironmouse’s 320,000-follower marathon.
- Esports remains a primary engagement driver, evidenced by the LCK Grand Final between T1 and GEN drawing a peak of two million concurrent viewers.
- The live-streaming ecosystem is diversifying through the rapid expansion of non-English markets, particularly Spanish-language streams on the Kick platform.
+1
Stream HatchetSept 2024
Report22 pages
Global Indie Games Market Report 2024
The 2024 Global Indie Games Market Report by Video Game Insights analyzes the significant growth and evolving structure of the independent gaming sector on Steam from 2018 through September 2024. The central thesis posits that indie games have reached a historical milestone, with their revenue share doubling since 2018 to match the combined earnings of AA and AAA titles for the first time. This surge is largely attributed to the rise of "Triple I" games—high-budget independent projects with teams of over 50 people—which now account for more than half of all indie revenue.
Key findings highlight that 2024 was a record-breaking year driven by exceptional hits like Black Myth: Wukong and Palworld, which sold 20.6 million and 20.1 million units respectively. The data reveals an increasing concentration of wealth at the top of the market; excluding these two titles, all other 2024 indie releases combined generated less revenue than Black Myth: Wukong alone. Furthermore, the report identifies a trend toward studio maturity, noting that second and third releases typically outperform debut titles. Successful developers like Pocketpair and Sunlock Studios achieved massive hits only after releasing multiple previous games.
The scope of the analysis focuses on the Steam platform, segmenting the market into four categories: Triple I, Middle Market, Small Teams, and Hobbyists. While all segments saw a "boom" during the COVID-19 pandemic, the larger Triple I and Middle Market tiers have seen the most substantial long-term growth. Methodology involves proprietary algorithms and the Boxleiter method to estimate unit sales and gross revenue from public Steam data, adjusted for regional pricing and returns. The findings suggest that the traditional definition of "indie" is blurring as production qualities and budgets of top-tier independent games now rival those of major AAA studios.
- Indie games have reached a historical milestone, doubling their revenue share since 2018 to match the combined earnings of AA and AAA titles on Steam.
- High-budget 'Triple I' projects, defined as teams of over 50 people, now generate more than half of all indie market revenue.
- Market wealth is increasingly concentrated at the top, as 2024 hits Black Myth: Wukong and Palworld sold 20.6 million and 20.1 million units respectively.
- Excluding the two top-selling titles, all other indie games released in 2024 combined generated less revenue than Black Myth: Wukong alone.
- Studio maturity is a key success factor, as second and third releases from developers like Pocketpair and Sunlock Studios consistently outperform debut titles.
Video Game InsightsSept 2024
Report23 pages
U.S. Gamer Segmentation 2024 Edition
This analysis of the 2024 U.S. video gaming market identifies a resilient landscape where 71% of the population, or approximately 236.4 million people, engage with games. While this reflects a slight decline from the 74% peak seen in 2020, it remains significantly higher than the 67% recorded in 2018. The study utilizes a survey of 5,100 active gamers aged two and older, conducted between May and June 2024, to categorize the audience into six distinct behavioral segments: Super Gamers, Console Warriors, Transitionals, Easy Accessors, Daily Dabblers, and Incidental Players.
A primary finding is that while the total player count has dipped slightly, engagement and monetization are increasing. Gamers now spend an average of 14.5 hours per week playing, an increase of 1.8 hours since 2022. Spending has also risen to an average of $56.20 over a six-month period. Mobile remains the most pervasive platform, used by 65% of the total population, while console gaming has seen the most significant growth in weekly time investment. Conversely, PC gaming saw a 4% decline in reach since 2022.
The market is shifting toward more dedicated segments. There has been a notable decrease in casual "Incidental Players" and "Daily Dabblers," with a corresponding migration toward "Super Gamers" and "Transitionals." Super Gamers represent the most valuable demographic, typically consisting of males aged 18 to 34 who play across multiple platforms and engage deeply with gaming culture, including streaming and esports. Although teens and young adults remain the most valuable segments in terms of time and spend, the report notes that player investment is rising across nearly all age groups despite the overall contraction in the total number of gamers.
- The U.S. gaming population stands at 236.4 million people, representing 71% of the population, which is a slight decline from the 2020 peak of 74% but remains above 2018 levels.
- Average weekly engagement has increased to 14.5 hours, up 1.8 hours since 2022, while average spending over a six-month period has risen to $56.20.
- The market is shifting toward more dedicated segments, with a migration away from casual 'Incidental Players' and 'Daily Dabblers' toward 'Super Gamers' and 'Transitionals'.
- Mobile remains the dominant platform with 65% reach, while console gaming has experienced the most significant growth in weekly time investment.
- PC gaming reach has declined by 4% since 2022.
+1
CircanaAug 2024
Report20 pages
Live Streaming Trends Report: Q2 2024
The global live streaming industry experienced a significant resurgence in the second quarter of 2024, with total viewership reaching 8.5 billion hours. This 10% year-over-year increase represents the first substantial growth period since the pandemic-era peak. While Twitch maintains its position as the primary market leader, its dominance has softened from 70% to 60% of total hours watched. This shift reflects a diversifying landscape where YouTube Gaming and Kick have captured 23.4% and 5.5% of the market, respectively, and Rumble has established itself as a top-ten platform by leveraging political content and debate-related viewership.
Content trends during this period were heavily influenced by major software releases and political events. The launch of downloadable content for Elden Ring triggered a 331% surge in viewership for the title, driving a 30% increase in the broader Action genre. Conversely, traditional pillars such as First-Person Shooters and MOBAs saw slight declines in market share. The VTuber segment remains a high-growth area, particularly within the Grand Theft Auto V category, where individual creators saw viewership spikes exceeding 300%. Esports also reached new heights, evidenced by the LCK Grand Final achieving a record 2.7 million concurrent viewers.
A critical structural shift is occurring in creator demographics, characterized by the decentralization of viewership. The market share held by the top 5% of streamers fell to 86% from a 2019 high of 98%, while the share held by the top 0.01% of channels dropped from 45% to 33%. This trend suggests a maturing ecosystem where visibility is increasingly distributed among a broader range of mid-tier creators rather than being concentrated exclusively at the top. These findings indicate a healthy, diversifying industry that is successfully transitioning from pandemic-driven volatility to sustainable, multi-platform growth.
- The live streaming industry saw a 10% year-over-year growth in Q2 2024, reaching 8.5 billion total hours watched.
- Twitch's market share dropped from 70% to 60%, while YouTube Gaming and Kick captured 23.4% and 5.5% of the market, respectively.
- Viewership is decentralizing, with the top 5% of streamers now holding 86% of the market share, down from 98% in 2019.
- The top 0.01% of channels saw their market share decline from 45% to 33%, indicating a shift toward mid-tier creator visibility.
- Major software releases significantly impact genre performance, evidenced by Elden Ring's DLC launch driving a 331% surge in its viewership and a 30% increase in the broader Action genre.
+1
Stream HatchetJul 2024
Report1 pages
Project & Studio Financing Snapshot July 2024
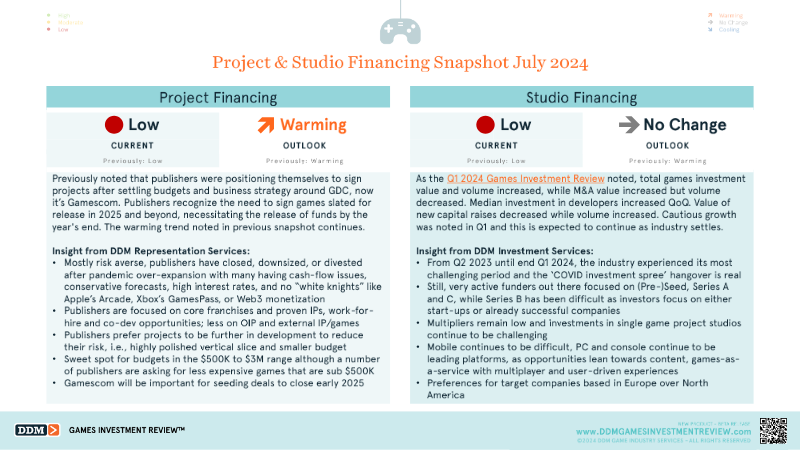
The snapshot evaluates financing conditions for game projects and development studios as of mid‑2024, highlighting a persistently constrained capital environment while noting modest signs of warming in project funding. Publishers remain risk‑averse after pandemic‑driven over‑expansion, with many having reduced staff, divested assets, and facing cash‑flow pressures compounded by high interest rates and the absence of large platform backers. Consequently, they prioritize core franchises, proven IP and work‑for‑hire arrangements, demanding projects that are further along in development, feature polished vertical slices, and fall within a budget sweet spot of roughly $500 k to $3 million, though an emerging demand for sub‑$500 k titles is evident. The upcoming Gamescom event is expected to catalyze deal flow for releases slated for 2025 and beyond.
Studio financing remains low with no change in outlook, reflecting cautious growth after a volatile Q1 2024 period in which total investment value and volume rose, M&A value increased while deal count fell, and median developer investment grew quarter‑over‑quarter. New capital raises saw a decline in total value but an increase in deal count, underscoring a shift toward smaller, more frequent funding rounds. Investors continue to focus on early‑stage (pre‑seed, Series A) and later‑stage (Series C) opportunities, while Series B financing proves scarce as capital gravitates toward either nascent start‑ups or already successful entities.
Geographically, funders exhibit a preference for European‑based studios over North American counterparts, and platform trends show mobile projects facing heightened difficulty, whereas PC and console titles dominate, especially those built around games‑as‑a‑service, multiplayer, and user‑generated content models. Overall, the financing landscape is characterized by conservative publisher behavior, modest but steady studio investment, and a strategic emphasis on later‑stage, lower‑risk projects as the industry settles post‑pandemic.
- Publishers are prioritizing low-risk projects with budgets between $500k and $3 million, though there is an emerging demand for titles under $500k.
- Investment is heavily skewed toward early-stage (pre-seed/Series A) and late-stage (Series C) rounds, leaving Series B financing scarce.
- Funding trends show a shift toward smaller, more frequent capital raises, evidenced by a decline in total new capital value despite an increase in deal count.
- PC and console titles—specifically those featuring games-as-a-service, multiplayer, or user-generated content—are currently prioritized over mobile projects.
- Investors are showing a geographic preference for European-based studios over North American counterparts.
+1
DDMJul 2024
Report145 pages
State of Web3 in Saudi Arabia
Saudi Arabia has emerged as the dominant hub for Web3 investment in the Middle East and North Africa, capturing 51 % of Q1 2024 venture‑capital funding with $429 million across 163 deals. This concentration reflects a supportive ecosystem that blends proactive government initiatives, a growing pool of local founders, and active participation from international investors. The market is presently skewed toward consumer‑facing applications such as DeFi, GameFi and SocialFi, while foundational protocol development remains limited, highlighting a clear opening for infrastructure builders.
Founders of Saudi‑based Web3 ventures underscore the rapid maturation of the sector, citing high‑profile partnerships—including Animoca Brands with NEOM, collaborations with Hedera, and alignment with Vision 2030—as catalysts for growth. Yet they identify three persistent barriers: inadequate user‑friendly interfaces, insufficient public and investor education, and ambiguous regulatory frameworks that impede both builder activity and funding cycles. Sector‑specific use cases—blockchain‑enabled freelance payments, Sharia‑compliant insurance, and localized NFT platforms—are viewed as primary drivers of mass adoption.
Government commitment reinforces this trajectory, with $37.7 billion earmarked for esports and $13.3 billion for gaming, complemented by sizable venture funds such as Wa’ed’s $500 million vehicle and 500 Global’s $2.4 billion under management. Notable projects illustrate tangible impact: Tharawat Green Exchange aims to plant ten million trees by 2030, while Ticket Souq has generated $3.3 million in gross merchandise value, serving 36 k users across 55 events in ten countries. Stakeholders agree that clear, supportive regulation, robust education, and targeted technology investment are essential to translate this momentum into sustainable, high‑pay‑off outcomes for the kingdom’s burgeoning gaming, fintech, e‑commerce and proptech sectors.
- Saudi Arabia captured 51% of all MENA Web3 venture capital funding in Q1 2024, totaling $429 million across 163 deals.
- The government has committed $37.7 billion to esports and $13.3 billion to gaming, supported by major investment vehicles like Wa’ed’s $500 million fund and 500 Global’s $2.4 billion under management.
- While the market is currently concentrated in consumer-facing sectors like DeFi, GameFi, and SocialFi, there is a significant supply gap for foundational infrastructure development.
- Founders identify three primary barriers to growth: a lack of user-friendly interfaces, insufficient public and investor education, and regulatory ambiguity.
- High-profile partnerships, such as Animoca Brands with NEOM and collaborations with Hedera, are serving as key catalysts for sector maturation under the Vision 2030 framework.
+2
AdaverseJul 2024
Report30 pages
Global Gamer Study 2024: How Consumers Engage with Games Today
This analysis examines global consumer engagement with video games, drawing on data from over 73,000 surveyed individuals across 36 markets. The findings reveal that gaming has become a dominant pillar of modern entertainment, with 80% of the total online population playing games and 85% engaging with the medium through playing, viewing content, or participating in social communities. Engagement is highest among younger demographics; over 90% of Gen Alpha and Gen Z consumers are game enthusiasts, with Gen Alpha notably spending more time on gaming (5.2 hours per week) than on social media.
The data highlights a significant shift in how different generations and genders interact with the medium. While Adventure is the top genre for Gen Alpha, Gen Z, and Millennials, younger female players are increasingly likely to invest in pay-to-play titles, challenging traditional industry stereotypes. On PC and console platforms, players are motivated primarily by vast open worlds and deep storytelling. These platforms also attract higher-spending audiences compared to mobile; 22% of console players spend more than $25 per month, and over half are classified as medium-to-high spenders.
Despite a market where a small number of established franchises capture the majority of playtime, a vital segment of "new game seekers" remains. Approximately 31% of PC and console players actively hunt for trending titles. This cohort is highly valuable, as 80% of them spend money on games monthly and they are 50% more engaged than the average player. Geographically, this appetite for new experiences is strongest in emerging markets like China, India, and Saudi Arabia, while more mature markets like Japan and Western Europe show more conservative play patterns. The findings suggest that success in a competitive landscape requires moving beyond playable experiences to engage consumers across multiple dimensions, including social media, creator content, and transmedia brands.
- Gaming is a primary entertainment pillar, with 80% of the global online population playing games and 85% engaging through play, viewing, or social communities.
- Gen Alpha and Gen Z are the most active demographics, with over 90% engagement and Gen Alpha spending 5.2 hours per week on gaming, surpassing their time spent on social media.
- A high-value segment of 'new game seekers' makes up 31% of PC and console players; these users are 50% more engaged than average players and 80% of them spend money on games monthly.
- PC and console platforms command higher spending than mobile, with 22% of console players spending over $25 per month and more than half classified as medium-to-high spenders.
- Emerging markets including China, India, and Saudi Arabia show the strongest appetite for new titles, contrasting with more conservative play patterns in Japan and Western Europe.
+1
NewzooJul 2024
Report15 pages
Mobile Games Annual Investment Report
The mobile gaming investment landscape in 2023 was characterized by a strong concentration of capital within early-stage ventures, with a significant emphasis on blockchain integration and infrastructure. Venture capital activity was led by prominent firms such as Andreessen Horowitz, which deployed 63 million dollars across eight investments, including a notable 33 million dollar seed round for Proof of Play. This trend highlights a strategic pivot toward developers who combine traditional mobile gameplay with decentralized technologies and infrastructure solutions.
Investment patterns reveal a diverse range of sub-sectors receiving capital, including social gaming, AI-driven development, and fantasy sports. For instance, Lumikai focused heavily on the Indian market and social platforms, leading a 22 million dollar round for Eloelo. Meanwhile, firms like BITKRAFT Ventures and Animoca Brands continued to bridge the gap between mobile and web3, funding projects like Redemption Games and Upland. While early-stage seed and Series A rounds dominated the volume of transactions, late-stage funding remained selective, as evidenced by Animoca Brands’ 11.9 million dollar raise.
Geographically and operationally, the sector shows a global distribution of capital, targeting both established publishers and niche studios. Total round values for top investors ranged from approximately 15 million to over 60 million dollars, signaling a cautious but steady flow of capital into the mobile ecosystem. The data suggests that while the broader gaming market faced economic headwinds, investors remained committed to high-growth areas such as blockchain-enabled rewards platforms, mid-core mobile development, and innovative monetization models through digital ownership.
- Venture capital in 2023 prioritized early-stage mobile gaming ventures, specifically those integrating blockchain technology and decentralized infrastructure.
- Andreessen Horowitz led investment activity by deploying 63 million dollars across eight deals, including a 33 million dollar seed round for Proof of Play.
- Investment focus remained diverse, spanning social gaming, AI-driven development, and fantasy sports, exemplified by Lumikai’s 22 million dollar investment in Eloelo.
- Firms such as BITKRAFT Ventures and Animoca Brands actively funded projects like Redemption Games and Upland to bridge the gap between traditional mobile gaming and Web3.
- While early-stage seed and Series A rounds dominated transaction volume, late-stage funding remained highly selective, highlighted by Animoca Brands’ 11.9 million dollar raise.
+1
DDMJun 2024
Report20 pages
Stream Hatchet Q2 2024 Report
Live streaming viewership reached 8.5 billion hours watched in the second quarter of 2024, marking a 10% year-over-year increase and a significant resurgence following a post-pandemic decline. While Twitch remains the market leader, its dominance is waning; its market share of hours watched fell from 70% in Q2 2023 to 60% in Q2 2024. This shift is driven by the growth of YouTube Gaming, which rose to a 23% share, and the emergence of alternative platforms like Kick, which now holds 5.5% of the market. Regional and niche platforms such as the South Korean Chzzk and the politically-oriented Rumble also gained traction, with the latter seeing a viewership spike during U.S. presidential debates.
The industry is also witnessing a democratization of viewership. The market share held by the top 5% of creators dropped from 98% in 2019 to 86% in 2024, suggesting a more diverse ecosystem for smaller streamers. In terms of content, Grand Theft Auto V and League of Legends remain the most-watched titles, though the Action genre saw a 30% surge driven by the Elden Ring DLC. Esports viewership remained stable at 654 million hours, with the League of Legends Mid-Season Invitational serving as the quarter's premier event.
This analysis covers global live-streaming trends across major platforms including Twitch, YouTube, Kick, and several emerging services. Data is derived from Stream Hatchet’s business intelligence platform, which aggregates granular viewership metrics such as hours watched and peak concurrent viewers. The findings highlight a transition from traditional FPS and MOBA dominance toward more dynamic RPG and Action titles, alongside a shifting platform landscape where new competitors are successfully challenging established leaders.
- Live streaming viewership reached 8.5 billion hours in Q2 2024, representing a 10% year-over-year increase.
- Twitch's market share of hours watched declined from 70% in Q2 2023 to 60% in Q2 2024.
- YouTube Gaming grew to a 23% market share, while the platform Kick captured 5.5% of the total viewership.
- The top 5% of creators now account for 86% of total viewership, down from 98% in 2019, indicating a more democratized creator ecosystem.
- The Action genre experienced a 30% surge in viewership, largely driven by the release of the Elden Ring DLC.
+1
Stream HatchetJun 2024
Report19 pages
Q2’24 Gaming Deals Report
The second quarter of 2024 marks a period of stabilization for the global gaming industry, signaling an end to the post-pandemic "hangover" phase. Private investments established a new quarterly benchmark of $1 billion across 116 rounds, driven by a steady volume of early-stage venture capital. While late-stage deal-making remains sluggish due to ongoing market headwinds, early-stage activity has normalized around stable Seed rounds and more volatile Series A funding. Corporate venture capital has also shifted toward increased co-investment alongside traditional venture firms.
The mergers and acquisitions segment shows a gradual recovery in deal volume, though the total value of closed transactions remains lower than historical peaks due to a lack of large-scale announcements. Public offerings continue to be the most muted segment, with listing activity remaining low amid macroeconomic instability and turbulence in gaming stocks. Geographically, Asia remains the primary driver for mobile gaming hits, with titles like Dungeon & Fighter: Origin generating significant in-app purchase revenue. On PC and console platforms, Steam full-game sales grew 27% year-over-year, largely supported by a robust catalog of indie and AA titles.
The analysis covers global transactions involving video game publishers, developers, and platform technology providers, excluding pure gambling and non-gaming blockchain entities. Data is sourced from public media, business partners, and market insights, focusing on closed transactions rather than announced deals. The methodology utilizes a weighted average ranking system for venture funds based on both total deal participation and lead investor roles. Overall, the findings suggest the industry is entering a more predictable growth phase characterized by cautious but consistent investment and a diversifying PC/console market.
- Private investment in the gaming industry reached a new quarterly benchmark of $1 billion across 116 rounds in Q2 2024, signaling a stabilization of the market.
- Steam full-game sales grew by 27% year-over-year, driven primarily by a strong performance from indie and AA titles.
- Early-stage venture capital is fueling current market activity, while late-stage deal-making remains sluggish due to persistent economic headwinds.
- Mergers and acquisitions are seeing a gradual recovery in volume, though total transaction values remain below historical peaks due to a lack of large-scale deals.
- Asia continues to lead the mobile gaming sector, with titles such as Dungeon & Fighter: Origin driving significant in-app purchase revenue.
+1
InvestGameJun 2024
Report35 pages
Gaming Spotlight H1 2024
Mobile gaming solidifies its position as the leading segment of the global video‑game market, with revenue projected to reach $83 billion in 2024, reflecting a 6 percent year‑over‑year increase. In contrast, home‑console spending is expected to decline by 1 percent to $42 billion, while handheld revenues are slated to fall 2 percent to just under $2.5 billion. The upward trajectory of mobile is driven primarily by rapid expansion in emerging regions such as India and Indonesia, where user acquisition and spending are accelerating faster than in mature markets. Within mobile, fast‑growing sub‑genres—particularly simulators and multiplayer online battle arenas—accounted for $2.34 billion, representing 5.8 percent of total mobile revenue, and achieved a modest 0.4‑point rise in download share during the latest reporting period.
In the United States, monetisation patterns among mobile players continue to favour rewarded‑video advertisements. These ads recorded the highest net‑sentiment score of +20 points and were the most frequently encountered format in the third quarter of 2023. Other ad formats, including playable, native, banner/display, and standard video, lagged behind both in visibility and user sentiment, indicating a clear preference hierarchy that shapes publisher revenue strategies.
Overall, the data underscore a market increasingly centred on mobile platforms, propelled by growth in developing economies and reinforced by user‑friendly ad experiences. Console and handheld segments face modest contractions, suggesting that future investment and innovation will likely concentrate on mobile‑first titles, emerging‑region outreach, and optimisation of rewarded‑video ad ecosystems to sustain growth.
- Mobile gaming remains the dominant market segment with projected 2024 revenues of $83 billion, representing a 6 percent year-over-year increase.
- Home-console and handheld gaming segments are experiencing a decline, with projected revenues of $42 billion (down 1 percent) and $2.5 billion (down 2 percent) respectively.
- Growth in the mobile sector is primarily driven by rapid user acquisition and spending expansion in emerging markets, specifically India and Indonesia.
- Mobile simulators and multiplayer online battle arenas generated $2.34 billion in revenue, accounting for 5.8 percent of total mobile earnings and a 0.4-point increase in download share.
- Rewarded-video advertisements are the most effective monetization format in the U.S. market, achieving the highest net-sentiment score of +20 points during Q3 2023.
+2
Sensor TowerJun 2024