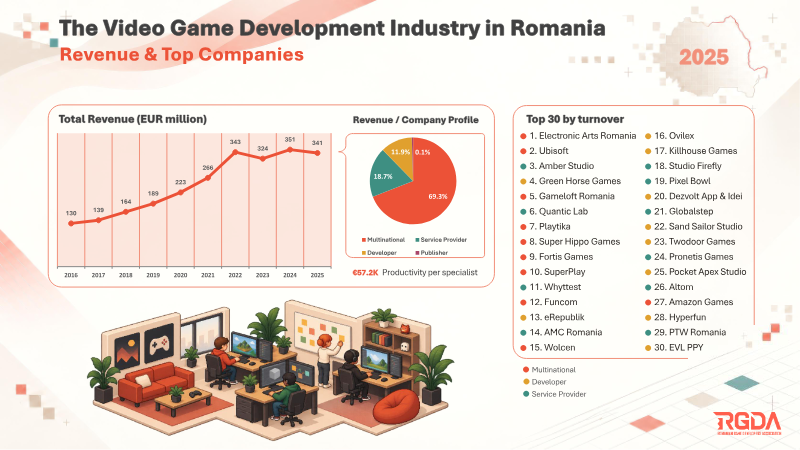
Revenue & Top Companies: Romania 2025
2 pages~1 min full read
Key insights
Distilling the key insights…
Distilling the key insights…
The Romanian video game industry has demonstrated significant resilience and structural evolution, reaching a total revenue of 351 million EUR by 2025. While the sector experienced a post-pandemic contraction that impacted service providers, the market has pivoted toward a surge in creative output. This shift is evidenced by a 2.5-fold increase in game releases over the past two years, signaling a robust expansion within the independent development sector. The industry currently maintains a productivity rate of 57,200 EUR per specialist, supported by a workforce of 6,000 professionals.
Geographically, the industry remains heavily concentrated in major urban hubs, with Bucharest serving as the primary center of operations, hosting 46 percent of all studios. Cluj, Iași, Timiș, and Brașov follow as secondary clusters, collectively accounting for 28 percent of the ecosystem. The current landscape comprises 234 active studios, ranging from multinational corporations to independent developers and service providers. Among the top 30 companies by turnover are major international players such as Electronic Arts Romania, Ubisoft, and Gameloft, alongside a diverse array of specialized local studios.
The industry ecosystem is supported by a domestic player base of 8.6 million individuals. The transition from a service-heavy model to a more balanced mix of development and publishing has fostered a more sustainable environment for local talent. By diversifying its operational focus, the Romanian gaming sector has successfully navigated recent economic pressures, positioning itself as a key European hub for both large-scale multinational production and agile, independent game creation.
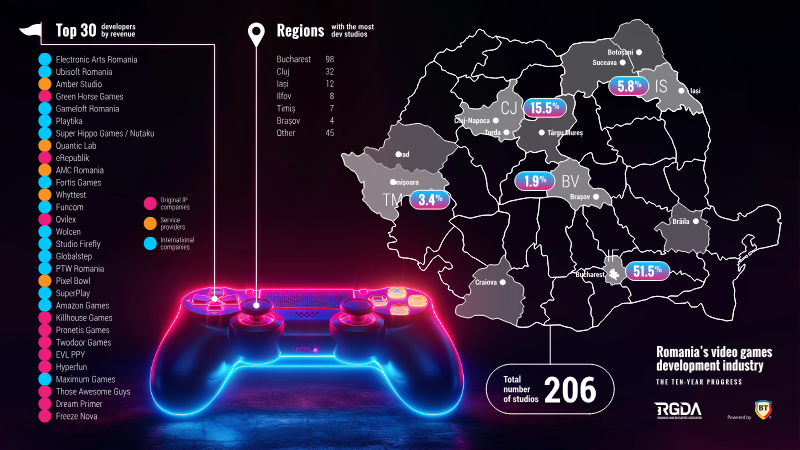
RGDA – Romanian Game Developers Association · 2025
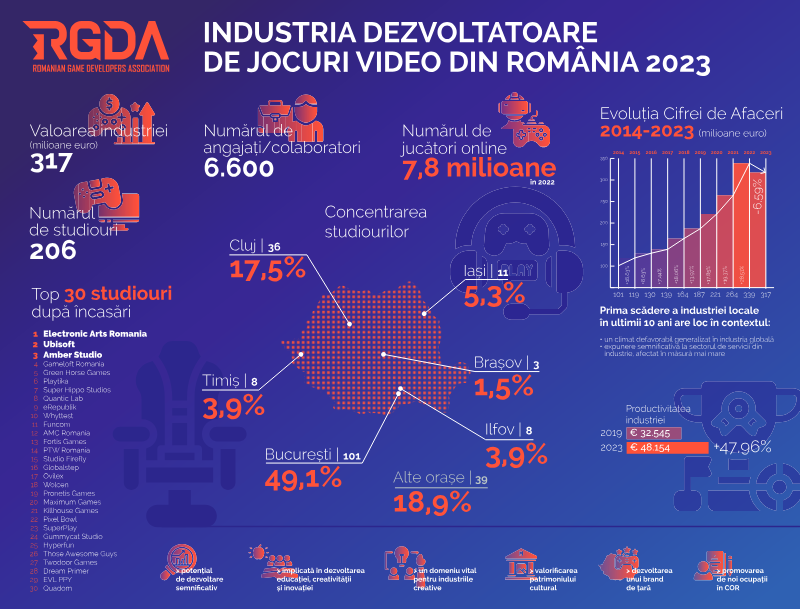
RGDA – Romanian Game Developers Association · 2023
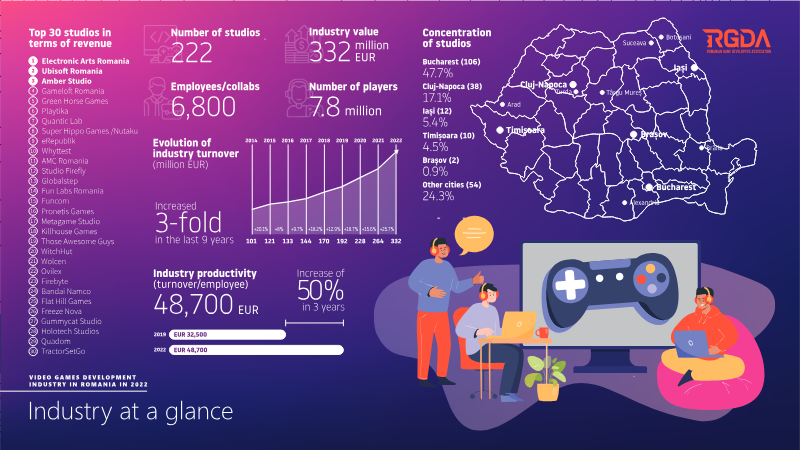
RGDA – Romanian Game Developers Association · 2022
RGDA – Romanian Game Developers Association · 2021
RGDA – Romanian Game Developers Association · 2019
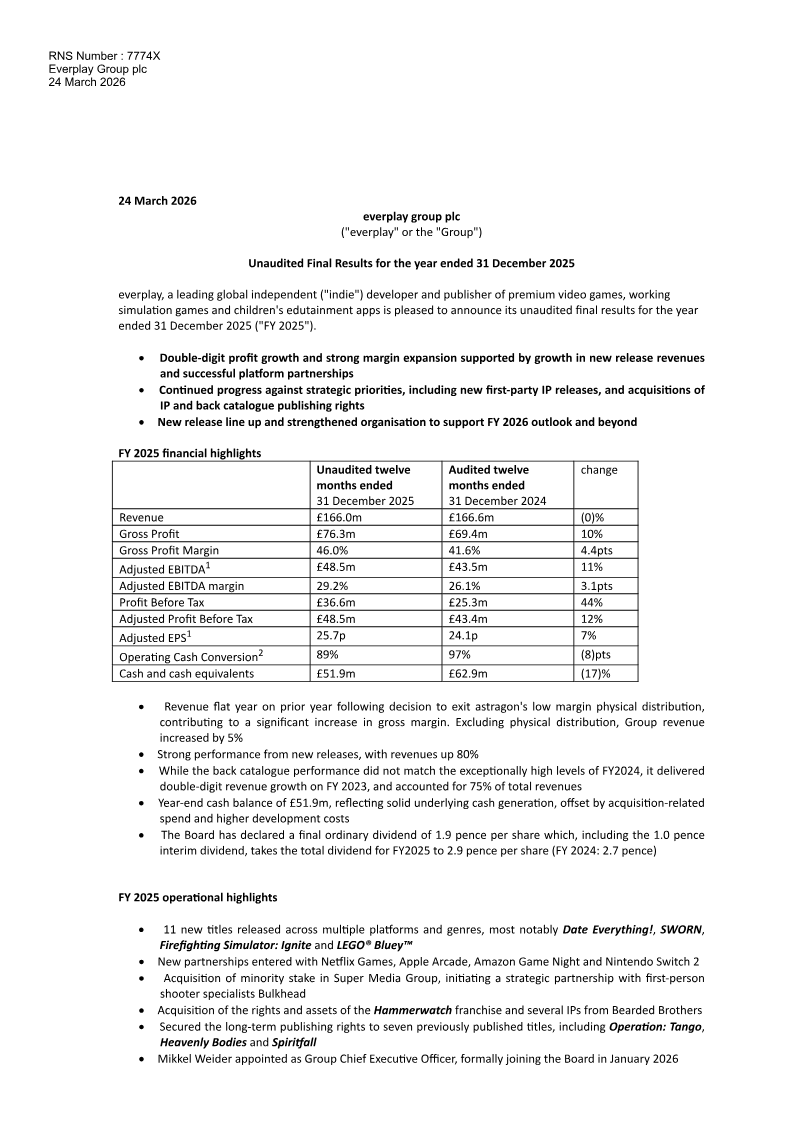
Everplay Group · 2026
Naavik · 2026
Dataspelsbranschen · 2023
game – Verband der deutschen Games-Branche e. V.
11 bit studios
11 bit studios
GREE
11 bit studios
PCF Group
11 bit studios
Frontier Developments
GREE