Mergers & Acquisitions reports and market data
Documents
What Was Left Unsaid by Playtika’s Proposal and Jam City’s Exits? - Naavik Gaming Podcast
The global gaming industry is currently navigating a period of significant strategic realignment, characterized by aggressive consolidation attempts, leadership transitions, and the ongoing search for sustainable growth in emerging sectors.
- Meta’s Reality Labs has incurred a $30 billion deficit, highlighting the massive capital expenditure required to overcome hardware and ergonomic barriers in the VR sector.
- Major mobile gaming firms like Playtika are pursuing acquisitions of established studios like Rovio to address stagnant development pipelines and aging product portfolios.
- Jam City is refocusing on core free-to-play mobile operations by spinning off experimental Web3 and AI divisions following internal layoffs and leadership turnover.
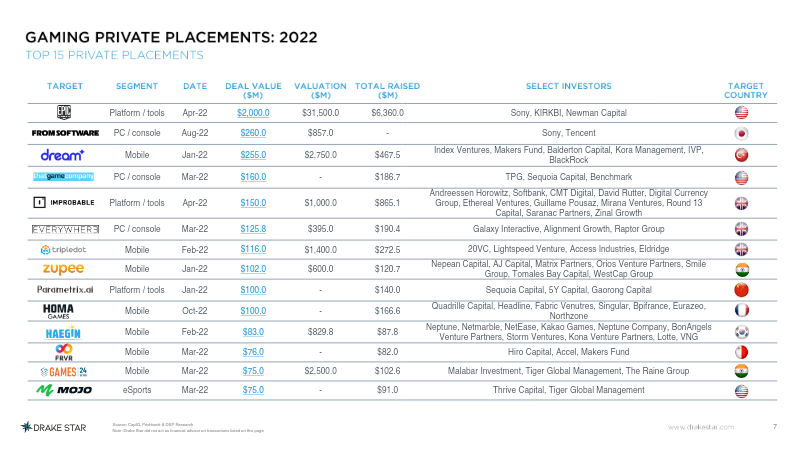
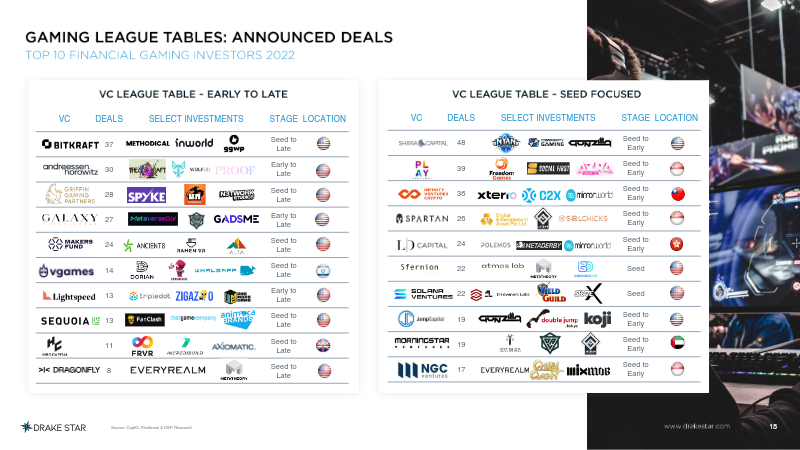
Global Gaming Report 2022
The global gaming market achieved a record $127 billion in total deal value across 1,320 transactions in 2022, a surge primarily fueled by a threefold increase in merger and acquisition volume.
- The global gaming market reached a record $127 billion in deal value across 1,320 transactions in 2022, driven by a threefold increase in M&A volume headlined by Microsoft’s $68.9 billion pending acquisition of Activision Blizzard and Take-Two’s $12.7 billion purchase of Zynga.
- Public gaming stocks faced significant volatility with many market capitalizations dropping over 30%, while private financing deal counts rose 29% despite a decline in total capital raised to $11.1 billion due to cooling late-stage investment.
- Blockchain gaming proved resilient, securing $4 billion in funding across nearly 400 companies, bolstered by over $13 billion in specialized venture capital fund commitments.
H1 2023 Gaming Deals Report: Navigating Turbulence
The gaming industry experienced a significant contraction in deal-making activity during the first half of 2023, characterized by a challenging macroeconomic environment and a cooling of investor sentiment.
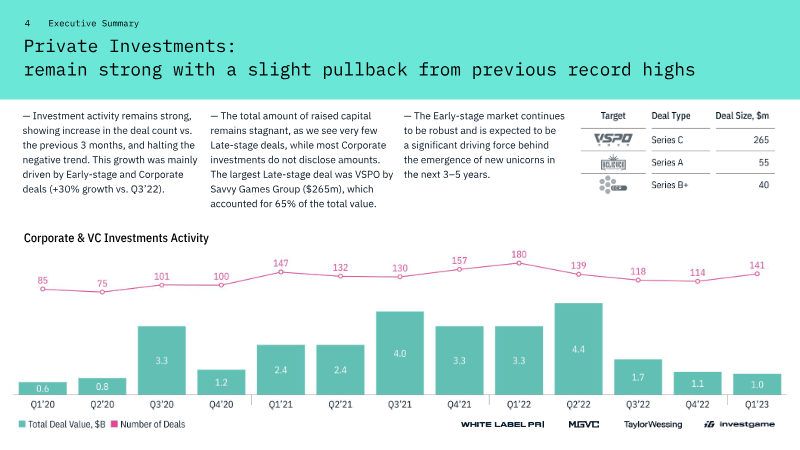
- H1 2023 saw a significant contraction in gaming deal-making, with private investments falling to $1.5 billion across 239 deals compared to the same period in 2022.
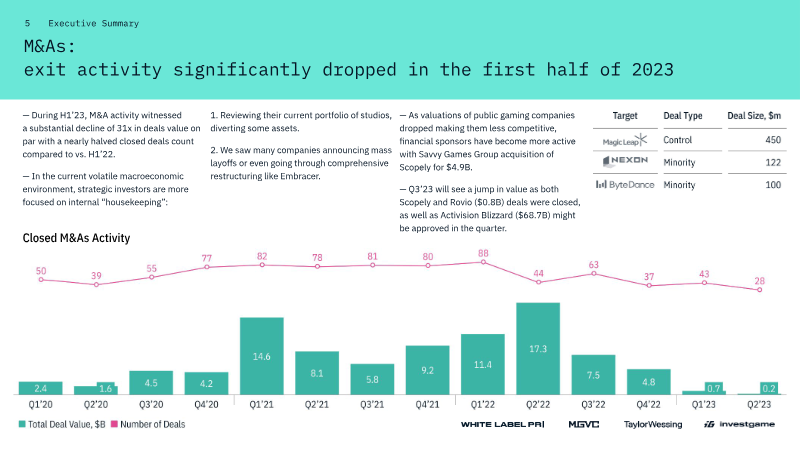
- M&A activity experienced a sharp decline as strategic investors prioritized internal restructuring and portfolio management over new acquisitions.
- Public offerings remained largely stagnant throughout the first half of 2023 due to unfavorable market conditions and necessary valuation corrections.
Q1 2023 Gaming Deals Report: Cooling Off After Years of Blistering Growth
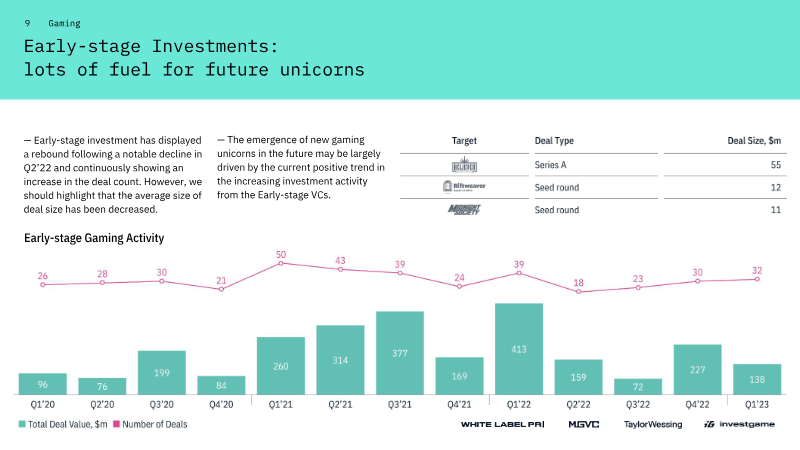
The gaming industry experienced a significant cooling period in the first quarter of 2023, characterized by a sharp decline in deal activity across private investments, mergers and acquisitions (M&A), and public offerings.
- Q1 2023 marked a significant industry-wide cooling period, characterized by a sharp decline in private investments, M&A activity, and public offerings compared to previous years of rapid growth.
- M&A activity hit a low point in Q1 2023, recording approximately half the volume seen in previous years.
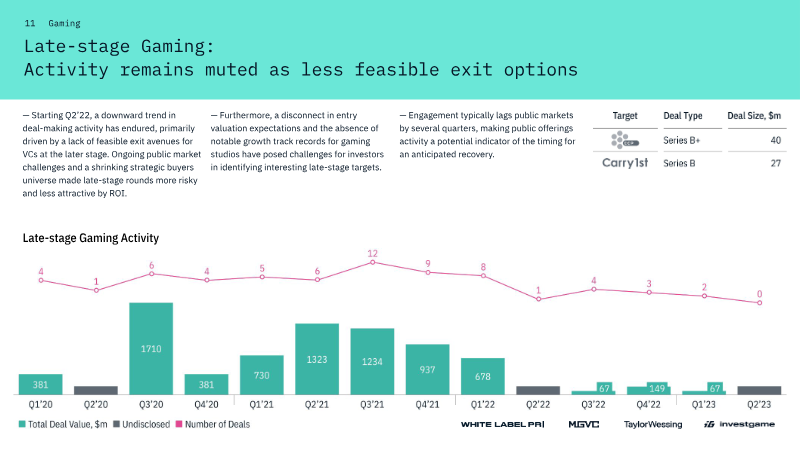
- Late-stage funding has stalled significantly, with only two closed transactions recorded throughout the entire first quarter.
2022 Gaming Deals Review & Naavik’s Highlights Awards - The Metacast by Naavik
The global gaming industry faced a period of significant contraction throughout 2022, characterized by a marked decline in both deal volume and total investment value.
- The global gaming industry experienced a significant contraction in 2022, marked by a decline in both total investment value and deal volume driven by macroeconomic instability and rising interest rates.
- Regulatory scrutiny intensified in 2022, highlighted by the Federal Trade Commission’s record-setting settlement with Epic Games regarding privacy and monetization practices.
- Despite the downturn, venture capital firms hold substantial dry powder, which is expected to support ongoing M&A activity and private investment throughout 2023.
Alexis Bonte: Stillfront’s Strategy, Synergies & Future - The Metacast by Naavik
Stillfront Group operates as a decentralized network of 23 game studios, employing 1,600 professionals under a structure designed to preserve creative autonomy while providing the governance of a public entity.
- Stillfront Group manages a decentralized network of 23 game studios and 1,600 employees, utilizing an inverted pyramid model that centralizes administrative, legal, and HR functions to preserve studio creative autonomy.
- The company’s M&A strategy prioritizes the acquisition of profitable, experienced studios within evergreen verticals like sports and role-playing games to ensure long-term operational stability over high-risk ventures.
- Stillfront leverages a centralized marketing hub and shared technical infrastructure to enable smaller studios to achieve economies of scale and cross-studio synergies.
Kress's Corner #2 How do gaming venture capitalists really work?
Venture capital in the gaming sector is currently undergoing a strategic shift, moving away from the speculative content-heavy investments of the 2020–2021 bubble toward more sustainable infrastructure and middleware solutions.
- Gaming venture capital is shifting away from speculative game studio investments toward B2B infrastructure and middleware solutions to build more defensible, sustainable market moats.
- Investment strategies are currently prioritizing strict valuation ratios and high-quality operators over the trend-chasing behavior that characterized the 2020–2021 market bubble.
- Venture firms operate on a 7-to-10-year fund lifecycle, focusing on rigorous deal filtering and 'smart capital' partnerships that provide founders with strategic guidance rather than just liquidity.
MTG Game Makers Day 2022
MTG has successfully transitioned into a pure-play mobile gaming group, shifting from a diversified holding company to an integrated acceleration platform.
- MTG has completed its transition into a pure-play mobile gaming group, operating as an integrated platform rather than a diversified holding company.
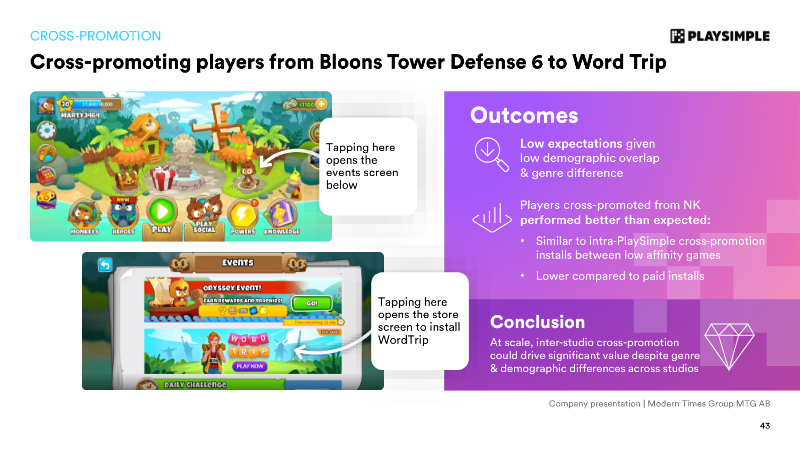
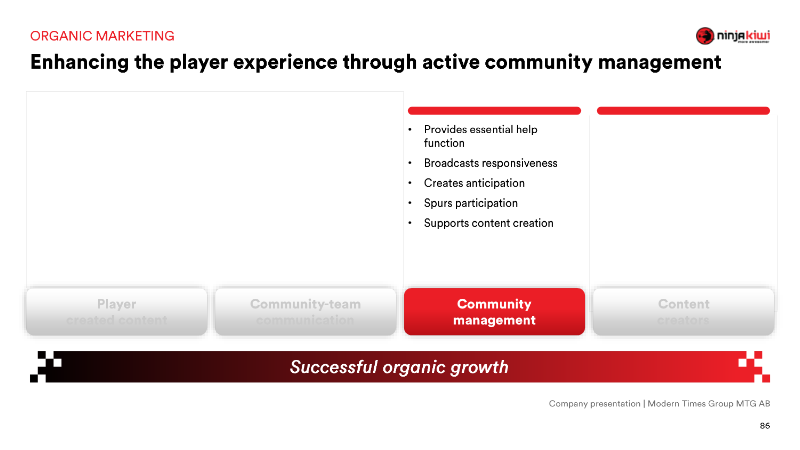
- The 'Flow Platform' serves as the central ecosystem for sharing data, marketing technology, and monetization tools across all portfolio studios to drive growth above market averages.
- PlaySimple drives revenue through a proprietary ad-tech stack focused on word games, while InnoGames utilizes AI-driven CRM and LiveOps to maintain long-term player retention.
Rise of The Mega-Investors: Tencent & Savvy Gaming Group - The Metacast by Naavik
The global gaming industry is currently undergoing a period of intense consolidation and strategic realignment, driven by the emergence of mega-investors such as Saudi Arabia’s Savvy Gaming Group and the international expansion efforts of Tencent.
- The gaming industry is shifting toward a centralized model driven by mega-investors like Tencent and Saudi Arabia’s Savvy Gaming Group, which prioritize large-scale asset accumulation over traditional competitive dynamics.
- The failure of Google Stadia demonstrates that massive financial backing cannot overcome a fundamental lack of alignment with gaming-specific consumer behaviors and technical ecosystem requirements.
- Supercell maintains a high-threshold development culture that prioritizes multi-billion dollar hit potential, strictly abandoning projects that fail to meet extreme user retention standards.
Gaming Industry Report: Q4 2022
The analysis presents a comprehensive overview of the global gaming market in 2022 and its projected trajectory to 2027, emphasizing a modest expansion of the sector’s revenue base and a shifting investment landscape.
- The global gaming market reached $184.4 billion in 2022, a 2.3% year-over-year increase, with projections estimating growth to $283 billion by 2027.
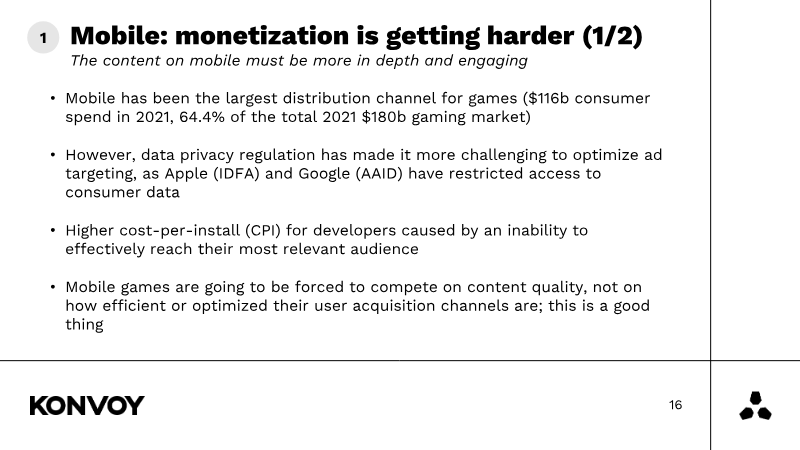
- Mobile gaming remains the primary revenue driver, accounting for 64% of total industry spend, or $116 billion in 2021.
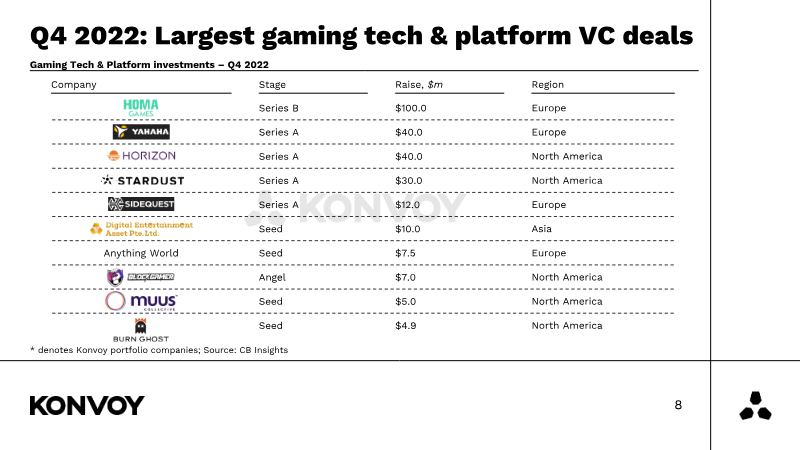
- Venture capital funding for the gaming sector contracted significantly in 2022, falling from $8.8 billion to $5.3 billion, with web3 gaming experiencing a global downturn and an 83% funding collapse in Latin America.
Embracer Group Annual General Meeting FY 21/22: Presentation
Embracer Group achieved substantial financial expansion during the 2021/2022 fiscal year, characterized by an 89 percent increase in net sales to SEK 17,037 million and a 54 percent rise in adjusted EBIT to SEK 4,416 million.
- Embracer Group achieved significant financial growth in FY 21/22, with net sales rising 89% to SEK 17,037 million and adjusted EBIT increasing 54% to SEK 4,416 million.
- The company is shifting from an aggressive acquisition-led strategy to a more disciplined, value-accretive approach focused on organic growth and stricter investment hurdles to manage macroeconomic volatility.
- A record SEK 3.5 billion was invested in internal game development during the fiscal year to support long-term IP value creation.
Strategy Case Studies: Mobile Clones, IP Ecosystem, UGC - The Metacast by Naavik
The mobile gaming landscape is currently defined by a strategic tension between agile, independent development and the massive scaling capabilities of established publishers.
- Small, agile teams can capture significant market share by adapting successful concepts for mobile-first audiences, as demonstrated by the nine-person team behind Stumble Guys.
- Successful mobile titles often follow a lifecycle of rapid development and scaling by independent teams, followed by acquisition by larger publishers to leverage infrastructure for long-term live operations.
- Major publishers like Ubisoft are pivoting toward expansive IP ecosystems, using cross-media partnerships like those with Netflix to transform franchises into centralized, multi-platform hubs.