Market Analysis
Documents
Cross-Platform Gaming: Bridging Mobile and PC/Console
The 2025 gaming landscape is defined by the convergence of mobile accessibility and PC/console depth. The primary thesis suggests that while mobile serves as a global discovery engine and a source of steady growth, PC and console platforms anchor brand prestige and high-value engagement. To maximize franchise value, publishers must strategically bridge these ecosystems through purposeful cross-platform design, turning mobile’s vast reach into lasting loyalty.
Data highlights a significant scale disparity between platforms: mobile is projected to reach 52 billion downloads and $82 billion in in-app purchase revenue in 2025, while the PC and console segment generates over $12 billion from 1 billion units sold. Mobile leaders like Roblox and Garena Free Fire drive mass acquisition, whereas premium titles such as EA SPORTS FC 25 and Marvel Rivals dominate engagement on Steam, PlayStation, and Xbox. The findings indicate that unified ecosystems, such as those used by Delta Force and Genshin Impact, strengthen retention by allowing players to switch devices without losing progress.
The scope of the analysis is global, covering over 100 markets with specific digital advertising data from 14 major regions, including the United States, Japan, and the United Kingdom. It focuses on the first three quarters of 2025, utilizing Sensor Tower’s proprietary App Performance, Video Game, and Pathmatics Advertising Insights. Methodology involves statistical sampling of digital ad placements and estimated revenue from the App Store and Google Play, excluding third-party Android stores and direct web payments.
Four strategic models for expansion are identified: companion apps for engagement, "lite" versions for mass discovery, adapted standalone experiences for genre diversification, and full cross-play models for community unification. The conclusion emphasizes that a resilient portfolio must balance high-volume mobile genres, such as Simulation and Puzzle, with high-depth PC genres like RPGs and Shooters to maximize monetization efficiency and franchise longevity.
- Mobile remains the primary driver of scale with 52 billion projected downloads and $82 billion in in-app purchase revenue for 2025, while PC and console segments generate over $12 billion from 1 billion units sold.
- Unified cross-platform ecosystems, exemplified by titles like Genshin Impact and Delta Force, significantly improve player retention by enabling seamless progress synchronization across devices.
- Publishers should adopt one of four strategic models—companion apps, 'lite' discovery versions, adapted standalone experiences, or full cross-play—to bridge the gap between mobile reach and PC/console engagement.
- A resilient gaming portfolio requires balancing high-volume mobile genres like Simulation and Puzzle with high-depth PC/console genres such as RPGs and Shooters to optimize monetization and franchise longevity.
- Mobile platforms currently function as global discovery engines for mass acquisition, whereas premium titles like EA SPORTS FC 25 and Marvel Rivals anchor high-value engagement on Steam, PlayStation, and Xbox.
From Games to the Big Screen: The Impact of IP Across Platforms
The entertainment industry is increasingly leveraging a transmedia strategy where video game intellectual property serves as the foundation for high-budget scripted content. This approach creates a symbiotic relationship between platforms, where the release of films and television series triggers a boomerang effect that revitalizes interest in the original games. Data indicates that these adaptations drive significant growth across multiple metrics, including active users, digital downloads, and in-app purchases, while simultaneously boosting the performance of the streaming services hosting the content.
The scope of this analysis covers major cross-platform releases between 2024 and 2025, focusing on global mobile, PC, and console gaming segments alongside digital advertising and streaming app performance. Key findings highlight the success of the Minecraft movie, which grossed over $900 million and led to a 44% spike in mobile in-app revenue and a 36% increase in console sales. Similarly, the Fallout television series drove a 23% increase in Amazon Prime Video downloads and a massive 410% surge in daily sales for Fallout 4 on PC. The longevity of this impact is notable, with daily active users for legacy Fallout titles remaining 225% higher for up to 20 weeks following the show's premiere.
Methodology relies on proprietary data from Sensor Tower, tracking digital market insights, app usage, and advertising spend. The data reveals that strategic marketing is essential to this success; for instance, Amazon increased its desktop video ad spend twentyfold to promote Fallout, specifically targeting gaming-focused platforms like Twitch and IGN. While results vary based on the faithfulness of the adaptation and the monetization model of the game, the overarching trend suggests that transmedia releases are a powerful tool for re-engaging historical players and attracting new audiences to established gaming franchises.
- The Fallout television series triggered a 410% surge in daily PC sales for Fallout 4 and sustained a 225% increase in daily active users for legacy titles for up to 20 weeks post-premiere.
- The Minecraft film grossed over $900 million while driving a 44% spike in mobile in-app revenue and a 36% increase in console sales.
- Transmedia adaptations create a symbiotic growth loop that simultaneously boosts gaming metrics and streaming platform performance, such as the 23% increase in Amazon Prime Video downloads following the Fallout series launch.
- Strategic marketing is a critical success factor, evidenced by Amazon increasing its desktop video ad spend twentyfold on gaming-centric platforms like Twitch and IGN to support the Fallout release.
- Video game IP is increasingly serving as a foundation for high-budget scripted content to re-engage historical players and attract new audiences across mobile, PC, and console segments.
Mapping IP fandom with the Global Gamer Study
This analysis explores the intersection of intellectual property (IP) fandom and player engagement within the global gaming industry. The primary thesis is that while transmedia collaborations are essential for driving player acquisition and retention in a live-service landscape, the effectiveness of an IP is heavily dictated by regional awareness and cultural sentiment. Success in global gaming requires a move away from one-size-fits-all licensing toward market-specific strategies that align with local fanbases.
The findings are based on the 2025 Global Gamer Study, which surveyed over 73,000 consumers across 36 markets, tracking awareness and attitudes toward 42 popular entertainment IPs. Data indicates that a majority of gamers in 24 of the 36 countries are more likely to play a game featuring their favorite IP. This influence is strongest in South Asia (74%) and Latin America (64%), while Western Europe and Oceania show more reserved engagement levels (45%).
The research categorizes IPs into four quadrants based on the relationship between awareness and favorability. Global Favorites, such as Harry Potter and Disney, maintain near-universal recognition (90%) and high sentiment. Familiar Faces like Star Wars and Barbie possess high awareness but suffer from polarizing or lower favorability in specific regions. Hidden Gems, including Studio Ghibli and various anime titles, maintain niche global awareness but command intense loyalty in specific markets like Japan or Vietnam. Finally, IPs with Limited Appeal, such as Doctor Who or Percy Jackson, struggle with both low recognition and lukewarm sentiment outside their core territories.
Geographic variations are stark; for instance, anime franchises like Dragon Ball achieve 85–90% awareness in Latin America and Southeast Asia, nearly double their recognition in the West. Conversely, Western staples like DC Comics see high awareness in the U.S. (70%) but significantly lower traction in Japan (21%). The study concludes that cultural resonance, linguistic accessibility, and historical distribution patterns are the primary drivers of IP success in the gaming sector.
- In 24 of 36 surveyed markets, gamers are more likely to play a title featuring an IP they favor, confirming that transmedia collaborations are a primary driver for acquisition and retention.
- IP influence on player engagement varies significantly by region, peaking in South Asia (74%) and Latin America (64%) compared to more reserved engagement in Western Europe and Oceania (45%).
- Global Favorites like Harry Potter and Disney maintain 90% recognition with high sentiment, whereas IPs like DC Comics show extreme regional variance, with 70% awareness in the U.S. versus only 21% in Japan.
- Anime franchises like Dragon Ball demonstrate the importance of market-specific strategies, achieving 85–90% awareness in Latin America and Southeast Asia—nearly double their recognition in Western markets.
- The 2025 Global Gamer Study, which tracked 42 entertainment IPs across 73,000 consumers, identifies cultural resonance, linguistic accessibility, and historical distribution as the primary determinants of IP success.
Roblox as a Strategic Growth Platform: What Developers Need to Know
Roblox has evolved from a youth-centric gaming site into a massive entertainment ecosystem and creator economy, boasting nearly 112 million daily active users and distributing over $300 million to creators in a single quarter. While the platform shares structural similarities with mobile gaming—such as an 80% mobile user base and monetization driven by cosmetics and gacha—it functions more like a social media platform such as TikTok or YouTube. Success is dictated by cultural fluency, rapid iteration, and social momentum rather than high graphical fidelity or traditional production cycles.
The platform’s audience is maturing, with the 13+ demographic growing at 54% year-over-year, significantly outpacing younger cohorts. This shift brings higher spending power and more sophisticated expectations to the ecosystem. Data indicates that Roblox is not a siloed experience; only 24% of players engage exclusively on mobile, with significant playtime occurring on PlayStation and PC. The genre landscape is dominated by Roleplay, Simulation, and Platformers, characterized by low-friction, social, and trend-driven mechanics that prioritize accessibility over complex skill sets.
For traditional developers, the platform serves as a strategic testing ground for intellectual property and audience cultivation among Gen Z and Gen Alpha. Because the discovery algorithm rewards speed and native platform knowledge, established studios are increasingly partnering with Roblox-native creators to navigate the unique development rhythm. The most effective strategies treat the platform as a long-term engagement tool rather than a standard publishing channel, focusing on branded activations and collaborative IP experiences to build brand affinity with the next generation of gamers.
- Roblox has scaled to 112 million daily active users and distributed over $300 million to creators in a single quarter, functioning more like a social media platform than a traditional gaming engine.
- The 13+ demographic is the platform's fastest-growing segment, increasing by 54% year-over-year and bringing higher spending power to the ecosystem.
- Success on the platform is driven by cultural fluency and rapid iteration rather than graphical fidelity, with discovery algorithms favoring native platform knowledge over traditional production cycles.
- Only 24% of players are mobile-exclusive, with significant engagement occurring across PlayStation and PC, necessitating a cross-platform approach to user retention.
- Established studios are increasingly partnering with Roblox-native creators to navigate the platform's unique development rhythm and trend-driven mechanics.
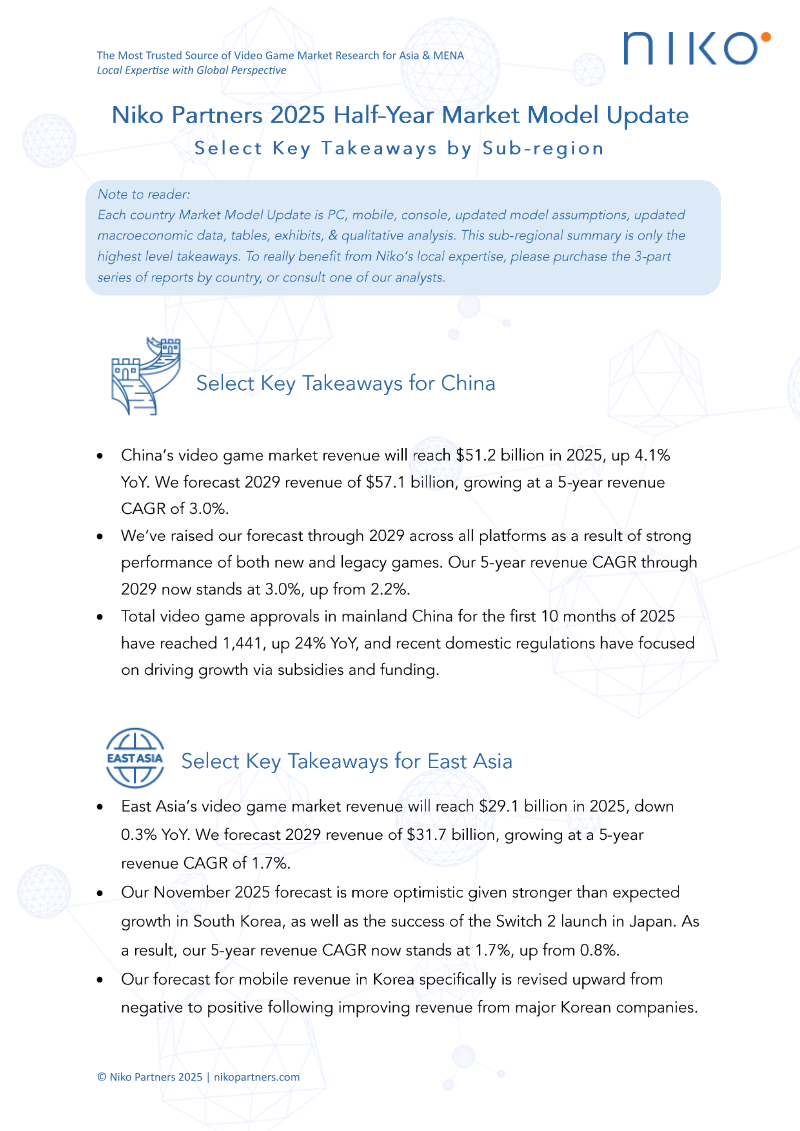
Asian & MENA Markets: 2025 Half-Year Report
The video game markets across Asia and the Middle East are entering a period of recalibrated growth, with total revenues across key sub-regions projected to reach significant milestones by 2025. China remains the dominant force, with revenues expected to hit $51.2 billion in 2025, supported by a 4.1% year-over-year increase. This growth is fueled by a 24% rise in game approvals and proactive government subsidies. While China maintains a steady long-term outlook with a 3.0% five-year compound annual growth rate, India emerges as the fastest-growing market. India is projected to surpass the $1 billion threshold in 2025 with a 16.2% year-over-year increase, driven by the PROG Act of 2025, which pivoted the industry away from real-money gaming toward traditional video games and esports.
Regional performance varies significantly based on local macroeconomic conditions and hardware cycles. East Asia, comprising Japan and South Korea, shows a more optimistic outlook than previously anticipated, with a revised five-year growth rate of 1.7%. This shift is attributed to the successful launch of the Nintendo Switch 2 and a recovery in the South Korean mobile sector. Conversely, Southeast Asia and the MENA-3 region (Saudi Arabia, UAE, and Egypt) face more tempered expectations. Southeast Asia’s growth forecast was lowered to 3.5% due to headwinds in Thailand and Indonesia, despite strong performance in Vietnam. Similarly, the MENA-3 forecast was adjusted downward to a 6.4% growth rate as economic challenges in Egypt and slower mobile growth in Saudi Arabia offset increased government support for localization and age-rating reforms.
The data, derived from Niko Partners’ 2025 half-year market model updates, covers PC, mobile, and console platforms across 13 distinct markets. The methodology integrates proprietary market models, macroeconomic indicators, and qualitative regulatory analysis to provide a comprehensive five-year outlook through 2029. Overall, the findings suggest that while mature markets like China and East Asia are stabilizing, emerging markets like India and Vietnam are becoming critical drivers of global industry expansion.
- China remains the dominant regional market with projected 2025 revenues of $51.2 billion, supported by a 4.1% year-over-year increase and a 24% rise in government game approvals.
- India is the fastest-growing market, projected to exceed $1 billion in 2025 with 16.2% year-over-year growth following the PROG Act's shift toward traditional gaming and esports.
- The MENA-3 region (Saudi Arabia, UAE, and Egypt) has a revised growth forecast of 6.4%, as economic challenges in Egypt and slowing mobile growth in Saudi Arabia temper the impact of government-led localization efforts.
- East Asia’s five-year growth outlook has been revised to 1.7%, bolstered by the launch of the Nintendo Switch 2 and a recovery in the South Korean mobile sector.
- Southeast Asia’s growth forecast is 3.5%, with strong performance in Vietnam being offset by macroeconomic headwinds in Thailand and Indonesia.
Video Gaming Report: How Platforms Are Colliding and Why This Will Spark the Next Era of Growth
The video gaming industry is transitioning into a new era of growth following a post-pandemic stabilization period. While the sector is unlikely to replicate the rapid doubling of the 2010s, a convergence of technological and structural shifts is expected to revitalize the market. This evolution is driven by four primary strategic trends: the integration of Generative AI, the expansion of the user-generated content (UGC) creator economy, the mainstream adoption of cloud gaming, and the regulatory opening of mobile app stores.
Key findings indicate that Generative AI is already being utilized by approximately 50% of studios to improve development efficiency and create adaptive gameplay, with 20% of new Steam games disclosing AI use by mid-2025. Simultaneously, the creator economy is surging; payouts from platforms like Roblox and Fortnite are projected to exceed $1.5 billion in 2025. Cloud gaming is also positioned for a massive scale-up, with revenues forecasted to grow from $1.4 billion in 2025 to $18.3 billion by 2030. This shift toward hardware-agnostic play is mirrored in distribution, where 33% of adult gamers have already purchased titles directly from developer web stores to bypass traditional platform fees.
The scope of this analysis is global, with a particular focus on major markets including the US, China, Germany, Japan, and South Korea. It covers the industry from late 2025 through projections for 2030, spanning mobile, console, and PC segments. Data is derived from the Global Gaming Survey of approximately 3,000 gamers, metadata analysis of the Steam platform, and interviews with industry leaders and developers.
The industry concludes that success in this new landscape requires a departure from traditional "console war" mentalities in favor of ecosystem-based strategies. Developers must master new monetization models, such as tiered pricing and windowing, to protect the value of premium content while navigating a market increasingly defined by infinite digital shelf space and algorithmic discovery.
- Cloud gaming revenue is projected to scale from $1.4 billion in 2025 to $18.3 billion by 2030, marking a transition toward hardware-agnostic play.
- The creator economy is expanding rapidly, with payouts to creators on platforms like Roblox and Fortnite projected to exceed $1.5 billion in 2025.
- Generative AI is currently used by 50% of studios to enhance development efficiency, with 20% of new Steam games expected to disclose AI usage by mid-2025.
- Direct-to-consumer distribution is gaining traction, as 33% of adult gamers have already purchased titles via developer web stores to circumvent traditional platform fees.
- Industry success now requires shifting from console-centric competition to ecosystem-based strategies that utilize tiered pricing and windowing to manage content value.
Championing the 25 Retailers and Digital Services Who Connect Music, Video and Games Creators with UK Fans Yearbook
The United Kingdom’s entertainment market reached a historic milestone in 2024, achieving a record valuation of £12.0 billion. This performance marks twelve consecutive years of growth and a 50% increase in market value since 2019. The industry has undergone a near-total digital transformation, with streaming and digital services now accounting for 93% of total revenues. Subscription-based models have become the primary engine of this economy, representing over three-quarters of total consumer spend across the music, video, and gaming sectors.
Video remains the largest individual segment, valued at £5.0 billion. This growth is fueled almost exclusively by Subscription Video on Demand (SVoD), which rose 8.3% to reach £4.46 billion, offsetting a sixteen-year decline in physical media. Conversely, the gaming sector experienced a 4.4% contraction to £4.61 billion. This decline was driven by a sharp 34.5% collapse in physical software sales and a cyclical downturn in hardware as major consoles reach maturity. Despite this, gaming remains overwhelmingly digital, with 98.6% of consumer spend occurring through online channels, particularly via mobile gaming and digital subscriptions.
Music emerged as the fastest-growing sector, reaching a record £2.4 billion. While digital streaming accounts for 85% of this value, the music industry is unique for its resilient physical market. Vinyl LPs saw their 17th consecutive year of growth, with unit sales rising to 7.1 million. This resurgence has revitalized the high street; independent music shops now account for 24% of total outlets, up from just 2% in 2015. While supermarkets and traditional retailers are exiting the physical games and video space, specialist and independent retailers are capturing a five-year high in physical market share, supported by major promotional events and a consumer shift toward high-definition and collectible formats.
- The UK entertainment market reached a record £12.0 billion valuation in 2024, marking twelve consecutive years of growth and a 50% increase since 2019.
- Digital services and streaming now dominate the industry, accounting for 93% of total revenue, with subscription models driving over 75% of consumer spending.
- Video is the largest sector at £5.0 billion, fueled by an 8.3% rise in Subscription Video on Demand (SVoD) to £4.46 billion, which successfully offset the decline in physical media.
- The gaming sector contracted 4.4% to £4.61 billion, impacted by a 34.5% collapse in physical software sales and a cyclical downturn in console hardware.
- Music is the fastest-growing sector at £2.4 billion, supported by a resilient physical market where vinyl LP sales grew for the 17th consecutive year to 7.1 million units.
Insights into Global Mobile Game Marketing Trends for H1 2025
The first half of 2025 reveals a rapid shift in mobile‑game user‑acquisition toward AI‑driven creative production, with short‑form video, live‑action clips and in‑game audio ads now accounting for the majority of impressions. Generative‑AI tools and AI‑enhanced playable ads compress development cycles to under a week, allowing marketers to test multiple concepts at low cost while retaining retargeting as a core pillar of acquisition strategy.
Genre competition intensifies, especially for role‑playing games, which generate an average of 224 new creatives per advertiser each month. Casino titles expand their share by 14.5 % year‑over‑year, becoming the second‑largest spend category. Europe hosts the largest pool of advertisers—over 43 000 monthly, a rise of 10 000 from the previous year—while North America exhibits the highest creative density, with roughly 119 assets per advertiser. In casual games, AI‑generated vertical video now consumes about 40 % of media spend, underscoring the dominance of automated formats across regions.
Key operational challenges include limited reach to high‑value users, protracted creative rollout times, and declining engagement as mature audiences become ad‑fatigued. Lengthy or fragmented landing‑page experiences further erode trust, suppressing download conversion and long‑term retention.
To counter these pressures, firms are advised to institute rapid‑iteration pipelines that move concepts to live within seven days, maintain a refresh cadence of two to three creative updates per month, and prioritize concise, transparent messaging that streamlines the post‑click flow. Embracing these practices is projected to improve acquisition efficiency and sustain user interest amid an increasingly saturated global mobile‑gaming market.
- AI-driven creative production has become the industry standard, with generative tools and AI-enhanced playable ads compressing development cycles to under one week.
- Europe leads in market participation with over 43,000 monthly advertisers, while North America maintains the highest creative density at approximately 119 assets per advertiser.
- Casino games have emerged as the second-largest spending category, recording a 14.5% year-over-year increase in market share.
- Role-playing games are the most competitive segment, requiring an average of 224 new creatives per advertiser each month to maintain visibility.
- In the casual gaming sector, AI-generated vertical video now accounts for 40% of total media spend.
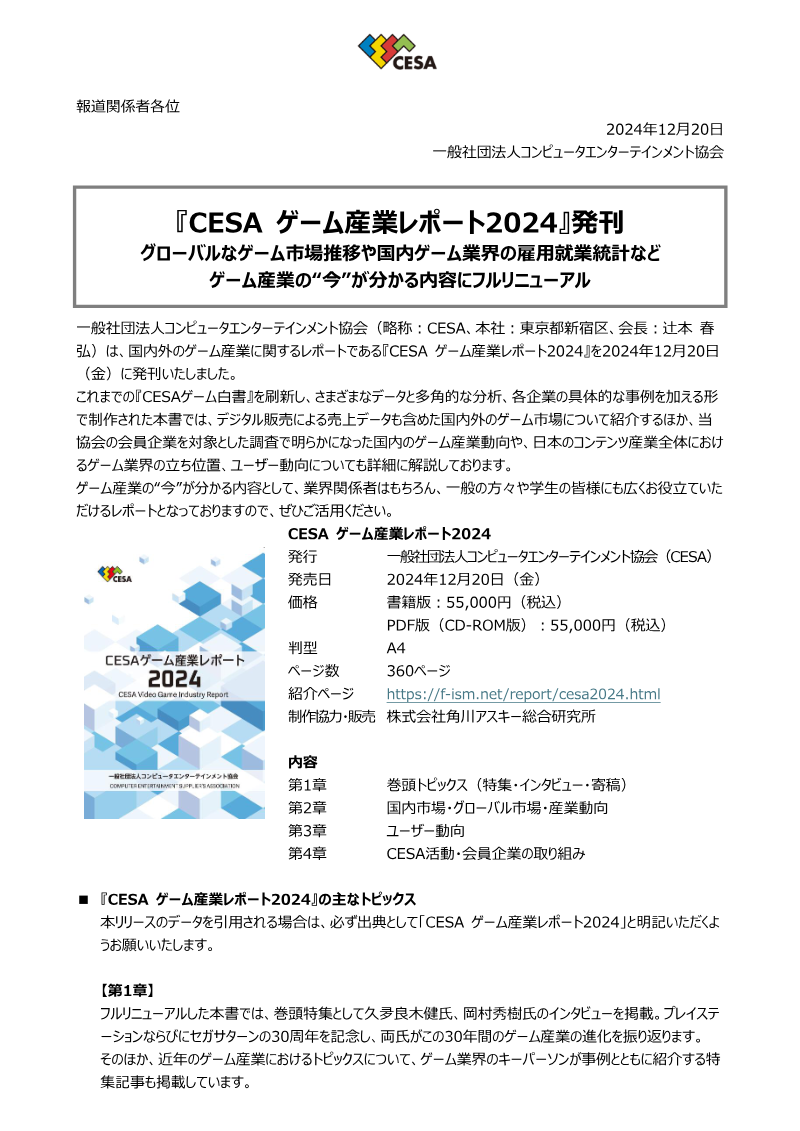
CESA Game Industry Report 2024
CESA Game Industry Report 2024 – Executive Summary (English)
1. Publication Details | Item | Information | |------|--------------| | Title | CESA ゲーム産業レポート 2024 (CESA Game Industry Report 2024) | | Publisher | 一般社団法人コンピュータエンターテインメント協会 (Computer Entertainment Supplier’s Association, CESA) | | Release date | 20 December 2024 (Friday) | | Price | ¥55,000 (incl. tax) – both printed book and PDF/CD‑ROM versions | | Format | A4, 360 pages | | ISBN / Catalog | CESAJ‑LV‑ (internal code) | | Production partner | 株式会社角川アスキー総合研究所 (Kadokawa ASCII Research Institute) | | Official page | <https://f-ism.net/report/cesa2024.html> | | Contact | [email protected] |
> Citation note – When quoting any data from the report, cite it as “CESA ゲーム産業レポート 2024”.
2. Report Structure
| Chapter | Focus | |---------|-------| | Chapter 1 – Front‑matter (Topics, Interviews, Contributions) | Interviews with industry veterans (久夛良木健, 岡村秀樹) reflecting on 30 years of PlayStation & Sega Saturn; other key‑person case studies. | | Chapter 2 – Market & Industry Trends (Domestic & Global) | Macro‑level market size, platform breakdown, development costs, employment, cross‑media context. | | Chapter 3 – User Trends | Player demographics, platform usage, esports, multi‑platform activity. | | Chapter 4 – CESA Activities & Member Initiatives | Overview of CESA‑hosted events (Tokyo Game Show, CEDEC) and member‑company projects. |
3. Key Findings
3.1 Global Game‑Content Market Size (2020‑2024) – Approximately ¥30 trillion in 2024, nearly double the 2020 level (¥20 trillion). Growth drivers – Strong yen‑depreciation effect post‑2022, continued expansion of mobile gaming, and rising PC‑gaming share (thanks to Steam). Platform share (2024) – Mobile: dominant share (≈ 60 % of global revenue). Console: ~ 20 % of revenue. PC: ~ 20 % (growing steadily).
3.2 Japan’s Content Industry & Game Share Total overseas export of Japanese content: ¥4.7 trillion (on par with semiconductor & steel sectors). Games’ contribution: ≈ 60 % of that export value → games are the primary driver of foreign‑exchange earnings within the broader content sector.
3.3 Domestic Game‑Industry Employment & Compensation Total industry employment: ≈ 200,000 workers (including peripheral sectors). Average annual salary: ¥7.08 million – markedly higher than the average across
- The global game-content market reached approximately ¥30 trillion in 2024, nearly doubling from the ¥20 trillion recorded in 2020.
- Mobile gaming remains the dominant global platform, accounting for approximately 60% of total revenue, while console and PC sectors each hold roughly 20% shares.
- Japanese game exports generate approximately ¥2.82 trillion, representing about 60% of the country's total ¥4.7 trillion content industry exports.
- The Japanese game industry's export value is now on par with major industrial sectors such as semiconductors and steel.
- The domestic game industry employs approximately 200,000 workers, including those in peripheral sectors.
Digital Market Index: Q4 2024
Global digital markets reached a significant milestone in the final quarter of 2024, with in-app purchase revenue hitting a record $39.4 billion. This growth was primarily fueled by a 28.2% year-over-year surge in non-game applications, exemplified by TikTok becoming the first app to surpass $6 billion in annual revenue. While the iOS ecosystem remains the primary driver of monetization by capturing 70% of total revenue, Google Play maintains its dominance in scale, facilitating nearly three-quarters of the 34.1 billion global downloads recorded during the period.
The mobile gaming landscape underwent a notable structural shift as consumer preferences migrated from traditional RPGs toward Strategy and Puzzle titles. Strategy games experienced a 26% year-over-year increase in downloads, helping to offset regional revenue declines in major markets like Japan and South Korea. Despite these shifts, Japan’s mobile sector showed signs of overall recovery, while emerging Android markets in Indonesia and Pakistan continued to expand rapidly. The successful launch of high-profile titles like Pokémon TCG Pocket further stabilized the gaming sector during this transition.
Advertising and retail media also reached unprecedented levels, with U.S. digital ad spend hitting $34 billion. Social media channels dominated this space, accounting for 77% of total expenditures as major retailers like Amazon and Walmart increased holiday investments. Retail media specifically generated a record 75.4 billion impressions, driven by high demand in consumer electronics and personal care. Strategic co-branded partnerships, such as the collaboration between Best Buy and Samsung, emerged as critical drivers of visibility, cementing the role of retail platforms as essential components of the broader digital advertising ecosystem.
- Global in-app purchase revenue reached a record $39.4 billion in Q4 2024, bolstered by a 28.2% year-over-year surge in non-game application spending.
- TikTok became the first application to surpass $6 billion in annual revenue, highlighting the massive monetization potential of non-game platforms.
- The iOS ecosystem captured 70% of total revenue, while Google Play maintained its dominance in scale by facilitating nearly 75% of the 34.1 billion global downloads.
- U.S. digital ad spend hit $34 billion in Q4 2024, with social media channels accounting for 77% of total expenditures.
- Mobile gaming preferences shifted toward Strategy and Puzzle titles, with Strategy games seeing a 26% year-over-year increase in downloads to help offset regional revenue declines in Japan and South Korea.
2024 Global Mobile Games Marketing Trends & Insights
The global mobile gaming industry is currently defined by extreme market concentration and a fundamental shift in monetization and marketing strategies. With the top 50 publishers generating 70% of total revenue, the sector is moving toward hybrid-casual models that blend ad-based revenue with in-app purchases to offset rising user acquisition costs. Strategic priorities for 2025 include the expansion of Direct-to-Consumer platforms to preserve margins and a resurgence in HTML5 web games. This evolution is occurring alongside a surge in marketing volume; in 2024, the industry saw over 250,000 advertisers and 46.2 million creative assets, representing a 60% year-over-year increase in advertising activity despite a declining rate of new market entrants.
Geographically, the landscape is marked by rapid growth in Southeast Asia and Latin America, while the United States remains a dominant but maturing market. High-production, cross-platform free-to-play titles, particularly from Chinese developers, are raising consumer expectations and challenging traditional premium pricing models. To navigate privacy-related data limitations, marketers are increasingly adopting creative-level attribution and generative AI for both content production and data analysis. Short-form video has become the primary driver of engagement, accounting for up to 81% of impressions in genres like Puzzle and Simulation, often utilizing AI-generated imagery and demographic-specific hooks to capture niche audiences.
Tactical trends reveal a widespread reliance on intellectual property and the integration of casual mini-game mechanics to market hardcore RPG and Strategy titles. Successful campaigns frequently leverage localized content and specialized creative formats, such as "stomp" transitions for social media or long-form puzzles to attract RPG players. This data, synthesized from over 1.6 billion ad records across 80 countries, underscores a transition toward high-volume, AI-enhanced marketing where deep user segmentation and creative variety are essential for maintaining player lifetime value in an increasingly competitive global environment.
- The top 50 publishers now control 70% of total global mobile gaming revenue, driving a market-wide shift toward hybrid-casual models that combine ad-based revenue with in-app purchases.
- Advertising activity surged by 60% year-over-year in 2024, with 250,000 advertisers deploying 46.2 million creative assets despite a decline in new market entrants.
- Short-form video has become the dominant engagement driver, accounting for up to 81% of impressions in the Puzzle and Simulation genres.
- Marketers are increasingly bypassing platform limitations by adopting creative-level attribution and leveraging generative AI for both content production and data analysis.
- Growth is accelerating in Southeast Asia and Latin America, while high-production, cross-platform free-to-play titles from Chinese developers are successfully challenging traditional premium pricing models.
Financial Results 9M24
PCF Group S.A. presents its financial and operational results for the first nine months of 2024, focusing on the performance of its global development studios and its VR-specialized subsidiary, Incuvo. The report covers the group’s activities across its primary hubs in Europe and North America, tracking the evolution of its workforce and project portfolio through September 30, 2024.
Financial performance for the 9M 2024 period shows total revenues of PLN 131.9 million, an increase from PLN 111.3 million in the same period of 2023. This growth was primarily driven by the recognition of revenues from the release of Bulletstorm VR in the first quarter and an increase in Work-for-Hire (WFH) revenues during the third quarter. However, profitability was negatively impacted by several factors, leading to a net loss of PLN 33.3 million compared to a loss of PLN 13.4 million in the previous year. Key detractors included a PLN 7.8 million write-down related to Project Red and revenue adjustments for Project Gemini following amended contract terms with Square Enix, which lowered margins. Adjusted EBITDA fell to negative PLN 1.7 million from a positive PLN 8.5 million in 9M 2023.
Operational highlights focus on the VR portfolio managed by Incuvo. Green Hell VR continues to expand with a co-op mode scheduled for release on December 16, 2024, following its addition to Meta Quest+ in June. Development of Project Bison, an internal IP, is progressing through the vertical slice phase with a planned 2025 premiere. Conversely, active development on Bulletstorm VR concluded in September 2024 following the version 1.4 update. The group’s total headcount remained stable at 767 employees, with a significant concentration of developers in Warsaw and North American studios.
- PCF Group reported a net loss of PLN 33.3 million for 9M 2024, widening from a PLN 13.4 million loss in the same period last year.
- Total revenue grew to PLN 131.9 million from PLN 111.3 million, driven by the release of Bulletstorm VR and increased Work-for-Hire activity.
- Adjusted EBITDA dropped to negative PLN 1.7 million, down from a positive PLN 8.5 million in 9M 2023.
- Profitability was hit by a PLN 7.8 million write-down for Project Red and margin compression on Project Gemini following contract amendments with Square Enix.
- Incuvo’s internal IP, Project Bison, is currently in the vertical slice phase with a scheduled premiere in 2025.