Showing 30 of 147 results · 0.28s
Jan 2022
Shooter Games
Newzoo
India, and utilizes a sample of over 19,000 active gamers to identify these behavioral and demographic trends
Report26 pages
Jan 2026
Reconnecting with Gen Z Mobile Gamers: UK
Bryter
Mobile gamers aged 18 to 24 represent a critical demographic for the UK gaming industry, characterized by high engagement levels but increasing volatility. While 79% of this cohort
Report10 pages
Jun 2020
Play Like a Girl: Key Ways to Engage Asia's Growing Female Gaming Audience
Niko Partners
each. Mobile technology serves as the dominant platform for this demographic, with 95% of Asia’s female gamers playing on mobile devices compared to much smaller shares
Presentation1 pages
May 2024
Gamers Have Become Less Interested in Strategic Thinking and Planning
Quantic Foundry
fundamental shift in player behavior rather than a result of demographic sampling bias. While core and hardcore gamers remain the primary focus of this study, the data indicates
Article1 pages
Nov 2025
Game Marketing: What Every Studio Needs to Know
Udonis
expansive, totaling approximately 3.3 billion players worldwide. Notably, the demographic is mature, with 80 percent of gamers being adults and the 18-to-34 age group representing
Article1 pages
Mar 2024
Analysis: The State of F2P Games on Nintendo Switch
GameDiscoverCo
serves as a value-add for a general demographic rather than a standalone destination for core gamers. While this shift provides consistent value for casual users and families
Article
Apr 2023
Sega's $776M Rovio Bid: Prickly Critters Team Up in Tough Mobile Market
SuperJoost
brands. Simultaneously, the market is expanding to include older demographics; research from the AARP identifies 52.4 million gamers aged 50-plus who contribute roughly $5 billion annually
Article
Nov 2024
Levelling Up: State of India Interactive Media & Gaming Research FY'24
Lumikai
weekly time spent, rising from 10 to 13 hours. Demographic data reveals a diversifying landscape where 44% of gamers are women and 66% reside in non-metro cities
Report15 pages
Feb 2026
Southeast Asia Gaming Consumer Economy
Telekom Malaysia, Twimbit
totaling US$5.57 billion. Urbanisation and a youthful demographic drive high willingness to spend, with 64 % of gamers willing to pay; average annual spend varies from
Report19 pages
Jan 2021
Games Marketing Insights for 2021
King
permanent expansion of the gaming audience, introducing a "new gamer" cohort that differs significantly from existing players in demographics and behavior. While existing players increased their time spent
Report24 pages
Mar 2024
State of Play: Spring Edition
Xsolla
Consumer behavior supports this shift, as 87% of multiplayer gamers now engage in cross-platform play. Younger demographics, specifically Gen Alpha and Gen Z, exhibit a 52% payer
Report49 pages
Jan 2019
Rapport Annuel 2019 Entertainment
ESAC – Entertainment Software Association of Canada
with more than 23 million Canadians identified as regular gamers through a 2018 NPD Group survey that captured demographic, console usage and purchasing patterns. The “Jeux vidéo
Report14 pages
Mar 2024
US Gaming Audience in 2023
Comscore
invest in premium content, with 45% of all gamers spending over $40 on their most recent purchase. The demographic profile of the U.S. gaming audience skews toward Millennials
Report26 pages
Jan 2022
State of Anime Gaming 2022
data.ai
illustrate cross‑regional appeal. Demographic profiling shows a strong Gen‑Z skew, with anime gamers on U.S. iPhones 217 % more likely to use Discord and 52 % more likely
Report19 pages
Aug 2026
How Do Brands Reach Gen Z Through Overwolf Ads?
Overwolf
serves as a critical channel for reaching this demographic, as nine in ten Gen Z respondents identify as gamers, spending between 6 and 12 hours per week playing
Article1 pages
Jul 2026
How Brands Can Reach Gen Z Gamers Without Disrupting Gameplay
Overwolf
Call of Duty. Rather than relying on broad demographic data, the methodology utilizes a deterministic targeting layer known as Gamer Grid. This system analyzes actual gameplay behavior, hardware
Article1 pages
Aug 2026
WEBTOON Is Bigger Than Monopoly Go: Inside a New Game Marketing Channel
Deconstructor of Fun
highly engaged audience that overlaps significantly with gaming demographics. With 156.9 million monthly global readers, 69% of whom are gamers, the platform provides a unique opportunity for publishers
Article1 pages
Jan 2021
Europe's Video Game Industry: Key Facts 2021
ISFE, EGDF
percent of the total European population. This demographic is increasingly diverse, with women accounting for nearly half of all gamers and the 45–64 age bracket emerging
Report19 pages
Jan 2024
The State of Gaming 2024
Sensor Tower
become more specialized, with TikTok attracting core gamers and Facebook remaining a stronghold for the female-skewing casual demographic. To mitigate rising costs, developers are increasingly leveraging intellectual
Report46 pages
Jan 2022
Southeast Asia’s Games Market
Niko Partners
viewers and gamers in the region. Approximately 60% of Southeast Asian gamers are strongly drawn to esports, and 42% are classified as competitive arena gamers. This interest
Report4 pages
Oct 2025
The Debrief: October 2025
Video Games Industry Memo
reporting the average age of a gamer is now 41. Furthermore, platform-specific research from Newzoo confirms that the user demographic for Roblox is aging alongside the platform
Article1 pages
Jan 2024
Study Report on African Video Games: Premier Results in Francophone Countries
The Game Hub Senegal
Cameroon, to assess current player demographics, awareness of locally produced titles, and the factors shaping market potential. By surveying 785 gamers between July and August 2023, the research
Report47 pages
Jan 2023
Misleading (Non-Core) Gameplay Ads Research 2023
Nexters
Wars, various "Scapes" games, and Evony. Demographic data reveals that the modern gaming audience is maturing, with nearly 10% of U.S. gamers over
Report15 pages
Jan 2012
Faits Essentiels 2012: Profil de l'industrie canadienne du jeu vidéo
ESAC – Entertainment Software Association of Canada
that 58% of Canadians identify as gamers, with an average age of 31. While 90% of children and adolescents play, the demographic is nearly balanced by gender, with
Report18 pages
Jan 2021
The State of Mobile Game Advertising 2021
Sensor Tower
optimize spend by matching network demographics to target audiences—YouTube for younger, male strategy players; Adcolony for older, female casino gamers—and by adopting emerging creative trends such
Report30 pages
Apr 2023
The 50-Plus Gamer of Today and Tomorrow
AARP
rate, transitions into this older demographic. Primary motivations for play center on mental acuity and passing time, with 70% of these gamers viewing play as an essential component
Report68 pages
Jan 2022
Consumer Insights: Games & Esports 2022
Newzoo
more likely to be "Ultimate Gamers" or "All-Round Enthusiasts." Even within the same genre, such as Battle Royale, player demographics and motivations vary significantly between titles like
Report18 pages
Jan 2020
The Past, Present and Future of Games
Newzoo
projected future states, emphasizing demographic shifts, monetization models, and technological convergence. It identifies a multi‑segment consumer base—ranging from “Ultimate Gamers” to “Time Fillers”—and quantifies engagement
Report33 pages
May 2022
Gaming Spotlight: 2022 Review
International Data Corporation
more inclusive player base. Female gamers and Gen Z cohorts are increasingly influential, serving as primary drivers of monetization and shifting the demographic focus of the industry
Report32 pages
Jul 2026
Farming Sims: Cultivating Long-term Engagement
Bryter
with 60% of mobile gamers having played at least one of the top ten farming sims. The genre’s success transcends casual demographics, attracting a broad audience that
Report13 pages
Shooter Games
Jan 202226 pages2k words
Summary
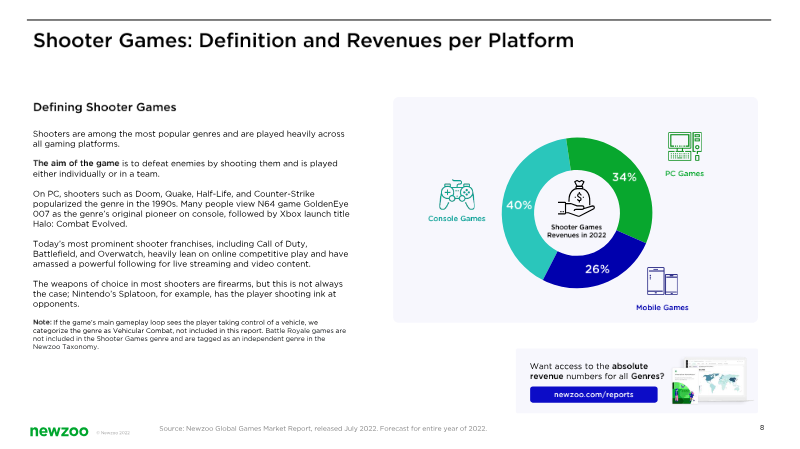
Shooter games represent the fifth highest-revenue generating genre globally as of 2022. This genre, defined by the primary mechanic of defeating enemies via firearms or projectiles, maintains a massive footprint across PC, console, and mobile platforms. While historical titles like Doom and Halo established the genre's foundation, modern success is driven by online competitive play and live streaming engagement. Notably, this analysis excludes Battle Royale and Vehicular Combat titles, which are classified as independent genres.
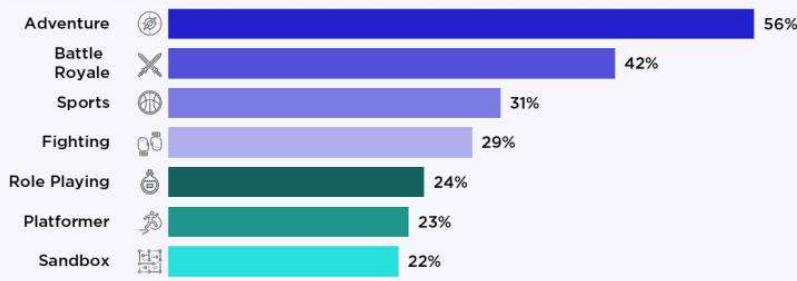
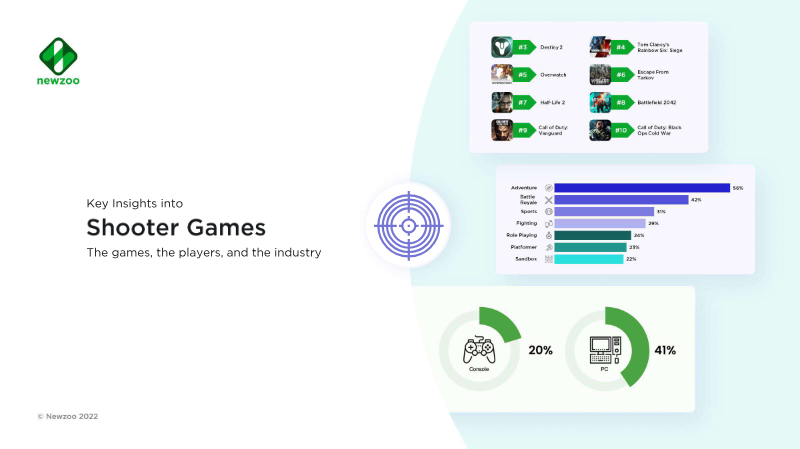
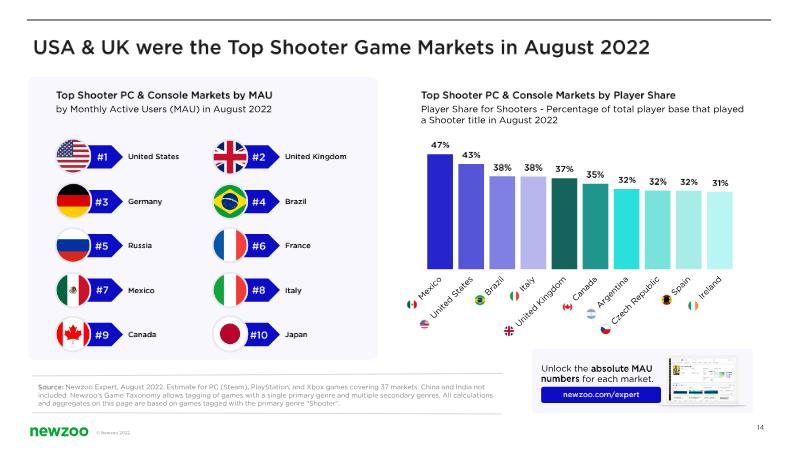
Data from August 2022 indicates that shooters command high engagement, ranking as a top genre for monthly active users on both Steam and consoles. The player base is predominantly male (63%) and young, with 38% of players falling between the ages of 10 and 20. High-intensity "Ultimate Gamers" and "All-Round Enthusiasts" show the strongest affinity for the genre, with 82% of the former group having played a shooter in the six months prior to the study. Beyond the core genre, shooter fans show significant cross-genre overlap with adventure and battle royale titles, while showing the least interest in simulation and strategy games.
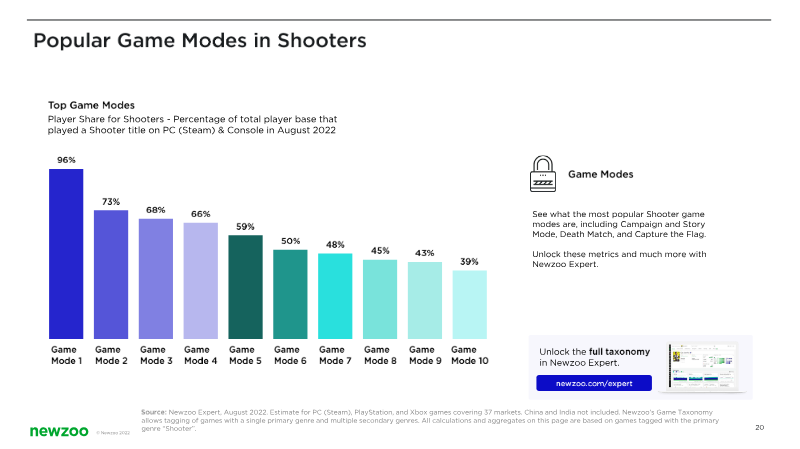
The genre's ecosystem is heavily influenced by specific themes and monetization strategies. Contemporary war is the most popular theme, utilized by 68% of the player base, while levels and maps remain the dominant gameplay mechanic. In terms of monetization, the market is characterized by a high prevalence of both pay-to-play models and in-app purchases, with 97% of players engaging with titles that feature microtransactions. Geographically, the research covers 37 markets, excluding China and India, and utilizes a sample of over 19,000 active gamers to identify these behavioral and demographic trends.
Pages
Insights
- Shooter games are the fifth highest-revenue generating genre globally, maintaining a massive footprint across PC, console, and mobile platforms as of 2022.
- Monetization is heavily driven by microtransactions, with 97% of players engaging in titles that feature in-app purchases.
- The player base is predominantly male (63%) and young, with 38% of players falling within the 10 to 20 age demographic.
- Contemporary war is the most popular thematic element, preferred by 68% of the shooter player base.
- Engagement is highest among 'Ultimate Gamers,' 82% of whom have played a shooter in the six months prior to the August 2022 study.
This image is a bar chart from a game industry report, illustrating the popularity of different game genres among players. It shows that "Adventure" is the most popular genre at 56%, followed by "Battle Royale" at 42%, and lists other genres like Sports, Fighting, Role Playing, Platformer, and Sandbox with their respective percentages of player preference.