Showing 30 of 80 results · 0.16s
Dec 2025
Esports 2023: Challenges and Opportunities in the UK
British Esports, Ukie
revenue streams but require regulatory clarity and infrastructure investment. Coordinated action across stakeholders is essential to unlock the UK’s full economic and cultural potential in esports
Report46 pages
Feb 2026
Southeast Asia Gaming Consumer Economy
Telekom Malaysia, Twimbit
highly spend‑active. eSports viewership is nascent but growing, with SEA tournaments ranking among the world’s most‑watched events; mobile eSports is expected to lead future growth
Report19 pages
Asia Pacific Market Report 2025: Creating Opportunities for Video Games in Asia
GamesBeat, Xsolla
Monster Hunter generating $215 billion in worldwide influence and $178.8 million in IP revenue, while mobile titles like Fate/Grand Order expand overseas earnings. The country’s mature domestic
Report36 pages
Jan 2022
Games, Esports, Live Streaming, Cloud and the Metaverse: 2022
Newzoo
posits that the sector is shifting toward an interconnected, cross-platform ecosystem where revenue diversification and creator-driven engagement models are essential for growth. While consumer skepticism persists
Report30 pages
Jan 2021
Newzoo Trends to Watch 2021
Newzoo
This analysis outlines the primary trends shaping the global games, esports, and mobile markets for 2021. The central thesis posits that while the COVID-19 pandemic accelerated engagement
Report23 pages
Jan 2022
Newzoo Trends to Watch 2022: Games, Esports, Live Streaming, Cloud and the Metaverse
Newzoo
The analysis projects that 2022 will be defined by a cautious expansion of emerging monetisation
Report30 pages
Jan 2022
Global White Paper on Mobile Advertising & Marketing Game
Tencent
driven by cross‑platform titles such as Genshin Impact and the rise of esports and metaverse expectations. Geographically, China’s HK/Macau/TW region maintained RPG dominance but broadened
Report106 pages
Jan 2020
Europe and Esports: High Engagement and Even Higher Potential
PayPal
study demonstrates that European esports audiences are expanding rapidly, with a projected 92 million viewers by the end of 2020 and a year‑over‑year growth
Report14 pages
Middle East & Africa Gaming Review 2025
Lucidity Insights
Legacy hardware sales remain a key revenue driver, with story‑rich single‑player titles and console sales generating multi‑billion dollar revenues. However, the rise of subscription models
Report52 pages
Jan 2020
Asia Spotlight Report: The Impact of COVID-19 on China’s Video Game Market in Q1 2020
Niko Partners
also forced a rapid evolution in industry operations, particularly within the esports and development sectors. Esports tournaments successfully migrated to online formats, supported by municipal government initiatives
Report21 pages
Jan 2025
Global State of Game Publishing & Marketing 2025 Industry Report
Epic Games
digital-first model, with digital sales accounting for 95% of total revenue. Marketing strategies now prioritize influencer partnerships and transmedia collaborations over traditional retail channels
Report46 pages
Jan 2020
For the Win: Breaking Down the Preferences of Asia's Mobile Gamers
Niko Partners
anime and manga aesthetics, with RPGs accounting for nearly half of its mobile revenue. South Korea leverages its robust 5G infrastructure and "PC bang" culture to sustain
Report22 pages
Jan 2021
Turkey Game Market 2021 Report
Gaming in Turkey
burgeoning esports ecosystem supported by approximately 6 million followers and a national federation overseeing 165 licensed clubs. Turkey’s selection as the host for the Global Esports Games
Report222 pages
Jan 2021
Newzoo’s Global Games Market Report 2021
Newzoo
This analysis explores the trajectory of the global games, esports, and mobile markets for 2021, forecasting a year of sustained engagement despite the easing of pandemic-related lockdowns
Report23 pages
Jan 2022
Key Insights Into French Gamers
Newzoo
France represents a significant gaming market, ranking seventh globally in terms of revenue and fifteenth in total player count as of 2022. The French gaming population is highly
Report18 pages
Jan 2021
The Gaming Playbook: Everything You Need to Know About the Gaming Audience
GWI
digital-first ecosystem where subscription services and digital sales dominate the market. Revenue models have transitioned accordingly, with in-game microtransactions and downloadable content emerging as the primary
Report39 pages
Jan 2025
Global Gaming Report Q2 2025
Drake Star Partners
billion. Deal distribution spanned mobile ($1.5 billion), PC/console ($0.8 billion), platform/tools ($0.4 billion), esports ($0.3 billion) and blockchain/VR‑AR ($0.2 billion). Key investors included CVC, Blackstone, Tencent
Report20 pages
Jan 2022
Key Insights Into American Gamers
Newzoo
United States represents the second-largest gaming market globally, generating $47.3 billion in revenue from a population of 191 million gamers. Research conducted in 2022 indicates that
Report11 pages
Jan 2021
Serbian Gaming Industry Report 2021
SGA
produced about 2,200 titles that generated an estimated US$125 million in revenue. The majority of earnings—between 75 % and 100 %—derived from markets outside the country
Report66 pages
Feb 2023
Japanese Esports on the Rise: Five Teams to Watch
Niko Partners
popular esports genres like MOBAs, recent policy shifts have transformed the landscape. Following the 2019 removal of most legal restrictions and the formation of the Japan Esports Union
Report15 pages
Jan 2022
Key Insights Into South Korean Gamers
Newzoo
South Korea represents the fourth largest gaming market globally by revenue, valued at $8.3 billion, with a highly engaged population of 33 million gamers. Research conducted
Report11 pages
Dec 2024
CESA Game Industry Report 2024
CESA – Computer Entertainment Supplier's Association
costs, employment, cross‑media context. | | Chapter 3 – User Trends | Player demographics, platform usage, esports, multi‑platform activity. | | Chapter 4 – CESA Activities & Member Initiatives | Overview of CESA‑hosted events
Report3 pages
Jan 2025
Yearly Live Streaming Trends Report 2024
Stream Hatchet
successfully attracted high-profile creators through non-exclusive contracts and aggressive revenue-sharing models. Geographically, the Asia-Pacific region remains the primary engine for mobile streaming growth, while
Report46 pages
Jun 2026
Vietnam Game Industry Monthly Report: May 2026
Gamota
Conversely, total in-app purchase (IAP) revenue grew by 3.13% month-over-month, with midcore revenue rising by 4.44%. This revenue expansion was driven primarily by long-lifecycle
Report23 pages
Mar 2026
Video Games Ecosystem Report: Cyprus 2025
InvestGame
Ludus, whose mobile titles have achieved multi‑million downloads and cross‑platform revenue streams exceeding $2 million. The mobile segment dominates, with Playrix, Easybrain, and Outfit7 leading
Report7 pages
Oct 2023
Leveling Up: State of India Gaming FY'23
Lumikai, Lumikai Investment Advisors
suspension of major titles like BGMI and Free Fire, as in-app purchase revenue for other titles grew by 37%. A survey of over 2,000 users reveals
Report12 pages
Jan 2022
Games India Plays!: A Look into the Gaming Habits of Indian Mobile Gamers and How to Reach Them
Newzoo
with 91% playing on mobile devices. Revenue for 2022 reached $2.2 billion, with RMG contributing over 50% of the total industry revenue in the preceding year. Demographic data
Report24 pages
Jan 2021
Video Game Streaming Trends Report: 2021 Yearly Report
Stream Hatchet
highlights 10 peak moments that drew record concurrent viewership, underscoring the influence of esports and mobile‑game tournaments. Demographic analysis shows a persistent gender imbalance: only
Report28 pages
Jan 2025
Asian & MENA Markets: 2025 Half-Year Report
Niko Partners
recalibrated growth, with total revenues across key sub-regions projected to reach significant milestones by 2025. China remains the dominant force, with revenues expected to hit $51.2 billion
Report3 pages
Jan 2020
The Past, Present and Future of Games: Global and Local Opportunities
Newzoo
accounting for 49% of global consumer revenues. Furthermore, the rise of cloud gaming is expected to generate $4.8 billion in revenue by 2023, supported by major infrastructure plays
Report33 pages
Esports 2023: Challenges and Opportunities in the UK
Dec 202546 pages30k words
Summary
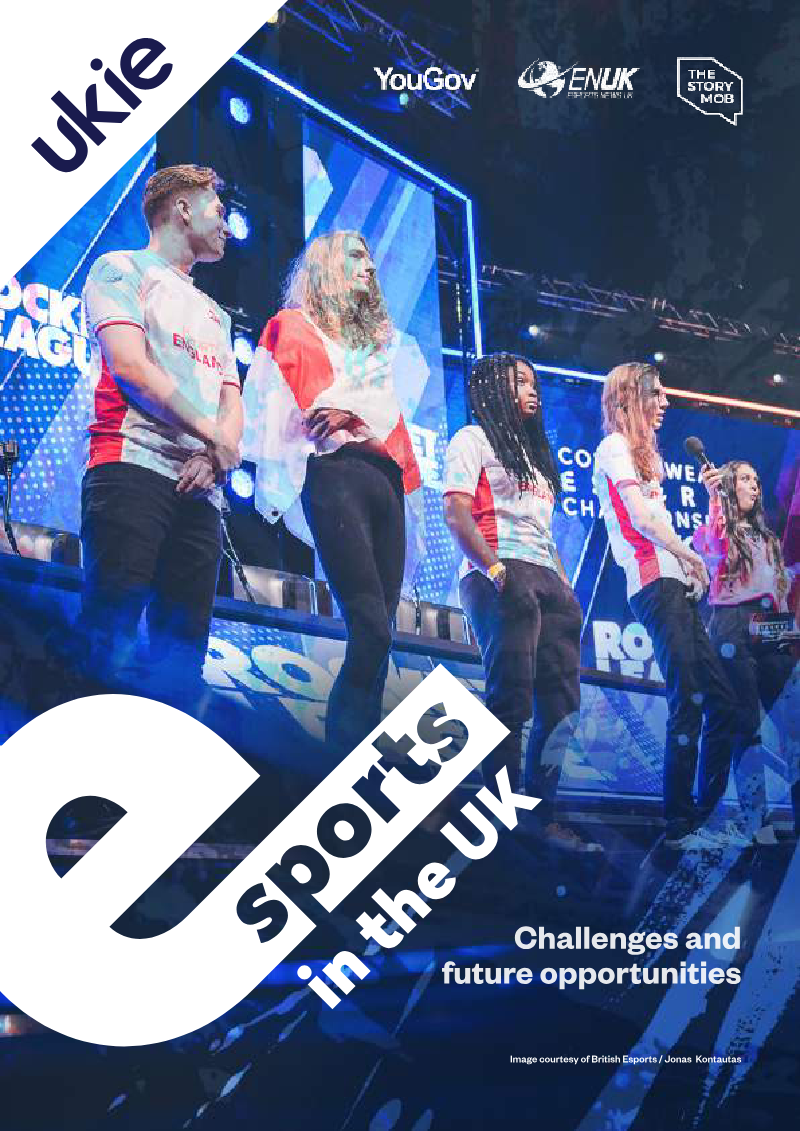
The report argues that the United Kingdom’s esports sector has evolved from a fragmented niche into a rapidly professionalised ecosystem, yet it still requires coordinated investment and policy to sustain growth. Key findings show an audience of roughly 55 million adults, with 82.7 % aged 18‑34 and a male dominance of 83 %. While shooters such as Call of Duty, CS:GO and Fortnite command the largest viewership, only 3.8 % of gamers follow competitive play, revealing a small “iceberg” of engaged fans. This gap highlights opportunities for talent development and global brand expansion, especially as the UK lags behind U.S. and Asian markets in producing top‑tier professionals.
Economic data underscore the sector’s momentum: gross value added reaches £111 million and sponsorship revenue exceeds $1.38 billion, with UK events and teams capturing a $1.5 billion share of the global market. Major brands—Intel, Red Bull, Saudi PIF—and tournament operators such as ESL, FACEIT and Gfinity are driving investment, while infrastructure projects by XLHQ, Royal Ravens and Cloud9 create dedicated studios and community hubs. Educational initiatives, including a BTEC programme with Pearson and university leagues like NUEL, demonstrate that esports can boost computing engagement and skill development among 10 000 pupils.
Despite these gains, challenges persist. Mainstream media coverage remains limited, and government support is uneven, constraining broader recognition of esports as a legitimate sport. Diversity and inclusion remain under‑addressed, with female participation at 17 % and a need for stronger links between education, industry and policy to create sustainable career pathways. Emerging monetisation models—Web3, NFTs, metaverse experiences—offer new revenue streams but require regulatory clarity and infrastructure investment. Coordinated action across stakeholders is essential to unlock the UK’s full economic and cultural potential in esports.
Pages
Insights
- The UK esports sector generates £111 million in gross value added, with UK-based teams and events capturing a $1.5 billion share of the global market.
- While the UK has a potential audience of 55 million adults, only 3.8% of gamers follow competitive play, indicating a significant opportunity for fan base expansion.
- The demographic profile of the UK esports audience is highly concentrated, with 82.7% aged 18–34 and 83% male, highlighting a need for improved diversity and inclusion efforts.
- Major investment is being driven by global brands like Intel, Red Bull, and the Saudi PIF, alongside infrastructure developments from organizations such as XLHQ, Royal Ravens, and Cloud9.
- Educational initiatives, including a Pearson BTEC programme and the NUEL university league, are currently engaging 10,000 pupils in computing and skill development.