ReportNewzoo
Rolling into the Southeast Asian Games Market: Sizing Opportunities in the World's Fastest Growing Region
16 pages~4 min full read
Key insights
6 slides
Market Size
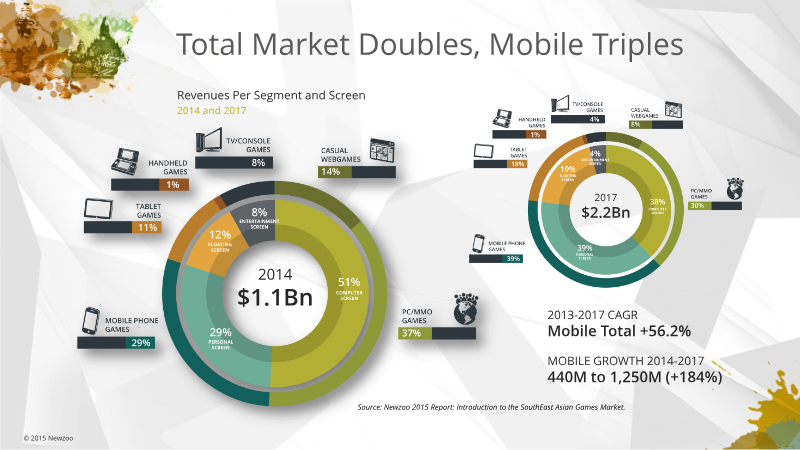
The Southeast Asian games market is projected to double in total revenue by 2017.
Total revenue is expected to increase from $1.1 billion in 2014 to $2.2 billion by 2017. This growth positions the region as one of the fastest-growing sectors in the global gaming industry.
Regional Scope
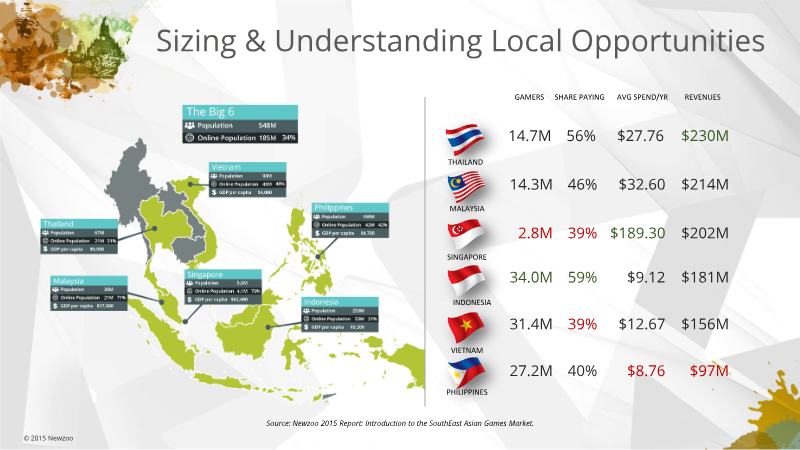
Six Southeast Asian countries represent a combined online population of 185 million people.
The 'Big 6' nations include Indonesia, Malaysia, Philippines, Singapore, Thailand, and Vietnam.
Mobile Dominance
Mobile gaming is the primary growth engine for the region, with revenues expected to triple.
Mobile revenues are projected to triple between 2014 and 2017. The total number of mobile gamers is also expected to grow significantly during this period.
Page 7 of the report184%
Projected growth in the total number of mobile gamers between 2014 and 2017.
- Mobile gamers in 2014
- 440 million
- Mobile gamers in 2017
- 1.25 billion
Market Share Shift
By 2017, mobile devices will dominate the market, accounting for 57% of total regional revenue.
PC/MMO games are projected to decline to 30% of the market share.
Fastest Growing
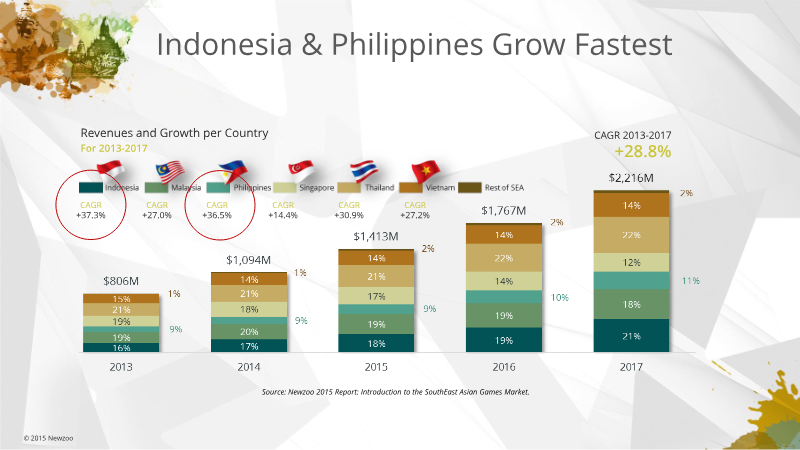
Indonesia and the Philippines are the fastest-growing markets in the region.
These two countries have projected CAGRs of 37.3% and 36.5% respectively between 2013 and 2017.
Spending Habits
Singapore maintains the highest average annual spend per gamer at $189.30.
This figure is significantly higher than the regional average. Singapore also has a high online population penetration rate of 75%.
1 / 6
Ask AI about this report