1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReport GAMEHEARTS
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReportGAMEHEARTS
The EU27 video games market generated €25.7 billion in 2023. 53% of Europeans aged 6 to 64, or 124.4 million people, play video games.
The GAMEHEARTS D4.1 EU/Comparative Policy Report examines how video game regulation varies across Europe and measures national approaches against EU governance principles. Its scope covers Austria, Finland, the Netherlands, Poland, and the United Kingdom, with the EU27 market as context. The EU27 video games market generated €25.7 billion in 2023, and 124.4 million Europeans, or 53% of those aged 6 to 64, play video games. The analysis draws on desk research and fifteen stakeholder interviews totalling 542 minutes, and its central thesis is that while unified EU frameworks exist in areas such as consumer protection and data protection, fragmentation across member states continues to create compliance burdens for developers and uncertainty for parents.
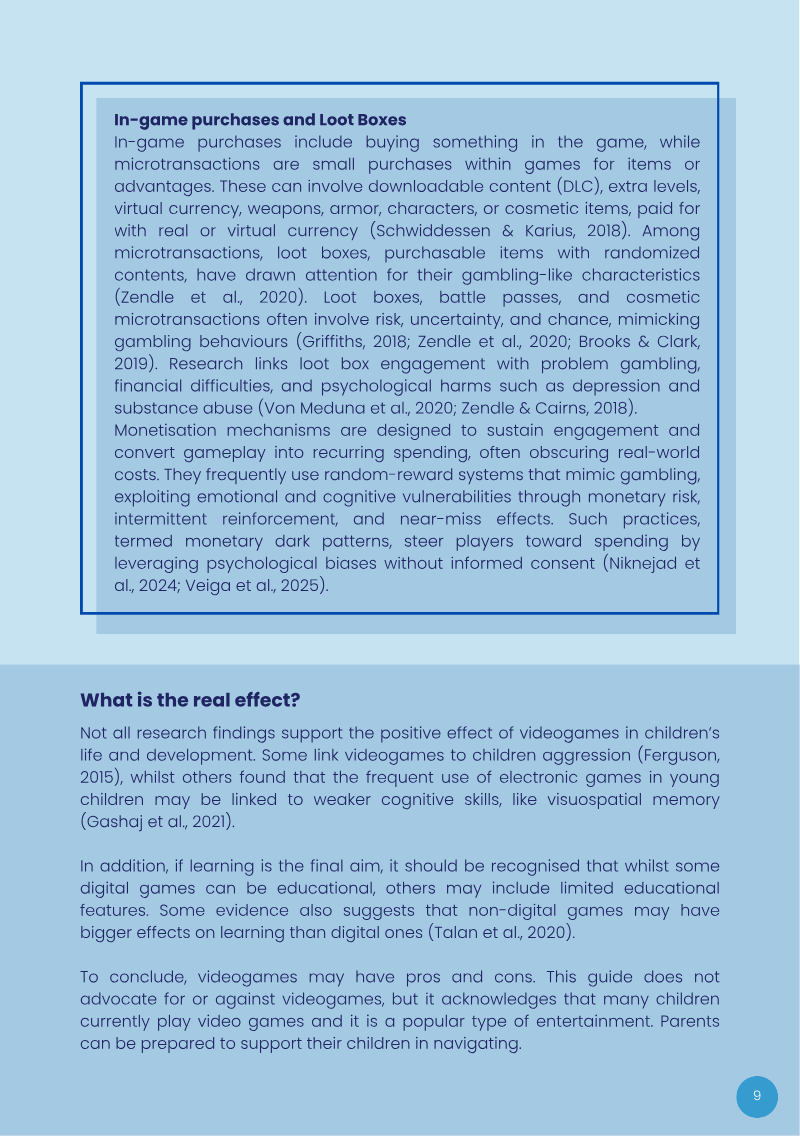
The report's most prominent findings concern loot boxes, minors' online safety, and data protection. Approaches diverge sharply: the Netherlands treats loot boxes as gambling under a vague "open norm" definition, Belgium applies a gambling classification, and the UK has relied on industry self-regulation after a 2020 DCMS inquiry, with compliance on probability disclosure found to be inconsistent. The PEGI age-rating system is widely adopted, used in 40 countries and recognised by 79% of parents, yet enforcement varies, and major storefronts do not consistently display ratings. Data protection enforcement is similarly uneven, with France's CNIL described as strict while other states are more lenient, and the national age-of-consent threshold differs from the GDPR baseline in Austria.
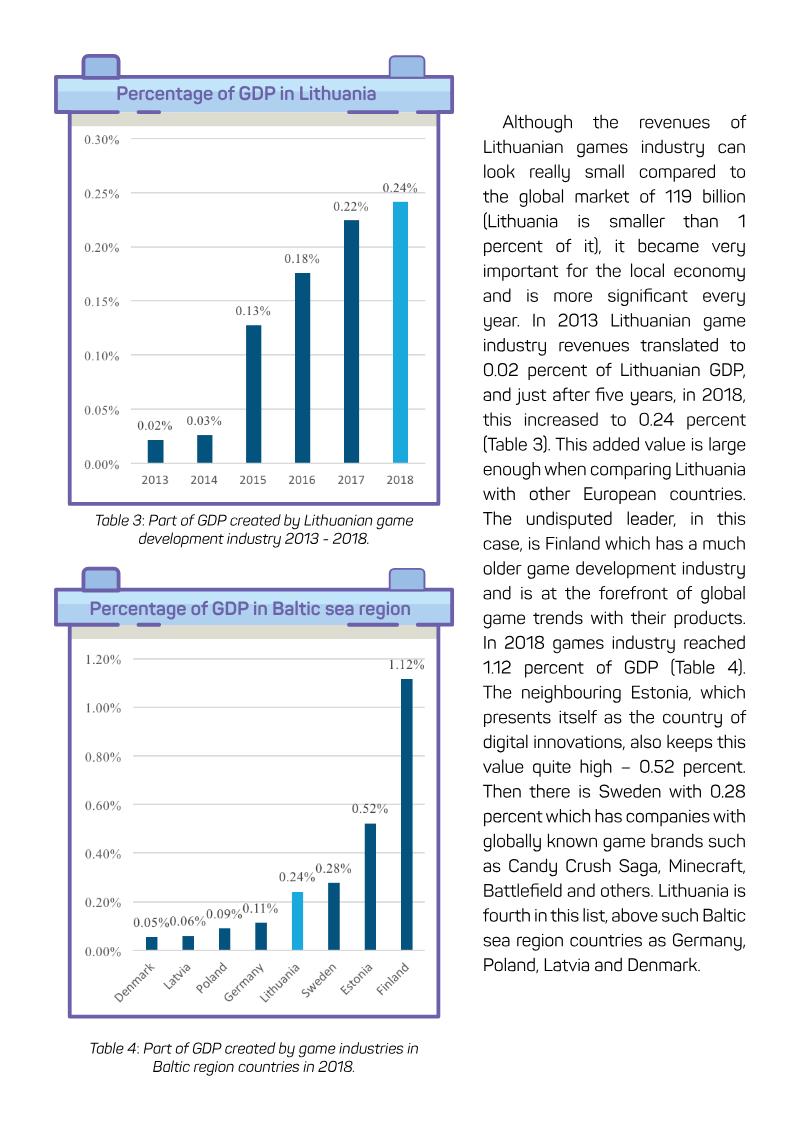
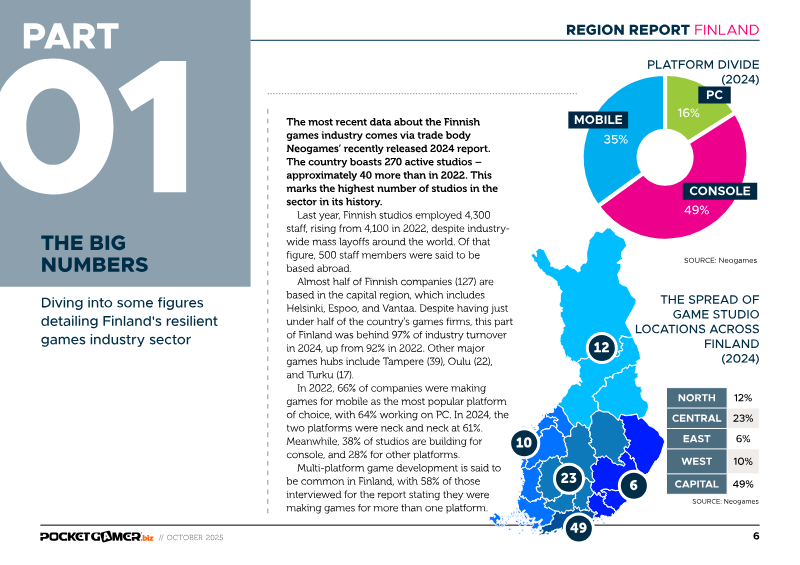
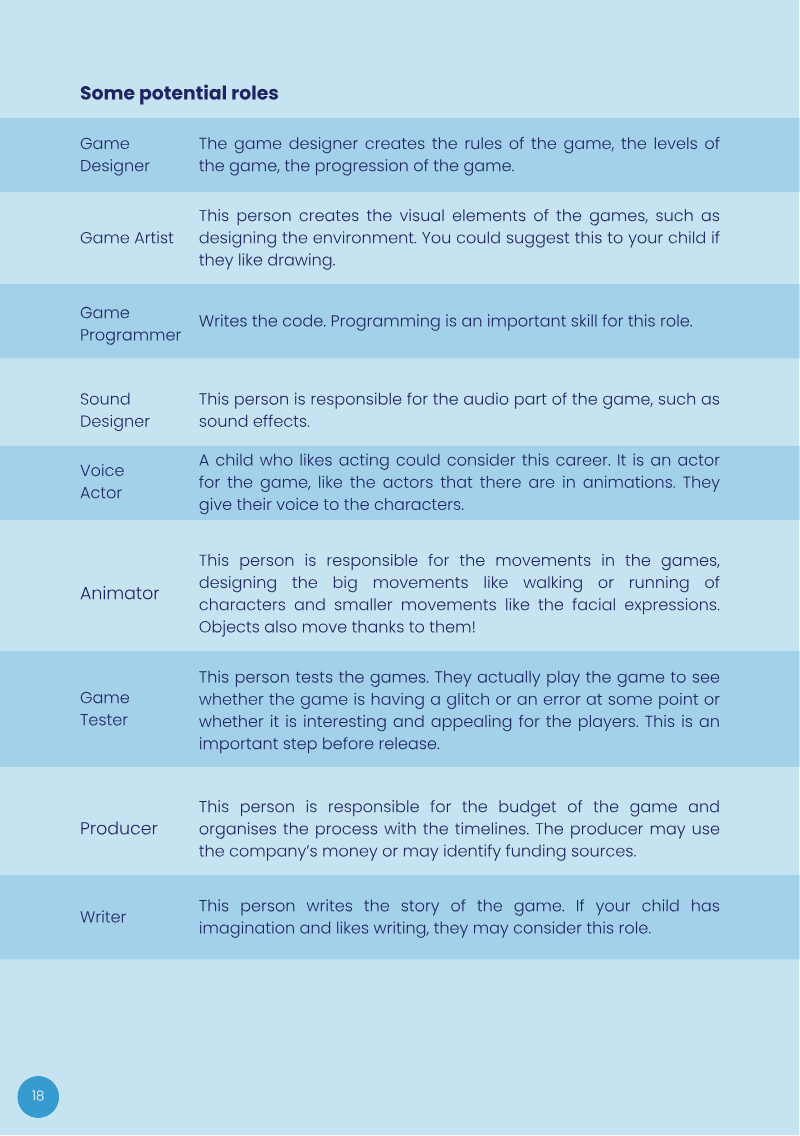
On workforce and industry conditions, the report identifies persistent gaps. Women make up only 24.4% of the European industry workforce, and no European country exceeds 30% female employment, though Dutch representation rose from 13.5% in 2012 to 23% in 2021. Finland reports a shortage of senior talent despite many educational programmes, and the UK faces funding challenges following the end of the UK Games Fund. Poland stands out as the second-largest European gaming market, with roughly 20 million gamers and growth of 23 to 37% annually since 2017.
The report concludes that no single regulatory approach is likely to work consistently across member states. It favours harm-reduction measures such as spending limits and probability disclosure over outright bans, and it recommends a unified EU framework for loot box regulation, structured dialogue between industry and regulators, and stronger digital literacy and youth protection. It argues that
GAMEHEARTS · 2026
GAMEHEARTS · 2026
GAMEHEARTS · 2026
GAMEHEARTS · 2026
GAMEHEARTS · 2026
GAMEHEARTS · 2026
GAMEHEARTS · 2025
GAMEHEARTS · 2025
GAMEHEARTS · 2025
GAMEHEARTS · 2025
GAMEHEARTS · 2025
GAMEHEARTS · 2025
DiGRA · 2026