Investment reports and market data
Documents
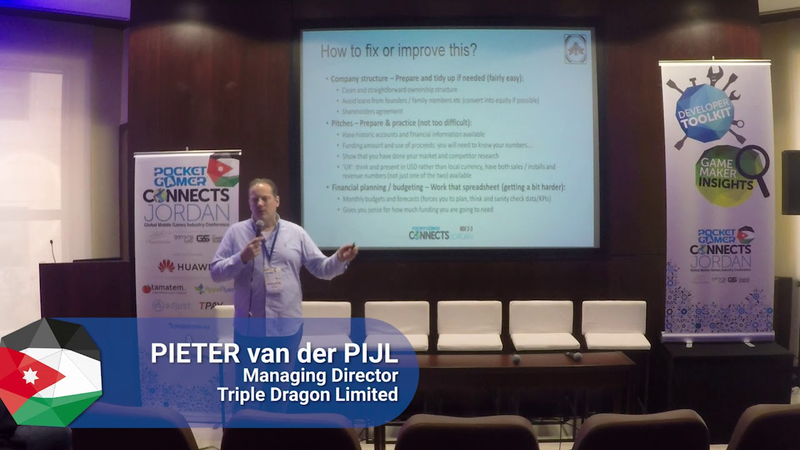
How to Organise a Business
This analysis outlines the essential requirements for game developers seeking investment, focusing on the necessity of professional business organization and data-driven decision-making.
- Securing investment requires transitioning from a creative-only mindset to a disciplined, analytical business model that prioritizes scalability and profitability.
- Studios must demonstrate financial rigor by maintaining clean legal entities, clear ownership structures, and comprehensive, month-by-month operational budgets.
- Investors evaluate project risk and scalability primarily through unit economics, specifically the relationship between Lifetime Value (LTV) and Cost Per Acquisition (CPA).
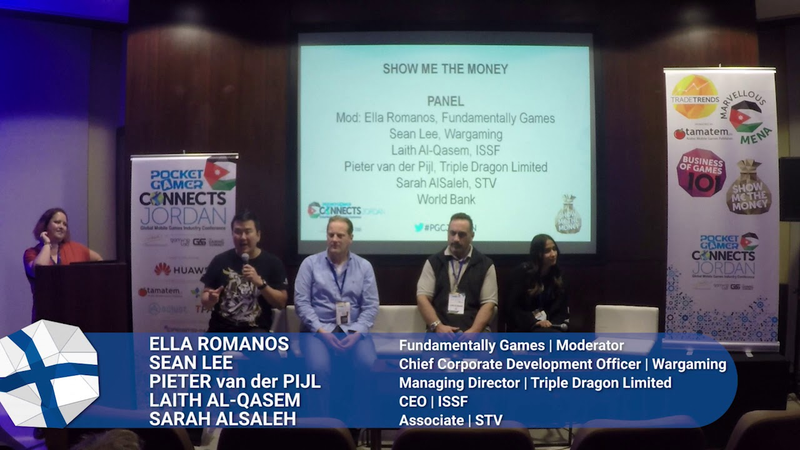
Panel: Inside the Dragons Den - How to Talk to Investors
Securing investment in the gaming industry requires a fundamental shift in perspective, moving away from a singular focus on game design toward the development of a scalable, institutionally managed business.
- Investors prioritize the founding team's management capability, cohesion, and commercial foresight over the specific merits of a single game design.
- To secure institutional funding, studios must transition from project-based entities into scalable, professionally managed businesses with robust organizational structures.
- Fundraising is a multi-month process that requires early engagement with investors well before capital reserves are depleted to ensure sufficient runway for prototyping.
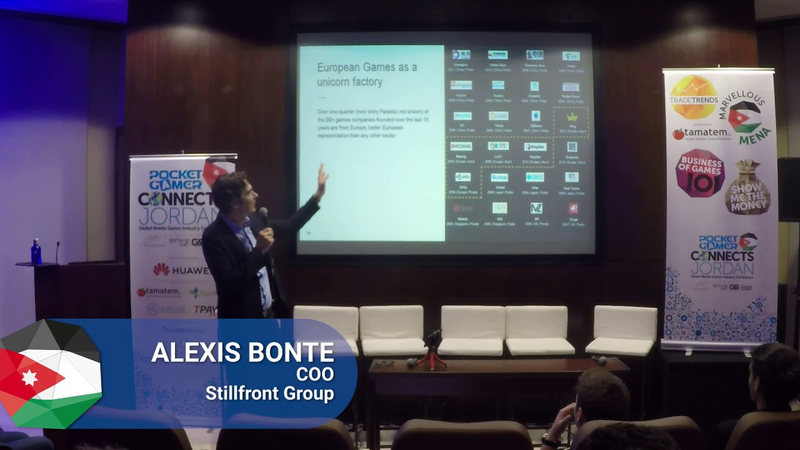
Hunting for the Next Supercell
The gaming industry represents a massive, high-growth global market, currently valued at approximately $140 billion.
- The global gaming industry is a $140 billion market driven by 2.2 billion active gamers accessing content through major distribution platforms like the iOS App Store and Google Play.
- Game studios often achieve profitability within their first few years of operation, offering higher cash efficiency and lower capital dilution compared to typical tech startups.
- Investment strategies prioritize the development of 'evergreen' titles capable of generating stable, long-term revenue, with successful breakout hits frequently yielding returns exceeding 10x.
Workshop: Pitch Perfect
Securing investment in the gaming industry requires a strategic shift in focus depending on the company’s maturity and the specific funding model pursued.
- Investors prioritize the management team’s execution capability and character over the specific game concept, looking for evidence of organizational tenacity and the ability to manage a title's full lifecycle.
- Fundraising must be treated as an iterative, multi-stage process where developers transition from project-based financing for early development to a long-term business vision for venture capital scaling.
- A successful pitch must balance creative vision with data-backed market viability, demonstrating a clear and sustainable path to generating significant financial returns.
AI's Ever-Growing Presence in Gaming: $1.8B in VC Investments
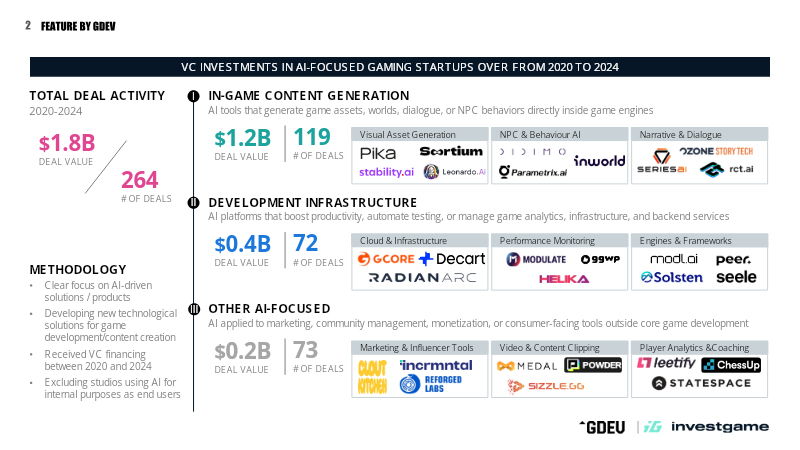
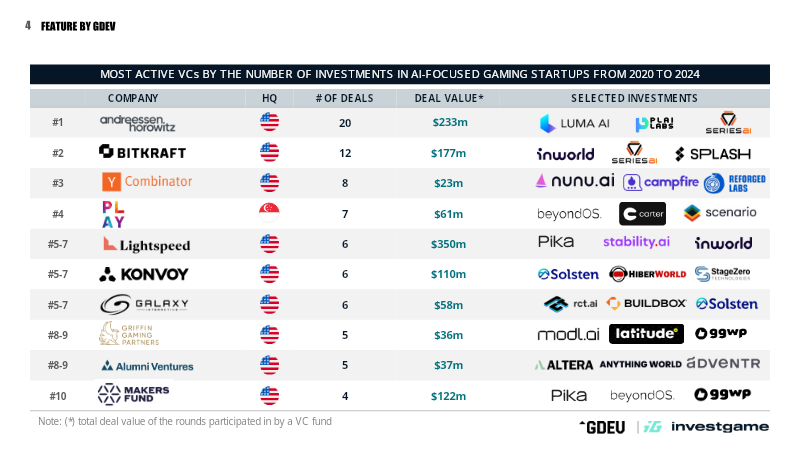
Venture capital investment in AI-focused gaming startups has experienced significant growth, totaling $1.8 billion between 2020 and 2024.
- Venture capital investment in AI-focused gaming startups reached $1.8 billion between 2020 and 2024, with deal value growing at a 35% compound annual rate from 2022 to 2024.
- AI-focused startups now account for approximately 65% of all gaming infrastructure deal activity, reflecting a strategic pivot toward specialized verticalized tooling over general platform investments.
- In-game content generation tools lead the market with $1.2 billion in funding across 119 deals, followed by $0.4 billion for development infrastructure and $0.2 billion for marketing and analytics.
Investment Activity Report Q1–Q3 2020
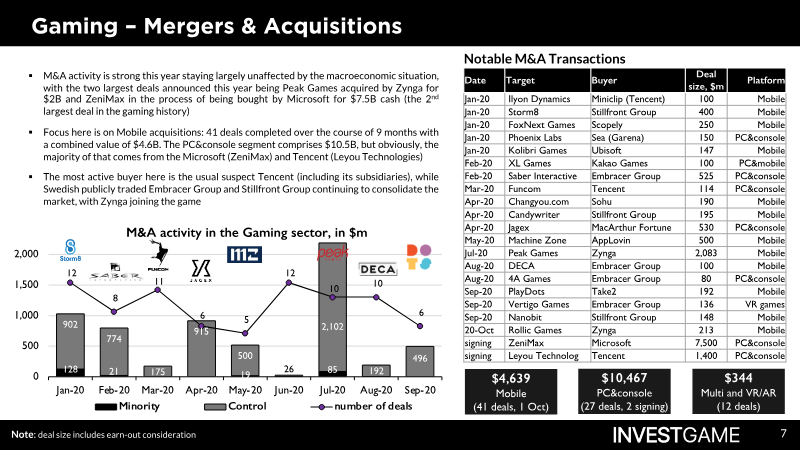
The report documents investment activity in the global gaming industry from January to September 2020, covering mobile, PC & console, multiplatform, VR/AR, cloud-native and esports segments.
- The global gaming industry saw $27.5 billion in total deal value across 1,000 transactions during the first nine months of 2020, with gaming-specific deals accounting for $15.3 billion.
- M&A activity was defined by large-scale consolidation, led by Microsoft’s $7.5 billion acquisition of ZeniMax and Zynga’s $2 billion purchase of Peak Games, with Tencent, Zynga, and Microsoft collectively exceeding $11 billion in deal value.
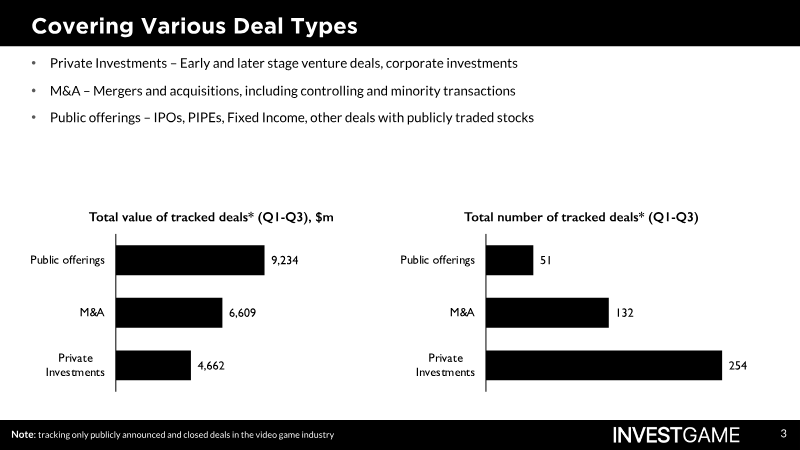
- Public offerings were the primary driver of capital, generating $9.2 billion from 51 IPOs and PIPEs, while private venture investments contributed $4.7 billion across 254 rounds.
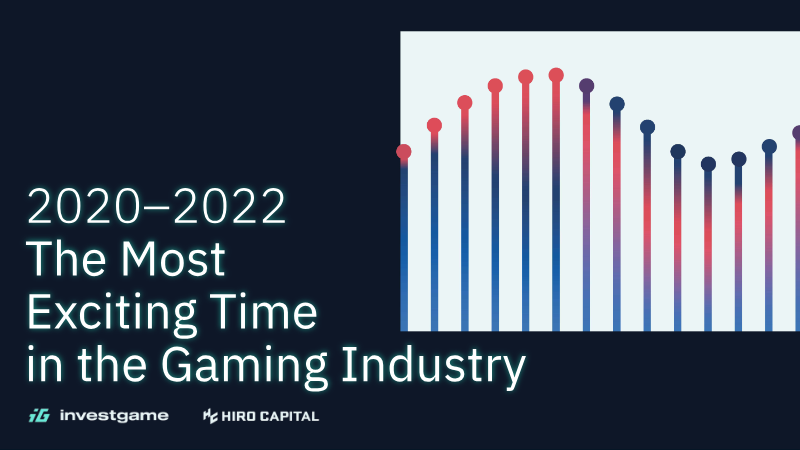
The Most Exciting Time in the Gaming Industry: 2020–2022
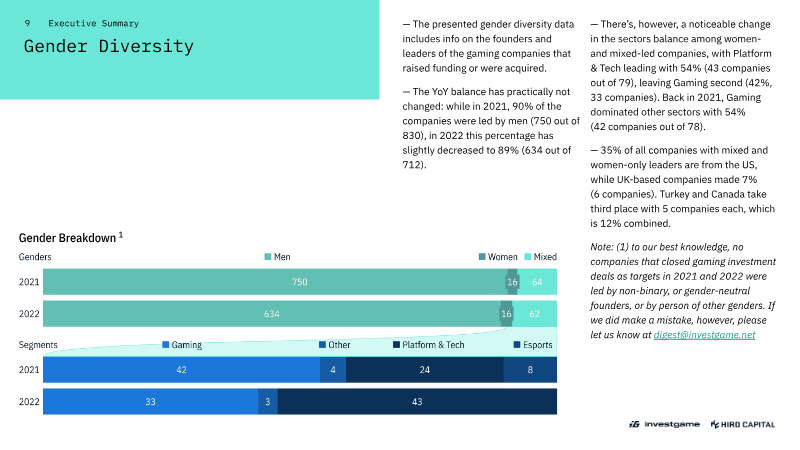
The analysis demonstrates that the gaming sector experienced a pronounced surge in deal activity between 2020 and 2022, with private equity investments peaking at $12 billion in 2021 before receding to $10.1 billion the following year.
- The gaming industry experienced a massive investment peak in 2021, with M&A reaching $41 billion, private equity hitting $12 billion, and public offerings peaking at $24.5 billion.
- Market activity cooled significantly by 2022, with public offerings collapsing to $4.6 billion and late-stage transaction values dropping four-and-a-half-fold to $0.9 billion in early 2023.
- Strategic acquisitions remain a primary driver of industry value, with the top 15 M&A deals—led by Microsoft’s purchases of Activision Blizzard and ZeniMax—accounting for approximately 80% of total announced deal value.


InvestGame Deals Report 2020 – Game M&A
The 2020 Game M&A landscape reached a record $33.6 billion in transaction value across 664 deals, with public offerings contributing 45% of the volume and $15.1 billion in 2020 alone, while M&A activity totaled $12.6 billion (potentially $22.2 billion when including recent mega-deals).
- The 2020 gaming market hit a record $33.6 billion in total transaction value across 664 deals, driven by $15.1 billion in public offerings and $12.6 billion in M&A activity.
- Tencent, Embracer, Stillfront, and Zynga emerged as the dominant market forces, collectively accounting for 60% of the total M&A value.
- The United States led the global market by capturing 36% of total deal value and hosting four of the year's top-10 largest transactions.
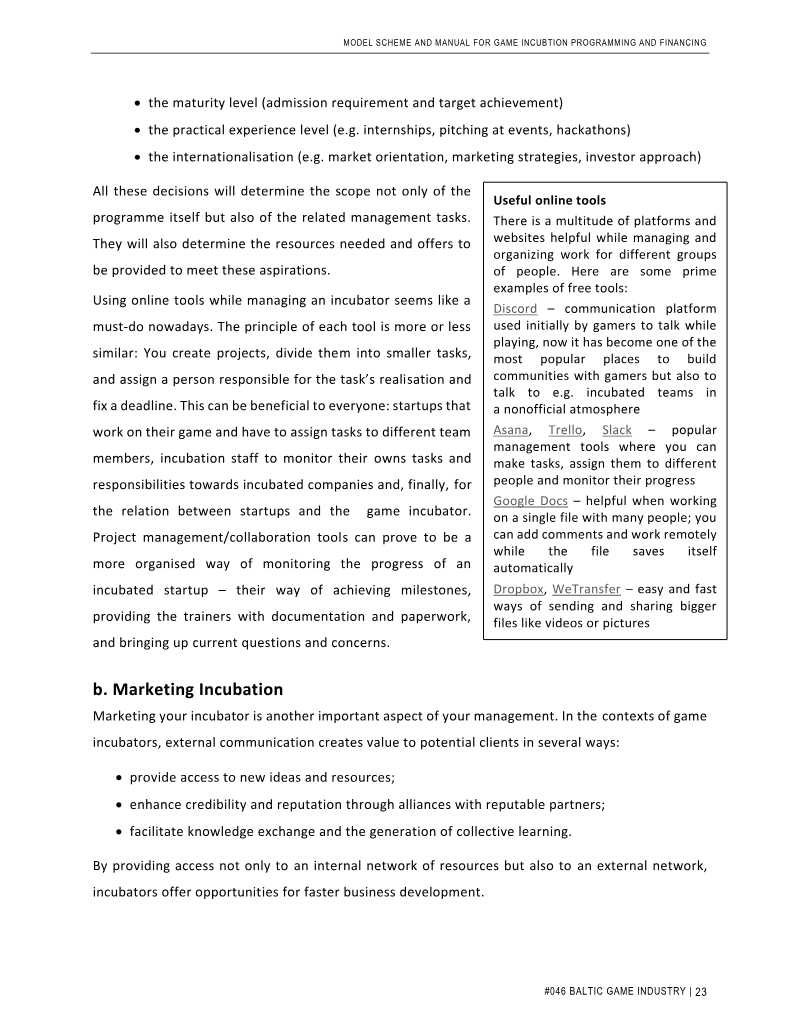
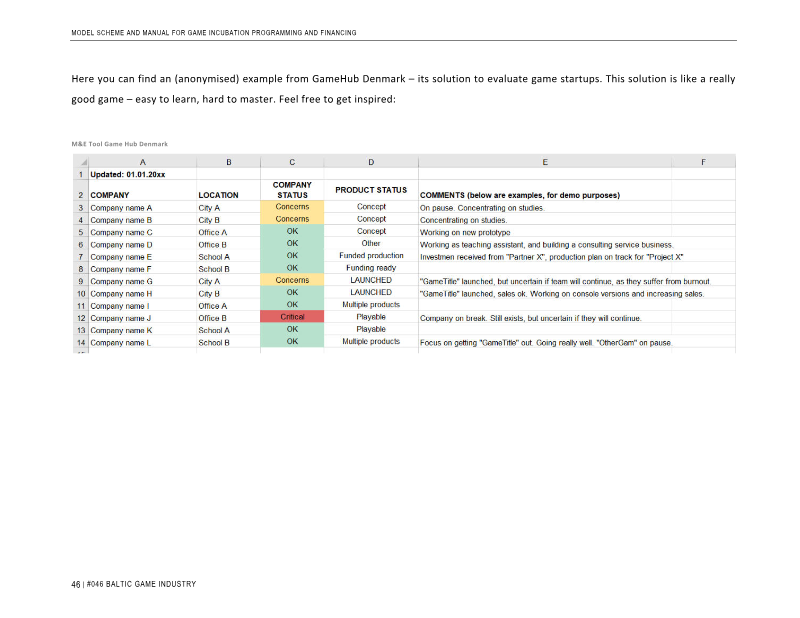
Model Scheme and Manual for Game Incubation Programming and Financing: Baltic Games Industry
The Baltic Sea region is currently undergoing a strategic transformation aimed at establishing itself as a globally competitive hub for game development.
- Most game incubators in Europe, especially those for game creators, are primarily funded by public sources, with private initiatives being a minority.
- Establishing a sustainable game incubator often takes over 5 years to break even, with only 40.8% of business incubators aiming to break even as part of their business plan.
- Game incubation programs can be structured in various ways, including long-term incubation (1 year+ for medium-maturity startups) and short-term acceleration (3-4 months for high-maturity startups, often involving equity exchange for funding).
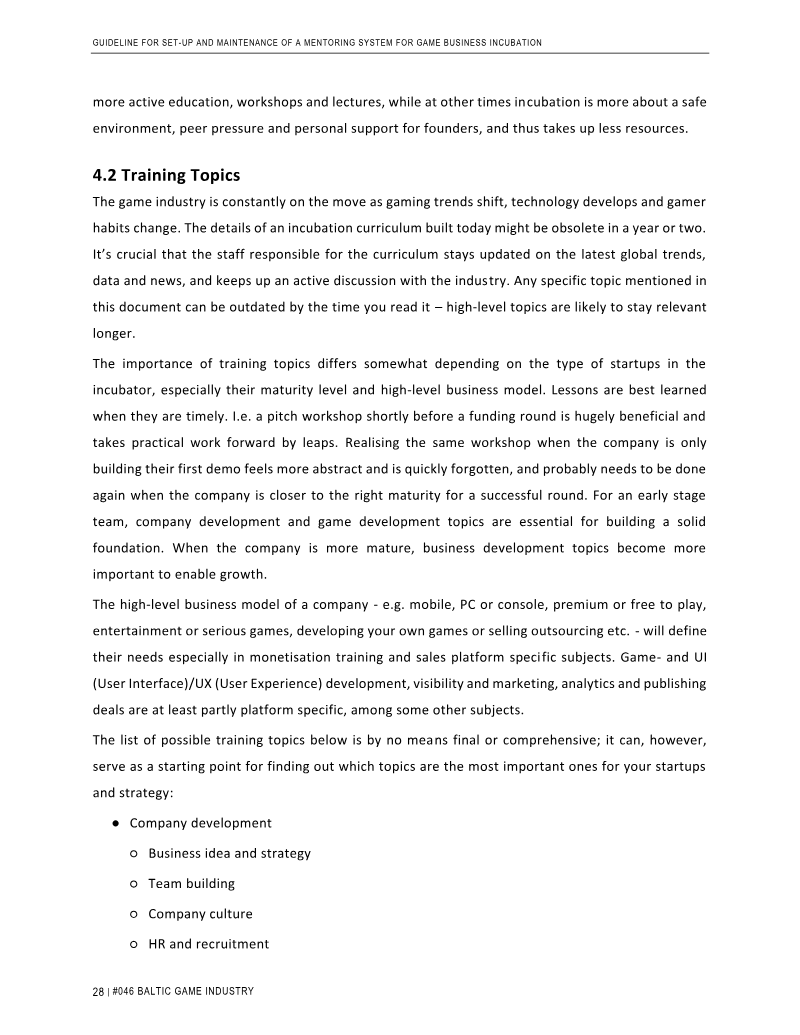
Guideline for Set-Up and Maintenance of a Mentoring System for Game Business Incubation
Establishing and maintaining a successful game business incubator requires a specialized framework that addresses the unique, multidisciplinary challenges of the gaming sector, such as rapid market volatility and complex monetization strategies.
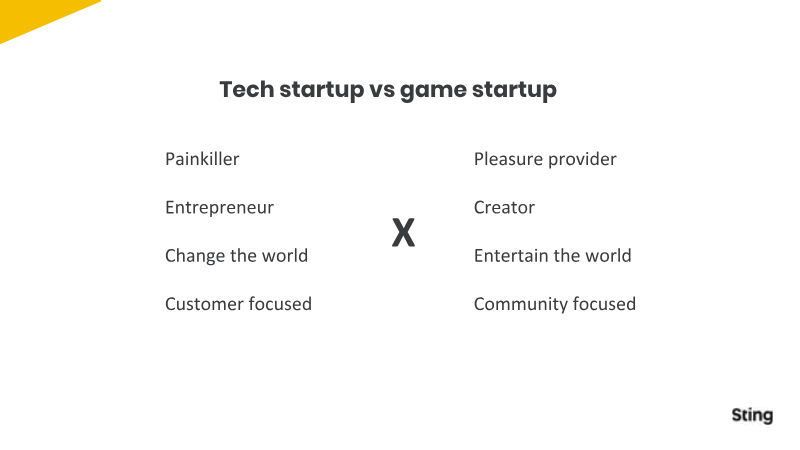
- The game industry is highly competitive and unique, with revenues exceeding three times that of the movie industry, requiring specialized incubation support distinct from generic tech incubators.
- Effective game incubation systems need to tailor their offerings based on the local startup ecosystem, considering factors like founders' experience (e.g., fresh graduates vs. industry veterans) and community focus (e.g., hobby developers needing business skills).
- Mentoring in game incubation involves a continuous, supportive relationship with experienced industry professionals, ideally based on a flexible long-term development plan, and requires mentors with strong communication, listening, and industry understanding.
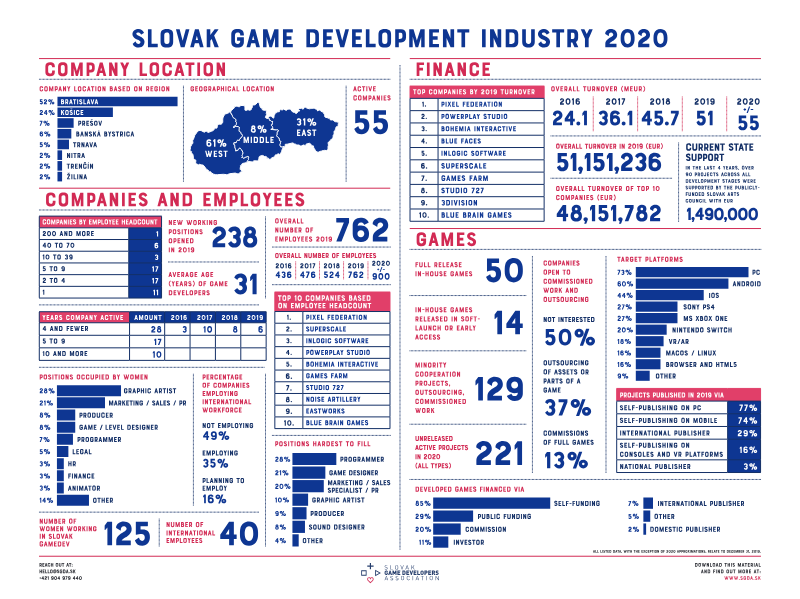
Slovak Game Industry Infographic
The Slovak game industry demonstrates consistent growth and professional maturation, characterized by a robust increase in both turnover and workforce capacity.
- The Slovak game industry experienced significant workforce expansion between 2016 and 2019, growing from 436 to 762 employees.
- The top ten companies in the sector generated over 48 million euros in annual turnover as of 2019.
- The industry is geographically concentrated, with 52 percent of the 55 active companies based in Bratislava and 24 percent in Košice.
White Paper on Spanish Video Game Development 2020
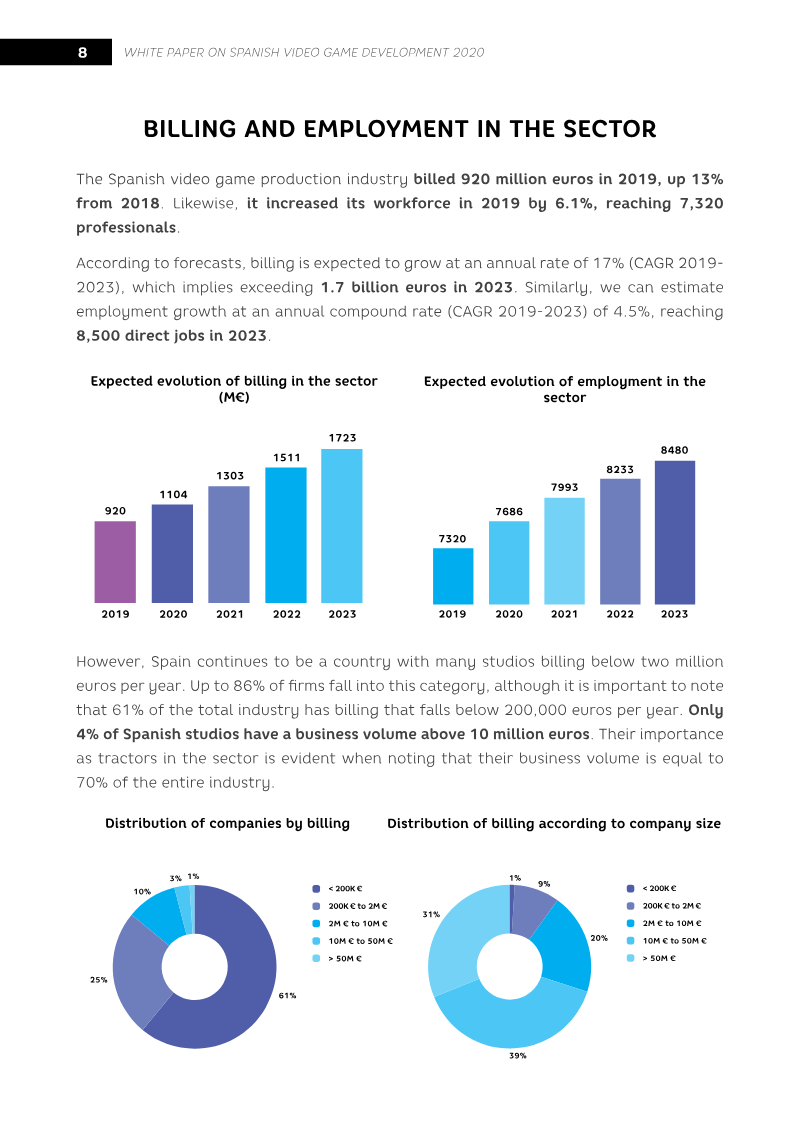
The Spanish video game industry represents a robust and expanding economic sector, generating 920 million euros in revenue and employing 7,320 professionals as of 2019.
- The Spanish video game industry billed 920 million euros in 2019, a 13% increase from 2018, and is projected to exceed 1.7 billion euros by 2023 with an annual growth rate of 17%.
- Employment in the sector grew by 6.1% in 2019, reaching 7,320 professionals, and is estimated to reach 8,500 direct jobs by 2023.
- Despite being the fifth European and tenth global market, 86% of Spanish studios bill below 2 million euros annually, with 61% billing under 200,000 euros, indicating a prevalence of small companies.