Showing 30 of 463 results · 0.68s
Jan 2021
Mobile Game Genre Report: Comparing & Contrasting Eastern and Western Markets
Newzoo
capturing over 21% of the global market share. This financial success is heavily concentrated in East Asia, specifically China, Japan, and South Korea, which collectively account
Report30 pages
Jan 2019
Tencent Games Strategy 2019
Niko Partners
cloud network that already supports 75% of China’s top mobile games, Tencent is positioned to lead the domestic market in the absence of major international competitors. With
Report14 pages
Jan 2023
Global Gaming M&A Landscape: 2023 Edition
Lu Weiming
value from 2022 peaks. Conversely, the Chinese market experienced a protracted decline, reaching its lowest activity levels since 2010. China recorded only 29 transactions in 2023, a sharp
Article
Mar 2026
Brutally Honest #92: UA in the Post-IDFA World
Matej Lancaric
focus on the Chinese and Western mobile markets during late 2023. Key findings highlight a significant regulatory shift in China, where new government mandates targeting loot boxes
Article
Jan 2023
From Hyper to Hybrid in 2023
Tenjin
Mexico remain the top five Android install markets in both 2022 and H1 2023, while iOS installs shift from China and Japan in 2022 to Canada and Germany
Report11 pages
Oct 2026
Russia’s Video Game Strategy
Video Games Industry Memo
mirrors professional development frameworks seen in other global markets, its implementation is complicated by the ongoing threat of restrictive, China-style regulatory legislation. Ultimately, the industry faces
Article1 pages
Jan 2021
Innovate to Win on the Next Level with Hybrid Genre Games
data.ai
since 2018, a trend largely spearheaded by China-based publishers who now command a 23% share of the international market. To sustain this trajectory, the industry is shifting
Report52 pages
Jan 2022
Podcast: Dread Hunger's James Tan Talks the Hit Social Deduction Game
GameDiscoverCo
social deduction. While the developers initially focused marketing efforts on Western audiences, the title achieved massive viral growth in China following its 1.0 launch. This expansion was driven
Article
Jan 2024
Palworld, the Equal-Opportunity Offender
SuperJoost
these comparisons has become part of its marketing narrative. Its global appeal is further evidenced by its performance in China, where it became the fourth most popular title
Article
Jan 2025
Games Industry Region Report: China 2025
PocketGamer.biz
China maintains its position as the world’s most lucrative and influential gaming market, generating $48.7 billion in total revenue during 2024. While the domestic landscape has faced
Report20 pages
Jan 2022
Global Games Market Report 2022
Newzoo
play and industry consolidation. Regulatory shifts in China have also prompted a strategic pivot toward global expansion in other emerging markets. As the industry evolves, success will likely
Report61 pages
Jan 2025
Take Rates in China: Will Quality Development Beat Out Traditional Distribution?
Niko
cost of doing business. However, the rise of direct distribution and community-centric marketing signals a broader trend where quality content and brand loyalty are becoming more influential
Report10 pages
Jan 2021
Go Global Mobile Game: New Insights
data.ai
During the first half of 2021, China-headquartered publishers ascended to the global leadership position in the mobile gaming market, capturing 23% of overseas consumer spend. This
Report52 pages
Feb 2025
NVIDIA Annual Report: Form 10-K FY2025
NVIDIA
high-performance AI semiconductors, particularly those targeting China and other regions, necessitate ongoing product adaptations and create significant uncertainty regarding market access and supply chain stability. Furthermore
Financial1 pages
Feb 2023
Japanese Esports on the Rise: Five Teams to Watch
Niko Partners
video game superpower into a significant esports market, overcoming historical regulatory and cultural hurdles. While the country previously lagged behind China and South Korea due to strict anti
Report15 pages
Jan 2026
Six Video Games Industry Predictions for 2026
Video Games Industry Memo
defining event for the market. Beyond individual blockbuster titles, the industry is shifting toward a landscape where China emerges as the dominant global power. Strategic trends
Article1 pages
Jun 2026
May's Top PlayStation Games by Copies Sold
Alinea Analytics
players in North American and Western European markets compared to the Steam version, which maintains a significant user base in China. Evergreen titles continue to anchor the platform
Article1 pages
Feb 2022
Deep Dive: How Astroneer Made It to 8 Million Players
GameDiscoverCo
representing 70% of total sales. Geographically, the market is led by the United States at 36% of purchasers, followed by China at 9%. The developer attributes this sustained
Article
Aug 2023
Your Early Access Launch Is Your Launch
GameDiscoverCo
Beyond Steam metrics, the scope includes global console market share data from 2019 to 2021 derived from UK Competition & Markets Authority filings. This data highlights the growth
Article
Jan 2015
Fiscal Year Ending March 2016: 1st Half Financial Results
Koei Tecmo
Online & Mobile segments. Although Japan remains the primary market, accounting for 74.9% of sales, the Asian market showed the most aggressive growth, with sales increasing
Financial34 pages
Aug 2023
Video Games Industry Memo: 17 August 2023
Video Games Industry Memo
global gaming policy, corporate finance, and market trends as of August 2023. The primary focus is a critical evaluation of China’s 2019 mandate to limit gaming time
Article
Jan 2025
China Game Industry Report 2025
Meridian Play
China Game Industry Report for 2025 presents a comprehensive assessment of the domestic and overseas gaming markets, highlighting sustained growth driven by youth protection initiatives, technological innovation
Report13 pages
May 2026
Form 10-Q: Q1 FY2026
NVIDIA
connected vehicles, open‑source models from China, and Chinese data‑center standards could further curtail revenue in automotive and data‑center markets. Potential supply disruptions from Taiwan
Article1 pages
May 2017
Current Report No. 31/2017: Agreement on Distribution of Agony and Car Mechanic Simulator 2018
PlayWay
United Kingdom, France, Italy, Japan, China, and Canada. In addition to logistics and sales, the distributor is tasked with managing marketing initiatives to support the commercial performance
Legal2 pages
Jan 2023
Global Games Market Report: August 2023
Newzoo
strong console demand in Western markets contrasts with slower growth in the Asia-Pacific region, where regulatory challenges in China continue to dampen momentum. To mitigate rising production
Report52 pages
Mar 2019
Gaming Spotlight 2018 Review
data.ai, International Data Corporation
freeze on new game approvals in China. In North America, the Nintendo Switch drove strong home console performance, while the handheld market faced contraction as franchises like Pokémon
Report16 pages
Jun 2018
Sony Group Annual Report FY2017
Sony Group
style standards. Geographically, Sony’s strongest markets remain Japan (¥2.39 trn) and the United States (¥1.67 trn), with growing presence in China and Asia‑Pacific across entertainment, technology
Financial1 pages
Jan 2021
Q1 2021 Market Snapshot Report - EN
King
falling to 45.4 % in China (‑2.7 pp) and sports expanding to 12.3 % in Japan (+27 pp). Monetisation patterns diverged by market: collectibles albums appear in over
Financial21 pages
Jan 2022
State of Mobile Indonesia 2022
data.ai
levels, with Traveloka leading the market. Global dating spend hit $5 billion, driven by growth in the US, Japan, UK, and China. Sports app engagement rose 30 % worldwide
Report61 pages
May 2025
Should Games Be 'Nasty, Brutish, and Short'?
GameDiscoverCo
social integration. Meanwhile, regulatory and market pressures, such as the EU’s Digital Fairness Act and evolving regional pricing strategies in China, are forcing developers to adopt more
Article1 pages
Mobile Game Genre Report: Comparing & Contrasting Eastern and Western Markets
Jan 202130 pages4k words
Summary
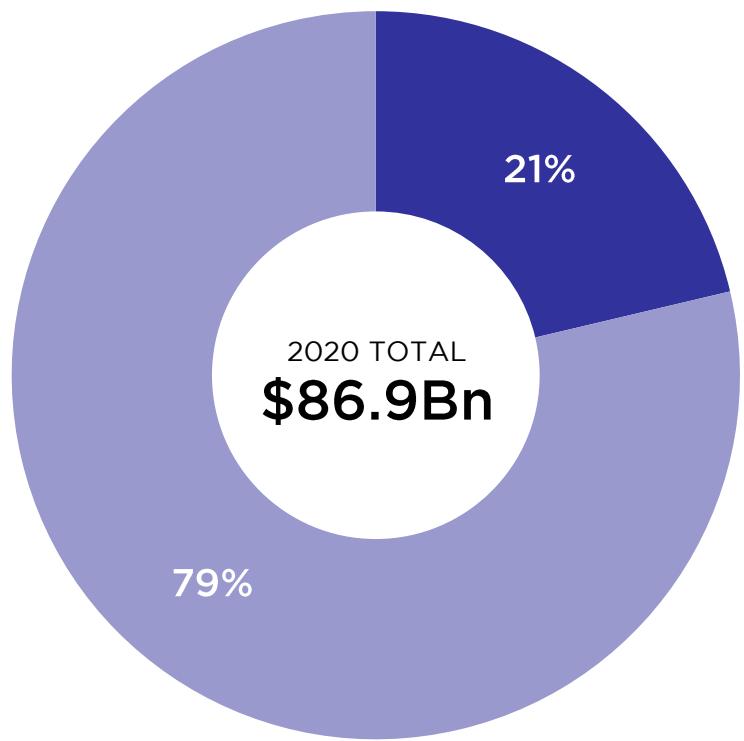
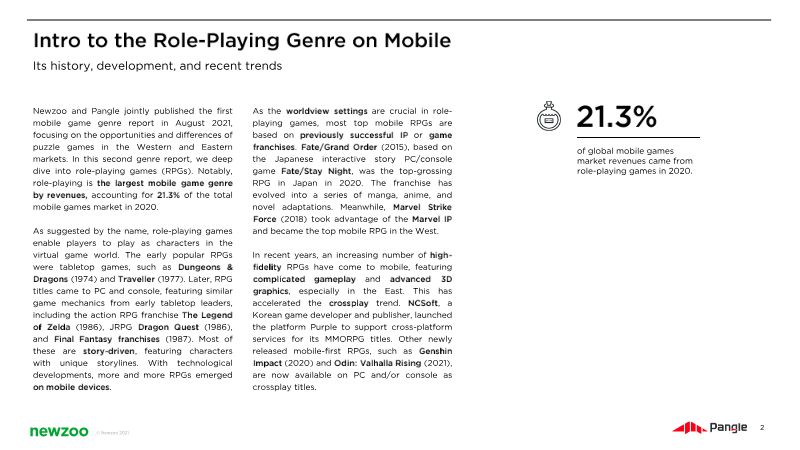
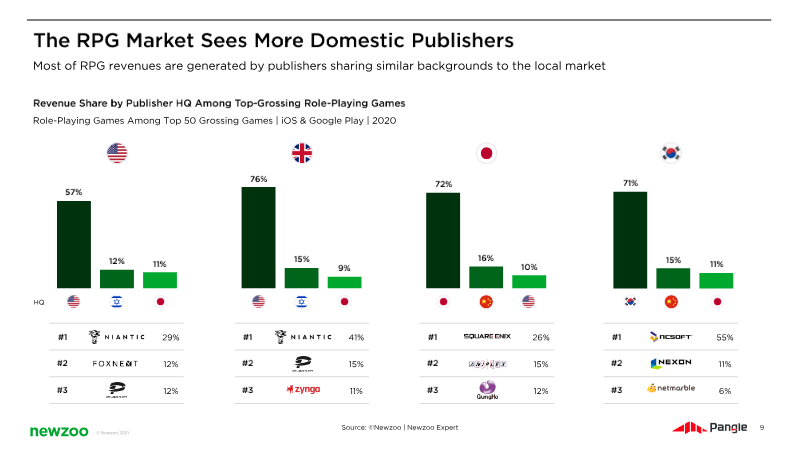
Role-playing games emerged as the dominant force in the mobile gaming industry in 2020, generating $18.5 billion in revenue and capturing over 21% of the global market share. This financial success is heavily concentrated in East Asia, specifically China, Japan, and South Korea, which collectively account for 72% of the genre's total earnings. The market is characterized by a heavy reliance on established intellectual properties from anime, film, and legacy PC franchises, which facilitate organic user acquisition and long-term retention. While Eastern markets are dominated by titles like Lineage, Western audiences gravitate toward major media brands such as Marvel and Star Wars, though original titles can achieve success through aggressive influencer marketing and high-quality creative campaigns.
The monetization landscape for the genre is currently shifting toward hybrid models that integrate traditional gacha-based in-app purchases with rewarded video advertisements. Data indicates that 83% of players are receptive to opt-in ads, and developers are increasingly utilizing battle passes to diversify revenue streams beyond high-spending "whales." These strategies, combined with robust live-ops and cross-media collaborations, have proven effective in maintaining engagement among the genre's core demographic of younger, high-income males.
To navigate modern privacy-related tracking challenges, successful developers are prioritizing early user value signals and optimizing for return on ad spend through interactive playable advertisements. By tailoring game design and monetization to regional preferences—leveraging data from major industry analysts—developers can better address the distinct behavioral patterns of Eastern and Western players. Ultimately, the integration of cross-platform play and sophisticated hybrid monetization remains essential for sustaining growth in this highly competitive and lucrative segment of the mobile industry.
Pages


Insights
- Role-playing games (RPGs) dominated the 2020 mobile market with $18.5 billion in revenue, representing over 21% of the global market share.
- East Asian markets (China, Japan, and South Korea) drive RPG financial performance, accounting for 72% of the genre's total global earnings.
- Successful RPG monetization is shifting toward hybrid models, as 83% of players are receptive to opt-in rewarded video ads alongside traditional gacha mechanics and battle passes.
- Eastern RPG success relies heavily on established anime and legacy PC intellectual properties, whereas Western markets favor major media brands like Marvel and Star Wars.
- To mitigate privacy-related tracking challenges, developers are increasingly prioritizing early user value signals and utilizing interactive playable advertisements to optimize return on ad spend.
This image is a pie chart from a game industry report showing the 2020 total revenue of $86.9 billion, divided into two segments: 21% and 79%. It illustrates the proportional distribution of this total revenue across two unspecified categories.