Showing 30 of 654 results · 1.06s
Mar 2024
US Gaming Audience in 2023
Comscore
utilize more than one platform and 40% play across PC, console, and mobile combined. While mobile-only gamers typically prefer free-to-play titles, console and PC players
Report26 pages
Jul 2024
Global Gamer Study 2024: How Consumers Engage with Games Today
Newzoo
Alpha and Gen Z consumers are game enthusiasts, with Gen Alpha notably spending more time on gaming (5.2 hours per week) than on social media. The data highlights
Report30 pages
Jan 2021
Mobile App Trends 2021: A Global Benchmark of App Performance
Adjust
mobile app industry underwent a transformative period of growth in 2020, characterized by a 50% year-over-year increase in global installs and a total consumer spend
Report35 pages
Jan 2024
2024 Professional Gamer Workforce and Career Structure in Korea
Korea Creative Content Agency
four titles: League of Legends (58 players), Valorant (56), PUBG (54) and PUBG Mobile (48). Smaller but notable presences include Rainbow Six Siege (37) and Eternal Return
Report6 pages
Sep 2020
Q1‑Q3 2020: Recap of the Investment Activity in the Video Game Market
InvestGame
first three quarters of 2020 saw the global gaming industry navigate significant volatility caused by the COVID-19 pandemic, ultimately demonstrating strong resilience and a rapid recovery
Report11 pages
Corporate Overhaul: Why Does CVC Play a Bigger Role Than Ever?
InvestGame
value. The largest disclosed CVC‑led investments target mature gaming studios and multiplatform developers, with EPIC Games securing $2.0 billion in April 2022 and Roblox raising $150 million
Report9 pages
The Rise of the Financial Kingmakers: Private Equity’s $21B+ Bet on Gaming
InvestGame
such as Scopely’s $4.9 billion purchase of Games Group and ESL’s $1.5 billion takeover of Facet Games Group. Minority stake purchases, while smaller in dollar terms
Report9 pages
1st Half 2022/23 Sales
Nacon
million) followed by a 10.6 % decline in the second quarter (€35.2 million). Game sales dominated revenue, rising 72.3 % to €47.0 million; catalogue (new releases) grew
Report2 pages
Jan 2022
App Marketer Survey
Liftoff
scale revenue across sectors such as gaming, finance, and e-commerce. By leveraging creator-led campaigns and advanced game data analytics, businesses across 74 countries are attempting
Report31 pages
Mar 2024
Level Up – Harnessing the Power of Gaming Audiences
Comscore
collaborative analysis by Comscore and Anzu, examines the evolving landscape of the U.S. gaming market and the expanding opportunities for brand integration. The study defines gamers as adults
Report26 pages
May 2026
2026 Live Ops Competitive Intelligence Playbook
Sensor Tower
game mechanics to include broader ecosystem shifts, such as the adoption of direct-to-consumer web stores to bypass platform fees and improve margins. Because the gaming landscape
Report57 pages
Jan 2021
Shooter Genre Snapshot: September 2021
GameRefinery, Vungle
revenue generated by the "Big Three" titles: Call of Duty: Mobile, PUBG Mobile, and Garena Free Fire. The removal of Fortnite from the App Store in August
Report22 pages
Jan 2021
Intro to the Metaverse 2021
Newzoo
fundamental evolution of the gaming industry, transitioning from Games-as-a-Service to Games-as-a-Platform. In this new paradigm, virtual worlds function as persistent social hubs
Report71 pages
Q4 2022-23 Sales and Annual Sales: FY 2022-23
Nacon
sales rose 19.1 % to €37.7 million after a 19.6 % decline in Q3. The Games segment dominated the growth, increasing by 67.0 % to €90.9 million for the full year
Report2 pages
Jan 2026
India Player Behavior & Market Insights: August 2026
Niko Partners
Indian gaming landscape is undergoing a significant demographic and structural transformation as of August 2026. Female participation has reached near parity, climbing to 49% of the total player
Report8 pages
Jan 2025
Power of Play: 2025 Global Video Games Report
IIDEA – Italian Interactive Digital Entertainment Association, Video Games Europe
more than twenty national markets, the majority of gamers report that playing video games reduces stress and enhances happiness, with 70‑90 % indicating lower stress levels
Report33 pages
Jan 2022
Games, Esports, Live Streaming, Cloud and the Metaverse: 2022
Newzoo
global gaming industry is undergoing a fundamental transformation characterized by the convergence of traditional media, high-fidelity content, and emerging Web3 technologies. The primary thesis posits that
Report30 pages
Sep 2021
Sports & Racing Games Report: Q3 2021
Sensor Tower
sports and racing gaming sectors experienced a transformative period throughout 2020 and early 2021, characterized by a 40.2% year-over-year revenue increase to $2 billion. This growth
Report91 pages
Jan 2023
Mobile Ad Creative Index
Liftoff
mobile advertising landscape in 2023 is defined by a strategic shift toward high-performing creative formats as advertisers navigate macroeconomic pressures and evolving privacy regulations. Despite these challenges
Report40 pages
Jan 2025
2025 Half-Year Market Model Update: Asia & MENA
Niko Partners
billion, supported by a 24% year-over-year increase in game approvals. Conversely, East Asia and Southeast Asia show more moderate growth trajectories, with five-year CAGRs
Report3 pages
Jan 2024
Live Streaming Trends Annual Report 2024
Stream Hatchet
YouTube Gaming, and Kick represent the primary pillars of audience engagement. While Twitch maintains its dominance in the non-gaming and community-driven sectors, YouTube Gaming has leveraged
Report54 pages
Jan 2022
Mobile App Trends 2022
Adjust
session durations in marketplace apps. Similarly, the gaming industry saw hyper-casual titles dominate download volumes while adventure and strategy games secured deeper engagement. Across all sectors
Report68 pages
Jan 2022
Store Intelligence Data Digest: Q2 2022
Sensor Tower
significant development occurred within the United States, where consumer spending on non-gaming applications surpassed gaming revenue on the App Store for the first time. This shift
Report75 pages
Apr 2025
Live Streaming Trend Report: Q2 2025
Stream Hatchet
first time since late 2021. The surge was led by YouTube Gaming, which recorded a historic 2.2 billion hours watched, while Kick’s creator‑incentive scheme lifted
Report24 pages
Jan 2022
Key Insights Into South Korean Gamers
Newzoo
population plays games, there is a significant overlap with viewership; 48% of South Koreans both play and watch gaming content, while 22% specifically engage with esports. The demographic
Report11 pages
Jan 2022
Key Insights Into Spanish Gamers
Newzoo
classified as game enthusiasts. Engagement is multifaceted, with 82% of the population playing games and 45% viewing gaming content. Notably, there is a high degree of overlap between
Report11 pages
Jan 2025
Interview with Yi Yuan, at Hiverlab: Southeast Asia
Korea Creative Content Agency
cost‑reduction ratios and increased foot‑traffic, supported by government funding and a mobile‑first infrastructure that leverages WebXR and expanding 5G networks. Large‑scale AR deployments
Report15 pages
Jan 2026
Mobile App Trends: 2026 Edition
Adjust
mobile app industry entered 2026 with significant momentum, characterized by a 10% year-over-year increase in global installs and a 7% rise in sessions throughout 2025. Consumer
Report41 pages
Jan 2024
Mobile App Predictions for 2024
data.ai
Mobile market analysts project a dynamic yet uneven 2024 landscape, with generative AI and video‑first platforms driving growth while text‑centric microblogging contracts. Global app store revenue
Report14 pages
Jan 2024
From Volatility to Stability: Q3 2024 Gaming Deals Report
InvestGame
rather than traditional gaming content. This trend is evidenced by a sharp uptick in private investments for infrastructure, payment, and development tools. Within the gaming segment, early-stage
Report24 pages
US Gaming Audience in 2023
Mar 202426 pages1k words
Summary
The gaming landscape in 2024 has solidified as a mainstream entertainment pillar, with 62% of U.S. adults aged 18 to 65 identifying as active gamers. This audience is characterized by high engagement across multiple devices, as 77% of players utilize more than one platform and 40% play across PC, console, and mobile combined. While mobile-only gamers typically prefer free-to-play titles, console and PC players demonstrate a high willingness to invest in premium content, with 45% of all gamers spending over $40 on their most recent purchase.
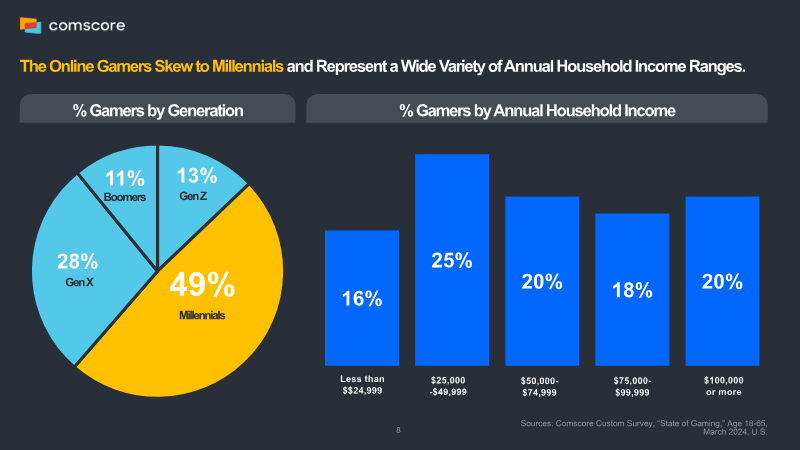
The demographic profile of the U.S. gaming audience skews toward Millennials and spans a wide range of household income levels. Genre preferences vary by platform; PC gamers favor first-person shooters, action, and role-playing games, while console players show a strong preference for action-adventure, sports, and racing titles. This broad reach is further amplified by the success of video game intellectual property in other media, evidenced by significant box office performance for game-inspired films.
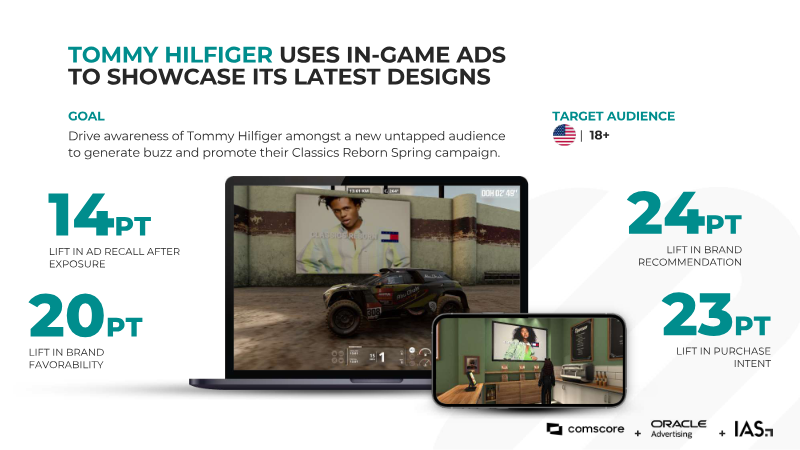
Advertising within the gaming ecosystem presents significant opportunities for brand growth through formats such as intrinsic in-game ads, rewarded video, and sponsorships. Approximately two-thirds of gamers view advertisements as having a positive or neutral impact on their experience, with 34% noting that product placements can enhance realism. Case studies, such as campaigns by Tommy Hilfiger, demonstrate that non-intrusive in-game ads can drive substantial lifts in brand favorability, recommendation, and purchase intent. Through partnerships between measurement firms like Comscore and ad-tech providers like Anzu, advertisers can now better quantify the incremental reach provided by these specialized digital environments.
Pages



Insights
- 62% of U.S. adults aged 18 to 65 are active gamers, with 77% of players utilizing multiple platforms and 40% playing across PC, console, and mobile combined.
- 45% of all gamers spent over $40 on their most recent purchase, indicating a strong willingness to invest in premium content among PC and console users.
- Approximately two-thirds of gamers view advertisements as having a positive or neutral impact on their gaming experience, with 34% stating that product placements can enhance realism.
- Non-intrusive in-game advertising, such as campaigns by Tommy Hilfiger, has been shown to drive measurable lifts in brand favorability, recommendation, and purchase intent.
- Genre preferences are platform-specific, with PC gamers favoring first-person shooters, action, and RPGs, while console players prefer action-adventure, sports, and racing titles.
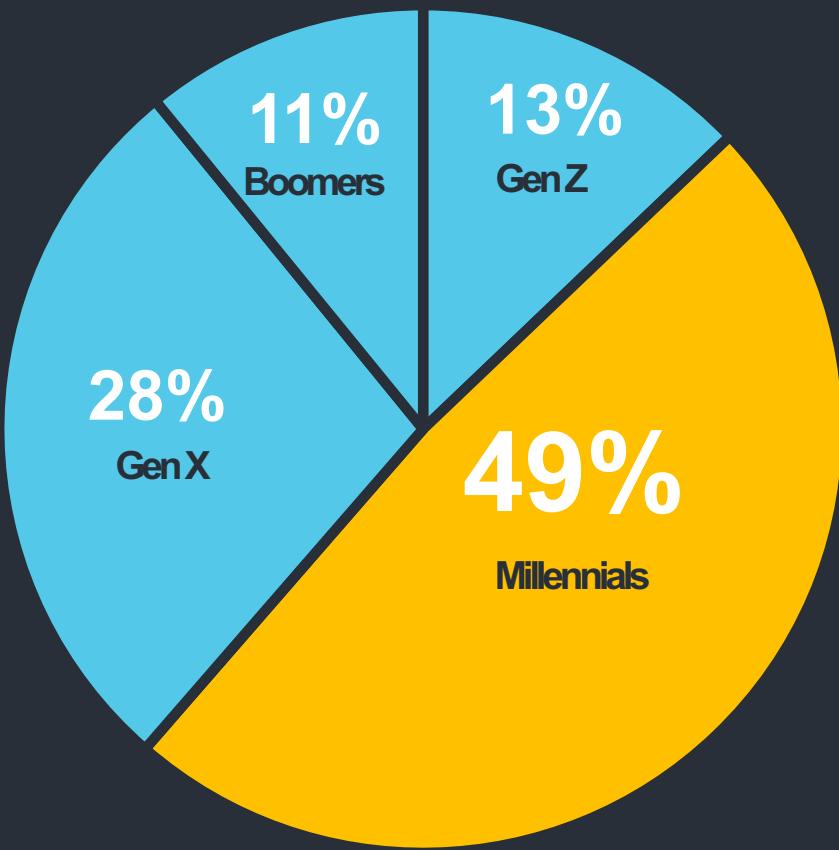
This pie chart from a game industry report illustrates the generational breakdown of gamers, showing the percentage of Boomers (11%), Gen Z (13%), Gen X (28%), and Millennials (49%) within the gaming audience. It highlights that Millennials constitute nearly half of the gaming population.