Report13 pages
FY2024 Report: Australian Game Development Survey
The Australian game development industry demonstrated resilience and stability during the 2024 financial year despite significant global economic headwinds. Total income generated by local studios reached $339.1 million, representing a minor 1.9% decrease from the previous year. Employment remained steady with 2,465 full-time equivalent workers, a marginal 0.3% increase. The sector is heavily export-oriented, with 93% of all revenue generated from outside Australia. Furthermore, 85% of studios focus on developing their own original intellectual property rather than work-for-hire projects.
The industry landscape is characterized by a mix of emerging and established entities. While 56% of studios were formed within the last five years, a quarter of the sector consists of mature studios operating for a decade or more. Small businesses dominate the ecosystem, with 47% of studios employing five or fewer staff members. Geographically, Victoria serves as the primary hub, hosting 52% of head offices and 36% of the national workforce, followed by Queensland and New South Wales.
Government support remains a critical pillar for the industry. The Digital Games Tax Offset, which passed in mid-2023, is already being utilized by 25% of respondents to fund new projects or expand existing ones. Despite this support, developers identified securing international and local publishing deals and attracting early-stage development funding as their primary challenges.
The findings are based on a voluntary survey of 137 Australian game development studios conducted by Bond University on behalf of the Interactive Games & Entertainment Association. The data covers the period from July 1, 2023, to June 30, 2024. Looking ahead, the sector maintains a cautiously optimistic outlook, with 81% of studios predicting stable or increased revenue and 61% planning to hire new staff in the coming year.
- The Australian game development industry generated $339.1 million in revenue during FY2024, reflecting a minor 1.9% year-over-year decline despite global economic headwinds.
- The sector is highly export-focused, with 93% of total revenue derived from international markets and 85% of studios prioritizing the development of original intellectual property.
- Employment remains stable at 2,465 full-time equivalent workers, with 61% of studios planning to increase their headcount in the coming year.
- Victoria is the industry's primary hub, hosting 52% of all studio head offices and 36% of the national workforce.
- The Digital Games Tax Offset, introduced in mid-2023, is already being utilized by 25% of studios to support project funding and expansion.
+1
Interactive Games & Entertainment AssociationJan 2024
Report76 pages
Big Games Industry Employment Survey 2024: Salaries, Compensation Trends and State of the Games Sector in Europe
The European games industry in 2024 is characterized by significant volatility and structural transformation, with 15% of the workforce experiencing layoffs and 10% exiting the sector entirely. This instability disproportionately affects junior professionals, nearly a third of whom have left the industry over the past year. While 44% of those who switched jobs secured career gains, a notable 24% accepted lower pay or seniority to remain employed. Job satisfaction and employee loyalty follow a U-shaped trajectory, typically bottoming out between three and five years of experience before rebounding as professionals prioritize stability and mature corporate processes.
Technological integration and workplace culture are central to current industry shifts. AI adoption has surged by 17% year-over-year, with 54% of professionals now utilizing these tools. Despite this modernization, the sector struggles with persistent systemic issues, including a gender pay gap driven by a lack of female representation in leadership and technical roles. Discrimination remains prevalent, as 32% of respondents reported personal experiences with gender-based bias and 26% cited ageism. Furthermore, a significant gap in professional development exists; 55% of workers received no formal training in the past year, forcing 65% of those seeking advancement to self-fund their education.
Operational pressures continue to impact well-being, with 28% of the workforce reporting stagnant career development and 7% working overtime almost daily. High dissatisfaction is closely linked to professional burnout, poor management, and a lack of work-life balance. However, certain segments show resilience; the outsourcing sector saw a significant rise in employee net promoter scores, and hybrid work models remain a primary driver of retention. While free-to-play studios generally offer higher compensation than premium developers, long-term stability perks and profit-sharing remain the most effective tools for maintaining a committed workforce in an increasingly precarious market.
- The European games industry faces significant instability, with 15% of the workforce experiencing layoffs and 10% leaving the sector entirely, disproportionately impacting junior professionals.
- AI adoption has surged by 17% year-over-year, with 54% of industry professionals now integrating these tools into their daily workflows.
- Systemic workplace issues persist, as 32% of respondents reported gender-based bias and 26% cited ageism, contributing to a gender pay gap rooted in a lack of female leadership and technical representation.
- Professional development is stagnating, with 55% of workers receiving no formal training in the past year, forcing 65% of those seeking career advancement to self-fund their education.
- While 44% of job switchers achieved career gains, 24% were forced to accept lower pay or reduced seniority to maintain employment in the current market.
+1
InGameJobJan 2024
Report37 pages
State of the Game Industry 2024
The global game industry entered 2024 in a state of profound volatility, defined by a painful market correction following post-pandemic overexpansion. This period of instability is marked by widespread layoffs affecting one-third of the workforce and a surge in studio closures linked to rapid corporate conglomeration. While North America remains the primary hub for development and PC continues to be the dominant platform, the workforce is increasingly preoccupied with job security and the ethical implications of emerging technologies. Generative AI has seen rapid adoption, with nearly half of developers utilizing these tools, yet 84% express deep concern regarding copyright infringement and the potential for further job displacement.
Labor dynamics are shifting as developers react to economic pressures and perceived corporate mismanagement. Support for unionization has climbed to 57%, with particularly high enthusiasm among younger professionals aged 18 to 24 who are grappling with inflation and precarious employment. This desire for collective bargaining coincides with a growing rejection of mandatory return-to-office policies and a decline in confidence regarding corporate diversity and sustainability initiatives. Furthermore, the technical landscape is fracturing; significant dissatisfaction with Unity’s recent policy changes has led one-third of developers to consider switching engines, often favoring open-source alternatives like Godot.
Business models remain centered on digital premium downloads, favored by 51% of the industry, even as marketing strategies face disruption due to overwhelming negative sentiment toward major social media platforms like Twitter/X. Despite the internal turmoil, there is a measurable increase in the implementation of accessibility features, which now appear in nearly half of all projects. However, the industry’s demographic makeup remains largely stagnant, continuing to be predominantly White and male. Ultimately, the current landscape reflects a workforce caught between the necessity of financial stability through consolidation and a growing demand for systemic reform to address ethical, technical, and labor-related grievances.
- The industry is undergoing a severe market correction characterized by widespread layoffs affecting one-third of the global workforce and a surge in studio closures.
- Support for unionization has reached 57%, driven largely by younger professionals (ages 18–24) facing economic instability and dissatisfaction with corporate management.
- While 49% of developers have adopted generative AI, 84% of the workforce reports significant concerns regarding copyright infringement and potential job displacement.
- Technical infrastructure is shifting, with one-third of developers considering engine migrations—often toward open-source options like Godot—following recent policy changes at Unity.
- Digital premium downloads remain the primary business model for 51% of the industry, even as marketing strategies struggle with declining sentiment toward major social media platforms.
+3
Game Developers ConferenceJan 2024
Report68 pages
The Economic Impacts of Video Game Technology Spillover: UK and Nordic Economies
The analysis quantifies how video‑game technology generates measurable economic benefits beyond the entertainment sector, arguing that spill‑over effects constitute a significant engine of growth for advanced‑technology economies. By applying the IMPLAN input‑output model to 2021 data, the study estimates that spill‑overs contributed roughly £1.3 billion of total output and £760 million of GDP to the United Kingdom, delivering £380 million of labour income and £250 million of government revenue while sustaining about 9,900 non‑gaming jobs. These positions are concentrated in information‑technology, business services and energy extraction, with average salaries 25 % above the national mean. In the Nordic region, comparable effects amounted to £190 million of output and £40 million of GDP, underscoring the broader relevance across Western Europe.
The research situates these figures within the wider UK games ecosystem, which comprises approximately 2,600 firms and 71,400 jobs across direct, indirect and induced employment. Spill‑over activity accounts for roughly 13 % of the industry’s gross value added and 19 % of its employment, highlighting the sector’s pivotal role in supporting ancillary markets. Sectoral case studies illustrate how real‑time engines (Unreal, Unity), VR/AR headsets and haptic devices are reshaping healthcare, oil and gas, architecture, horticulture, furniture design and automotive safety, delivering faster, lower‑cost visualisation, enhanced training and new revenue streams.
The findings extend to the United States, where about one‑fifth of software‑job growth in 2016 and $0.5 billion of software output are linked to game‑technology diffusion. Collectively, the evidence demonstrates that video‑game innovations act as a cross‑industry catalyst, generating substantial fiscal, employment and productivity gains across multiple high‑value sectors during the 2021‑2022 period.
- In 2021, video game technology spill-overs contributed £1.3 billion in total output and £760 million to UK GDP, while sustaining 9,900 non-gaming jobs.
- Spill-over activity from the UK games industry accounts for 13% of the sector's gross value added and 19% of its total employment.
- Non-gaming roles supported by game technology—primarily in IT, business services, and energy—command average salaries 25% higher than the UK national mean.
- Real-time engines like Unreal and Unity, alongside VR/AR and haptic hardware, are driving productivity and cost reductions in sectors including healthcare, architecture, automotive safety, and energy extraction.
- The economic impact of game technology is significant across Western Europe, with the Nordic region recording £190 million in output and £40 million in GDP from these spill-overs.
+2
UkieNov 2023
Report68 pages
Spelutvecklarindex 2023: Swedish Games Industry
The Swedish games industry serves as a powerhouse of global digital entertainment, characterized by rapid revenue expansion and a vast international footprint. In 2022, the sector generated 86.5 billion SEK in global revenue, marking a 47% increase largely fueled by aggressive acquisition strategies. With 392 Swedish-owned studios operating across 59 countries, the industry employs approximately 25,000 people worldwide, including 8,445 domestic staff. This reach is immense, with Swedish-developed titles accumulating nearly 7 billion downloads and engaging roughly one-quarter of the global population.
Despite this commercial success, the industry faces structural bottlenecks that threaten long-term sustainability. A persistent talent shortage remains the primary constraint on production capacity, exacerbated by challenges regarding work permits and a lack of formal financial support structures for early-stage startups compared to European peers. To mitigate these issues, studios are increasingly leveraging productivity-enhancing technologies like generative AI, standardized game engines, and collaborative regional ecosystems that bridge the gap between specialized education and professional development.
Social and operational evolution remains a core priority for the sector. Efforts to improve gender diversity are yielding tangible results, with women accounting for nearly half of all new hires in 2022, bringing female representation to 23.4% of the workforce. Simultaneously, the industry is pivoting toward broader sustainability goals, focusing on reducing environmental footprints and fostering healthy, inclusive workplace cultures. As the sector navigates the complexities of hybrid work environments and the integration of emerging technologies, it continues to function as a vital catalyst for innovation, driving value that extends well beyond the boundaries of traditional game development.
- The Swedish games industry generated 86.5 billion SEK in global revenue in 2022, representing a 47% year-over-year increase driven largely by acquisition strategies.
- Swedish-owned studios now number 392 across 59 countries, employing 25,000 people globally with 8,445 staff based domestically.
- Swedish-developed titles have reached a massive scale, accumulating nearly 7 billion downloads and engaging approximately 25% of the global population.
- Gender diversity is improving, with women accounting for nearly 50% of all new hires in 2022, raising total female workforce representation to 23.4%.
- A persistent talent shortage and difficulties with work permits remain the primary constraints on production capacity, compounded by a lack of early-stage financial support compared to other European markets.
+2
DataspelsbranschenOct 2023
Report159 pages
Impacto de la aplicación de sistemas de incentivos fiscales en la industria de videojuegos: España
The analysis evaluates how a targeted fiscal‑incentive regime would reshape Spain’s video‑game industry, arguing that a 20 % corporate‑tax credit for developers could expand sector turnover from €1.435 billion in 2022 to roughly €5.5 billion by 2028—a compound annual growth rate of about 27 %—and raise full‑time employment from just under 10 000 jobs to more than 23 000 by 2030, an 80 % increase. Despite the lower tax rate, overall fiscal receipts would grow, with a direct contribution of €1.9 billion and an additional €1.0 billion generated through reinvestment and consumer spending, indicating a net positive return for the Treasury.
Spain’s ecosystem comprises roughly 760 active studios, of which 445 are incorporated, and 71 publishers, with the top ten accounting for almost 95 % of revenue. Development costs vary markedly by platform—averaging €419 k for consoles, €338 k for PC and €94 k for mobile—while break‑even periods range from 8.6 to 15.5 months, underscoring the financing pressure on predominantly
- Implementing a 20% corporate tax credit for developers is projected to grow Spain’s video game sector turnover from €1.435 billion in 2022 to €5.5 billion by 2028, representing a 27% compound annual growth rate.
- The proposed fiscal incentives are expected to increase full-time employment in the industry from under 10,000 jobs to more than 23,000 by 2030.
- The tax regime is forecast to be net-positive for the Treasury, generating €1.9 billion in direct contributions plus an additional €1.0 billion through reinvestment and consumer spending.
- The Spanish market is highly concentrated, with the top ten companies accounting for approximately 95% of total industry revenue.
- Development costs vary significantly by platform, averaging €419k for consoles, €338k for PC, and €94k for mobile.
+2
AEVIJun 2023
Report3 pages
NHK Enterprise's 'Kami-Ge Creator Evolution' Succeeds Japan Game Awards 'Amateur' and 'U18' Divisions
NHK Enterprise is launching the “Kami‑Ge Creator Evolution” contest as a dedicated platform for nurturing the next generation of Japanese game developers, and from 2024 it will incorporate the Japan Game Awards’ Amateur and U18 divisions. The initiative, begun in 2022 under the theme “Evolve the Game,” seeks to discover and develop talent through a series of contest events, community support, and media exposure, including a documentary broadcast on NHK General in February 2023 that generated strong public interest.
The competition invites creators from across Japan to submit original games, which are evaluated for innovative expansion of the medium’s boundaries by a diverse panel of established game designers, media artists, and other industry figures. In addition to expert judging, a public popularity vote is conducted, and the contest awards a Grand Prize, Excellence Awards, and Honorable Mentions in the Amateur category, while the U18 category focuses on participants aged 18 or younger, reflecting the Japan Game Awards’ long‑standing commitment to youth development since 2018. The 2024 schedule begins with an entry period from 1 February to the end of April, followed by nomination, second‑round video submissions in July, third‑round game submissions in October, finalist announcements at the end of October, and a final event slated for December.
A closed Discord community supports participants with exclusive benefits, knowledge sharing, and mentorship, reinforcing the project’s role as a learning environment. Special cooperation from the Computer Entertainment Supplier’s Association (CESA) provides additional industry credibility and resources. The contest is open to individuals, teams, corporations, and organizations regardless of age, gender, nationality, or the number of entries, emphasizing inclusivity and broad outreach.
By integrating the Amateur and U18 awards, the “Kami‑Ge Creator Evolution” aims to broaden the creative framework of Japanese games, foster innovative design, and strengthen the pipeline of skilled developers. The organizers are actively seeking sponsors to sustain the project’s growth and align with NHK Enterprise’s broader commitment to sustainable development and cultural enrichment.
- NHK Enterprise has integrated the Japan Game Awards’ Amateur and U18 divisions into its 'Kami-Ge Creator Evolution' contest, effective from 2024.
- The 2024 competition timeline spans from February 1 to a final event in December, featuring a multi-stage evaluation process including video submissions in July and game submissions in October.
- The contest is open to all applicants regardless of age, nationality, or organizational status, with specific categories for general amateur creators and those aged 18 or younger.
- Participants gain access to a closed Discord community providing mentorship, knowledge sharing, and exclusive resources to support developer growth.
- The initiative is supported by the Computer Entertainment Supplier’s Association (CESA) to provide industry credibility and resources for the project.
+2
CESA – Computer Entertainment Supplier's AssociationMay 2023
Presentation20 pages
People Can Fly: Q1 2023 Financial Results
PCF Group, the parent entity of the People Can Fly studio, reports a period of continued organizational expansion and strategic financial positioning as of the first quarter of 2023. The group has significantly grown its workforce to 642 employees by March 31, 2023, up from 612 at the end of 2022. This growth is concentrated primarily in its European hubs, including Warsaw, Rzeszów, and Newcastle, while maintaining a substantial presence in North America through its Montreal and New York studios. The team composition remains heavily weighted toward development, supported by specialized units like Incuvo and GameOn.
Financial data indicates a stable balance sheet with total assets and liabilities reaching 351.9 million PLN. A notable shift is observed in the group’s cash position, which decreased from 137.1 million PLN at the end of 2021 to 60.9 million PLN by the end of Q1 2023. Simultaneously, investment in development work in progress has surged to 139.7 million PLN, reflecting an intensive production cycle. Equity remains strong at 271.6 million PLN, providing a solid foundation for the group’s long-term objectives.
The strategic focus is transitioning from a work-for-hire model toward self-publishing. While the group continues to leverage partnerships with global publishers to ensure financial stability and experimental freedom, the ultimate goal is to release three AAA projects under a self-publishing framework. This shift is projected to drive a 4.9x revenue increase between 2023 and 2027. Funding for this strategy is secured through a combination of operational cash flow, debt financing, and a strategic investment agreement with Krafton, which contributed 144.5 million PLN via a share subscription. This diversified capital structure is intended to support the full realization of the group’s ambitious development pipeline.
- People Can Fly is transitioning from a work-for-hire model to self-publishing, with a strategic goal to release three AAA projects by 2027.
- The group projects a 4.9x revenue increase between 2023 and 2027, supported by a capital structure that includes a 144.5 million PLN share subscription from Krafton.
- Development intensity has surged, with investment in work-in-progress projects reaching 139.7 million PLN as of Q1 2023.
- The company's cash position decreased from 137.1 million PLN at the end of 2021 to 60.9 million PLN by the end of Q1 2023, reflecting heavy reinvestment into production.
- The workforce grew to 642 employees by March 31, 2023, up from 612 at the end of 2022, with expansion focused on European hubs and North American studios.
+1
PCF GroupMay 2023
Report36 pages
Vägar in i spelbranschen: Kompetens, utbildning och konsten att skapa spel (2023)
The Swedish game industry is currently experiencing a critical talent shortage that threatens its long-term competitiveness and growth. With the sector recording 1,348 new hires in 2021 alone, domestic educational institutions are failing to meet demand, producing fewer than half of the required professionals. This imbalance is exacerbated by the rapid expansion of the industry and the lack of official recognition for game development as a formal academic discipline, which complicates data tracking and strategic planning. To sustain its global standing, the industry must bridge the gap between educational output and the evolving needs of studios, particularly in core disciplines such as programming, design, and graphics.
The Swedish educational landscape is characterized by a robust ecosystem of vocational programs and academic institutions that prioritize project-based, team-oriented learning. While these programs are highly effective at producing job-ready graduates, the reliance on international recruitment remains essential, with roughly one-third to half of the workforce originating from abroad. However, this dependency is hampered by significant bureaucratic obstacles, including restrictive work permit policies for non-EU vocational students and complex regulations regarding international remote work. Furthermore, the industry faces persistent challenges related to housing shortages and the need to improve gender diversity within the workforce.
To ensure future stability, the industry must foster closer alignment between academic research funding and practical studio requirements. Strengthening the pipeline for domestic talent while simultaneously streamlining pathways for international professionals is vital. By formalizing game development within the academic framework and addressing the administrative barriers that currently impede the retention of global talent, Sweden can maintain its position as a leading hub for game development. These systemic adjustments are necessary to transform the current recruitment bottleneck into a sustainable model for continued innovation and economic success.
- The Swedish game industry faces a critical talent shortage, with domestic educational institutions producing fewer than half of the professionals required to meet the demand of 1,348 new hires recorded in 2021.
- Between one-third and one-half of the current Swedish game industry workforce consists of international talent, highlighting a heavy reliance on global recruitment to sustain growth.
- Restrictive work permit policies for non-EU vocational students and complex regulations regarding international remote work act as significant bureaucratic barriers to maintaining the necessary talent pipeline.
- The lack of official recognition for game development as a formal academic discipline hinders effective data tracking and strategic planning for the sector.
- Industry growth is further constrained by domestic infrastructure challenges, specifically persistent housing shortages and a need to improve gender diversity within the workforce.
+1
DataspelsbranschenJan 2023
Report61 pages
Games & Interactive Salary & Satisfaction Survey 2023
The 2023 Games & Interactive Salary & Satisfaction Survey establishes that financial compensation has emerged as the primary catalyst for professional mobility within the global gaming industry. Driven largely by the prevailing cost of living crisis, employees are increasingly prioritizing salary increases when evaluating career moves. While monetary remuneration remains the dominant factor, non-monetary benefits such as flexible working arrangements, private healthcare, and robust pension schemes are essential for talent retention. The data indicates a high degree of industry volatility, with a significant portion of the workforce—particularly among programmers and artists—actively considering new employment opportunities throughout the year.
Geographically focused on the UK, Europe, and broader global markets, the findings underscore a fundamental shift in workplace expectations. Remote work has transitioned from a temporary accommodation to a standard requirement, with the vast majority of professionals now expecting at least one day of remote work per week. Despite this, a disconnect persists between employee needs and employer support. Many workers report inadequate institutional backing regarding mental health, neurodiversity accommodations, and financial pressures. Furthermore, project completion cycles serve as a major inflection point for retention, as employees frequently initiate job searches immediately following the conclusion of their current assignments.
Ultimately, the industry faces a complex retention landscape where high mobility is tempered by a desire for stability and work-life balance. Although a large percentage of the workforce is open to changing employers, many candidates decline offers that fail to meet specific salary thresholds or project-based interests. To remain competitive, organizations must reconcile the demand for flexible, remote-first environments with the necessity of addressing the financial and psychological well-being of their staff, particularly as project-based turnover continues to threaten long-term team cohesion.
- Financial compensation is the primary driver of professional mobility in the gaming industry, largely fueled by the global cost-of-living crisis.
- High workforce volatility persists, with programmers and artists showing the highest propensity to actively seek new employment opportunities throughout the year.
- Remote work has shifted from a temporary accommodation to a baseline industry requirement, with the majority of professionals now expecting at least one day of remote work per week.
- Project completion cycles are critical retention inflection points, as employees frequently initiate job searches immediately after finishing current assignments.
- A significant disconnect exists between employee needs and employer support regarding mental health, neurodiversity accommodations, and financial well-being.
+1
SkillsearchJan 2023

Report61 pages
2023 Games & Interactive Salary & Satisfaction Survey
The ninth‑year Games & Interactive Salary & Satisfaction Survey demonstrates that financial remuneration has become the predominant catalyst for career moves, eclipsing flexible or remote work as a primary motivator. Across the United Kingdom and Western Europe, 31 % of respondents cite higher pay as their main reason for leaving a position, while culture and benefits remain significant secondary drivers. In Eastern Europe, remote working is almost universal (91 %) yet salary still leads the list of motivations for job changes. The survey’s high response rate allows a granular view of compensation trends, revealing junior programmers earning £25‑£50 k globally and senior or managerial roles reaching up to £200 k in certain markets.
A notable trend is the heightened turnover during project close‑out periods, with 22 % of UK respondents declining offers to finish current projects and a global job‑hunt rate of 46 %. This suggests studios must strengthen retention strategies once projects conclude. Remote work expectations are high, with 92 % of global respondents anticipating at least one remote day per week, and flexible/remote working remains a top benefit sought (16‑19 % across regions).
Artist compensation has risen sharply, with average salaries increasing 35 % from 2021 to 2023. Mid‑level artists now earn around £75 k, while senior and lead roles approach £50 k. Remote work is preferred by 76 % of artists, and private health care (41 %) and pension plans (39 %) are the most valued benefits. Technical artists show lower job‑hunting activity compared to concept or character artists, indicating varying stability across creative roles. Overall, the survey underscores a cost‑of‑living pressure that prioritizes pay, while culture, flexibility, and robust post‑project retention remain critical for talent attraction and retention across the global games industry.
- Salary has overtaken flexible work as the primary driver for career moves, with 31% of UK and Western European respondents citing higher pay as their main reason for leaving a position.
- Artist compensation has seen a sharp 35% increase between 2021 and 2023, with mid-level artists now earning approximately £75k.
- Project close-out periods are a critical retention risk, as 22% of UK respondents decline new offers to finish current projects and 46% of global staff are actively job hunting.
- Remote work remains a baseline expectation for the industry, with 92% of global respondents requiring at least one remote day per week and 91% of Eastern European staff working remotely.
- Global compensation ranges are broad, with junior programmers earning between £25k–£50k and senior or managerial roles reaching up to £200k in specific markets.
SkillsearchJan 2023
Report81 pages
2023 European Video Games Industry Insight Report
By European Games Developer Federation (EGDF) Supported by Video Games Europe European Video Games Industry Data 5 Number of game developer studios 7 Number of people working in the video games industry 8 Percentage of women working in the industry 9 Main European game dev hubs by the number of employees ...
- In 2023, the EU was home to 5,900 game developer studios.
- Public funding plays a crucial role in financing new game studios and supporting research and development across Europe.
- Each European country exhibits unique platform preferences for game development.
- The Czech Republic's video game industry saw its number of studios grow from 110 in 2019 to 1748 in 2022, with turnover reaching 226 million euros in 2022.
- Norway's video game industry had 24 studios in 2022, employing 824 people, and generated 55 million euros in turnover in 2022.
+1
European Games Developer FederationJan 2023
Report19 pages
European Key Facts 2023
This analysis provides a comprehensive overview of the European video game sector in 2023, detailing market health, player demographics, and regulatory priorities. The industry demonstrated resilience with annual revenues reaching €25.7 billion, representing a 5% year-on-year increase. Employment also saw significant growth, with the workforce expanding by nearly 7% to reach approximately 115,000 people across Europe.
The data reveals that video games are a mainstream cultural fixture, with 53% of the European population aged 6–64 identifying as players. Contrary to youth-centric stereotypes, the average player age is 31.4 years, and 75% of the gaming population are adults. Women represent 43.5% of the total player base, averaging 6.7 hours of play per week. While smartphones remain the most popular platform (68%), consoles (56%) and PCs (46%) maintain significant engagement. Despite the rise of digital media, average weekly playtime has remained stable for over a decade at approximately 8.9 hours.
A central thesis of the findings is the industry’s commitment to social responsibility and self-regulation. The Pan European Game Information (PEGI) system celebrated 20 years of operation, with 79% of parents aware of its ratings and 62% actively using parental tools to manage gameplay. Furthermore, the industry is increasingly focused on sustainability and diversity, noting that 44% of new hires in regions like Sweden are women and highlighting energy-saving agreements that have saved 54 TWh of electricity over the lifetime of major consoles.
The geographic scope covers the European Union and broader European markets, utilizing data from Ipsos, GameTrack, and Games Sales Data (GSD). Methodology includes online polling of 60,000 individuals across major markets, calibrated by nationally representative face-to-face surveys. Looking forward, the industry advocates for EU policy that recognizes video games as unique creative works, supports a robust talent pipeline through STEAM education, and maintains a fair regulatory framework that avoids distorting the single market.
- The European video game sector generated €25.7 billion in 2023, marking a 5% year-on-year revenue increase.
- Industry employment grew by nearly 7% in 2023, reaching a total workforce of approximately 115,000 people across Europe.
- Video games are a mainstream fixture with 53% of the population aged 6–64 identifying as players, maintaining a stable average of 8.9 hours of gameplay per week.
- The player base is mature and diverse, with an average age of 31.4 years, 75% adult representation, and 43.5% female participation.
- Smartphones are the leading platform at 68% usage, followed by consoles at 56% and PCs at 46%.
+1
Video Games EuropeJan 2023
Report14 pages
Australian Game Development Survey FY 2023
The Australian Game Development Survey FY2023 reveals a maturing industry experiencing significant growth in both revenue and employment. Total income generated by local studios reached $345.5 million, a 21% increase over the previous year, while the workforce expanded by 17% to 2,458 full-time equivalent employees. This growth is largely attributed to increased federal and state government support, including the Digital Games Tax Offset (DGTO), which has bolstered developer confidence and attracted international interest.
The sector is heavily export-oriented, with 87% of revenue derived from markets outside of Australia. While the industry is diversifying, it remains concentrated in the eastern states, with Victoria housing 29% of studios and 41% of the workforce. The ecosystem is characterized by a mix of established and emerging entities; 32% of studios have operated for over a decade, yet 45% are five years old or less, and 29% are currently developing their first title. Small businesses dominate the landscape, with 79% of respondents employing fewer than 20 people.
Despite this upward trajectory, the industry faces notable headwinds. The primary challenges identified include difficulty hiring staff with specialized technical skills, attracting early-stage development funding, and securing international publishing deals amidst tightening global economic conditions. Nevertheless, 63% of studios intend to hire more staff in the coming year, and 68% predict continued income growth.
The findings are based on a survey of 111 Australian game development studios conducted by Bond University on behalf of the Interactive Games & Entertainment Association (IGEA). The data covers the financial year from July 1, 2022, to June 30, 2023, and includes metrics on gender diversity, which showed an increase in the representation of women and gender-diverse individuals within the workforce.
- The Australian game development industry generated $345.5 million in revenue during FY2023, marking a 21% year-over-year increase.
- Total industry employment grew by 17% to 2,458 full-time equivalent employees, with 63% of studios planning further hiring in the coming year.
- The sector is highly export-focused, with 87% of total revenue derived from international markets.
- Government support, specifically the Digital Games Tax Offset (DGTO), is a primary driver of developer confidence and international investment.
- The industry is geographically concentrated in Victoria, which accounts for 29% of studios and 41% of the total workforce.
+1
Interactive Games & Entertainment AssociationJan 2023
Report1 pages
Video Games in Romania 2023
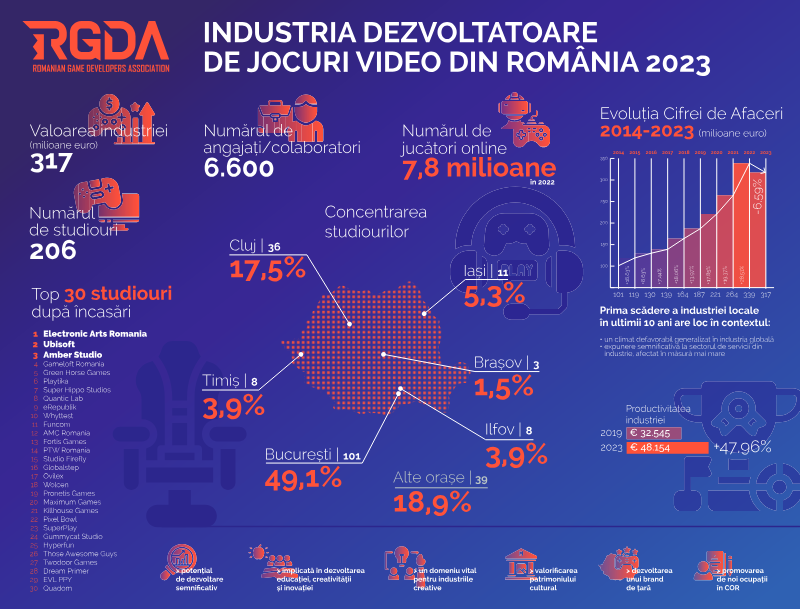
The 2023 analysis of Romania’s video‑game sector presents a comprehensive overview of its economic evolution, workforce expansion, and market concentration over the past decade. It establishes that the industry’s turnover has risen sharply, reaching approximately €6.6 billion in 2023, while the number of active studios grew to 350 and employment climbed to roughly 6 600 people. Online player participation also expanded, with an estimated 7.8 million gamers engaging with Romanian titles or services.
Growth trends are detailed year by year from 2014 to 2023, highlighting an overall upward trajectory in revenue and studio count, yet noting a first‑time contraction in 2022 of about 6.6 percent, attributed to a broadly unfavorable global climate and heightened exposure to the service‑sector dynamics that affect the industry more acutely than other creative fields. Geographic distribution shows a pronounced clustering in key urban hubs: Cluj hosts the largest concentration with 36 studios, followed by Iași, which accounts for 17.5 percent of the total, and other significant presences in Bucharest, Timișoara, and Brașov.
The report identifies the top thirty studios, which together generate roughly 5 percent of total industry revenue, and lists leading companies such as Electronic Arts Romania, Ubisoft, Amber Studio Brașov, and Playtika, among others. Their individual growth rates vary, with some recording double‑digit percentage increases, underscoring a heterogeneous performance landscape within the sector. The analysis concludes that despite recent headwinds, the Romanian video‑game ecosystem remains a vital and expanding creative economy, but it calls for reinforced educational initiatives, stronger promotion, and strategic support to sustain momentum and mitigate external risks.
- The Romanian video game industry reached a turnover of approximately €6.6 billion in 2023, supported by 350 active studios and a workforce of 6,600 employees.
- The sector experienced a 6.6% contraction in 2022, marking the first decline in a decade due to an unfavorable global economic climate and service-sector volatility.
- Industry activity is highly concentrated in key urban hubs, led by Cluj with 36 studios and Iași, which accounts for 17.5% of the total studio count.
- The top 30 studios, including major players like Electronic Arts Romania, Ubisoft, Amber Studio Brașov, and Playtika, generate roughly 5% of the industry's total revenue.
- The Romanian gaming ecosystem serves an estimated 7.8 million players through its titles and services.
+1
RGDA – Romanian Game Developers AssociationJan 2023
Report33 pages
White Paper Catalan Video Game Industry 2023
The 2023 white paper on Catalonia’s video‑game industry presents a detailed assessment of the sector’s economic performance and labour dynamics for the year 2022. It establishes that the regional market generated €709 million in revenue, reflecting a 7.5 percent decline compared with the previous year, while employment rose to 4 619 workers, an increase of 8.7 percent. This juxtaposition of falling turnover and rising headcount suggests a shift toward more labour‑intensive activities, such as development and ancillary services, even as overall sales pressures persist.
The analysis situates the sector within Catalonia’s broader creative economy, emphasizing its continued relevance as a source of high‑skill jobs and its capacity to attract talent despite modest revenue contraction. The data underline the resilience of the local ecosystem, which appears to be sustaining employment growth through diversification and possibly increased public or private investment in development capacities.
Overall, the findings portray a video‑game industry that, while facing short‑term market headwinds, maintains a solid employment base and remains a pivotal component of Catalonia’s digital and cultural output. The report implies that strategic support and continued innovation could reverse the revenue dip and further strengthen the region’s position in the European gaming landscape.
- Catalonia’s video game industry generated €709 million in revenue during 2022, representing a 7.5 percent decline from the previous year.
- Total employment in the sector grew by 8.7 percent in 2022, reaching a workforce of 4,619 people.
- The simultaneous decrease in revenue and increase in headcount indicates a strategic shift toward more labor-intensive development and ancillary service activities.
- The regional gaming ecosystem demonstrates resilience by sustaining job growth despite broader market headwinds and revenue contraction.
- The industry remains a critical component of the Catalan creative economy, serving as a primary driver for high-skill employment and digital innovation.
+3
DEVJan 2023
Report166 pages
Pesquisa Nacional da Indústria de Games 2023
The 2023 national survey of Brazil’s game‑development ecosystem maps the sector as it stood in 2022, revealing a vibrant but highly fragmented industry dominated by micro‑ and small studios. With 1,042 active studios and a representative sample of 309 developers, 214 freelancers and 80 support organisations, the market expanded despite a 5.1 % contraction in the global games market, delivering a 3 % domestic growth that lifted the industry to US $182.9 bn in 2022 and projecting US $206.4 bn by 2025. Brazil ranks fifth worldwide in online population, hosting roughly 103 million gamers; revenue generation is led by mobile (49 %), followed by PC (26 %) and consoles (25 %), while gender parity approaches equality with women accounting for 46.2 % of players.
Export orientation is emerging, as 76 % of developers target the domestic market but substantial shares also aim at the United States (58 %), Latin America (57 %) and Western Europe (55 %). Prospects for the next three years show Canada and Latin America each featuring in 47 % of sales roadmaps, with China appearing in 44 % of plans, indicating a gradual diversification of export destinations. The sector is supported by 17 regional industry associations and coordinated nationally by Abragames, Brazil Games and ApexBrasil, which provide market representation, business‑matching missions and participation in overseas fairs.
Artificial intelligence dominates technology priorities, cited by more than half of respondents as a short‑ and long‑term focus, while XR/VR/AR follows closely, driven by 5G and new engines such as Unreal Engine 5. Interest in blockchain and
- Brazil’s game industry grew 3% in 2022 despite a 5.1% global market contraction, reaching a valuation of US$182.9 billion with projections to hit US$206.4 billion by 2025.
- The Brazilian market is highly fragmented, consisting of 1,042 active studios that are primarily micro or small in size.
- Mobile gaming leads revenue generation at 49%, followed by PC at 26% and consoles at 25%, supported by a massive domestic player base of approximately 103 million people.
- Developers are increasingly export-oriented, with 58% targeting the U.S., 57% targeting Latin America, and 55% targeting Western Europe, while future roadmaps show growing interest in China (44%).
- Artificial intelligence is the primary technology priority for over 50% of developers, followed by XR/VR/AR applications enabled by 5G and Unreal Engine 5.
+1
AbragamesJan 2023
Report15 pages
Annual Report 2023: Canada
The 2023 annual review underscores a year of extraordinary expansion for Canada’s video‑game industry, positioning the nation as a pre‑eminent global hub for development talent and creative output. Canadian studios not only captured a record share of international awards and critical praise, but also deepened export revenues, reinforcing the sector’s contribution to the broader digital economy. Concurrently, the industry association intensified its advocacy agenda, securing more favourable regulatory frameworks and advancing diversity, equity and inclusion initiatives that aim to broaden participation across the workforce.
Financial analysis reveals that the Canadian Entertainment Software Association (ALD) concluded the fiscal year with a substantial surplus, reflecting both robust membership growth and effective cost management. The surplus enabled the organization to maintain flat membership fees for existing constituents while expanding its full‑time staff, thereby enhancing service delivery and policy‑making capacity. This fiscal stability signals confidence among stakeholders and provides a solid foundation for future strategic investments.
Geographically, the findings pertain to the Canadian market, encompassing all provinces and territories, and cover the calendar year 2023. The scope spans development studios, publishing entities, and ancillary service providers within the interactive entertainment ecosystem, as well as the association’s governance and advocacy functions.
Overall, the data illustrate a thriving, financially sound industry that is both internationally competitive and increasingly inclusive, supported by an association that leverages its surplus to reinforce member value and influence public policy.
- Canada’s video game industry experienced extraordinary expansion in 2023, solidifying its status as a global hub for development talent and creative output.
- Canadian studios achieved record-breaking international award recognition and critical acclaim throughout the 2023 calendar year.
- The sector deepened its export revenues in 2023, significantly increasing its contribution to the national digital economy.
- The Canadian Entertainment Software Association (ALD) ended the 2023 fiscal year with a substantial financial surplus resulting from robust membership growth and cost management.
- The ALD utilized its fiscal surplus to increase full-time staffing and enhance policy-making capacity while maintaining flat membership fees for existing constituents.
+1
ESAC – Entertainment Software Association of CanadaJan 2023
Report36 pages
State of the Game Development Industry 2023: Workplace Health & HR Culture, Mental Trends
The global game development industry entered a period of profound instability throughout 2023, characterized by widespread layoffs affecting 28% of the workforce and a pervasive crisis of employee loyalty. This volatility is reflected in a negative Employee Net Promoter Score of -19%, signaling deep-seated dissatisfaction across the sector. While economic recalibration and management failures are the primary drivers of this distress, only 3% of job losses are currently attributed to AI automation. Instead, the workplace is increasingly defined by "quiet hiring" practices, where 37% of employees take on expanded responsibilities without additional compensation, often coupled with unpaid overtime and insufficient severance packages.
Despite these hardships, remote and hybrid work models have become the industry standard, with 80% of professionals operating outside traditional office environments. Job seekers now prioritize salary, remote flexibility, and skill development above all else. However, a significant disconnect exists between employer expectations and worker reality. While 88% of firms prioritize industry expertise and portfolios over formal education, they simultaneously struggle to fill high-level specialist roles. This talent gap is exacerbated by a competitive market where 50% of professionals find suitable opportunities scarce, particularly entry-level candidates and marginalized groups who face heightened barriers to entry.
The most critical factor for improving retention and workplace culture is managerial mindfulness, specifically ethical leadership and empathy. Despite its statistical importance to employee satisfaction, only 13% of companies provide leadership training in these areas. As 70% of professionals report general dissatisfaction and 34% of companies have scaled back hiring, the industry faces a structural imbalance. Success in the current landscape requires a shift away from traditional recruitment and toward fostering supportive environments that address the mental health and professional growth of a demoralized workforce.
- The game industry experienced significant instability in 2023, with 28% of the workforce affected by layoffs and an Employee Net Promoter Score of -19% indicating widespread dissatisfaction.
- Economic recalibration and management failures are the primary drivers of industry distress, while AI automation currently accounts for only 3% of total job losses.
- Workplace culture is suffering from 'quiet hiring' practices, where 37% of employees are absorbing expanded responsibilities without corresponding increases in compensation.
- Remote and hybrid work models have become the industry standard, with 80% of professionals now operating outside of traditional office environments.
- A structural talent gap persists as 50% of professionals report a scarcity of suitable opportunities, despite 88% of firms prioritizing portfolios and expertise over formal education.
+1
80 LevelJan 2023
Report4 pages
Slovak Game Development Industry 2023
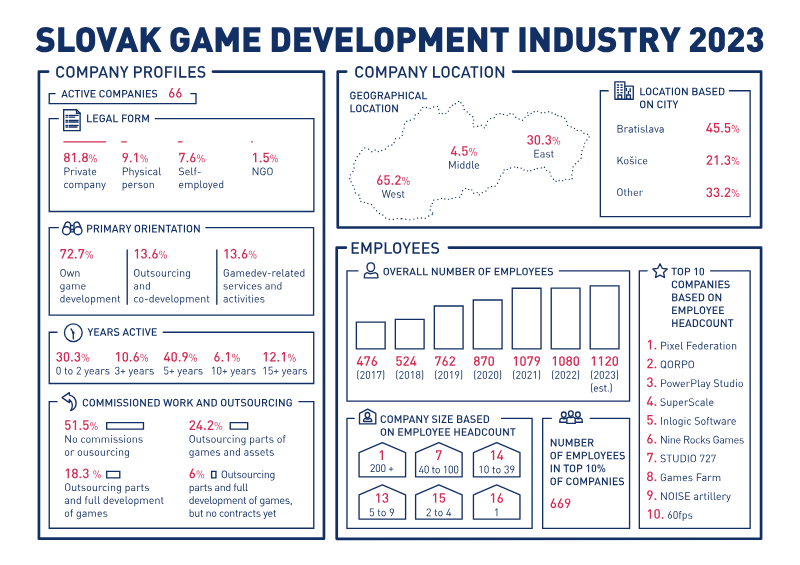
The Slovak game development industry in 2023 is characterized by a stable ecosystem of 66 active companies, primarily concentrated in the western region of the country. The sector is dominated by private entities, with 72.7% focusing on core game development and the remainder providing outsourcing or specialized services. While the industry features a mix of experience levels, over 40% of companies have been active for more than five years. The workforce has seen consistent growth, rising from 476 employees in 2017 to an estimated 1,120 in 2023. However, the industry exhibits significant centralization, with the top 10% of companies employing approximately 60% of the total workforce and generating 84.6% of the annual turnover.
Financial data indicates a mature but plateauing market, with an overall turnover of €77.1 million in 2022 and a nearly identical estimate of €76.9 million for 2023. Pixel Federation, SuperScale, and Inlogic Software lead the market in both headcount and revenue. Development is largely self-funded, though 37.9% of companies utilize public funding. PC remains the primary target platform for development, followed by mobile and consoles. Notably, half of all projects remain unpublished, while those that reach the market are predominantly self-published via digital storefronts like Steam, Google Play, and the App Store.
The labor market reveals a workforce with a median age of 30, where women represent 19% of the total headcount, primarily occupying roles in graphic arts and community management. Recruitment remains a challenge for specialized roles, particularly for programmers and game designers. To address talent shortages, nearly half of Slovak firms employ international staff, largely from Czechia and Ukraine. Operational trends show a decisive shift toward flexible work arrangements, with over 89% of companies utilizing remote or hybrid office models. Industry stakeholders express a strong desire for increased state support, specifically through tax incentives and improved education for the digital arts.
- The Slovak game industry is highly centralized, with the top 10% of companies accounting for 60% of the 1,120-person workforce and 84.6% of the total annual turnover.
- Industry revenue has plateaued, with turnover reaching €77.1 million in 2022 and an estimated €76.9 million in 2023.
- Pixel Federation, SuperScale, and Inlogic Software are the dominant market leaders in both headcount and revenue.
- The workforce has grown significantly since 2017, rising from 476 employees to 1,120 by 2023, though recruitment for specialized roles like programmers and designers remains difficult.
- While 89% of companies utilize remote or hybrid work models, firms are increasingly reliant on international talent, with nearly half employing staff from countries like Czechia and Ukraine.
+1
Slovak Game Developers AssociationJan 2023