1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticle GameDev Reports
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticleGameDev Reports
The global gaming industry experienced a significant transition throughout 2025 and into the first quarter of 2026. PC growth is currently outpacing console performance.
The global gaming industry experienced a significant transition throughout 2025 and into the first quarter of 2026, characterized by a shift in consumer spending habits and a divergence in platform performance. The PC and console sectors reached a combined valuation of $88.3 billion in 2025, with PC growth currently outpacing consoles. While total playtime across all platforms saw a marginal decline of 1%, the industry is moving away from a reliance on free-to-play models toward buy-to-play titles. PC remains the notable exception to this trend, as it is the only platform where free-to-play monetization efficiency improved year-over-year, supported by a robust ecosystem where over 5,800 games generated more than $100,000 in revenue during 2025.
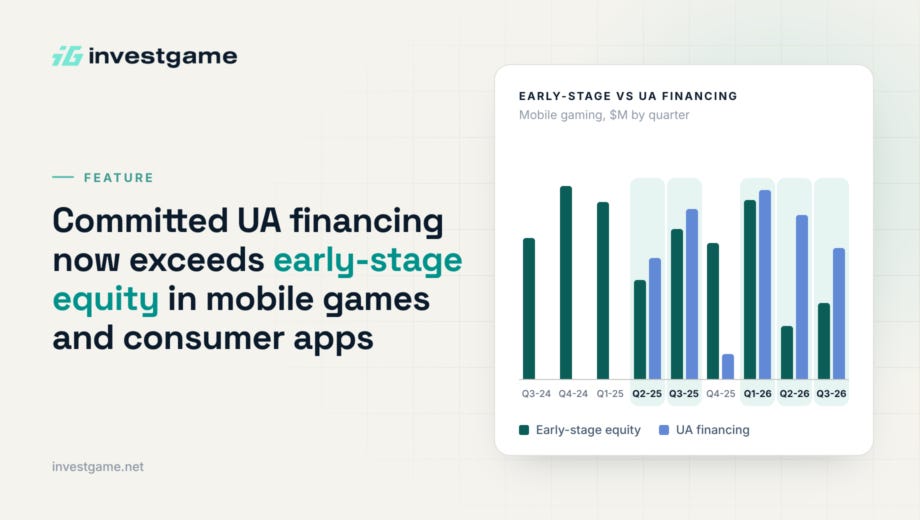
Market dynamics reveal a stark contrast between established platform health and the broader financial environment. While Steam and Nintendo continue to drive record revenue, the investment landscape remains bifurcated. The first quarter of 2026 saw $7.7 billion in merger and acquisition activity, heavily skewed by a single $6 billion transaction, yet public market sentiment remains bearish. Gaming stocks have largely declined, with mobile-focused firms suffering the most significant valuation drops. This volatility is mirrored in the private sector, where early-stage fundraising has hit a five-year low, making it increasingly difficult for new developers to secure capital despite the overall growth of the PC and console markets.
Ultimately, the industry is undergoing a structural realignment toward sandbox genres and more diversified revenue models. Although major franchises continue to command significant engagement, the decrease in market concentration by playtime suggests a more fragmented and competitive landscape. As the industry moves forward, the disparity between the record-breaking performance of established platforms and the tightening of early-stage investment suggests that future growth will likely favor developers capable of navigating shifting monetization preferences rather than those relying on traditional free-to-play engagement metrics.
 ValveCompany · United States · founded 1996 · 528 documents
 Crimson Desert EnhancedGame · Pearl Abyss · 2026 · 54 documents
 Pearl AbyssCompany · South Korea · founded 2010 · 33 documents
 BungieCompany · United States · founded 1991 · 176 documents
 Death Stranding 2: On the BeachGame · Kojima Productions · 2025 · 40 documents
 CairnGame · The Game Bakers · 2026 · 7 documents
 The Game BakersCompany · France · founded 2010 · 5 documents
 Hooded HorseCompany · United States · founded 2019 · 21 documents
 Mouse: P.I. For HireGame · Fumi Games · 2026 · 5 documents
 Fumi GamesCompany · Poland · 4 documents
Each row is a game or company this document names, each column a document, oldest first. A mark means that document names it. Select a row to see those documents.
GameDev Reports · 2026
GameDev Reports · 2026
Jason Schreier · 2026