ArticleGameDev Reports
Asia Game Buzz & GameDev Reports: China’s Steam & PC Gaming Market in 2025
9 Jun 20261 page~5 min full read
The market is supported by an estimated 683 million players nationwide. Client-based PC games constitute 22.3% of total market revenue.
China’s gaming market is projected to reach a valuation of $51.8 billion in 2025, supported by an estimated 683 million players nationwide and a Steam user base of 42.4 million within the country, compared with 89.6 million global Steam players. Client-based PC games—both premium and free-to-play—constitute 22.3% of total market revenue, roughly $11–12 billion. The legal console segment remains modest at an estimated $1.1–$1.2 billion, with Steam dominating PC/console monthly active users at 87%, while PlayStation, Nintendo, and Xbox capture 6%, 5% and 2% respectively. Console players numbered over 16.7 million by end-2022, generating about $2.3 billion in revenue.
Key distribution channels for PC titles include Heybox (primary), TapTap, and Sonkwo; marketing should focus on Heybox, Bilibili, Douyin, Xiaohongshu (RED), and Weibo. Steam remains the most significant platform for PC gaming, yet a multi-platform presence is advised due to fragmented user habits. Popular genres on Steam in China are action/shooters (33%), RPG/adventure (24%), and simulation/management (16%). Pricing averages 20–37% lower than Western markets, a factor to consider when setting launch prices.
Major events such as ChinaJoy (410 k visitors) and Bilibili World (300 k visitors) offer high-visibility opportunities, though competition is intense; smaller events can also be strategic. Merchandise sales are growing rapidly, with over 100 million users searching for gaming-related products in 2025. The report draws on publicly available Chinese data, compiling over 20 sources to provide a directional overview rather than definitive figures.
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDev Reports · 2026
GameDiscoverCo · 2026
The Game Business · 2026
GameDiscoverCo · 2026
PocketGamer.biz · 2026
Deconstructor of Fun · 2026
Extra Credits · 2026
The Game Business · 2026
Naavik · 2026
Deconstructor of Fun · 2025
Extra Credits · 2025
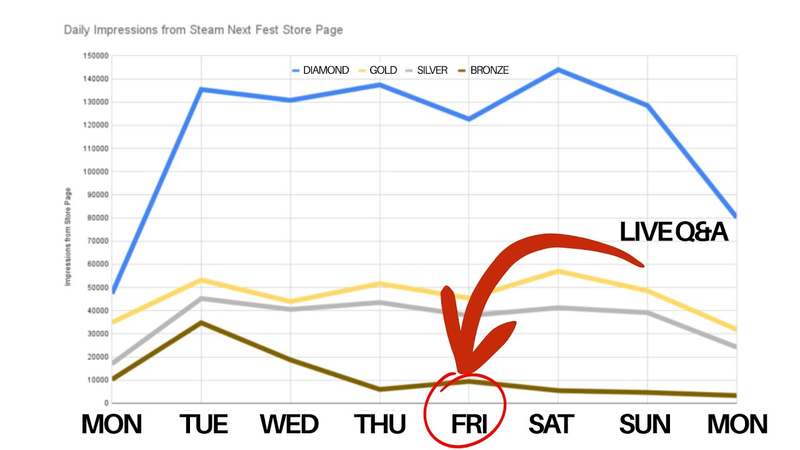
How To Market A Game · 2025
Jonas Tyroller · 2025
Comments