PC & Console
Steam, consoles, cross-platform play and cloud gaming.
145 documents
Korea Creative Content Agency
ReportKorea's Game Studios: Where the Next Breakout Title Is Actually Built
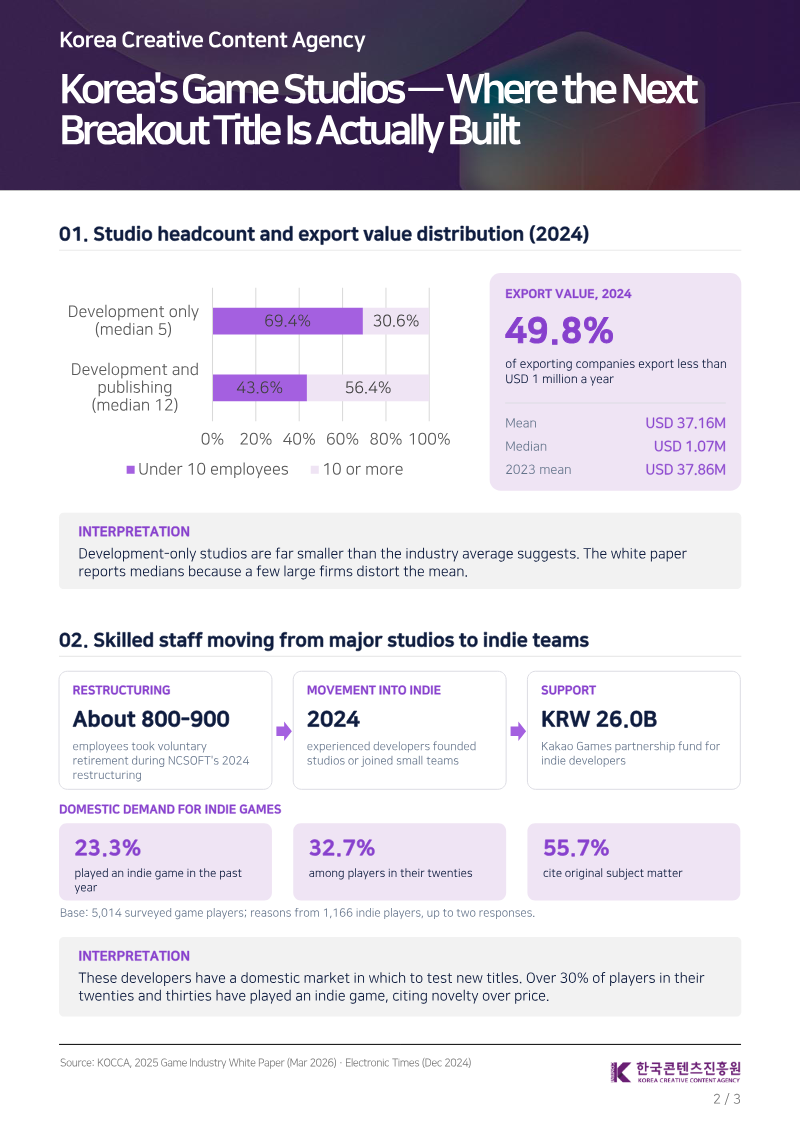
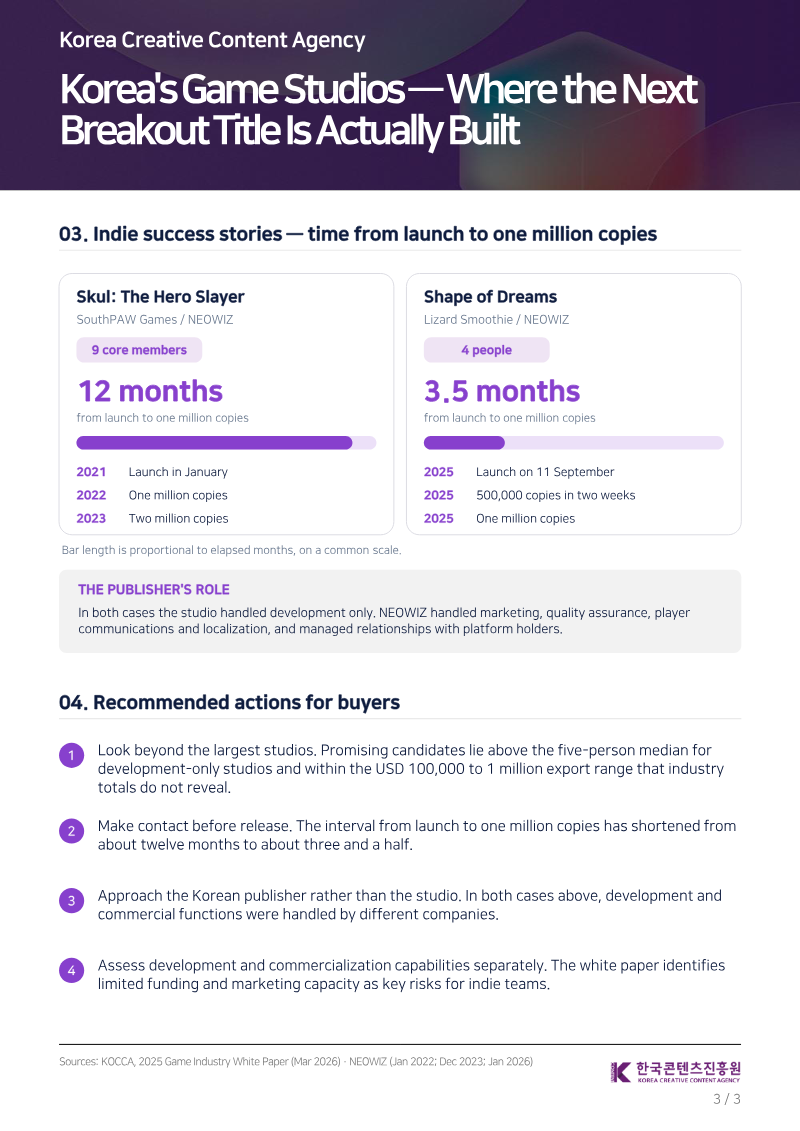
The South Korean gaming landscape is currently defined by a significant structural shift toward small-scale, high-impact development studios. While industry-wide averages are often skewed by a few massive publishers, the reality of the market is that 69.4% of development-only firms employ fewer than ten people. This segment has been bolstered since 2024 by an influx of experienced talent departing major publishers, creating a robust ecosystem of indie teams capable of producing breakout titles. Data indicates that these smaller studios are increasingly efficient, with some teams of as few as four people reaching one million copies sold in just three and a half months. The domestic market serves as a vital testing ground for these developers, as over 30% of players in their twenties and thirties actively engage with indie games, prioritizing original subject matter over pricing. Despite this creative success, these studios often face limitations in funding and marketing capacity. Consequently, the commercialization of these titles is frequently decoupled from development, with major publishers managing localization, quality assurance, and platform relations. Half of all exporting companies in this sector currently generate less than USD 1 million in annual export value, highlighting a vast, untapped middle market. For international buyers and stakeholders, the primary takeaway is the necessity of looking beyond the largest, most visible firms. Successful acquisition and partnership strategies require engaging with studios that exceed the five-person median while simultaneously negotiating with the Korean publishers who handle the commercial infrastructure. Because the time-to-market for breakout hits has accelerated significantly, early engagement is essential. Buyers should evaluate development and commercialization capabilities as distinct entities to mitigate the risks associated with the limited operational resources of smaller indie teams.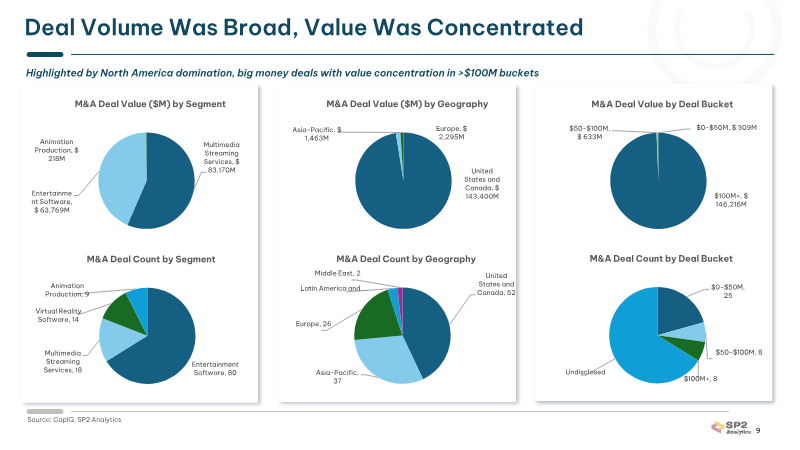
SP2 Analytics
ReportGlobal Gaming Report 2025
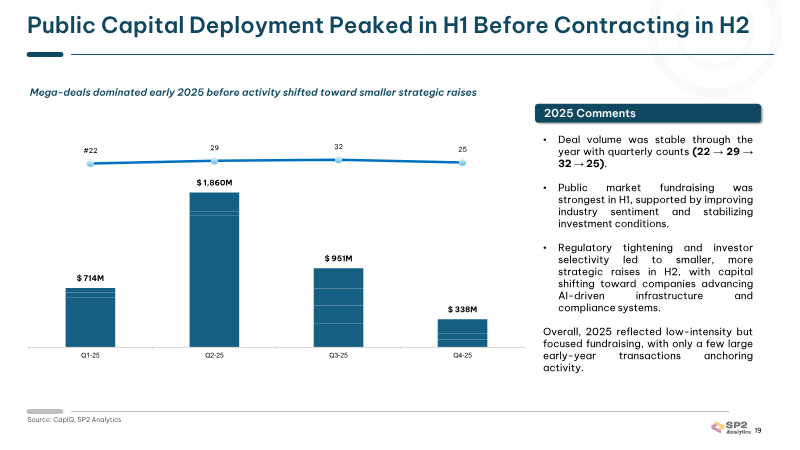
The 2025 Global Gaming Report characterizes the gaming industry as a capital-intensive, scale-driven sector where competitive advantage is increasingly defined by platform ownership, intellectual property (IP) aggregation, and long-term strategic positioning rather than individual title performance. The industry experienced a year of mega-deal consolidation, with approximately $147 billion in announced M&A value. This activity was heavily skewed toward the second half of the year, anchored by transformational transactions such as the $83 billion Netflix-Warner Bros. deal and the $55 billion take-private of Electronic Arts. Market data indicates a widening valuation dispersion, with strategically positioned players commanding premium EV/EBITDA multiples exceeding 25x. While overall deal volume moderated throughout 2025, capital deployment became more concentrated, reflecting high-conviction investments in defensible growth platforms. Private placement activity followed a similar trend, dominated by a limited number of large-scale, infrastructure-led rounds—notably in AI-driven simulation and development tools—which attracted over $100 million per transaction. Public market activity was strongest in the first half of the year, shifting toward smaller, more disciplined strategic raises as regulatory and market conditions evolved. Geographically, North America dominated both M&A and private placement deal values, while the Asia-Pacific region maintained a significant presence in public market capital raises. The report utilizes data sourced from CapIQ and internal research to analyze these trends across global gaming segments, including multimedia streaming, entertainment software, and virtual reality. Looking ahead to 2026, the industry anticipates a content-led growth phase driven by major IP sequels and hardware transitions, such as the rollout of the Nintendo Switch 2, as companies pivot toward service-led, recurring revenue models to ensure long-term stability.
TP
ReportGaming Trendz to Watch in 2025 and Beyond: Comprehensive Player Support Strategies
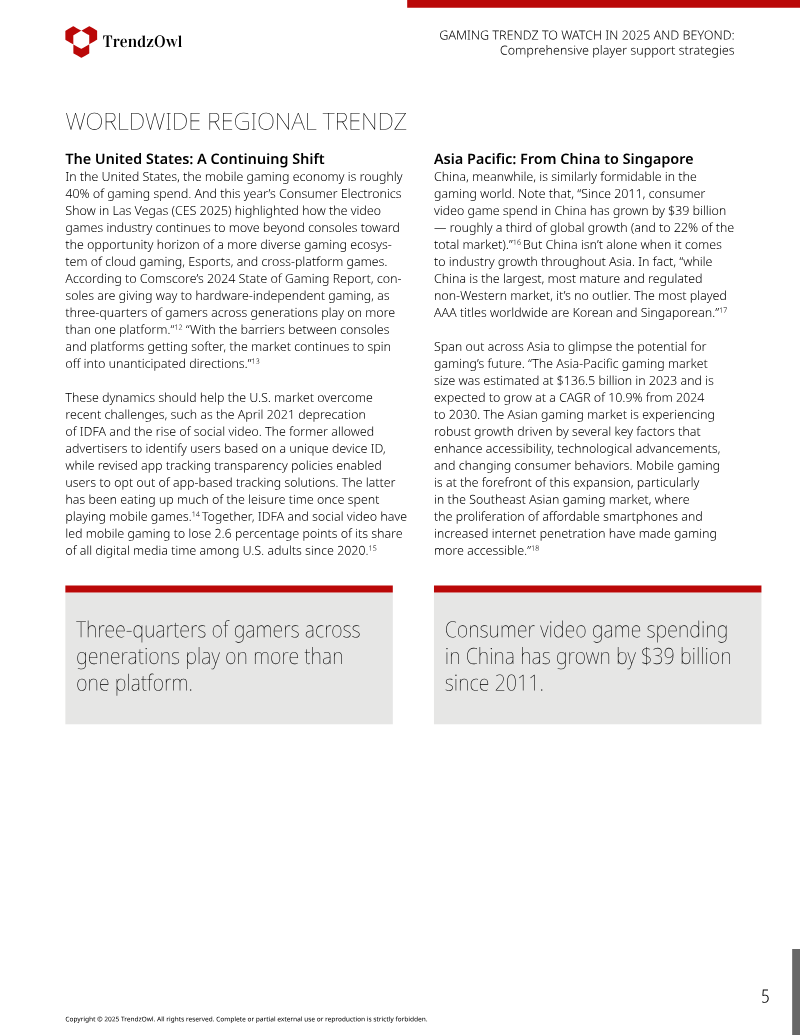
The video game industry is poised for a significant rebound in 2025 following a period of contraction characterized by layoffs and project cancellations. The sector is currently transitioning toward a mobile-first, cloud-enabled future where hardware-independent gaming is becoming the standard. This shift is supported by the rapid growth of mobile gaming, which now accounts for 55% of the total market, and the increasing ubiquity of cloud technology that allows for cross-platform accessibility. Regional analysis indicates robust expansion, with Africa’s market growing six times faster than the global average and the Asia-Pacific region maintaining a strong compound annual growth rate of 10.9% through 2030. To navigate this evolving landscape, the industry must prioritize sophisticated player support strategies that balance technological efficiency with human-centric engagement. Data suggests that providing a diverse range of contact options increases player loyalty by 41%. While AI-driven personalization is essential for managing complex, data-heavy environments, human advisors remain critical for resolving sensitive billing issues, enforcing community guidelines, and moderating player interactions to prevent toxicity. The analysis draws on a variety of industry data sources, including the 2024 Global Insights Survey, market forecasts from Newzoo and Grand View Research, and reports from regional gaming organizations. The findings emphasize that as gaming becomes a primary social venue—with 81% of players reporting that the medium facilitates connections they would not otherwise form—the responsibility of developers to foster safe, inclusive, and empathetic environments has become a core business imperative. Ultimately, the industry’s long-term success depends on integrating high-quality technical support with a commitment to community health and human-led judgment.
InvestGame
ReportState of Gaming & Influencer Marketing 2025
The global gaming industry is currently navigating a transition from a period of stagnation between 2022 and 2024 toward a more resilient, diversified future. While early-stage venture capital has receded from its 2021 peak, the sector is stabilizing through increased merger and acquisition activity and a projected expansion of the global player base to nearly 4 billion by 2027. Mobile gaming remains the primary revenue driver, accounting for 55 percent of market growth and generating $80.9 billion in 2024, even as download volumes face slight contraction. Concurrently, the PC and console markets are evolving, with software revenues increasingly reliant on subscription models and add-on content rather than traditional full-game sales. The influencer marketing landscape is undergoing a parallel transformation, projected to reach a valuation of $32.55 billion by 2025. Brands are moving away from broad, reach-based promotional tactics toward long-term, narrative-driven partnerships that prioritize authentic community engagement. This shift is supported by the rise of nano-influencers, who currently command engagement rates exceeding 10 percent on platforms like TikTok, and the integration of advanced AI tools for campaign management and data-driven targeting. The emergence of new streaming platforms, such as the rapid growth of Kick and the regional expansion of Chzzk, further underscores the need for multi-channel strategies. Ultimately, the industry is defined by a strategic pivot toward cross-platform experiences and creative excellence. Success in this environment requires a balanced approach that leverages both established platforms like Steam and emerging social channels to foster lasting player loyalty. As studios and brands move toward more targeted, value-driven content, the integration of generative AI and the professionalization of the creator economy will remain central to sustaining growth and navigating the complexities of a global, multi-device gaming ecosystem.
Newzoo
ReportThe PC & Console Gaming Report 2024
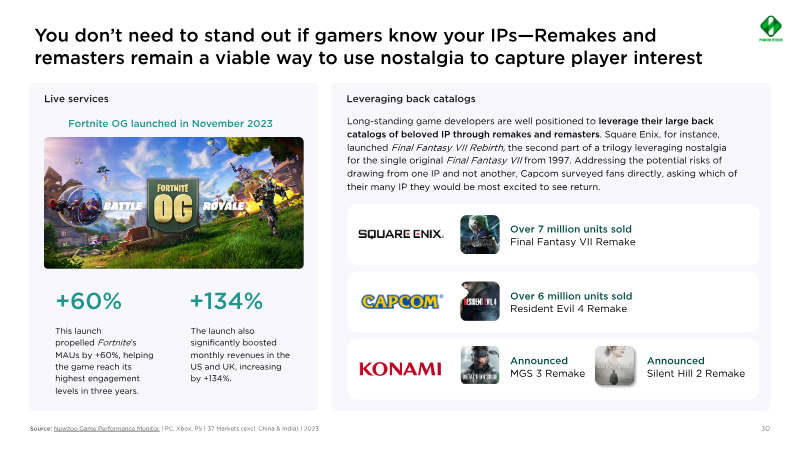
The global PC and console gaming market reached $93.5 billion in 2023, reflecting a modest 2.6% growth rate. Despite this financial expansion, the industry faces a challenging structural shift characterized by a 26% decline in total playtime since 2021. As pandemic-era engagement habits wane, the market has become increasingly consolidated, with a small cohort of evergreen titles—many over six years old—capturing more than 60% of total player engagement. This environment creates a high barrier to entry for new releases, which must compete against established franchises and dominant live-service behemoths for a shrinking pool of player attention. To navigate this saturated landscape, publishers are prioritizing risk mitigation through the development of remakes, sequels, and transmedia adaptations. While the competition for engagement is intense, breakout successes remain possible for titles that effectively leverage community feedback, viral social mechanics, and refined gameplay loops. Furthermore, the industry is witnessing a transition toward cross-platform play, as users who engage across multiple devices demonstrate significantly higher levels of financial and temporal investment. Future growth strategies are increasingly focused on geographic diversification and technological accessibility. Developers are encouraged to target emerging markets where player populations are expanding more rapidly than in traditional regions. By utilizing cloud gaming to bypass hardware limitations and implementing localized monetization and distribution strategies, studios can reach broader demographics. Ultimately, sustaining long-term viability in the current climate requires a shift away from reliance on domestic saturation toward a more flexible, multi-platform, and globalized approach to player acquisition and retention.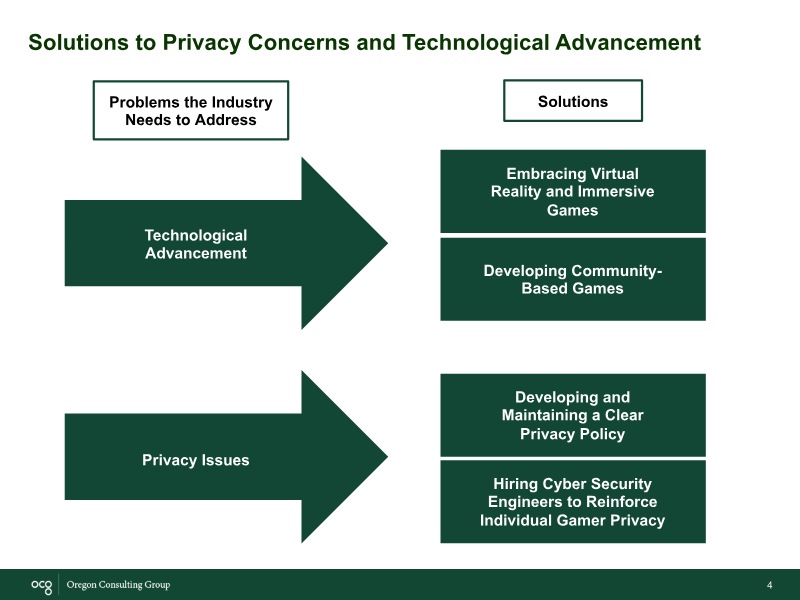
Lundquist College of Business
ReportU.S. Video Game Industry: Technological Advancements and Privacy Issues
The U.S. video game industry, a significant global economic force, faces a critical juncture defined by rapid technological evolution and escalating privacy vulnerabilities. As of 2020, the sector generates $60.4 billion in annual revenue, supported by 240,000 employees across more than 42,000 businesses. While the industry has demonstrated resilience and growth during the COVID-19 pandemic—evidenced by surging engagement on platforms like Steam and Twitch—it must navigate complex challenges to maintain long-term stability and consumer trust. Privacy concerns represent a primary threat, driven by the widespread collection of player data and the persistent risk of cyberattacks. With over 12 billion cyberattacks recorded against gaming websites within a 17-month period, the industry faces significant pressure to secure user information. The re-identification of supposedly anonymized data and the use of psychometric evaluations in games have heightened these risks. To mitigate these threats, the industry is advised to adopt more transparent, user-friendly privacy policies and invest in specialized cybersecurity engineering to protect player credentials, a strategy already successfully employed by major players like Microsoft. Simultaneously, the industry must adapt to shifting consumer expectations regarding artificial intelligence and virtual reality. The demand for immersive, community-based gaming experiences has intensified, as seen in the success of titles like Pokémon Go. By integrating advanced technologies such as text-to-speech software and AI-driven character development, companies can optimize production lifecycles and enhance engagement. Ultimately, the industry’s ability to balance aggressive technological innovation with robust, transparent security measures will determine its capacity to sustain its current market dominance and satisfy an increasingly privacy-conscious consumer base.
Bandai Namco
ReportBandai Namco Group Fact Book
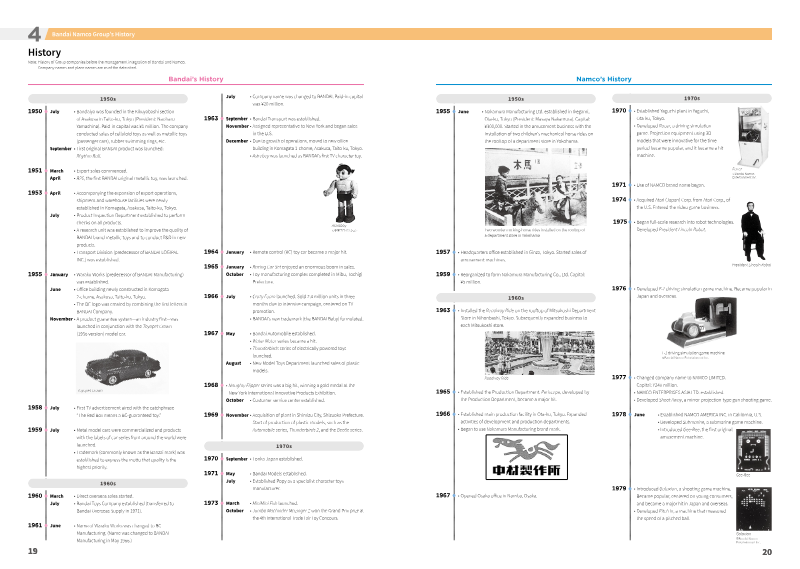
Bandai Namco Group maintains a dominant position in the global entertainment industry by leveraging a robust portfolio of intellectual property to drive consistent financial growth. For the fiscal year ending March 2025, the organization achieved significant expansion, reporting consolidated net sales of ¥1,241,513 million. This performance is anchored by a diversified business model where the Toys and Hobby unit serves as the primary revenue driver at 45.2% of total sales, followed closely by the Digital unit at 34.5%. The group’s strategic trajectory is defined by a commitment to IP-led innovation, spanning model kits, card products, and digital gaming, which has allowed the company to sustain market leadership across international territories. The group’s evolution from the 2005 integration of Bandai and Namco to its current three-unit organizational structure reflects a long-term strategy of diversification and global scaling. Historical milestones, including the development of iconic franchises such as Gundam, PAC-MAN, and Tamagotchi, underscore a consistent focus on creative development and intellectual property protection. Recent years have seen further commercial success through high-profile titles like ELDEN RING and the expansion of amusement facilities, all operating under a unified vision to deepen engagement with global fan bases. Beyond financial and creative output, the organization integrates rigorous ESG standards into its core operations. Current initiatives prioritize carbon management, with significant investments in renewable energy and a reduction in Scope 1 and 2 emissions. Governance remains a priority, characterized by a clean record regarding anti-competitive behavior and corruption. Furthermore, the company demonstrates a commitment to human capital through extensive employee training programs and a measurable increase in female representation within management, which reached 23.7% by 2025. These efforts reflect a holistic approach to corporate sustainability, ensuring that long-term growth is balanced with social responsibility and ethical supply chain management.
Microsoft
PresentationMicrosoft Windows Azure Gaming Summit: Overview of and Future Outlook on the Global Games Market
The global games market is undergoing a fundamental transformation, shifting from a product-based model to a service-oriented ecosystem driven by cloud connectivity and multi-screen engagement. As of 2012, the industry generated $66.3 billion in global revenue, with 967 million gamers worldwide. The market is characterized by a transition toward free-to-play business models, which now account for a significant majority of revenue across mobile and digital platforms. This evolution requires developers to prioritize continuous player engagement, data-driven monetization, and cross-platform accessibility to remain competitive. The industry’s growth is increasingly defined by the proliferation of screens, with gamers now frequently utilizing television, PC, tablet, and smartphone devices simultaneously. This multi-screen behavior, coupled with the rise of cloud infrastructure, allows for seamless content streaming, real-time data analysis, and global scalability. Regional performance varies significantly, with Asia-Pacific leading in total revenue at $22.4 billion, followed by North America at $22.5 billion and Europe at $18.7 billion. Emerging markets are showing rapid growth, with mobile spending patterns in countries like Russia and Japan increasingly rivaling those of established Western markets. Methodologically, these insights are derived from a combination of financial company data, primary consumer research, and actual transaction records. The analysis emphasizes that the cloud serves as the essential backbone for this new era, enabling companies to bypass traditional hardware limitations and manage games as live services. To succeed, organizations must adopt flexible, scalable architectures that support global localization and sophisticated, real-time monetization strategies. Ultimately, the ability to maintain a continuous, balanced relationship with both free and paying players across multiple devices has become the primary indicator of long-term commercial viability in the modern gaming landscape.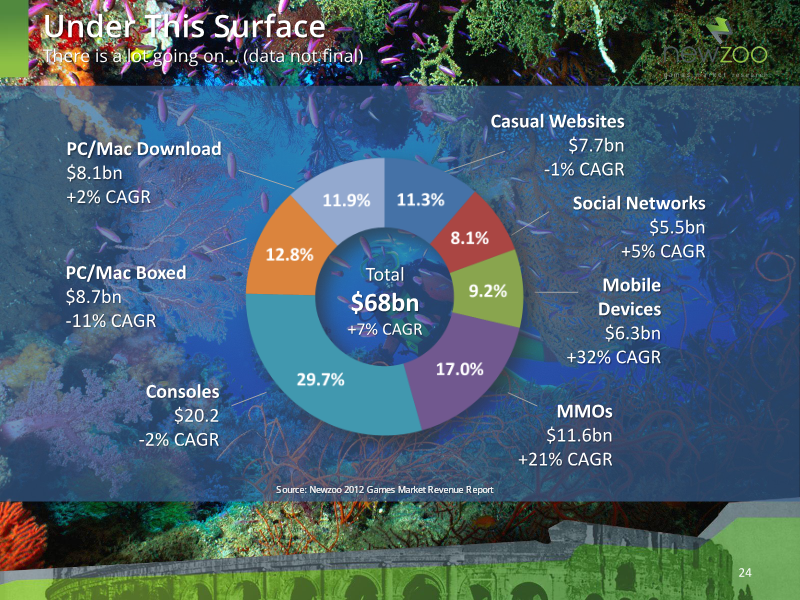
Newzoo
ReportImpact of Free-to-Play: Online, Mobile & Cross-Platform
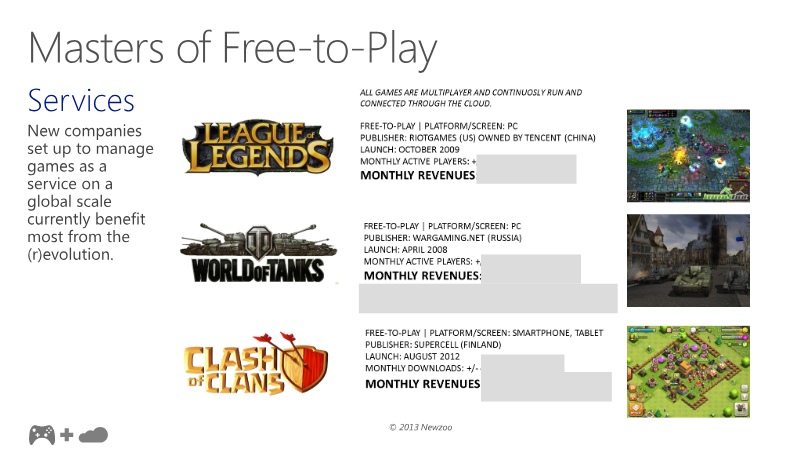
The global games industry is undergoing a fundamental transformation as the traditional boxed product model stagnates in favor of free-to-play mechanics and cross-platform accessibility. As of 2012, the market is shifting toward a service-oriented ecosystem where mobile devices and massively multiplayer online games serve as the primary engines for growth. Mobile revenue is projected to expand at a compound annual growth rate of 32 percent, significantly outpacing the decline of dedicated handheld consoles. This transition necessitates a departure from legacy revenue-only metrics, requiring publishers to prioritize granular tracking of player engagement time and the conversion rates of paying users to ensure long-term sustainability. Success in this evolving landscape depends on treating free-to-play as a holistic business strategy rather than a mere pricing tactic. Titles such as League of Legends and Kingdoms of Camelot demonstrate that profitability is increasingly tied to continuous service updates and the ability to capture value across multiple hardware environments. The integration of the Screen Segmentation Model reveals that while computer screens remain the primary venue for total playtime, a growing cohort of high-value gamers now fluidly transitions between entertainment, personal, and mobile screens. Major retailers are responding to this trend by aggressively integrating free-to-play models to secure market share. Ultimately, the industry is moving toward a multi-device reality where consumer spending is no longer tethered to a single platform. While the paying demographic remains predominantly male, the expansion of mobile monetization is creating a global footprint that challenges established retail norms. To remain competitive, publishers must reorganize their operations to support cross-platform experiences that provide consistent value, as modern players increasingly distribute their gaming budgets across a diverse array of digital touchpoints.
Newzoo
PresentationThe eSports Industry to Date: The Drivers Behind Current and Future Growth
The global esports industry is undergoing a rapid transformation from a niche gaming subculture into a significant, multi-billion dollar economic force. Driven by high levels of player engagement and massive viewership on platforms like Twitch, the sector is successfully transitioning toward mainstream adoption. This evolution is underpinned by increasing professionalization, strategic investments from major media and hardware corporations, and the emergence of diverse, direct revenue streams that capitalize on a highly valuable, digitally savvy demographic. Financial data from 2015 underscores this momentum, with industry revenues reaching $252 million and establishing a clear trajectory toward a $1 billion economy by 2019. This growth is fueled by a complex interplay of evolving game genres, supportive regulatory frameworks, and the convergence of traditional and digital media. Notable indicators of this expansion include record-breaking crowdfunded prize pools, such as the $18 million generated for The International, and substantial venture capital injections, exemplified by the $26 million investment in Super Evil Megacorp. The industry’s current high-growth phase is characterized by enthusiasts who actively participate in betting, fantasy leagues, and multi-screen consumption. As the market matures beyond the volatility seen in previous decades, the focus has shifted toward sustaining this expansion through 2017 and beyond. Ongoing success depends on the continued tracking of audience trends and revenue metrics, ensuring that stakeholders can effectively navigate the sector's rapid development and capitalize on the deepening integration of consumer-generated content and professionalized streaming ecosystems.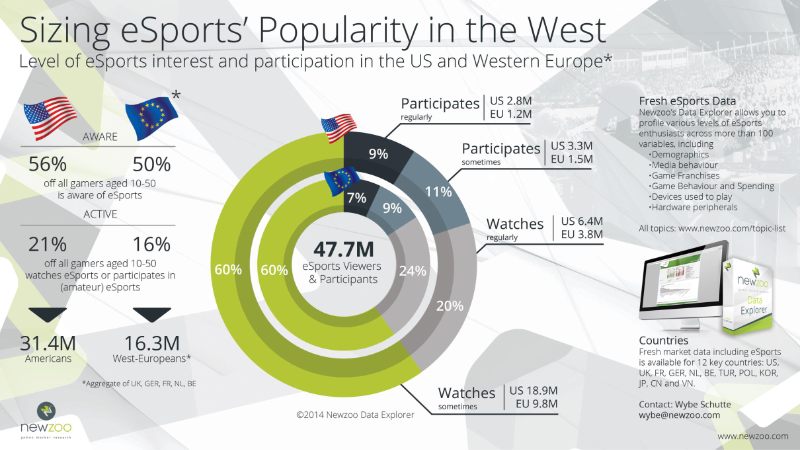
Newzoo
ReportSizing & Profiling eSports' Popularity: The West
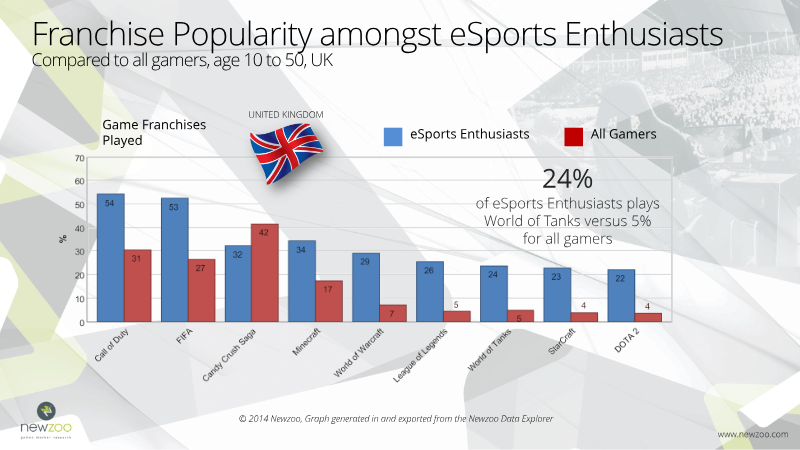
The rapid expansion of eSports in Western markets represents a significant shift in the gaming industry, driven by the rise of free-to-play titles such as League of Legends, Dota 2, and World of Tanks. This growth is characterized by a transition where time spent engaging with game franchises has become a critical key performance indicator, often serving as a precursor to increased monetary spending. As eSports viewership continues to double year-over-year, major publishers and global brands are increasingly utilizing competitive gaming as a primary marketing vehicle to reach affluent young males aged 18 to 34. Data indicates that eSports enthusiasts are highly dedicated, with average viewers watching over ten times per month for sessions lasting approximately 2.2 hours. The demographic profile of these participants is notably valuable to advertisers; for instance, 22% of eSports enthusiasts are identified as big spenders on games, compared to only 8% of the general gaming population. Furthermore, these enthusiasts demonstrate higher professional stability and engagement across multiple platforms, including console and mobile gaming, than the average gamer. The scope of this analysis covers the United States and Western Europe, utilizing primary consumer research to profile engagement levels across various demographics and media behaviors. The findings highlight that eSports has evolved from a niche interest into a mainstream phenomenon, with major tournament prize pools reaching millions of dollars and concurrent viewership figures rivaling traditional sports events. This research underscores the strategic importance of competitive gaming for companies seeking to maximize user retention and monetization in an increasingly crowded digital entertainment landscape.
Newzoo
Report