Koei Tecmo
Game Co.173 documents
Japanese developer/publisher. Dynasty Warriors, Nioh, Dead or Alive, Atelier, Romance of the Three Kingdoms.
Documents

Financial6 pages
Consolidated Financial Results: Nine Months Ended December 31, 2023
The consolidated financial results for the nine months ended December 31, 2023 demonstrate a strong rebound in sales and profitability compared with the same period in 2022. Net sales rose to ¥61,136 million, an increase of 23.7 % from ¥49,439 million in 2022, while operating profit fell modestly to ¥20,316 million (‑11.7 % versus ¥22,994 million). Ordinary profit and profit attributable to owners of the parent company both increased sharply, reaching ¥33,825 million (‑100.4 % versus ¥16,880 million) and ¥24,283 million (‑80.2 % versus ¥13,477 million), respectively. Basic earnings per share climbed to ¥76.95 (¥71.61 in 2022). Comprehensive income for the period was ¥30,129 million, a dramatic turnaround from ¥59 million in 2022.
Total assets grew to ¥244,844 million, up from ¥210,889 million at the end of March 2023, while net assets increased to ¥157,595 million, reflecting a capital adequacy ratio of 64.1 %. Shareholders’ equity rose to ¥158,208 million, supported by retained earnings of ¥153,561 million. The company’s dividend policy remains unchanged; no dividends were paid in fiscal year 2023, and a forecast of ¥50 million per share is maintained for fiscal year 2024.
The financial statements cover the entire Japanese market, covering all operating segments of Koei Tecmo Holdings. The reporting period spans April 1 2023 to December 31 2023, with a forecast for the full fiscal year ending March 31 2024. Data are presented under Japanese GAAP, with no significant changes in accounting policies or estimates noted for the period.
- Koei Tecmo Holdings reported a 23.7% increase in net sales to ¥61,136 million for the nine months ended December 31, 2023, compared to the same period in 2022.
- Profit attributable to owners of the parent company rose 80.2% to ¥24,283 million, while ordinary profit increased 100.4% to ¥33,825 million.
- Operating profit declined by 11.7% to ¥20,316 million, despite the significant growth in net sales and other profit metrics.
- Comprehensive income saw a major turnaround, reaching ¥30,129 million for the period compared to ¥59 million in the prior year.
- Total assets grew to ¥244,844 million as of December 31, 2023, up from ¥210,889 million at the end of March 2023, with a capital adequacy ratio of 64.1%.
+1
Koei Tecmo
Financial15 pages
Financial Results for the Third Quarter: Fiscal Year Ending March 2024
The quarterly financial release outlines KOEI TECMO HOLDINGS CO., LTD.’s performance for the first nine months of fiscal 2023, ending March 2024. Total sales rose 23.7 % YoY to ¥61,136 million, driven primarily by new mobile titles that boosted online and mobile game revenue. Operating profit fell 11.7 % to ¥20,316 million due to higher platform, royalty and advertising costs associated with the expanded title portfolio. Ordinary profit increased 100.4 % to ¥33,825 million and net profit grew 80.2 % to ¥24,283 million, largely supported by gains from marketable securities and other non‑operating items.
Geographically, Japan contributed 61.1 % of sales while overseas sales accounted for 38.9 %, with the United States and Europe showing modest declines in unit volumes but maintaining strong digital sales. The entertainment segment recorded a 24 % YoY sales increase, with mobile and online channels contributing 47.1 % of segment revenue; console package sales declined by 10.3 %. Digital sales ratio for the entertainment sector rose to 84.2 %, reflecting a shift toward downloadable content and mobile downloads.
Cost analysis revealed a 12.9 % rise in employment costs, a 78.8 % jump in subcontracting expenses, and a 92.8 % increase in advertising spend, all linked to new title launches. The company maintains its FY2024 operating profit target of ¥37,500 million, citing anticipated revenue from the March release of “Rise of the Ronin” and continued expansion in mobile markets.
- Koei Tecmo’s total sales for the first nine months of fiscal 2023 rose 23.7% year-over-year to ¥61,136 million, driven primarily by strong performance in mobile and online gaming.
- Operating profit declined 11.7% to ¥20,316 million, as increased investment in advertising (up 92.8%), subcontracting (up 78.8%), and employment costs outweighed revenue gains.
- Net profit surged 80.2% to ¥24,283 million and ordinary profit grew 100.4% to ¥33,825 million, bolstered significantly by gains from marketable securities and non-operating items.
- The entertainment segment’s digital sales ratio reached 84.2%, with mobile and online channels now accounting for 47.1% of segment revenue while console package sales fell 10.3%.
- Overseas markets accounted for 38.9% of total sales, with the United States and Europe experiencing a decline in unit volumes despite stable digital revenue.
+3
Koei Tecmo

Financial39 pages
Financial Results: Fiscal Year Ending March 2024
for the Fiscal Year Ending March 2024 FY22 FY23 Vs Previous Year Full Year Full Year Amount Ratio Amount Ratio Amount % Change Sales 78,417 - 84,584 - 6,167 7.9% Operating Profit 39,133 49.9% 28,494 33.7% △ 10,639 -27.2% Ordinary Profit 39,899 50.9% 45,741 54.1% 5,842 14.6% Net Profit 30,935 39.4% 33,792 40.0% ...
- KOEI TECMO HOLDINGS CO., LTD. missed its FY23 sales target by 11.0% (¥10,416 million) and operating profit target by 24.0% (¥9,006 million), primarily due to lower-than-expected sales of new console and mobile titles, underperforming repeat sales of FY22 titles, and one title being delayed to FY24.
- Despite missing sales and operating profit targets, Ordinary Profit for FY23 exceeded the plan by 12.9% (¥5,241 million) and Net Profit exceeded the plan by 9.0% (¥2,792 million).
- Total unit sales for FY23 decreased by 23.9% to 7.34 million units compared to FY22, with overseas sales declining by 26.5% and Japan sales by 18.0%. Digital sales constituted 69.6% of total sales, an increase of 2.6 percentage points from FY22.
- Online and mobile sales achieved a new record high in FY23, driven by multiple new in-house developed mobile titles, establishing stable earnings in a competitive market.
- For FY24, the company projects a conservative plan with sales increasing by 6.4% to ¥90,000 million and operating profit increasing by 5.3% to ¥30,000 million, based on repeat console sales, monthly online/mobile sales, and IP licensing royalties.
+2
Koei Tecmo
Financial22 pages
Financial Results for the First Quarter of Fiscal Year Ending March 2025
The quarterly financial release presents KOEI TECMO HOLDINGS’ first‑quarter fiscal 2025 results, showing a modest decline in consolidated sales to ¥17.6 billion from ¥18.3 billion, a 3.8 % year‑over‑year drop driven mainly by reduced console and online/mobile sales. Operating profit fell ¥1.8 billion to ¥5.7 billion, a 23.8 % decline, while ordinary and net profits rose to ¥18.7 billion and ¥13.6 billion, respectively, reflecting higher operating leverage and lower tax rates.
Segment analysis indicates the entertainment division—encompassing console, download, DLC, and mobile titles—experienced a 3.1 % sales decline, with physical console units down 7.4 % and digital download units falling 5.9 percentage points. The amusement segment’s consignment sales dropped sharply, whereas real‑estate sales saw a modest increase in operating profit due to reduced repair costs. Regional performance shows Japan’s contribution falling 6.9 %, while overseas sales grew marginally (0.5 %) and Europe experienced a 101.7 % jump, driven by new title launches.
Cost structure shifts include a slight reduction in COGS and outsourcing expenses, offset by increased variable costs. Headcount rose 7.9 % to 2,736 employees, with employment and advertising costs trending upward. The company maintains its FY2024 guidance unchanged, targeting ¥90 billion in sales and a 33.3 % operating profit margin, supported by planned releases of major titles such as “Romance of the Three Kingdoms 8” and “Fairy Tail 2.” The TSE Prime listing compliance remains close to the 35 % tradable‑share threshold, with planned treasury conversion actions.
- Koei Tecmo’s Q1 FY2025 operating profit fell 23.8% to ¥5.7 billion, while consolidated sales declined 3.8% year-over-year to ¥17.6 billion.
- Net profit rose to ¥13.6 billion due to higher operating leverage and lower tax rates, despite the decline in core operating income.
- The entertainment division saw a 3.1% sales decline, characterized by a 7.4% drop in physical console units and a 5.9 percentage point decrease in digital downloads.
- Regional performance was mixed, with Japan sales falling 6.9% while European sales surged 101.7% due to new title launches.
- Operating costs increased as headcount grew 7.9% to 2,736 employees, alongside rising advertising and variable expenses.
Koei Tecmo
Financial22 pages
Financial Results for the First Quarter: Fiscal Year Ending March 2025
Financial results for the first quarter of fiscal year ending March 2025 show a modest decline in consolidated sales to ¥17.6 billion, down 3.8 % YoY and 24.9 % QoQ, driven by weaker console sales after a strong launch in the prior quarter and declining online/mobile revenue from titles introduced in 2023. Operating profit fell ¥1.78 billion, a 23.8 % YoY drop and 30 % QoQ decline, largely due to higher variable costs from an expanded mobile portfolio and reduced partner‑covered development expenses. Ordinary profit rose ¥4.02 billion (27.3 % YoY) and net profit increased to ¥13.64 billion (29.2 % YoY), supported by higher non‑operating income amid a volatile financial environment.
Segment analysis indicates the entertainment division—comprising console and mobile businesses—experienced a 3.1 % sales decline, with physical console units falling 7.4 % and digital downloads dropping 5.9 pp. The amusement segment saw a modest sales drop, while real‑estate sales decreased due to property disposals but profit rose from lower repair costs. Regional performance shows Japan sales down 6.9 %, overseas up 0.5 %, North America up 5.3 %, Europe up 101.7 % (though still small in volume), and Asia down 11.3 %.
Methodologically, the report aggregates quarterly data from all operating segments, with expense breakdowns by employment, outsourcing, and advertising costs. No change to FY 2024 guidance is announced; the company maintains a conservative plan of ¥90 billion sales and ¥30 billion operating profit for the full year, with a focus on repeat console titles, steady online/mobile revenue, and incremental royalty income.
- Consolidated sales fell to ¥17.6 billion, a 3.8% year-over-year decline, while operating profit dropped 23.8% to ¥1.78 billion due to increased mobile portfolio costs and reduced partner-funded development.
- Net profit rose 29.2% to ¥13.64 billion and ordinary profit increased 27.3% to ¥4.02 billion, bolstered by non-operating income despite the decline in core operating performance.
- The entertainment division, which houses console and mobile operations, saw a 3.1% sales decline, driven by a 7.4% drop in physical console units and a 5.9 percentage point decrease in digital downloads.
- Regional performance was mixed, with Japan sales falling 6.9% and Asia sales dropping 11.3%, while North America grew 5.3% and Europe saw a 101.7% increase, albeit from a small volume base.
- The company maintains its full-year guidance of ¥90 billion in sales and ¥30 billion in operating profit, focusing on repeat console titles and steady mobile revenue to stabilize performance.
+1
Koei Tecmo
Financial51 pages
Financial Results for the First Half: Fiscal Year Ending March 2025
This document was created by machine translating the Japanese version. Financial Results for the First Half of the Fiscal Year Ending March 2025 KOEI TECMO HOLDINGS CO, LTD Kenjiro Asano Director, Senior Executive Officer & CFO FY23 1st Half FY24 1st Half Vs Previous Year Amount Profit Ratio Amount Profit Ratio Amount Percent Sales 39,722 - 35,197 - (4,525) -11.4% Operating Profit 13,855 34.9% 10,65...
- Koei Tecmo Holdings significantly exceeded its initial forecasts for the first half of FY2025, with Operating Profit up 33.1% (¥2,651 million), Ordinary Profit up 61.5% (¥8,000 million), and Net Profit up 59.8% (¥5,975 million), despite sales being 7.4% lower than forecast.
- The strong performance was driven by better-than-expected sales from the back catalog in Console/PC games, while sales of self-published mobile titles launched in 2023 were weaker than anticipated.
- The company saw a decrease in personnel costs, outsourcing costs, and advertising expenses during the first half of FY2025, contributing to improved profitability.
- Koei Tecmo plans to release several major console/PC titles in late 2024 and early 2025, including "ROMANCE OF THE THREE KINGDOMS 8 REMAKE" (Oct 2024), "FAIRY TAIL 2" (Dec 2024), "DYNASTY WARRIORS: ORIGINS" (Jan 2025), and "Atelier Yumia" (Mar 2025).
- For the full FY2024, Koei Tecmo projects sales of ¥90,000 million (up 6.4% YoY) and operating profit of ¥30,000 million (up 5.3% YoY), but anticipates a decrease in Ordinary Profit by 12.6% and Net Profit by 11.2% compared to FY2023.
+1
Koei Tecmo
Report2 pages
Koei Tecmo Holdings Financial Summary: FY2024 3Q
Koei Tecmo Holdings reported FY2024 Q3 results, showing a 17.6 % decline in consolidated sales to ¥14,677 million versus ¥16,109 million in Q2 and a 25.4 % drop from the same period in FY2023. Gross profit fell to ¥8,392 million, reflecting higher cost of sales (¥6,285 million) and a lower gross margin of 32 % compared with 41 % in Q2. Operating profit contracted to ¥4,673 million (profit ratio 32 %) from ¥6,664 million in Q2 and 41 % in FY2023 Q3. Ordinary profit turned negative for the first time in the quarter, at ¥(787) million, largely due to a ¥5,461 million non‑operating loss. Net profit was ¥(171) million, a reversal from the ¥6,898 million gain in Q2.
Segment analysis indicates entertainment sales dominated at ¥13,515 million (92 % of total), with console/PC and digital downloads each contributing roughly ¥5–6 million. Amusement revenue remained modest at ¥794 million, while real‑estate income was negligible. Regional sales were strongest in Japan (¥7,890 million) and Asia excluding Japan (¥5,232 million), with North America and Europe contributing ¥1,087 million and ¥468 million respectively.
Expenses rose in cost of sales (¥6,285 million) and SG&A (¥3,718 million). Employment costs increased to ¥5,200 million, and outsourcing expenses climbed to ¥1,400 million. Digital download units accounted for 75 % of total sales units in Q3, up from 73.9 % in Q2, indicating a continued shift toward digital channels.
Headcount remained steady at 2,400 employees. Capital expenditures for FY2024 were ¥1,967 million, with real‑estate investment at ¥1,631 million and depreciation expense at ¥1,776 million. The data cover the Japanese market and overseas regions for FY2024 Q3, with comparative figures from FY2023.
- Koei Tecmo reported a net loss of ¥171 million for FY2024 Q3, a significant reversal from the ¥6,898 million profit recorded in the previous quarter.
- Consolidated sales fell 25.4% year-over-year to ¥14,677 million, while operating profit contracted to ¥4,673 million from ¥6,664 million in Q2.
- Ordinary profit turned negative at ¥(787) million, primarily driven by a substantial non-operating loss of ¥5,461 million.
- The entertainment segment remains the core revenue driver, accounting for 92% of total sales at ¥13,515 million.
- Digital download penetration continues to rise, reaching 75% of total sales units in Q3 compared to 73.9% in Q2.
+1
Koei Tecmo
Financial6 pages
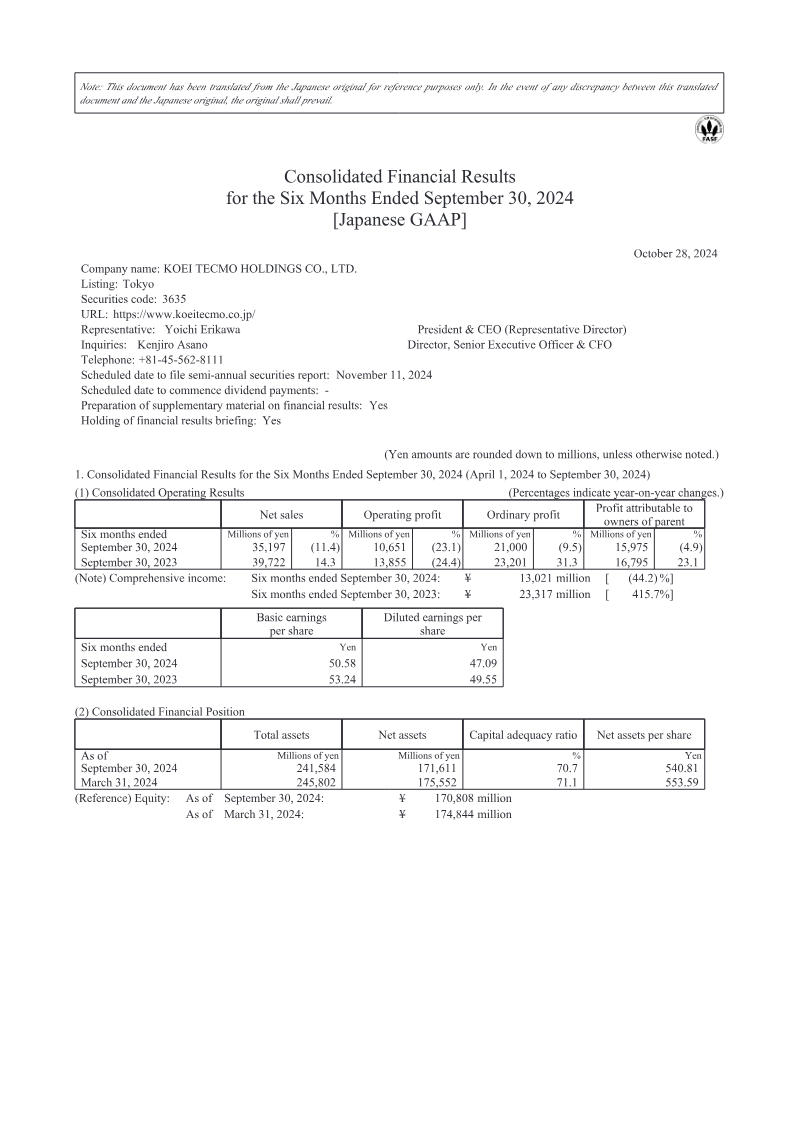
Consolidated Financial Results: Six Months Ended September 30, 2024
The six‑month financial results for Koei Tecmo Holdings, covering April 1 to September 30, 2024, show a decline in key performance metrics compared with the same period in 2023. Net sales fell by 11.4 % to ¥35,197 million from ¥39,722 million, while operating profit dropped 23.1 % to ¥10,651 million and ordinary profit decreased 9.5 % to ¥21,000 million. Profit attributable to owners of the parent company fell 4.9 % to ¥15,975 million. Earnings per share also slipped, with basic earnings at ¥50.58 and diluted earnings at ¥47.09 versus ¥53.24 and ¥49.55 in 2023.
Total assets contracted slightly from ¥245,802 million to ¥241,584 million, and net assets declined to ¥171,611 million, reflecting a lower capital adequacy ratio of 70.7 %. Cash and deposits rose markedly to ¥41,733 million, driven by a substantial increase in short‑term borrowings of ¥9,000 million. Investment securities and other assets decreased modestly.
Dividend policy remained unchanged; no dividends were declared for the fiscal year ending March 31, 2024, and a forecast of ¥48.00 per share is projected for the fiscal year ending March 31, 2025. The company’s forecasted full‑year net sales for FY 2025 are ¥90,000 million, with operating profit expected at ¥30,000 million and ordinary profit at ¥40,000 million.
The report covers Japan‑based operations under Japanese GAAP for the first half of FY 2025, with no significant changes in consolidation scope or accounting policies. The semi‑annual statements are exempt from external audit review.
- Koei Tecmo Holdings experienced a broad financial decline for the six months ending September 30, 2024, with net sales falling 11.4% to ¥35,197 million and operating profit dropping 23.1% to ¥10,651 million.
- Profit attributable to owners of the parent company decreased by 4.9% to ¥15,975 million, resulting in a decline in basic earnings per share to ¥50.58 from ¥53.24 in the prior year.
- The company maintains an optimistic full-year forecast for FY 2025, projecting ¥90,000 million in net sales, ¥30,000 million in operating profit, and ¥40,000 million in ordinary profit.
- Cash and deposits increased significantly to ¥41,733 million, a shift supported by a new ¥9,000 million short-term borrowing.
- Total assets contracted to ¥241,584 million, contributing to a lower capital adequacy ratio of 70.7% compared to previous periods.
+1
Koei Tecmo
Financial21 pages
Financial Results for the Q3: Fiscal Year Ending March 2025
The presentation reports KOEI TECMO HOLDINGS’ consolidated financial performance for the third quarter of fiscal 2025, ending March 2025. Sales fell by 14 % YoY to ¥61.1 billion, driven by a shift from new console/PC releases in FY23 to fewer titles and reliance on existing mobile IPs in FY24. Operating profit declined 25.8 % to ¥20.3 billion, while ordinary and net profits remained near flat, with net profit up 3.6 % to ¥25.2 billion. The Entertainment segment contributed the bulk of sales, yet its revenue dropped 14.9 % due to weaker console/PC and mobile performance; the Amusement, Real Estate, and Other segments showed modest gains or losses. Personnel costs rose 10 % YoY, offset by reductions in outsourcing and advertising expenses.
Expense trends indicate a continued emphasis on hiring and base‑pay increases, with outsourcing costs decreasing after one‑time collaboration outlays. The company maintains a 50 % payout ratio, allocating half of net profit to dividends and buybacks and the remainder to growth investments. Forecasts for FY24 remain unchanged, targeting ¥90 billion in sales and operating profit of ¥30 billion, contingent on the success of upcoming console titles such as “Dynasty Warriors: ORIGINS.” The Q4 outlook anticipates more than five new releases, with a major title expected to drive sales. The company also outlines measures to meet Tokyo Stock Exchange Prime Market listing standards by March 2026, including actions to achieve a 35 % free‑float ratio.
- Koei Tecmo’s Q3 sales fell 14% year-over-year to ¥61.1 billion, primarily due to a lighter release schedule for console and PC titles compared to the previous fiscal year.
- Operating profit declined 25.8% to ¥20.3 billion, though net profit increased 3.6% to ¥25.2 billion due to stable ordinary and net profit performance.
- The company maintains its full-year forecast of ¥90 billion in sales and ¥30 billion in operating profit, heavily dependent on the performance of upcoming titles like 'Dynasty Warriors: ORIGINS'.
- The Entertainment segment, the company's primary revenue driver, saw a 14.9% revenue drop as the business relied more on existing mobile IPs rather than new console and PC releases.
- Personnel costs rose 10% year-over-year due to base-pay increases and hiring, which were partially offset by reduced spending on outsourcing and advertising.
+1
Koei Tecmo
Report4 pages
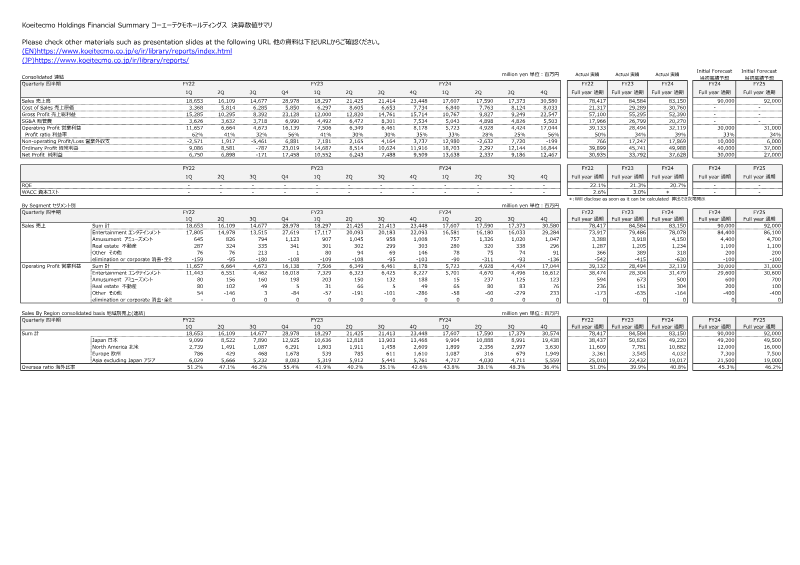
FY2024 Annual Data Appendix
The FY2024 Annual Data Appendix presents a comprehensive financial and operational snapshot of Koei Tecmo’s performance across fiscal years 2022–2025, with detailed quarterly and full‑year figures for sales, cost of sales, gross profit, SG&A, operating profit, ordinary profit, and net profit. Sales peaked in FY22 Q4 at ¥28,978 million before declining to ¥17,590 million in FY23 Q4 and rebounding to ¥23,448 million in FY24 Q4. Gross profit margins fell from 62% in FY22 Q1 to 25% in FY24 Q4, reflecting rising cost of sales and SG&A. Operating profit followed a similar trend, with FY24 Q4 at ¥8,178 million versus ¥16,139 million in FY22 Q4. Net profit swung from ¥17,458 million in FY22 Q4 to a loss of ¥171 million in FY24 Q3, before recovering to ¥9,509 million in FY24 Q4. Return on equity rose from 20.7% in FY22 to 22.1% in FY24, while the weighted average cost of capital increased from 2.6% to 3.0%.
Segment analysis shows the Entertainment division dominates revenue, contributing ¥73,917 million in FY24 and accounting for 94% of total sales. Amusement and real‑estate segments remain small, each under ¥5 billion annually. Geographic revenue distribution highlights Japan as the largest market (¥38,437 million FY24), followed by Asia excluding Japan (¥25,010 million) and North America (¥11,609 million). Overseas sales consistently exceed 40% of total revenue, peaking at 55.4% in FY24 Q4.
Cost breakdowns reveal SG&A expenses rising from ¥3,626 million in FY22 Q1 to ¥8,301 million in FY24 Q3, driven largely by advertising and other variable costs. Employment costs increased modestly from ¥5,110 million to ¥6,500 million over the period. Capital expenditures remained modest, with FY24 cumulative investment at ¥1,967 million.
Headcount grew from 2,413 employees in FY22 Q1 to 2,736 by FY24 Q4, a 9% YoY increase. Digital sales dominate the Entertainment segment, with digital download and DLC revenue accounting for over 60% of total entertainment sales in FY24. New title launches remain steady, with 2,370 units sold in FY24.
The appendix also outlines the FY24 title line‑up, featuring high‑profile releases such as “Romance of the Three Kingdoms 8 Remake” and “Fairy Tail 2,” targeting global markets across console, PC, and mobile platforms. These releases are positioned to support the company’s strategy of expanding digital and overseas sales while maintaining strong domestic performance.
- Koei Tecmo's Entertainment division remains the primary revenue driver, contributing ¥73,917 million in FY24 and accounting for 94% of total company sales.
- Gross profit margins experienced a significant contraction, falling from 62% in FY22 Q1 to 25% in FY24 Q4 due to rising costs of sales and SG&A expenses.
- Overseas markets are increasingly critical to the company's performance, with international revenue reaching 55.4% of total sales in FY24 Q4.
- Digital revenue, including downloads and DLC, now accounts for over 60% of total entertainment sales, underscoring the company's shift toward digital-first distribution.
- Operating profit in FY24 Q4 reached ¥8,178 million, a decline from the ¥16,139 million peak recorded in FY22 Q4.
+1
Koei Tecmo
Report6 pages
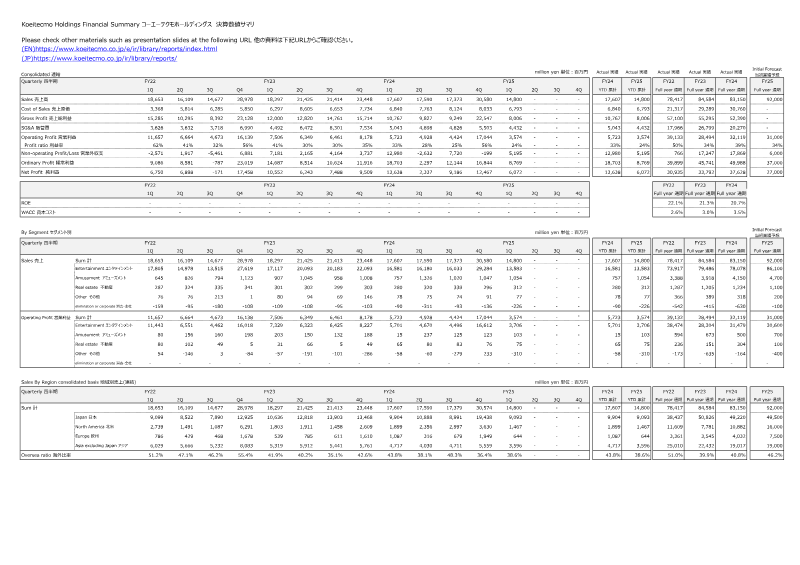
FY2025 1st Quarter Data Appendix: Koei Tecmo
Koei Tecmo’s FY2025 first‑quarter financial appendix presents consolidated performance for the fiscal year 2024, with comparative data through FY2023 and projections to FY2025. Sales rose from ¥18.7 billion in Q1 2024 to ¥21.4 billion in Q1 2025, driven by a 20% increase in the Entertainment segment and a 30% rise in the Amusement division. Gross profit improved to ¥15.3 billion, reflecting a higher gross margin of 82% versus 78% in the prior year. Operating profit climbed to ¥11.7 billion, with SG&A costs rising modestly to ¥3.6 billion as marketing spend increased in the online and mobile sectors.
Segment analysis shows Entertainment sales of ¥17.8 billion, Amusement ¥0.6 billion, Real Estate ¥0.3 billion, and Other ¥0.08 billion in Q1 2024, with Entertainment maintaining the largest share at 95%. Regional revenue distribution highlights Japan as the leading market (¥9.1 billion, 49% of total), followed by North America (¥2.7 billion) and Asia excluding Japan (¥6.0 billion). Overseas sales accounted for 51% of total revenue, up from 46% in the previous year.
Capital expenditures totaled ¥789 million for FY2024, with real estate and equipment investments of ¥526 million and ¥263 million respectively. Depreciation expense reached ¥1.6 billion, consistent with prior periods.
The appendix also details major series performance, noting that “Dynasty Warriors” and “Nobunaga’s Ambition” collectively exceed 30 million units sold, while online/mobile titles such as “DEAD OR ALIVE Xtreme Venus Vacation” and “Romance of the Three Kingdoms: Hadou” have sustained multi‑year service periods. Overall, Koei Tecmo demonstrates steady growth across core entertainment offerings, with strategic emphasis on digital and mobile platforms to sustain revenue momentum.
- Koei Tecmo reported Q1 2025 sales of ¥21.4 billion, a significant increase from ¥18.7 billion in Q1 2024, driven by 20% growth in the Entertainment segment and 30% growth in the Amusement division.
- Operating profit reached ¥11.7 billion, supported by an improved gross margin of 82%, up from 78% in the previous year.
- Overseas markets now account for 51% of total revenue, surpassing domestic Japan revenue (49%) for the first time compared to 46% in the prior year.
- The Entertainment segment remains the company's primary revenue driver, contributing 95% of total sales, with core franchises like 'Dynasty Warriors' and 'Nobunaga’s Ambition' maintaining a cumulative lifetime sales volume exceeding 30 million units.
- Strategic investment is shifting toward online and mobile platforms, evidenced by increased SG&A spending on marketing and the sustained performance of long-running titles like 'DEAD OR ALIVE Xtreme Venus Vacation' and 'Romance of the Three Kingdoms: Hadou'.
+1
Koei Tecmo
Financial10 pages
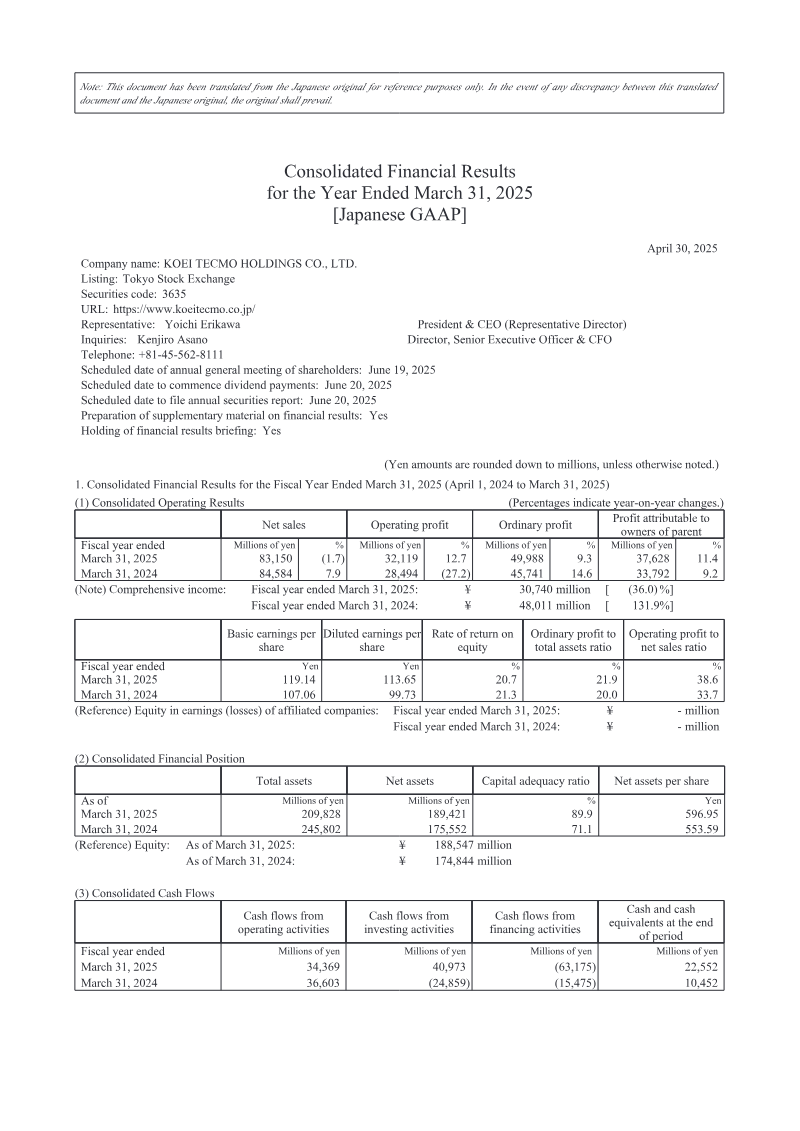
Consolidated Financial Results: Year Ended March 31, 2025
The consolidated financial results for Koei Tecmo Holdings Co., Ltd. cover the fiscal year ended March 31, 2025 (April 1, 2024 to March 31, 2025) under Japanese GAAP. Net sales declined 1.7 % to ¥83,150 million from ¥84,584 million in the prior year, while operating profit rose 12.7 % to ¥32,119 million and ordinary profit increased 9.3 % to ¥49,988 million. Profit attributable to owners of parent reached ¥37,628 million, a 11.4 % rise, yet comprehensive income fell sharply to ¥30,740 million from ¥48,011 million due to a 36.0 % decline in other comprehensive items.
Total assets contracted from ¥245,802 million to ¥209,828 million, driven by a significant reduction in current assets and investment securities. Net assets grew to ¥189,421 million, improving the capital adequacy ratio from 71.1 % to 89.9 %. Cash and cash equivalents increased markedly, ending the year at ¥22,552 million after a net inflow of ¥12,100 million.
Operating cash flow decreased to ¥34,369 million from ¥36,603 million, while investing activities shifted from a net outflow of ¥24,859 million to an inflow of ¥40,973 million, largely due to higher proceeds from securities sales. Financing cash flow turned negative, with a net outflow of ¥63,175 million driven by dividend payments of ¥17,027 million and redemption of convertible bonds.
The company forecasts a modest decline in net sales for the 2026 fiscal year, projecting ¥92,000 million versus ¥84,584 million in 2025. Operating profit is expected to fall by 3.5 % to ¥31,000 million, while ordinary profit is projected to drop 26.0 % to ¥37,000 million. Dividend policy remains steady at a payout ratio of 50.4 %. The forecast reflects the inclusion of Koei Tecmo Corporate Finance Co., Ltd. in consolidation and no significant changes to accounting policies or estimates.
- Koei Tecmo Holdings reported a 12.7% increase in operating profit to ¥32,119 million and an 11.4% rise in net profit to ¥37,628 million for the fiscal year ended March 31, 2025, despite a 1.7% decline in net sales to ¥83,150 million.
- The company’s capital adequacy ratio improved significantly from 71.1% to 89.9% as total assets contracted to ¥209,828 million, largely due to a reduction in investment securities.
- Investing activities shifted to a net inflow of ¥40,973 million, primarily driven by proceeds from the sale of securities, while financing cash flow saw a net outflow of ¥63,175 million due to dividend payments and bond redemptions.
- Management forecasts a decline in profitability for the 2026 fiscal year, projecting a 3.5% drop in operating profit to ¥31,000 million and a 26.0% decrease in ordinary profit to ¥37,000 million.
- Comprehensive income fell sharply by 36.0% to ¥30,740 million, reflecting a significant decline in other comprehensive items compared to the previous fiscal year.
Koei Tecmo