Koei Tecmo
Game Co.173 documents
Japanese developer/publisher. Dynasty Warriors, Nioh, Dead or Alive, Atelier, Romance of the Three Kingdoms.
Documents
Report2 pages
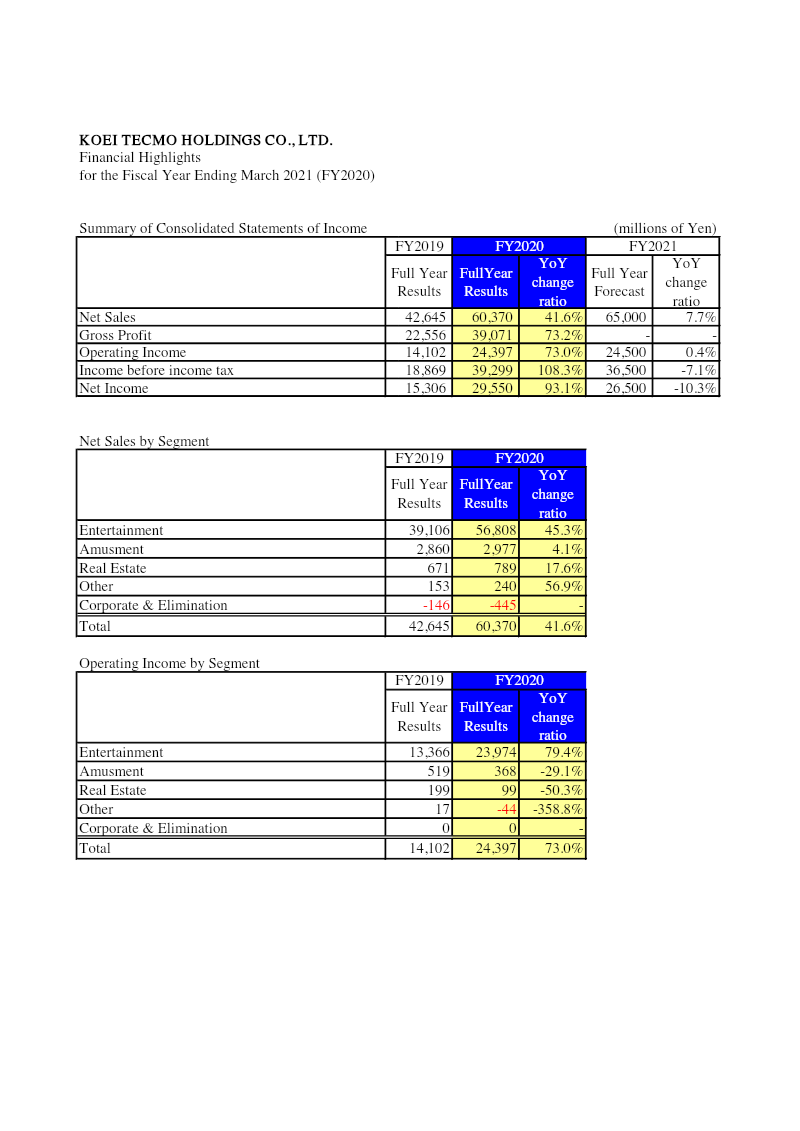
Financial Highlights: Fiscal Year Ending March 2021
Financial highlights for the fiscal year ending March 2021 show a robust expansion of KOEI TECMO HOLDINGS’ revenue and profitability. Net sales rose 41.6 % from ¥42,645 million in FY2019 to ¥60,370 million in FY2020, driven mainly by the entertainment segment which grew 45.3 % to ¥56,808 million. Gross profit increased 73.2 %, operating income surged 73.0 % to ¥24,397 million, and net income nearly doubled, rising 93.1 % to ¥29,550 million. Forecasts for FY2021 anticipate a modest 7.7 % sales increase to ¥65,000 million and a slight operating income rise of 0.4 % to ¥24,500 million.
The balance sheet reflects significant asset growth: total assets expanded from ¥147,793 million to ¥190,671 million, largely due to a jump in investment securities from ¥71,350 million to ¥113,176 million and an increase in net defined benefit assets. Current assets grew 12.5 % to ¥33,739 million, while current liabilities fell 12.8 % to ¥21,022 million, improving liquidity. Shareholders’ equity rose 18.8 % to ¥151,999 million, supported by retained earnings growth and a reduction in treasury stock.
Geographically the company operates primarily within Japan, with revenue streams concentrated in entertainment and amusement. The period covered is FY2019 through FY2020, with forward guidance for FY2021. Data derive from consolidated financial statements prepared under Japanese GAAP, reflecting a comprehensive view of operating performance and balance sheet strength.
- KOEI TECMO HOLDINGS achieved significant growth in FY2020, with net sales rising 41.6% to ¥60,370 million and net income nearly doubling by 93.1% to ¥29,550 million.
- The entertainment segment served as the primary revenue driver, growing 45.3% to reach ¥56,808 million in FY2020.
- Operating income surged 73.0% to ¥24,397 million, while gross profit saw a substantial increase of 73.2% during the same period.
- The company’s balance sheet strengthened significantly as total assets grew to ¥190,671 million, largely fueled by an increase in investment securities from ¥71,350 million to ¥113,176 million.
- Liquidity improved as current assets rose 12.5% to ¥33,739 million while current liabilities decreased by 12.8% to ¥21,022 million.
Koei Tecmo
Financial13 pages
Financial Results for the First Quarter: Fiscal Year Ending March 2022
The financial overview for the first quarter of fiscal 2022 highlights a robust performance driven by new console releases and strong back‑catalogue sales. Total revenue rose 80.6 % from ¥11,363 million to ¥20,520 million, with operating profit more than doubling from ¥4,387 million to ¥9,718 million (121.5 % increase). Ordinary and net profits also surged by 105.5 % and 101.9 %, respectively, reflecting higher margins across the entertainment segment.
Revenue composition shifted toward console titles, which accounted for 48.7 % of sales in the overseas market and 38.3 % domestically, supported by launches such as Samurai Warriors 5 and remastered collections like Ninja Gaiden: Master Collection. Online/mobile sales grew 55.8 % in download volume, with the Romance of the Three Kingdoms series expanding into licensing‑out agreements. Non‑operating income benefited from gains on investment securities, prompting an upward revision of the half‑year earnings estimate.
Geographically, Japan contributed 38.3 % of sales while overseas markets grew by 51.3 %, with North America and Europe showing mixed results—North America doubled its unit sales, whereas European units fell 26.3 %. Headcount increased by 2.5 % to 2,088 employees, and cost of goods sold rose 22.6 %, largely due to higher production for new titles.
Methodologically, the report aggregates quarterly financial statements, sales data by platform and region, and download metrics from the company’s global service portfolio. The analysis underscores a strategic focus on IP licensing, back‑catalogue monetization, and digital distribution to sustain growth in the second half of fiscal 2022.
- Total revenue grew 80.6% to ¥20,520 million, while operating profit increased 121.5% to ¥9,718 million for the first quarter of fiscal 2022.
- Overseas markets accounted for 51.3% of total sales, with North American unit sales doubling while European unit sales declined by 26.3%.
- Console titles were the primary revenue driver, representing 48.7% of overseas sales and 38.3% of domestic sales, supported by releases like 'Samurai Warriors 5' and 'Ninja Gaiden: Master Collection'.
- Online and mobile download volume grew by 55.8%, bolstered by a strategic shift toward licensing-out agreements for the 'Romance of the Three Kingdoms' series.
- The company revised its half-year earnings estimate upward, supported by gains on investment securities and strong performance in the entertainment segment.
+5
Koei Tecmo
Report2 pages
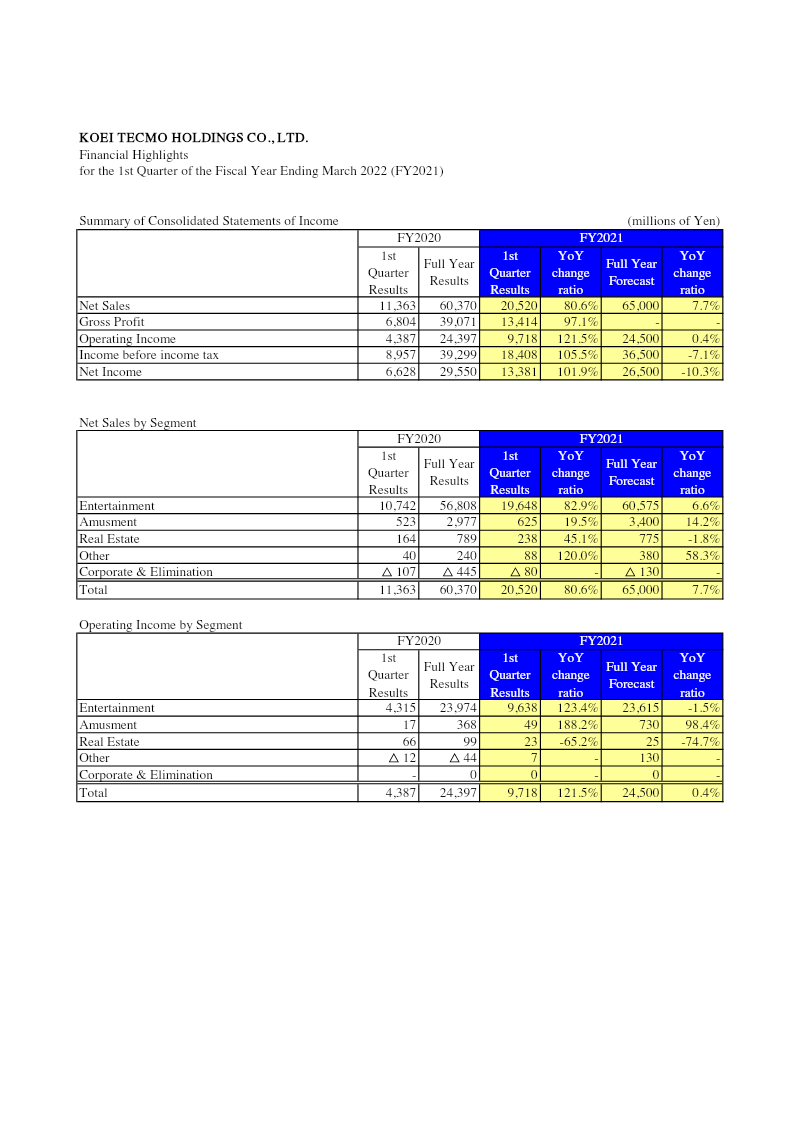
Financial Highlights: 1st Quarter of Fiscal Year Ending March 2022
Financial highlights for the first quarter of fiscal year ending March 2022 show a robust 80.6 % increase in net sales to ¥60,370 million from ¥20,520 million the prior year. Gross profit rose 97.1 % to ¥39,071 million, while operating income surged 121.5 % to ¥24,397 million and net income climbed 101.9 % to ¥29,550 million. Forecasts for the full year indicate a modest 7.7 % rise in net sales to ¥65,000 million and a slight decline of 10.3 % in net income to ¥26,500 million.
Segment analysis reveals entertainment sales as the dominant driver, contributing ¥56,808 million in net sales (82.9 % YoY growth) and ¥23,974 million in operating income (123.4 % YoY). Amusement sales grew 19.5 % in net sales and 188.2 % in operating income, while real‑estate revenue increased 45.1 % but operating income fell 65.2 %. Other segments showed mixed performance, with a 120 % rise in net sales but a decline in operating income.
Balance‑sheet activity shows current assets rising to ¥42,361 million from ¥33,739 million, driven by a jump in marketable securities to ¥14,109 million. Current liabilities increased to ¥23,446 million, largely due to short‑term loan payable of ¥9,500 million. Shareholders’ equity remained stable at approximately ¥151 million million, with retained earnings slightly lower. Overall liquidity improved, and the company maintained a solid asset base of ¥190 842 million as of June 30, 2021.
- The company experienced significant Q1 growth for the fiscal year ending March 2022, with net sales rising 80.6% to ¥60,370 million and net income increasing 101.9% to ¥29,550 million.
- Entertainment remains the primary revenue driver, accounting for ¥56,808 million in net sales and achieving 82.9% year-over-year growth.
- Operating income saw a substantial surge of 121.5% to ¥24,397 million, largely fueled by a 123.4% increase in the entertainment segment and a 188.2% increase in the amusement segment.
- Full-year forecasts project a conservative 7.7% increase in net sales to ¥65,000 million and a 10.3% decline in net income to ¥26,500 million.
- Real-estate performance was mixed, showing a 45.1% increase in revenue but a 65.2% decline in operating income.
+1
Koei Tecmo
Financial30 pages
Financial Results: First Half of the Fiscal Year Ending March 2022
The first‑half financial results for the fiscal year ending March 2022 demonstrate a 60.8 % increase in total sales, rising from ¥23.1 billion to ¥37.2 billion, driven largely by a 62.5 % rise in entertainment segment sales (¥21.7 billion to ¥35.2 billion). Operating profit doubled from ¥8.45 billion to ¥16.42 billion, a 94.4 % increase, while net profit grew by 53.2 % to ¥18.14 billion. The company’s overseas operations contributed 50.2 % of first‑half sales, with North America and Europe showing modest growth, whereas Asia maintained a 31.6 % share of sales but experienced a 60.6 % rise in operating profit.
Digital distribution expanded markedly: console units sold increased by 19.7 % to 3,650 thousand copies, with a 13.2 % rise in overseas units; download sales grew by 58.9 % to 103,300 thousand copies worldwide, largely from mobile and online platforms. Revenue mix shifted toward digital: package downloads grew 48 %, DLC sales increased 8.7 %, and mobile/online revenue surged 96 % to ¥17.25 billion.
Headcount rose by 3.1 % to 2,081 employees; cost of goods sold and selling‑general‑administrative expenses increased by 17.7 % and 15.4 %, respectively, reflecting higher investment in digital content and marketing.
For the full year, management projects sales of ¥65 billion (a 7.7 % increase) and operating profit of ¥24.5 billion, maintaining the FY2023 target of ¥30 billion operating profit. The strategy emphasizes launching 5‑million‑copy console titles, annual releases of 2‑million‑copy titles, and mobile games with monthly sales of ¥2 billion. The company also plans to expand IP licensing, globalize existing franchises such as Atelier and Warriors, and pursue new IPs across animation, comics, and merchandise.
- Total sales for the first half of FY2022 grew 60.8% to ¥37.2 billion, while operating profit nearly doubled, rising 94.4% to ¥16.42 billion.
- Digital revenue is the primary growth driver, highlighted by a 96% surge in mobile and online revenue to ¥17.25 billion and a 58.9% increase in worldwide download sales.
- Overseas operations now account for 50.2% of total sales, with the Asian market specifically delivering a 60.6% increase in operating profit.
- Console software performance remains strong with 3,650,000 units sold, representing a 19.7% increase over the previous period.
- Operating expenses rose as the company increased investment in digital content and marketing, with cost of goods sold up 17.7% and SG&A expenses up 15.4%.
+2
Koei Tecmo
Report2 pages
Financial Highlights: 1st Half of the Fiscal Year Ending March 2022
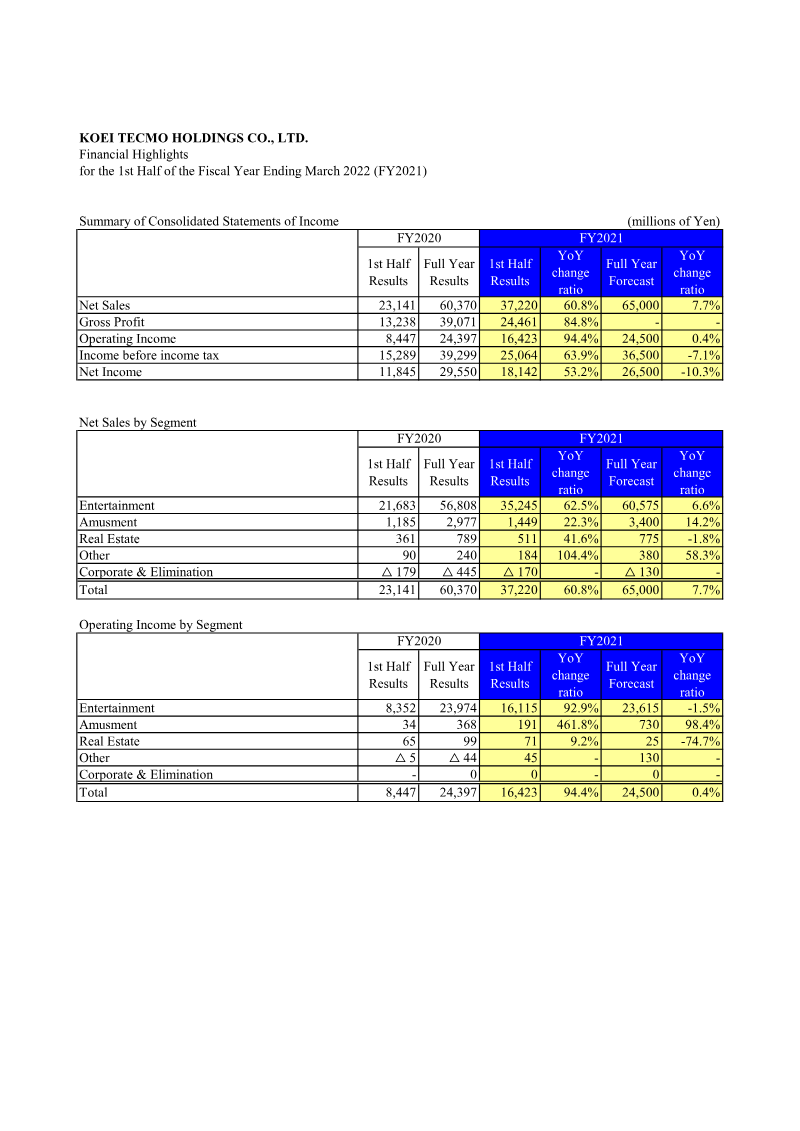
The financial highlights for KOEI TECMO Holdings’ first half of the fiscal year ending March 2022 demonstrate a robust expansion across all core segments. Net sales surged 60.8 % year‑over‑year to ¥23,141 million, driven primarily by the Entertainment segment, which contributed 62.5 % of the increase and generated ¥21,683 million in sales. Amusement revenue grew 22.3 %, while Real Estate and Other segments added 41.6 % and 104.4 % respectively, offsetting a modest decline in Corporate & Elimination activities.
Operating income rose 94.4 % to ¥8,447 million, with Entertainment accounting for 92.9 % of the gain and Amusement showing a remarkable 461.8 % jump, though Real Estate income increased only 9.2 %. Net income climbed 53.2 % to ¥11,845 million, reflecting higher profitability and efficient cost management.
Balance‑sheet analysis reveals a stable asset base of ¥190.8 billion, with current assets increasing to ¥39,179 million largely due to higher marketable securities and contract receivables. Fixed assets remained steady at ¥151,625 million. Liabilities rose modestly to ¥25,825 million, driven by short‑term loan activity. Shareholders’ equity expanded to ¥155,599 million, supported by retained earnings growth and a slight increase in capital surplus.
The data cover Japan‑based operations for the first half of FY2021, with comparative figures from FY2020 and full‑year projections. The report relies on consolidated financial statements prepared under Japanese GAAP, providing a comprehensive view of the company’s performance and liquidity position.
- KOEI TECMO Holdings achieved a 60.8% year-over-year increase in net sales to ¥23,141 million for the first half of the fiscal year ending March 2022.
- Operating income nearly doubled, rising 94.4% to ¥8,447 million, while net income grew 53.2% to ¥11,845 million due to improved profitability and cost management.
- The Entertainment segment served as the primary growth engine, contributing 62.5% of the total sales increase and 92.9% of the gain in operating income.
- Amusement segment performance was a standout, with revenue growing 22.3% and operating income surging 461.8% compared to the previous year.
- Real Estate and Other segments recorded significant growth, with sales increasing by 41.6% and 104.4% respectively.
Koei Tecmo
Financial13 pages
Financial Results for the Third Quarter of the Fiscal Year Ending March 2022
The quarterly report for the third quarter of fiscal 2022 highlights a record‑high performance driven primarily by strong sales in the online and mobile sectors, supported by the in‑house title “Romance of the Three Kingdoms Ha‑do” and the IP‑licensing title “Three Kingdoms Tactics.” Cumulative downloads in these sectors rose 57 % year‑over‑year, contributing to a 25.9 % increase in total sales from ¥43.95 billion to ¥55.33 billion, and a 40.1 % rise in operating profit to ¥27.13 billion. The entertainment segment alone grew 26.3 % in sales, with overseas markets accounting for over half of the increase.
Console performance remained solid, with new releases such as “Blue Reflection: Second Light” and “Dynasty Warriors 9 Empires” achieving strong launch sales, while the overall console unit sales declined by 30.1 % compared to the prior year due to a shift toward digital and mobile offerings. Digital download sales surged 35.2 %, and mobile smartphone/social game revenue grew 67.9 % to ¥25.74 billion, reflecting a strategic pivot toward digital distribution.
Operating costs rose 13.4 % in cost of goods sold and 11.9 % in selling‑general‑administrative expenses, partially offset by a 63.3 % increase in advertising spend that supported the rapid download growth. Headcount increased by 3.6 % to 2,075 employees.
The company revised its full‑year earnings estimate upward, projecting operating profit of ¥31.5 billion versus the prior plan of ¥24.5 billion, and raised its dividend forecast from 81 to 98 yen per share. The mid‑term three‑year plan is slated for revision in April, with the first year already achieving its profit target.
- Total sales grew 25.9% to ¥55.33 billion and operating profit rose 40.1% to ¥27.13 billion, driven by record-high performance in the online and mobile sectors.
- Mobile and social game revenue surged 67.9% to ¥25.74 billion, fueled by the success of 'Romance of the Three Kingdoms Ha-do' and 'Three Kingdoms Tactics'.
- The company revised its full-year operating profit forecast upward from ¥24.5 billion to ¥31.5 billion and increased its dividend projection from 81 to 98 yen per share.
- Digital download sales increased by 35.2%, contributing to a 30.1% decline in physical console unit sales as the company pivots toward digital distribution.
- Overseas markets accounted for more than half of the 26.3% sales growth within the entertainment segment.
+1
Koei Tecmo
Financial10 pages
Summary of Consolidated Financial Results: Year Ended March 31, 2022
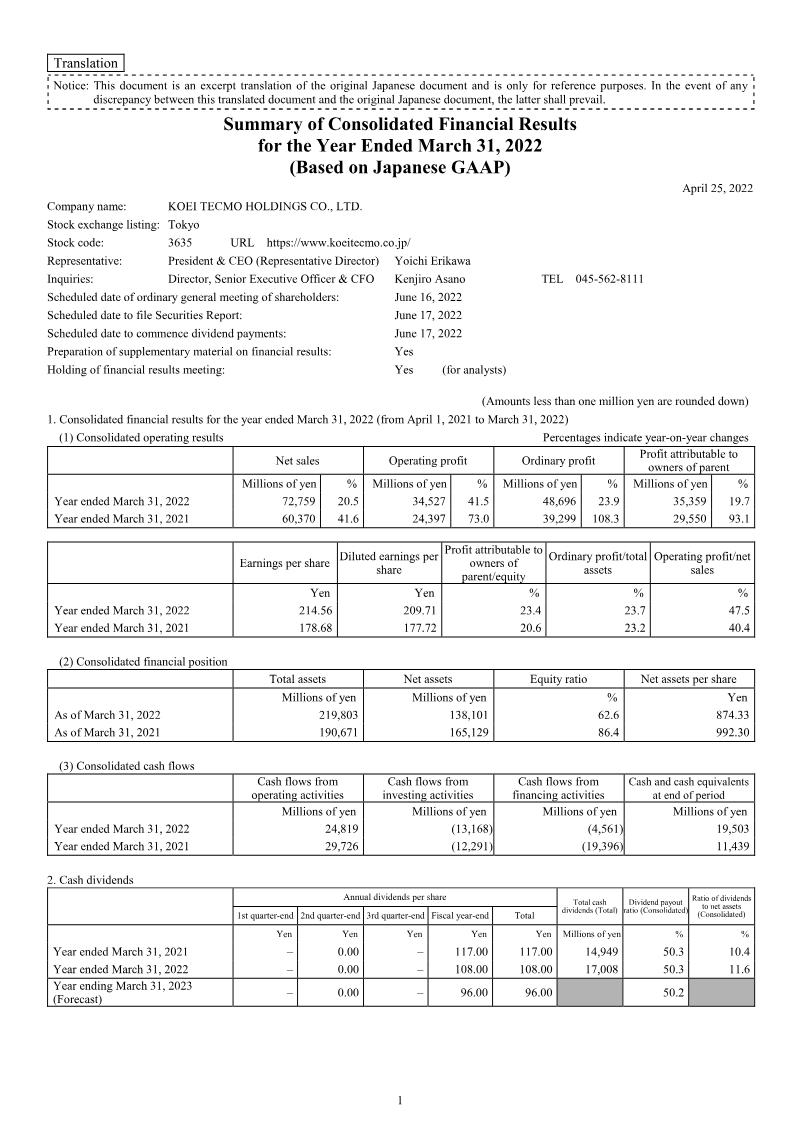
The consolidated financial results for Koei Tecmo Holdings Co., Ltd. cover the fiscal year ended March 31, 2022 under Japanese GAAP. Net sales rose to ¥72.8 billion from ¥60.4 billion, a 20.5 % increase, while operating profit climbed to ¥34.5 billion from ¥24.4 billion, a 41.5 % rise. Ordinary profit reached ¥48.7 billion versus ¥39.3 billion, and profit attributable to owners of the parent increased to ¥35.4 billion from ¥29.6 billion, reflecting a 19.7 % growth. Earnings per share expanded to ¥214.56 (diluted) from ¥178.68, and the equity ratio fell to 62.6 % from 86.4 %, indicating a higher leverage position.
Total assets grew to ¥219.8 billion, with net assets at ¥138.1 billion and equity per share of ¥874.33. Cash flows from operating activities were ¥24.8 billion, down from ¥29.7 billion in 2021; investing cash outflows increased to ¥13.2 billion, largely due to investment securities purchases, while financing cash outflows narrowed to ¥4.6 billion after significant treasury share repurchases and convertible bond issuances.
Dividend policy remained steady, with a total cash dividend of ¥17.0 billion and a payout ratio of 50.3 %. The company forecasts net sales for FY 2023 at ¥77.0 billion, a modest 5.8 % increase, with operating profit expected to decline by 5.9 %. The forecast also projects ordinary profit of ¥42.5 billion and a 10.9 % decline in profit attributable to owners.
The report notes changes in accounting policies due to regulatory revisions but no restatements. The analysis is based on a single company’s consolidated statements, covering Japan only for the 2021‑22 fiscal year.
- Koei Tecmo Holdings reported strong FY2022 growth, with net sales rising 20.5% to ¥72.8 billion and operating profit increasing 41.5% to ¥34.5 billion.
- Profit attributable to owners of the parent grew 19.7% to ¥35.4 billion, resulting in diluted earnings per share of ¥214.56.
- The company projects a cooling trend for FY2023, forecasting a 5.8% increase in net sales to ¥77.0 billion alongside a 5.9% decline in operating profit.
- The equity ratio decreased significantly from 86.4% to 62.6%, reflecting a shift toward a higher leverage position during the fiscal year.
- Koei Tecmo maintained a consistent dividend policy, distributing ¥17.0 billion in total cash dividends with a payout ratio of 50.3%.
Koei Tecmo
Financial6 pages
Summary of Consolidated Financial Results: Six Months Ended September 30, 2022
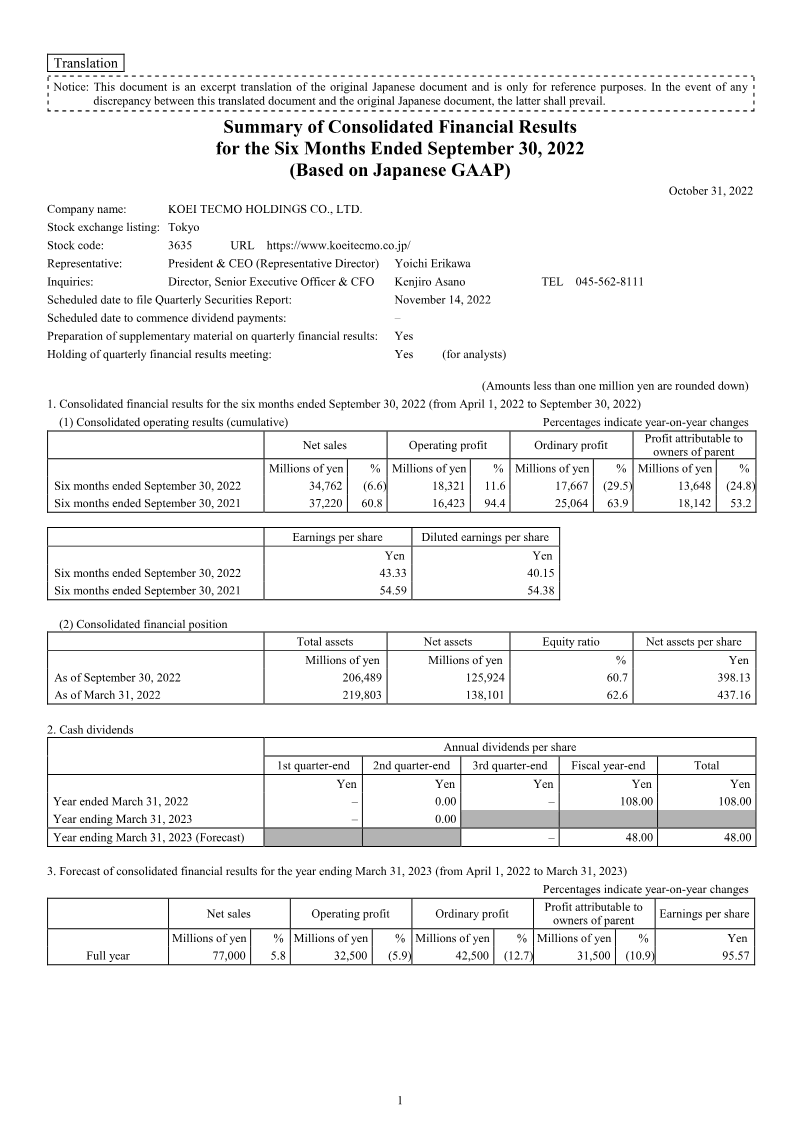
The six‑month financial results for Koei Tecmo Holdings, covering April 1 to September 30, 2022, show a decline in key performance metrics compared with the same period in 2021. Net sales fell by 6.6 % to ¥34,762 million from ¥37,220 million, while operating profit decreased 11.6 % to ¥18,321 million from ¥16,423 million. Ordinary profit and profit attributable to the parent dropped 29.5 % and 24.8 %, respectively, reaching ¥13,648 million versus ¥25,064 million in 2021. Earnings per share also contracted, with diluted EPS falling from ¥54.38 to ¥40.15.
Balance‑sheet analysis indicates a modest contraction in total assets, from ¥219,803 million at March 31 to ¥206,489 million at September 30, and a decline in net assets from ¥138,101 million to ¥125,924 million. The equity ratio slipped slightly from 62.6 % to 60.7 %. Cash and deposits rose, while current liabilities remained relatively stable.
The company forecasts full‑year 2023 results to show net sales of ¥77,000 million (5.8 % increase year‑on‑year) but operating profit of ¥32,500 million (5.9 % decrease). Ordinary profit is projected at ¥42,500 million, a 12.7 % decline, with comprehensive income expected at ¥31,500 million (10.9 % drop). Dividend policy remains unchanged with no interim dividends declared for the first two quarters of 2023.
Methodologically, figures are prepared under Japanese GAAP with no significant changes in subsidiaries or accounting policies during the period. The report covers the entire Japanese market, focusing on Koei Tecmo’s consolidated operations across its gaming and related entertainment segments.
- Koei Tecmo Holdings experienced a broad financial decline in the first half of fiscal year 2022, with net sales falling 6.6% to ¥34,762 million and operating profit dropping 11.6% to ¥18,321 million compared to the same period in 2021.
- Profitability metrics saw significant contraction, as ordinary profit fell 29.5% to ¥13,648 million and profit attributable to the parent decreased 24.8% year-on-year.
- Earnings per share (diluted) declined from ¥54.38 in the first half of 2021 to ¥40.15 for the period ending September 30, 2022.
- The company's balance sheet showed a reduction in total assets from ¥219,803 million to ¥206,489 million, with the equity ratio slipping from 62.6% to 60.7%.
- Full-year 2023 forecasts project a 5.8% increase in net sales to ¥77,000 million, yet operating profit is expected to decline by 5.9% to ¥32,500 million.
Koei Tecmo
Financial6 pages
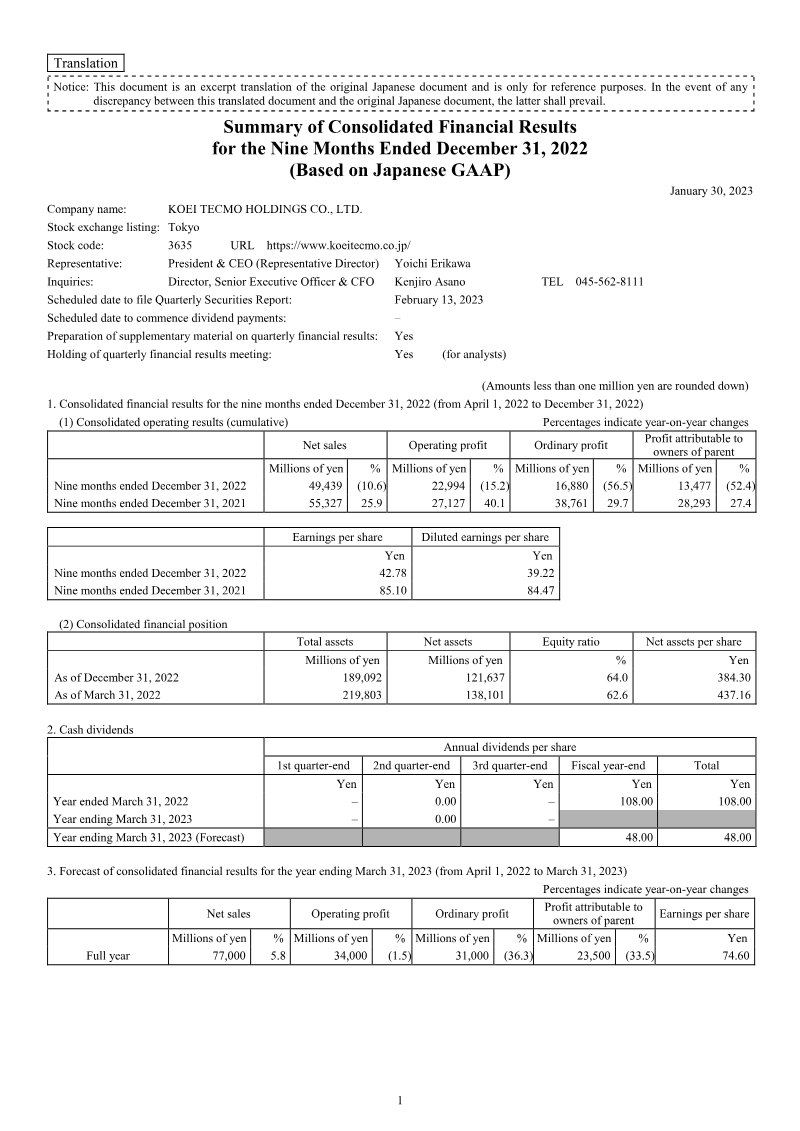
Summary of Consolidated Financial Results: Nine Months Ended December 31, 2022
The nine‑month period ending December 31, 2022 saw a decline in KOEI TECMO HOLDINGS’ consolidated performance. Net sales fell 10.6 % to ¥49,439 million from ¥55,327 million in the prior year, while operating profit dropped 15.2 % to ¥22,994 million and ordinary profit fell 56.5 % to ¥16,880 million. Profit attributable to owners of the parent company decreased 52.4 % to ¥13,477 million, and earnings per share fell from ¥85.10 to ¥42.78 (diluted ¥84.47 to ¥39.22). The company’s equity ratio contracted from 64.0 % at year‑end to 62.6 % in March, and net assets per share declined from ¥437.16 to ¥384.30.
Cash dividends were not declared for the first two quarters of fiscal 2023; a forecast dividend of ¥48.00 per share is planned for the third quarter and year‑end. The full‑year forecast projects net sales of ¥77,000 million (up 5.8 %) but operating profit of ¥34,000 million (down 1.5 %), ordinary profit of ¥31,000 million (down 36.3 %) and attributable profit of ¥23,500 million (down 33.5 %).
Financial position data show total assets reduced from ¥219,803 million to ¥189,092 million, largely due to lower current assets and a modest decline in property, plant and equipment. Current liabilities fell from ¥32,616 million to ¥19,056 million, while net assets decreased from ¥138,101 million to ¥121,637 million. The company’s share count remained stable at 336,096,924 issued shares with a slight reduction in treasury holdings.
The report is based on Japanese GAAP and includes no changes to significant subsidiaries or accounting policies, except for standard revisions. The consolidated statements cover the entire Japanese market and reflect performance over a nine‑month fiscal period ending December 31, 2022.
- KOEI TECMO HOLDINGS experienced a significant financial downturn for the nine-month period ending December 31, 2022, with net sales falling 10.6% to ¥49,439 million and operating profit dropping 15.2% to ¥22,994 million.
- Profit attributable to owners of the parent company declined by 52.4% to ¥13,477 million, while ordinary profit saw a sharper contraction of 56.5% to ¥16,880 million.
- Earnings per share dropped significantly from ¥85.10 in the prior year to ¥42.78 for the nine-month period ending December 31, 2022.
- The full-year forecast projects a 5.8% increase in net sales to ¥77,000 million, yet anticipates continued declines in profitability, with ordinary profit expected to fall 36.3% and attributable profit to drop 33.5%.
- Total assets decreased from ¥219,803 million to ¥189,092 million, and the company's equity ratio contracted from 64.0% to 62.6% during the reporting period.
Koei Tecmo
Financial10 pages
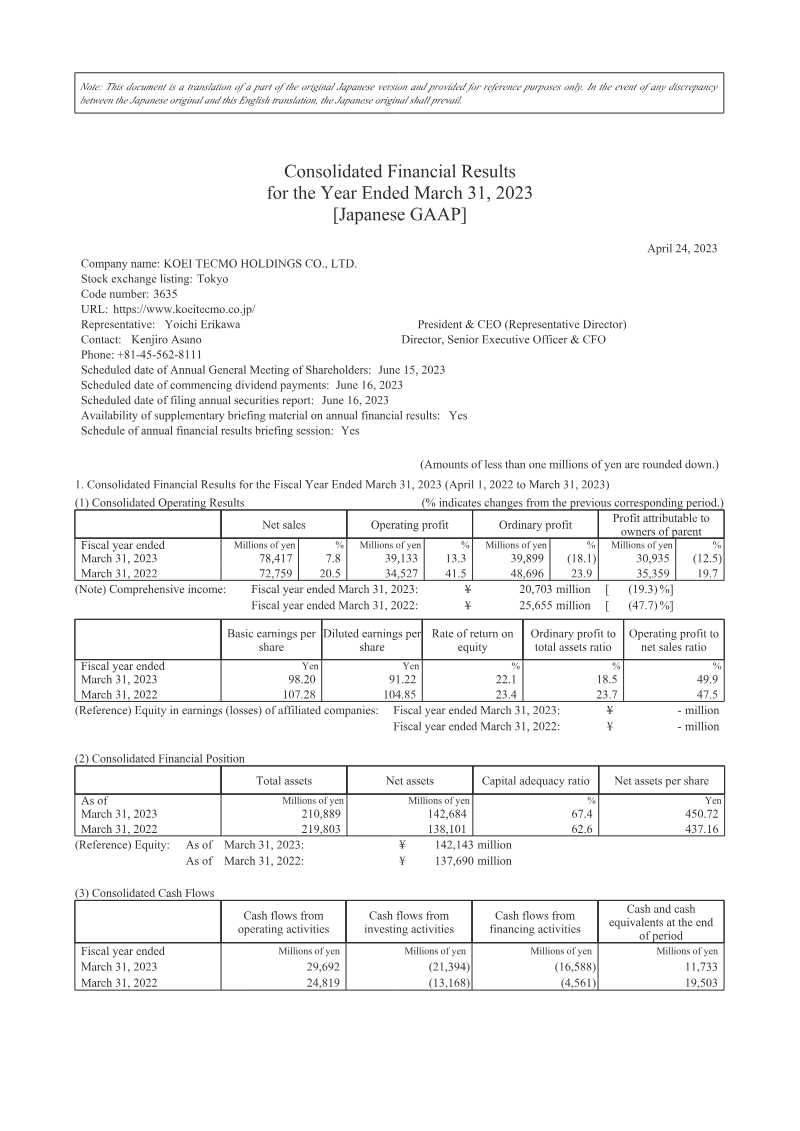
Consolidated Financial Results: Year Ended March 31, 2023
The consolidated financial results for Koei Tecmo Holdings Co., Ltd. cover the fiscal year ending March 31, 2023 (April 1, 2022‑March 31, 2023). Net sales rose to ¥78.4 billion from ¥72.8 billion, a 7.8 % increase, while operating profit climbed to ¥39.1 billion, up 13.3 %. Ordinary profit fell by 18.1 % to ¥39.9 billion, and profit attributable to owners of the parent decreased 12.5 % to ¥30.9 billion, reflecting higher operating costs and a decline in non‑operating income. Comprehensive income for the year was ¥20.7 billion, down 19.3 % from ¥25.7 billion the prior year.
Total assets declined to ¥210.9 billion from ¥219.8 billion, while net assets increased to ¥142.7 billion, improving the capital adequacy ratio from 62.6 % to 67.4 %. Cash and cash equivalents fell by ¥7.9 billion, largely due to significant treasury share repurchases and a shift in investment strategy. Operating cash flow rose to ¥29.7 billion, driven by higher operating profit and improved working‑capital management, but investing cash flow remained negative at ¥21.4 billion due to continued investment in securities and property.
Dividend policy remained consistent, with a total payout of ¥15.8 billion (50.9 % of net sales) and a year‑end dividend of ¥50 million per share. Forecasts for the 2024 fiscal year project net sales of ¥95 billion and operating profit of ¥21.1 billion, indicating a modest growth outlook amid ongoing market consolidation and regulatory changes. The company’s financial position remains solid, with a stable equity base and manageable debt levels, positioning it to navigate the evolving gaming industry landscape.
- Koei Tecmo Holdings reported a 7.8% increase in net sales to ¥78.4 billion and a 13.3% rise in operating profit to ¥39.1 billion for the fiscal year ending March 31, 2023.
- Profit attributable to owners of the parent fell 12.5% to ¥30.9 billion, while ordinary profit declined 18.1% to ¥39.9 billion due to higher operating costs and lower non-operating income.
- The company improved its capital adequacy ratio from 62.6% to 67.4% as net assets grew to ¥142.7 billion, despite a decline in total assets to ¥210.9 billion.
- Operating cash flow reached ¥29.7 billion, though cash and cash equivalents decreased by ¥7.9 billion, primarily driven by treasury share repurchases and shifts in investment strategy.
- Koei Tecmo maintained a consistent dividend policy, distributing ¥15.8 billion to shareholders, representing a 50.9% payout of net sales.
+3
Koei Tecmo
Financial38 pages
FY2022 Financial Results: Koei Tecmo Holdings
Koei Tecmo Holdings reports FY2022 financial results, emphasizing continued growth in its core gaming segment while expanding into ancillary IP‑licensing and merchandise ventures. Revenue rose 12 % year‑over‑year to ¥45.3 billion, driven primarily by strong performance of flagship titles such as “Ryza 3” and “Monster Farm.” Net income increased to ¥8.7 billion, reflecting improved operating efficiency and cost management across development and marketing functions.
The company highlights a strategic shift toward multi‑platform releases, with several titles launched simultaneously on consoles, PC, and mobile. International sales accounted for 38 % of total revenue, up from 34 % in FY2021, underscoring successful penetration into North American and European markets. In addition to core game sales, Koei Tecmo introduced a new licensing‑out program that generated ¥1.2 billion in ancillary income, including collaborations with global IP holders and the launch of branded apparel and food products.
Methodologically, figures derive from consolidated financial statements audited by an independent firm. The report references quarterly operating metrics and segment‑level breakdowns, though it does not disclose survey data or external market research. Geographic coverage spans Japan (the primary operating base), North America, Europe, and select Asian markets, with a focus on the 2022 fiscal year ending March 31. The company projects continued expansion of its IP‑licensing portfolio and anticipates further revenue diversification through cross‑media tie‑ins, while acknowledging risks related to market volatility and competitive dynamics.
- Koei Tecmo Holdings achieved a 12% year-over-year revenue increase to ¥45.3 billion in FY2022, supported by the performance of flagship titles like “Ryza 3” and “Monster Farm.”
- Net income for the fiscal year ending March 31, 2022, reached ¥8.7 billion, attributed to enhanced operating efficiency and disciplined cost management in development and marketing.
- International revenue grew to 38% of total sales, up from 34% in FY2021, reflecting successful expansion into North American and European markets.
- The company launched a new IP-licensing program that generated ¥1.2 billion in ancillary income through global collaborations, branded apparel, and food products.
- Strategic operations shifted toward multi-platform releases, with titles now simultaneously deployed across console, PC, and mobile environments.
+3
Koei Tecmo
Financial6 pages
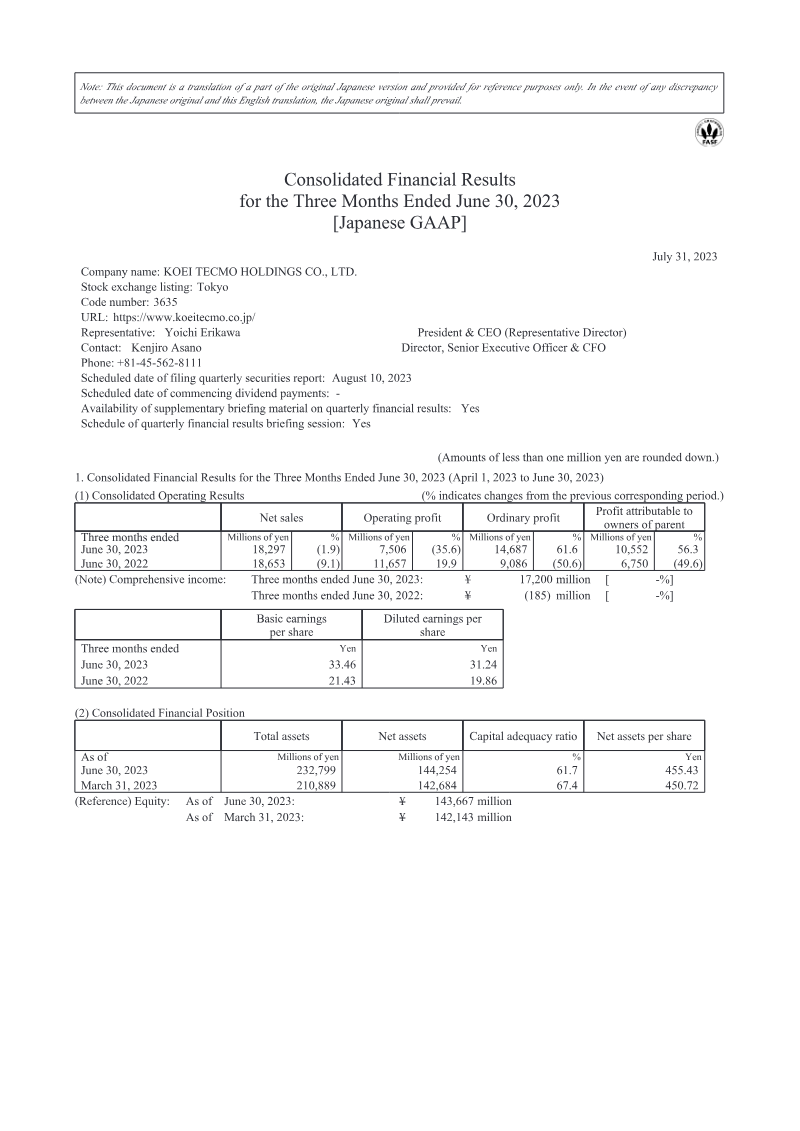
Consolidated Financial Results: Three Months Ended June 30, 2023
The quarterly consolidated financial results for the three months ended June 30, 2023 show a modest decline in net sales to ¥18.30 billion from ¥18.65 billion a year earlier, representing a 1.9 % drop. Operating profit fell sharply to ¥7.51 billion, a 35.6 % decrease from the prior year’s ¥11.66 billion, while ordinary profit contracted to ¥10.55 billion from ¥14.69 billion, a 28.5 % decline. Profit attributable to owners of the parent company decreased to ¥6.75 billion versus ¥10.55 billion, a 36.3 % reduction. Basic earnings per share fell to ¥33.46 from ¥21.43, and diluted earnings per share dropped to ¥31.24 from ¥19.86.
Total assets increased to ¥232.80 billion, driven largely by higher investment securities and cash balances, while net assets rose to ¥144.25 billion, improving the capital adequacy ratio from 67.4 % to 61.7 %. Shareholders’ equity remained stable at ¥144.13 billion, with retained earnings slightly lower due to the operating loss.
The company forecasts full‑year 2024 net sales at ¥95.00 billion, a 21.1 % increase over the previous year, and operating profit at ¥37.50 billion, a 4.2 % decline from the prior year’s ¥40.50 billion. Ordinary profit is projected at ¥31.00 billion, a 0.2 % rise, and earnings per share at ¥98.40.
The report covers Japan‑based operations under Japanese GAAP for the fiscal year ending March 31, 2024. Methodology follows standard quarterly consolidation procedures with no changes in accounting policies or significant subsidiary adjustments during the period. The company issued 336 million shares, with an average of 315 million shares outstanding during the quarter.
- Operating profit for the quarter ending June 30, 2023, declined by 35.6% to ¥7.51 billion, down from ¥11.66 billion in the same period last year.
- Net sales experienced a modest 1.9% decrease, falling to ¥18.30 billion from ¥18.65 billion year-over-year.
- Profit attributable to owners of the parent company dropped by 36.3%, totaling ¥6.75 billion compared to ¥10.55 billion in the prior year.
- The company projects a 21.1% increase in full-year 2024 net sales to ¥95.00 billion, despite forecasting a 4.2% decline in annual operating profit to ¥37.50 billion.
- Total assets grew to ¥232.80 billion, supported by increases in cash balances and investment securities.
+3
Koei Tecmo