CyberAgent
Game Co.111 documents
Internet/media company, parent of Cygames (Granblue Fantasy, Uma Musume, Princess Connect). Game segment is major revenue driver.
Documents
Financial40 pages
2Q FY2023 Presentation Material: January to March 2023
CyberAgent achieved record-high quarterly consolidated sales of 195.6 billion yen during the second quarter of fiscal year 2023, representing a period of significant operational recovery and strategic growth. While consolidated operating profit experienced a year-over-year decline to 18.7 billion yen, the company realized a substantial quarter-on-quarter profit surge of 191.7% within its Game business. This financial rebound was primarily driven by high-performing anniversary events for flagship titles such as Uma Musume Pretty Derby and Granblue Fantasy, alongside a robust portfolio of intellectual property managed through subsidiaries like Cygames and strategic partnerships with major industry players including Bandai Namco and SEGA.
The Media segment, centered on the ABEMA streaming platform, demonstrated a 22.4% year-over-year revenue increase to 33.4 billion yen. This growth was supported by a sustained expansion of the user base, with weekly active users remaining 1.5 times higher than levels recorded prior to the FIFA World Cup. Consequently, the Media segment significantly narrowed its operating losses to 0.5 billion yen. Simultaneously, the WINTICKET betting platform expanded its market share to 40%, further diversifying the company’s revenue streams.
Looking toward the remainder of the fiscal year, the company remains positioned to meet its full-year sales forecast of 720 billion yen. Future growth strategies focus on long-term monetization through the release of high-profile titles like Final Fantasy VII Ever Crisis and the continued scaling of the Internet Advertisement business. By leveraging a mix of proprietary ownership and collaborative development, the company maintains a stable trajectory across its core gaming, media, and advertising segments within the Japanese market.
- CyberAgent achieved record-high consolidated quarterly sales of 195.6 billion yen for 2Q FY2023.
- The Game business saw a 191.7% quarter-on-quarter profit surge, driven by anniversary events for flagship titles like Uma Musume Pretty Derby and Granblue Fantasy.
- The Media segment, led by ABEMA, increased revenue by 22.4% year-over-year to 33.4 billion yen while narrowing operating losses to 0.5 billion yen.
- The WINTICKET betting platform reached a 40% market share, contributing to the company's revenue diversification strategy.
- Weekly active users on the ABEMA platform remain 1.5 times higher than pre-FIFA World Cup levels.
+2
CyberAgentApr 2023
Financial10 pages
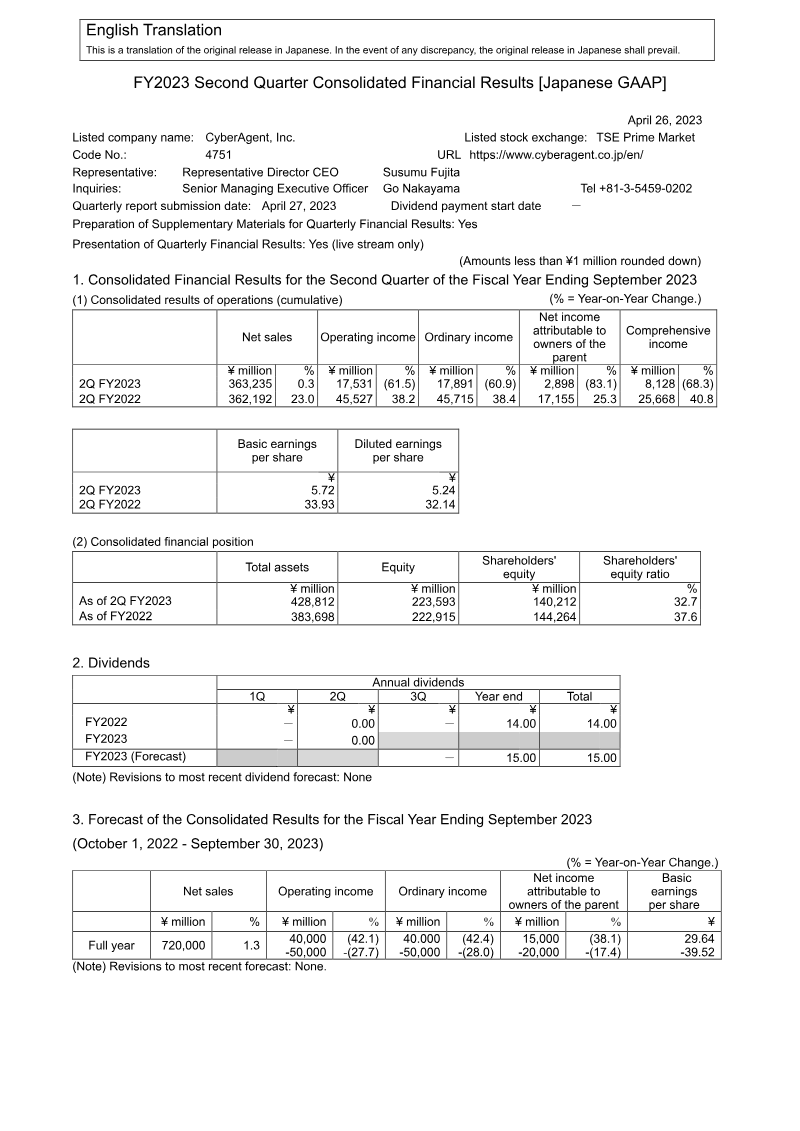
FY2023 Second Quarter Consolidated Financial Results: Japanese GAAP
CyberAgent’s financial performance for the second quarter of fiscal year 2023 reflects a period of revenue stability contrasted by significant profit compression. Consolidated net sales remained nearly flat at ¥363.2 billion, representing a marginal 0.3% year-over-year increase. However, operating income experienced a sharp 61.5% decline, falling to ¥17.5 billion from ¥45.5 billion in the prior year. This contraction was primarily driven by a 47% drop in Game Business income and heightened operating losses within the Media Business, the latter of which was impacted by the substantial costs associated with distributing the FIFA World Cup Qatar 2022.
The Game Business remains a cornerstone of the company’s portfolio despite its segment income decreasing from ¥38.5 billion to ¥17.3 billion. Simultaneously, the Internet Media segment demonstrated revenue growth, though it continued to operate at a loss. Total assets expanded to ¥428.8 billion, supported by a robust cash position of ¥185.3 billion. This liquidity was significantly bolstered by the strategic issuance of ¥40.5 billion in convertible bonds, providing a financial cushion despite rising selling, general, and administrative expenses.
While the company faced immediate downward pressure on profitability due to high-profile content investments and shifting performance in the gaming sector, it has maintained its full-year financial forecasts. The results indicate a transition phase where the company is balancing long-term media expansion with the volatility of its core gaming assets. After accounting for ¥3.5 billion in unallocable corporate administrative expenses, the final consolidated operating income confirms a challenging but stable fiscal position as the company navigates its current investment cycle.
- CyberAgent’s consolidated operating income fell 61.5% year-over-year to ¥17.5 billion in Q2 FY2023, despite net sales remaining nearly flat at ¥363.2 billion.
- The Game Business segment experienced a 47% decline in income, dropping from ¥38.5 billion in the prior year to ¥17.3 billion.
- Operating losses in the Internet Media segment increased due to substantial costs associated with distributing the FIFA World Cup Qatar 2022.
- The company maintains a strong liquidity position with ¥185.3 billion in cash, bolstered by a ¥40.5 billion convertible bond issuance.
- Total assets reached ¥428.8 billion as the company continues to navigate an investment cycle characterized by rising selling, general, and administrative expenses.
CyberAgentApr 2023
Financial30 pages
1Q FY2023 Presentation Material: October to December 2022
This financial analysis covers the first quarter of the 2023 fiscal year, specifically the period from October to December 2022. The data reflects the performance of a diversified digital conglomerate operating across internet advertising, mobile gaming, and media services. The primary focus of the period was the strategic integration of the FIFA World Cup Qatar 2022 into the ABEMA media platform, which served as a significant driver for user acquisition and brand visibility.
Financial results show a consolidated quarterly revenue of 191.1 billion yen, maintaining a steady trajectory compared to the previous year's peak of 192.2 billion yen. However, operating profit for the quarter was 5.2 billion yen, representing a decline in operating margin to 5.2%. This compression is attributed to heavy front-loaded investments in the media segment and increased personnel costs, which rose to 25 billion yen. The advertising business remains the primary profit engine, generating 95.6 billion yen in quarterly sales, while the game business contributed 40.9 billion yen.
The media segment experienced a transformative surge due to the World Cup, with weekly active users peaking at over 30 million. Data indicates a diverse viewing demographic, with 44% of users being female and 31% falling in the 20-34 age bracket. The event also accelerated the adoption of large-screen viewing, with television-based streaming accounting for 24% of the device breakdown. While the media segment reported an operating loss of 9.3 billion yen due to content acquisition and infrastructure costs, the company views this as a long-term investment to establish its platform as a "television of the future" and social infrastructure.
The company’s medium-to-long-term strategy involves using the accumulated profits from the established advertising and gaming businesses to fund the growth of the media segment. This includes expanding into peripheral areas such as the WINTICKET betting service, which saw transaction volumes reach 88.9 billion yen, and increasing investments in high-quality original content and global animation projects.
- Consolidated quarterly revenue reached 191.1 billion yen for 1Q FY2023, while operating profit fell to 5.2 billion yen due to increased personnel costs of 25 billion yen and heavy media segment investments.
- The advertising business remains the primary profit driver with 95.6 billion yen in sales, followed by the gaming business at 40.9 billion yen.
- The ABEMA media platform incurred a 9.3 billion yen operating loss during the quarter, driven by content acquisition and infrastructure costs associated with the FIFA World Cup Qatar 2022.
- The World Cup drove ABEMA weekly active users to a peak of over 30 million, with 24% of viewership occurring on television screens.
- The company is leveraging profits from advertising and gaming to fund media growth, including the WINTICKET betting service, which recorded 88.9 billion yen in transaction volume.
+2
CyberAgentJan 2023
Financial8 pages
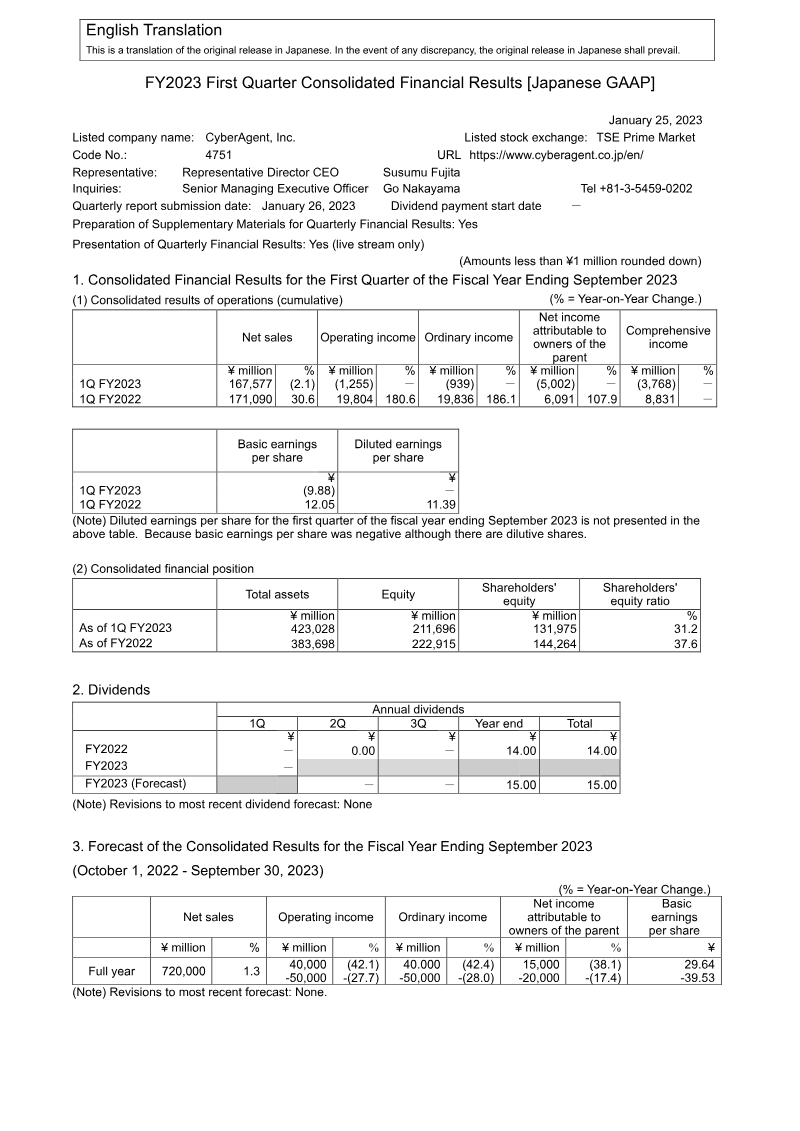
FY2023 First Quarter Consolidated Financial Results [Japanese GAAP]
CyberAgent’s consolidated financial results for the first quarter of the fiscal year ending September 30, 2023, reveal a period of strategic investment and market fluctuation. Covering the period from October 1, 2022, to December 31, 2022, the data shows a slight year-on-year decline in net sales of 2.1%, totaling ¥167,577 million. The company shifted from a significant operating income of ¥19,804 million in the previous year to an operating loss of ¥1,255 million. This downturn resulted in a net loss attributable to owners of the parent of ¥5,002 million, compared to a ¥6,091 million profit in the same quarter of the prior year.
Performance varied significantly across business segments. The Media Business, which includes ABEMA and Ameba, saw a 34% increase in net sales to ¥33,485 million, driven largely by the distribution of the FIFA World Cup Qatar 2022. However, high content and distribution costs led to an expanded operating loss of ¥9,356 million for the segment. The Internet Advertisement Business remained a stable core, growing sales by 8.9% to ¥95,639 million, though operating income dipped 13% due to economic conditions. Conversely, the Game Business experienced a sharp decline, with sales falling 29.9% to ¥40,916 million and operating income dropping 69.6% to ¥5,212 million as major titles moved away from their anniversary peaks.
The consolidated financial position shows total assets increased to ¥423,028 million, primarily due to the issuance of convertible bonds, which also contributed to a rise in total liabilities to ¥211,331 million. Despite the quarterly loss, the company maintained its full-year forecast, projecting net sales of ¥720,000 million and operating income between ¥40,000 and ¥50,000 million. The report, prepared under Japanese GAAP, indicates that while short-term profitability was impacted by heavy media investments and game cycle volatility, the company continues to focus on the medium-to-long-term growth of its smartphone-based services.
- CyberAgent reported a consolidated operating loss of ¥1,255 million for Q1 FY2023 (ending December 31, 2022), a significant reversal from the ¥19,804 million operating income recorded in the same period the previous year.
- The Game Business segment experienced a sharp downturn, with sales falling 29.9% to ¥40,916 million and operating income dropping 69.6% to ¥5,212 million as major titles moved past their anniversary peaks.
- The Media Business, driven by FIFA World Cup Qatar 2022 coverage, grew net sales by 34% to ¥33,485 million, though heavy content and distribution costs resulted in an operating loss of ¥9,356 million.
- The Internet Advertisement Business remained the company's core revenue driver with ¥95,639 million in sales (an 8.9% increase), although operating income for the segment declined by 13% due to broader economic conditions.
- Total consolidated net sales for the quarter declined 2.1% year-on-year to ¥167,577 million, resulting in a net loss attributable to owners of the parent of ¥5,002 million.
CyberAgentJan 2023
Financial41 pages
FY2022 Presentation Material
The fiscal year 2022 presentation for CyberAgent outlines the company’s strategic evolution and financial performance, emphasizing its transition into a diversified internet services conglomerate. The primary thesis centers on leveraging the internet and technological innovation to break through economic stagnation, with a specific focus on establishing the streaming platform ABEMA as a foundational "television of the future."
The scope of the report covers the Japanese market across three primary business segments: Media, Games, and Advertising. Financial data indicates steady growth over the last two decades, with recent quarterly revenues reaching approximately 4.69 billion yen. The Game business, led by flagship titles from Cygames such as Uma Musume Pretty Derby, serves as a significant profit engine that funds long-term investments in the Media segment.
Key findings highlight the massive scale of the Media business, particularly the acquisition of broadcasting rights for the FIFA World Cup Qatar 2022. This initiative is positioned as a critical driver for user acquisition, featuring high-quality streaming, multi-camera angles, and on-demand replays to enhance social infrastructure. Additionally, the company is expanding its DX (Digital Transformation) capabilities through partnerships with major entities like NTT Docomo and ANA, aiming to digitize various industries including retail and finance.
The organizational methodology emphasizes a shift away from traditional seniority systems, favoring a leadership structure that promotes younger talent and female executives. By integrating AI and creative technologies across its gaming and advertising pipelines, the company aims to sustain its competitive advantage and transition into a global entity capable of adapting to rapid technological shifts.
- CyberAgent utilizes its Game segment, anchored by Cygames' 'Uma Musume Pretty Derby,' as a primary profit engine to fund long-term strategic investments in its Media business.
- The company is positioning its streaming platform, ABEMA, as the 'television of the future' by securing high-profile broadcasting rights, such as the FIFA World Cup Qatar 2022, to drive mass user acquisition.
- Financial performance shows consistent growth over the last two decades, with recent quarterly revenues reaching approximately 4.69 billion yen.
- CyberAgent is expanding its Digital Transformation (DX) capabilities through strategic partnerships with major corporations including NTT Docomo and ANA to digitize sectors like retail and finance.
- The organization is actively transitioning away from traditional seniority-based systems to a leadership structure that prioritizes younger talent and female executives.
CyberAgentOct 2022
Financial18 pages
FY2022 Consolidated Financial Results (Japanese GAAP)
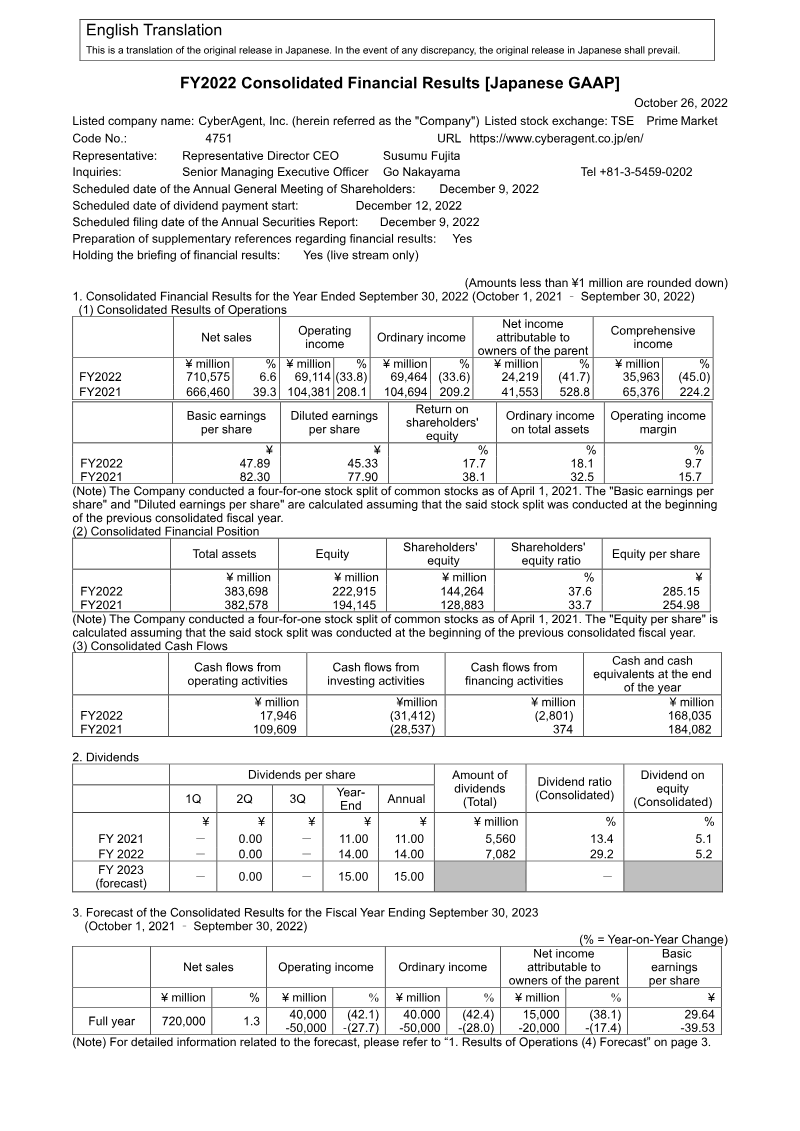
CyberAgent achieved record net sales of ¥710.6 billion for the 2022 fiscal year, representing a 6.6% year-on-year increase. This growth was primarily driven by the Internet Advertisement Business, which expanded by 17.3%, and a 35.3% revenue surge in the Media Business fueled by the ABEMA platform. Despite these gains, consolidated operating income fell 33.8% to ¥69.1 billion, while net income attributable to the parent dropped to ¥24.2 billion. This profitability decline stems largely from a normalization of the Game Business, which saw sales and operating income decrease by 13.1% and 37.2% respectively as major titles from the previous year experienced natural slowdowns.
The financial landscape was further impacted by a shift in revenue recognition for the Game Business, moving from the point of purchase to the estimated customer usage period. While shareholders' equity grew to ¥222.9 billion, cash and cash equivalents decreased to ¥168 billion due to elevated tax payments and strategic investing activities. The company also recorded a ¥4.2 billion impairment loss on long-lived assets within the gaming segment. These shifts reflect a transition period as the organization rebalances its portfolio away from the exceptional highs of previous gaming hits toward long-term media infrastructure.
Looking toward the 2023 fiscal year, the strategic focus shifts toward content investment and market share expansion. Management forecasts modest sales growth to ¥720 billion but anticipates a further contraction in operating income to between ¥40 billion and ¥50 billion. This outlook accounts for heavy investments in high-profile content, specifically the FIFA World Cup on ABEMA, which is intended to narrow media losses and solidify the platform's user base. While the Game Business remains a significant profit center, the overall corporate trajectory emphasizes scaling the advertisement and media segments to ensure diversified, sustainable growth within the Japanese digital economy.
- CyberAgent achieved record net sales of ¥710.6 billion in FY2022, a 6.6% year-on-year increase, despite a 33.8% decline in consolidated operating income to ¥69.1 billion.
- The Game Business experienced a significant contraction, with sales falling 13.1% and operating income dropping 37.2% due to the natural slowdown of major titles and a shift in revenue recognition policies.
- The Internet Advertisement Business grew by 17.3% and the Media Business, driven by the ABEMA platform, surged by 35.3%, signaling a strategic pivot toward media infrastructure.
- Management forecasts a further decline in operating income for FY2023 to between ¥40 billion and ¥50 billion, attributed to heavy content investments including the FIFA World Cup on ABEMA.
- The company recorded a ¥4.2 billion impairment loss on long-lived assets within the gaming segment as it rebalances its portfolio away from previous gaming highs.
CyberAgentOct 2022

Financial43 pages
3Q FY2022 Presentation Material
CyberAgent’s financial performance for the third quarter of fiscal year 2022 reflects a strategic transition period characterized by a 10.4% year-over-year decline in consolidated sales to 172.1 billion yen. This contraction was primarily driven by a 50% revenue drop in the Game business, which faced difficult comparisons against the previous year’s peak performance of major titles. Consequently, quarterly operating profit fell 76.7% to 10.3 billion yen. Despite these headwinds, the company maintained its full-year sales forecast of 700 billion yen and increased its dividend projection to 14 yen, signaling confidence in its diversified business model and long-term growth trajectory.
The Internet Advertisement and Media segments emerged as significant growth drivers during this period. The Advertisement business achieved record quarterly sales of 99.5 billion yen, while the Media segment grew by 48.2%, bolstered by the expansion of ABEMA. The media platform reached 81 million downloads and generated record-breaking pay-per-view revenue from high-profile events such as THE MATCH 2022. Additionally, the related WINTICKET business saw transaction volumes surge to 200.7 billion yen. In the Game segment, while revenue normalized, Uma Musume Pretty Derby surpassed 15 million downloads and successfully expanded into the Korean and Chinese markets, demonstrating the enduring value of core intellectual properties.
The overarching corporate strategy focuses on utilizing stable profits from the Game and Advertisement sectors to fund the evolution of ABEMA into a primary long-term profit pillar. This approach is complemented by an aggressive expansion into the Digital Transformation sector through strategic partnerships with major financial and telecommunications firms. By prioritizing technological innovation and market share expansion, the company aims to overcome temporary stagnation and establish a sustainable ecosystem across the digital entertainment and advertising landscapes.
- CyberAgent reported a 10.4% year-over-year decline in consolidated sales to 172.1 billion yen and a 76.7% drop in operating profit to 10.3 billion yen for 3Q FY2022.
- The Game business experienced a 50% revenue contraction due to difficult year-over-year comparisons, though 'Uma Musume Pretty Derby' surpassed 15 million downloads and expanded into Korean and Chinese markets.
- The Internet Advertisement segment achieved record quarterly sales of 99.5 billion yen, serving as a primary stabilizer for the company's financial performance.
- The Media segment grew by 48.2%, driven by ABEMA's 81 million downloads and record pay-per-view revenue from events like 'THE MATCH 2022'.
- Transaction volume for the WINTICKET business surged to 200.7 billion yen, contributing to the company's diversified revenue streams.
+1
CyberAgentJul 2022
Financial45 pages
2Q FY2022 Presentation Material: January to March 2022
CyberAgent’s financial performance for the second quarter of fiscal year 2022 reflects a period of robust growth across its core business segments, characterized by consolidated sales of 191.1 billion yen and an operating profit of 25.7 billion yen. This 16.9% year-over-year increase in revenue was primarily fueled by record-breaking performance in the Internet Advertisement division and a significant recovery in the Game business. The gaming sector specifically benefited from high-profile anniversary events for major titles such as Uma Musume Pretty Derby and Granblue Fantasy, which drove quarterly segment sales to 69.0 billion yen and operating profit to 21.3 billion yen.
The strategic focus remains centered on leveraging the profitability of advertising and gaming to fund the long-term expansion of the ABEMA media platform. While ABEMA reported a quarterly loss of 1.9 billion yen, its sales grew by 37.9% year-over-year, supported by the rapid scaling of the WINTICKET betting service. WINTICKET achieved a 2.1x increase in transaction volume, capturing 31% of the online Keirin market. To further solidify ABEMA’s market position, the company secured exclusive free broadcasting rights for all 64 matches of the FIFA World Cup Qatar 2022, aiming to transition the platform into a primary profit pillar.
Despite the strong quarterly results, the full-year outlook remains cautious, with a projected 32.9% decline in operating profit to 70 billion yen. This forecast accounts for substantial upfront investments in media content and a normalization of the gaming sector following previous peaks. Future growth initiatives include the release of three major RPG titles later in 2022 and continued technological investments to maximize advertising effectiveness. The overall trajectory indicates a transition toward a diversified digital ecosystem where high-margin services subsidize the development of a dominant streaming and entertainment infrastructure.
- CyberAgent reported Q2 FY2022 consolidated sales of 191.1 billion yen and an operating profit of 25.7 billion yen, marking a 16.9% year-over-year revenue increase.
- The Game business generated 69.0 billion yen in sales and 21.3 billion yen in operating profit, driven by anniversary events for major titles including Uma Musume Pretty Derby and Granblue Fantasy.
- The full-year operating profit forecast is projected to decline by 32.9% to 70 billion yen due to heavy upfront media investments and the expected normalization of gaming sector performance.
- ABEMA media platform sales grew 37.9% year-over-year despite a quarterly operating loss of 1.9 billion yen, bolstered by the WINTICKET betting service which saw a 2.1x increase in transaction volume.
- CyberAgent secured exclusive free broadcasting rights for all 64 matches of the FIFA World Cup Qatar 2022 to accelerate ABEMA's transition into a primary profit pillar.
+2
CyberAgentApr 2022
Financial10 pages
FY2022 Second Quarter Consolidated Financial Results (Japanese GAAP)
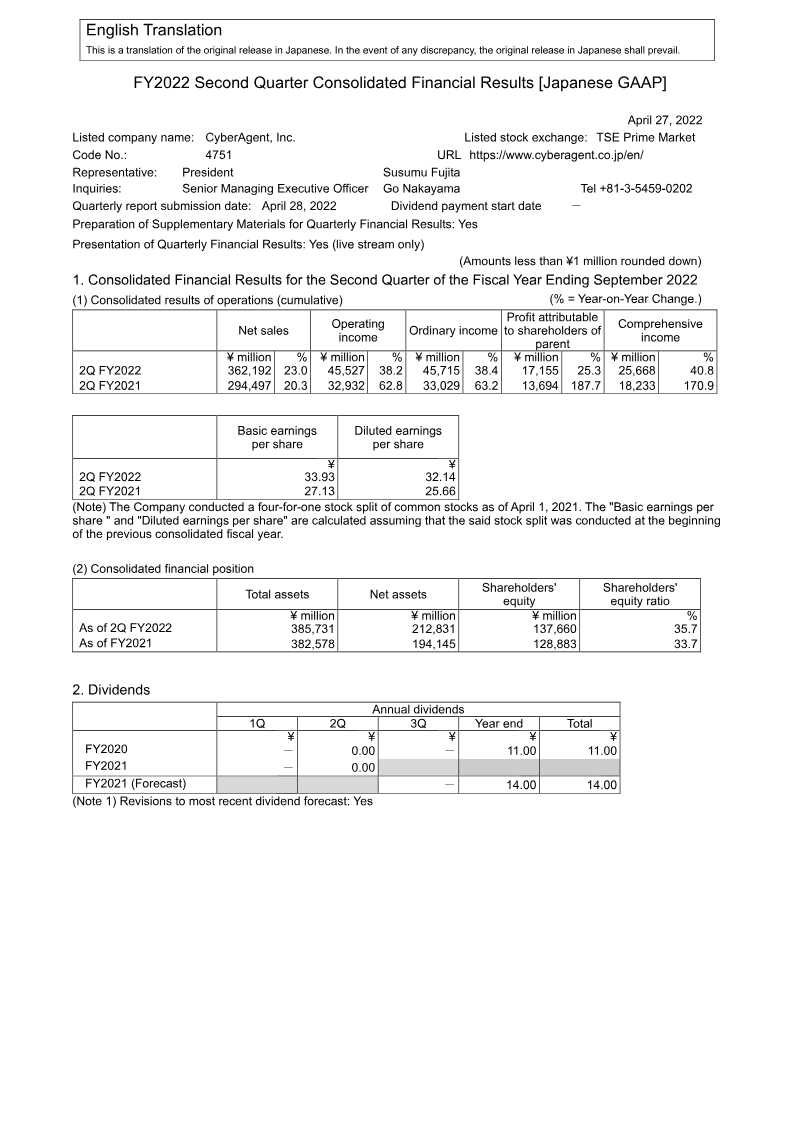
CyberAgent achieved significant financial growth during the second quarter of fiscal year 2022, characterized by a 23.0% year-on-year increase in net sales to ¥362,192 million and a 38.2% rise in operating income to ¥45,527 million. This performance was primarily anchored by the Game Business, which experienced a 58.2% surge in operating income driven by high-profile anniversary events for major titles. Simultaneously, the Internet Advertisement Business reached record-high performance levels, further stabilizing the company’s revenue base. While the Media segment, centered on the ABEMA platform, reported a loss of ¥5,804 million, this reflects a deliberate strategy of medium-to-long-term investment to scale the service.
The geographic focus remains centered on the Japanese market, with results reflecting the implementation of new revenue recognition standards. These accounting changes shifted the timing of game item charge recognition to align with estimated usage periods, though the overall impact on consolidated sales and segment income remained minor. Despite the robust quarterly figures, management maintains a conservative outlook for the remainder of the fiscal year, anticipating a potential pullback in gaming profits as the immediate impact of major events stabilizes.
The financial data reveals a stark contrast between the high-earning Game segment, which contributed ¥38,529 million in income, and the strategic losses incurred in the Media division. This disparity underscores a corporate strategy that utilizes the high margins of the gaming and advertising sectors to fund the expansion of digital media infrastructure. Overall, the results demonstrate a strong competitive position in the Japanese digital entertainment and advertising landscapes, supported by diversified revenue streams and a commitment to long-term platform growth.
- CyberAgent reported strong Q2 FY2022 growth with net sales reaching ¥362,192 million, a 23.0% year-on-year increase, and operating income rising 38.2% to ¥45,527 million.
- The Game Business served as the primary profit driver, generating ¥38,529 million in operating income, a 58.2% surge fueled by high-profile anniversary events.
- The Internet Advertisement Business achieved record-high performance levels, serving as a stable revenue pillar alongside the high-margin gaming segment.
- The Media segment, anchored by the ABEMA platform, reported a strategic operating loss of ¥5,804 million as part of a long-term investment plan to scale the service.
- Management maintains a conservative outlook for the remainder of the fiscal year, expecting gaming profits to normalize following the conclusion of major title events.
+1
CyberAgentApr 2022
Presentation43 pages
1Q FY2022 Presentation Material: October to December 2021
CyberAgent demonstrated significant financial growth during the first quarter of fiscal year 2022, with consolidated sales reaching 171 billion yen and operating profit increasing nearly threefold to 19.8 billion yen. This performance was primarily catalyzed by the Game business, where sales nearly doubled to 58.3 billion yen. The massive success of Uma Musume Pretty Derby, which surpassed 12 million downloads, drove a 15.1-fold year-over-year increase in operating profit for the segment. Despite this momentum, the inherent volatility of the gaming market led to a cautious approach regarding full-year forecasts.
The Media segment, led by the streaming platform ABEMA, achieved 24.9 billion yen in sales but reported an operating loss of 3.8 billion yen. This deficit reflects aggressive reinvestment into the online betting platform WINTICKET and content expansion, including the acquisition of Babel Label and integration with the Nintendo Switch. ABEMA continues to scale its reach, recording over 76 million downloads and 18 million weekly active users. Meanwhile, the Internet Advertisement business achieved record sales, supported by the launch of three new subsidiaries focused on digital transformation.
The long-term strategic framework involves utilizing high-margin profits from the Advertising and Game segments to fund the evolution of Media into a primary growth pillar and essential social infrastructure. This vision is underpinned by a corporate purpose focused on overcoming economic stagnation through digital innovation and global expansion. Future growth in the gaming sector is anticipated through a robust pipeline of high-profile intellectual properties, including titles based on Final Fantasy VII and Jujutsu Kaisen, while broader corporate sustainability is managed through integrated ESG initiatives.
- CyberAgent’s consolidated sales reached 171 billion yen in 1Q FY2022, with operating profit nearly tripling to 19.8 billion yen.
- The Game business segment saw sales nearly double to 58.3 billion yen, driven by the success of 'Uma Musume Pretty Derby' which exceeded 12 million downloads.
- Operating profit for the Game segment grew 15.1-fold year-over-year, though management remains cautious about full-year forecasts due to gaming market volatility.
- The Media segment, anchored by ABEMA, recorded 24.9 billion yen in sales but incurred an operating loss of 3.8 billion yen due to heavy reinvestment in WINTICKET and content expansion.
- ABEMA reached 76 million total downloads and 18 million weekly active users as of the end of 2021.
+1
CyberAgentJan 2022
Financial8 pages
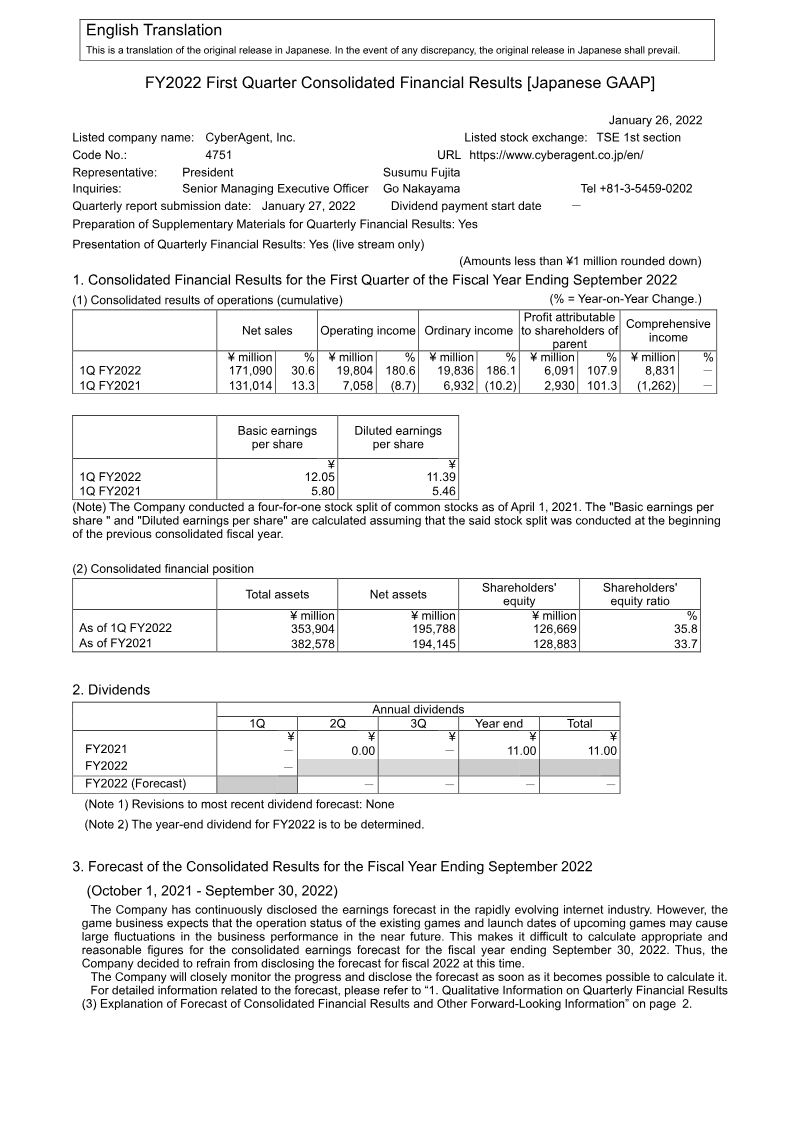
FY2022 First Quarter Consolidated Financial Results (Japanese GAAP)
CyberAgent’s consolidated financial results for the first quarter of the fiscal year ending September 2022 reveal a period of significant growth, primarily driven by a surge in the game business. For the three-month period ending December 31, 2021, net sales reached ¥171,090 million, a 30.6% increase year-on-year. Operating income saw a substantial rise of 180.6% to ¥19,804 million, while profit attributable to shareholders of the parent grew by 107.9% to ¥6,091 million.
The game business was the primary catalyst for this performance, reporting a 94.7% increase in net sales to ¥58,329 million and a 1,405.7% increase in operating income to ¥17,130 million, largely due to a successful title launched in early 2021. The internet advertisement business also achieved record-high net sales of ¥87,831 million. Conversely, the media business, which includes ABEMA, reported an operating loss of ¥3,840 million as the company continues to invest in the platform for long-term growth. The investment development business experienced a decline, with operating income falling 57.5% year-on-year.
Geographically focused on the Japanese market, the report notes a change in accounting policies following the adoption of the Accounting Standard for Revenue Recognition. This shift affects how in-game currency and item charges are recorded, though the immediate impact on profit and loss is described as minor. Despite the strong quarterly performance, CyberAgent has refrained from providing a full-year consolidated earnings forecast for fiscal 2022. This decision is attributed to the inherent volatility of the game business, where performance is highly dependent on the timing of new launches and the operational status of existing titles, making reasonable calculations difficult at this stage.
- CyberAgent’s Q1 FY2022 net sales rose 30.6% year-on-year to ¥171,090 million, with operating income surging 180.6% to ¥19,804 million.
- The game business was the primary growth driver, reporting a 94.7% increase in net sales to ¥58,329 million and a 1,405.7% jump in operating income to ¥17,130 million.
- The internet advertisement business reached record-high net sales of ¥87,831 million during the quarter ending December 31, 2021.
- The media business, including ABEMA, recorded an operating loss of ¥3,840 million as the company prioritizes long-term platform investment.
- The investment development business experienced a 57.5% year-on-year decline in operating income.
CyberAgentJan 2022
Financial1 pages
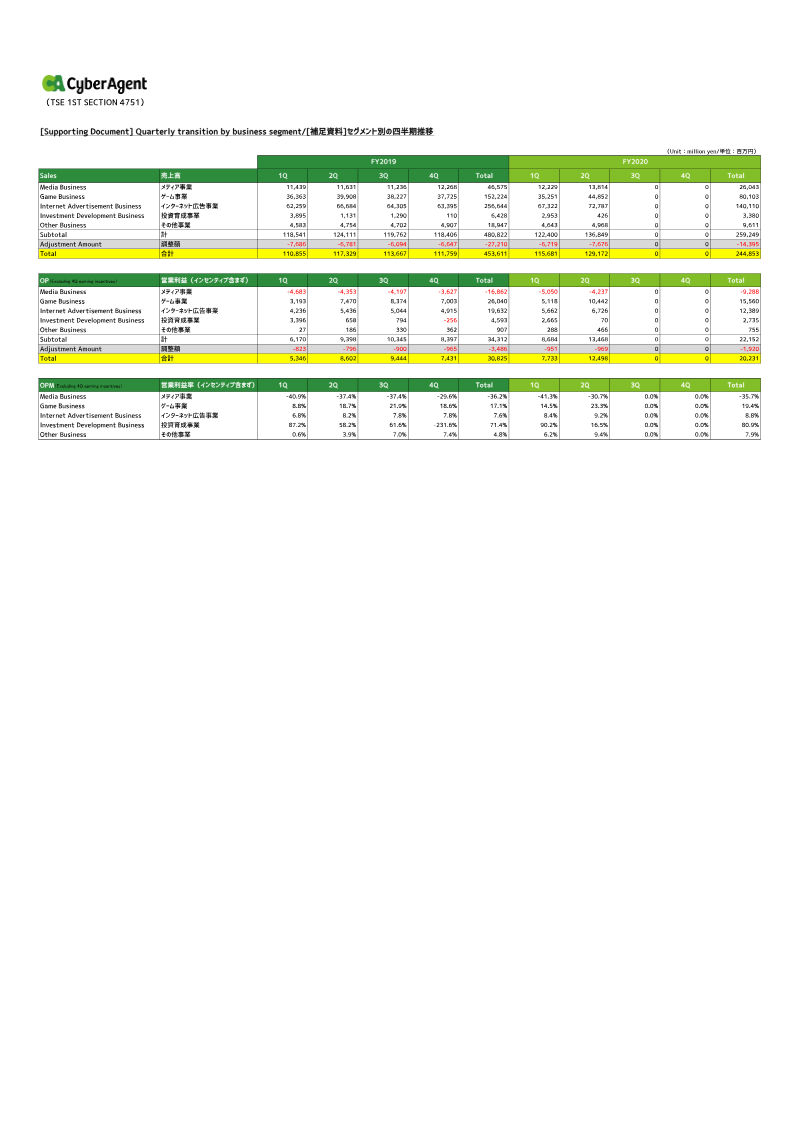
Supporting Document: Quarterly Transition by Business Segment
Financial performance data for the fiscal years 2019 and 2020 reveals a period of significant growth and operational scaling across multiple business segments, including media, gaming, internet advertising, and investment development. The data covers the full four quarters of FY2019 and the first two quarters of FY2020, providing a comparative look at quarterly transitions in sales, operating profit, and operating profit margins. Total sales increased from 453.6 billion yen in FY2019 to 244.8 billion yen in just the first half of FY2020, indicating a strong upward trajectory.
The internet advertisement business remains the largest revenue driver, generating 256.6 billion yen in FY2019 and reaching 140.1 billion yen by the midpoint of FY2020. While the media business continues to operate at a loss as it scales, its operating profit margin improved from negative 40.9% in the first quarter of FY2019 to negative 30.7% by the second quarter of FY2020. In contrast, the game business serves as a primary profit engine, showing substantial margin expansion. Game segment operating profit rose from 3.2 billion yen in the first quarter of FY2019 to 10.4 billion yen in the second quarter of FY2020, with margins climbing from 8.8% to 23.3% in that same period.
Overall profitability has strengthened significantly over the tracked timeframe. Total operating profit for the first half of FY2020 reached 20.2 billion yen, which is approximately 65% of the total profit recorded for the entire previous fiscal year. This growth is underpinned by the combined performance of the advertising and gaming sectors, which offset the planned investment losses in the media segment. The investment development business remains highly volatile, with margins fluctuating between 90.2% and negative 231.6% depending on the timing of asset realizations.
- The company is on a strong growth trajectory, with total sales reaching 244.8 billion yen in the first half of FY2020 compared to 453.6 billion yen for the entirety of FY2019.
- The game business is the primary profit engine, with operating profit increasing from 3.2 billion yen in Q1 FY2019 to 10.4 billion yen in Q2 FY2020, while margins expanded from 8.8% to 23.3%.
- Total operating profit for the first half of FY2020 reached 20.2 billion yen, representing approximately 65% of the total profit recorded for the full 2019 fiscal year.
- The internet advertisement segment remains the largest revenue driver, contributing 256.6 billion yen in FY2019 and 140.1 billion yen in the first half of FY2020.
- The media business continues to operate at a loss, though it is scaling effectively as evidenced by operating profit margins improving from negative 40.9% in Q1 FY2019 to negative 30.7% in Q2 FY2020.
+2
CyberAgentOct 2021