CyberAgent
Game Co.111 documents
Internet/media company, parent of Cygames (Granblue Fantasy, Uma Musume, Princess Connect). Game segment is major revenue driver.
Documents

Financial11 pages
Partial Correction to FY2025 First Quarter Consolidated Financial Results [Japanese GAAP]
CyberAgent, Inc. issued this formal correction to its consolidated financial results for the first quarter of fiscal year 2025, covering the period from October 1, 2024, to December 31, 2024. The primary purpose of the disclosure is to provide revised numerical data and financial statements following the submission of correction reports for past annual securities reports. The scope of the report encompasses the company’s primary business segments in Japan, including Media and IP, Internet Advertisement, Gaming, and Investment Development.
The revised data shows that CyberAgent achieved net sales of ¥203.8 billion, a 5.8% increase year-on-year. Operating income rose significantly by 41.6% to ¥8.3 billion, while ordinary income grew 45.4% to ¥8.8 billion. Net income attributable to owners of the parent reached ¥5.07 billion, a notable recovery from the ¥892 million loss recorded in the same period the previous year. Performance varied by segment: the Internet Advertisement Business remained the largest contributor with ¥117.8 billion in sales, while the Media and IP Business turned profitable due to loss reductions at ABEMA. Conversely, the Game Business saw a 15.1% decline in sales to ¥38.2 billion, attributed to the slowdown of existing titles and a ¥1.27 billion impairment loss.
Methodologically, the financial results were prepared in accordance with Japanese GAAP. A significant structural change was noted in the reporting methodology, as the company integrated its "Other Businesses" into the newly renamed "Media and IP Business" to better align with its multimedia franchise strategy. Despite the internal corrections to historical data, the company maintained its full-year forecast for fiscal year 2025, projecting net sales of ¥820 billion and operating income of ¥42 billion.
- CyberAgent reported Q1 FY2025 net sales of ¥203.8 billion, a 5.8% year-on-year increase, with operating income rising 41.6% to ¥8.3 billion.
- Net income attributable to owners of the parent reached ¥5.07 billion, marking a significant recovery from the ¥892 million loss recorded in the same period last year.
- The Game Business segment experienced a 15.1% decline in sales to ¥38.2 billion, impacted by the slowdown of existing titles and a ¥1.27 billion impairment loss.
- The Internet Advertisement Business remains the company's primary revenue driver, contributing ¥117.8 billion in sales for the quarter.
- The Media and IP Business achieved profitability during the quarter, driven primarily by successful loss reduction efforts at the ABEMA platform.
CyberAgentMay 2025
Financial10 pages
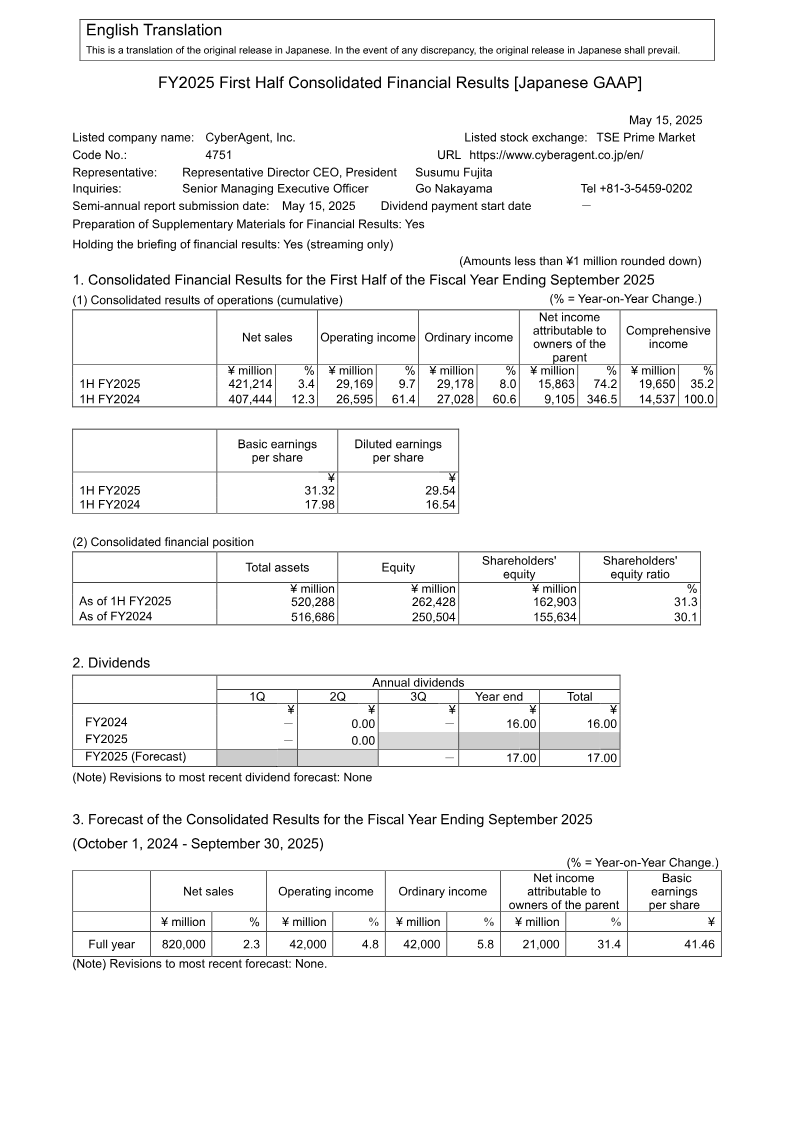
FY2025 First Half Consolidated Financial Results (Japanese GAAP)
CyberAgent achieved a consolidated net sales increase of 3.4% year-on-year, reaching ¥421.2 billion during the first half of fiscal year 2025. This growth was accompanied by a substantial 74.2% surge in net income attributable to owners, which rose to ¥15.86 billion. These results reflect a period of strategic transition and stabilization across the company’s diverse portfolio, which primarily spans the Japanese market. Despite fluctuations in individual business units, the organization maintained its full-year guidance of ¥820 billion in net sales and ¥42 billion in operating income, signaling confidence in its long-term financial trajectory.
The Internet Advertisement Business remains the primary engine of revenue, contributing ¥225.6 billion to the total. Simultaneously, the newly restructured Media & IP Business demonstrated a successful operational pivot, moving from a prior loss to a segment profit of ¥4.7 billion. This turnaround highlights improved profitability and steady growth within the company’s media assets. In contrast, the Game Business faced significant headwinds, reporting a 20.1% decline in sales and a 13.9% drop in operating income. This downturn is attributed to challenging year-on-year comparisons following a major console hit in 2024, though the segment still contributed a meaningful ¥18.7 billion to overall income.
Financial stability remains robust, with formal disclosures confirming no significant changes in shareholders' equity or concerns regarding the company’s status as a going concern. By merging peripheral operations into the Media & IP segment and maintaining market leadership in digital advertising, the company has offset the cyclical volatility inherent in the gaming sector. The overall performance for the first half of FY2025 underscores a shift toward more diversified profit streams and enhanced operational efficiency across its core Japanese business segments.
- CyberAgent reported a 3.4% year-on-year increase in consolidated net sales to ¥421.2 billion for the first half of FY2025, with net income rising 74.2% to ¥15.86 billion.
- The company maintained its full-year guidance of ¥820 billion in net sales and ¥42 billion in operating income, citing confidence in its long-term financial trajectory.
- The Internet Advertisement Business remains the primary revenue driver, contributing ¥225.6 billion to the total consolidated sales.
- The Game Business experienced a downturn, with sales declining 20.1% and operating income falling 13.9% due to difficult year-on-year comparisons following a 2024 console hit.
- The Media & IP Business successfully pivoted to profitability, generating a segment profit of ¥4.7 billion after previously operating at a loss.
+1
CyberAgentMay 2025

Financial37 pages
1Q FY2025 Presentation Material: October to December 2024
CyberAgent’s financial results for the first quarter of fiscal year 2025, covering October to December 2024, indicate a strong start to the year with consolidated sales reaching 203.8 billion yen, a 5.6% increase year-over-year. Operating income rose significantly by 32.1% to 8.3 billion yen, driven primarily by the improved profitability of the Media & IP segment and steady growth in Internet Advertising. The company has achieved approximately 25% of its full-year sales forecast and 20% of its operating profit target, maintaining a positive trajectory toward its annual goals.
The Media & IP business, which now includes the ABEMA streaming platform, saw revenue grow 10.5% to 55.6 billion yen. This segment transitioned to a 1.4 billion yen operating profit, a substantial recovery from previous losses, attributed to the reduction of upfront investment costs for ABEMA and high engagement with anime and combat sports content. The Internet Advertisement business remains the largest revenue contributor, growing 11.8% to 117.7 billion yen through new client acquisitions and AI-driven operational efficiencies. Conversely, the Game business experienced a 15.1% decline in revenue to 38.2 billion yen and a 4.1% dip in profit, as the natural slowdown of older titles offset the performance of newer releases.
The medium-to-long-term strategy focuses on evolving the Media & IP segment into a primary profit pillar alongside advertising and gaming. CyberAgent plans to accelerate IP production, evidenced by the January 2025 founding of the anime production company CA Soa, Inc. The gaming pipeline remains active with over six new titles planned for the remainder of the fiscal year, including international versions of major franchises. By leveraging synergies between ABEMA’s distribution reach and internal IP creation, the company aims to build a high-profit business model capable of sustained global growth.
- CyberAgent reported 1Q FY2025 consolidated sales of 203.8 billion yen, a 5.6% year-over-year increase, with operating income rising 32.1% to 8.3 billion yen.
- The Media & IP segment, including ABEMA, transitioned to a 1.4 billion yen operating profit on 55.6 billion yen in revenue, driven by reduced investment costs and high engagement with anime and combat sports.
- The Internet Advertisement business grew 11.8% to 117.7 billion yen, remaining the company's largest revenue contributor due to new client acquisitions and AI-driven efficiencies.
- The Game business experienced a 15.1% revenue decline to 38.2 billion yen and a 4.1% profit dip as the natural lifecycle slowdown of older titles outweighed new releases.
- CyberAgent has achieved 25% of its full-year sales forecast and 20% of its operating profit target for FY2025.
+1
CyberAgentJan 2025
Financial54 pages
FY2024 Presentation Material
CyberAgent achieved record consolidated sales of 802.9 billion yen in fiscal year 2024, representing an 11.5% year-over-year increase, while operating profit surged 70.4% to 41.8 billion yen. This performance marks a significant recovery for the Game business, which returned to growth for the first time in three years, and a narrowing of losses within the Media segment. The company’s strategic focus on operational efficiency through proprietary generative AI models and the expansion of its intellectual property portfolio drove these results. Projections for fiscal year 2025 suggest continued momentum, with a forecasted 29.3% increase in net income and a planned dividend hike to 17 yen.
The Game business remains a primary profit driver, generating 195.9 billion yen in annual sales and a 34.6% increase in operating profit. Success was largely attributed to the sustained popularity of the Umamusume: Pretty Derby franchise and the launch of five new titles. Simultaneously, the Media segment, anchored by ABEMA, reached a record 30.29 million weekly active users and grew sales by 22.4%. To enhance monetization, the segment is transitioning to a tiered pricing model for ABEMA Premium and leveraging group-wide synergies to develop original IPs across anime, film, and gaming.
The Internet Advertisement segment improved margins by integrating AI into its operations, contributing to the overall stability of the group. While fourth-quarter operating income saw a more modest 5.7% increase due to ongoing investments in social infrastructure and long-term profitability, the broader outlook remains positive. Future growth is expected to be supported by a robust pipeline of upcoming titles, including Chiikawa Pocket, and the continued evolution of the company’s media ecosystem into a sustainable, diversified entertainment platform.
- CyberAgent achieved record consolidated sales of 802.9 billion yen in FY2024, an 11.5% year-over-year increase, with operating profit surging 70.4% to 41.8 billion yen.
- The Game business returned to growth for the first time in three years, generating 195.9 billion yen in sales and a 34.6% increase in operating profit driven by Umamusume: Pretty Derby and five new title launches.
- ABEMA reached a record 30.29 million weekly active users with a 22.4% increase in sales, and is now transitioning to a tiered pricing model to improve monetization.
- The company projects continued momentum for FY2025, forecasting a 29.3% increase in net income and planning a dividend hike to 17 yen.
- Operational efficiency across the group was bolstered by the integration of proprietary generative AI models, which improved margins in the Internet Advertisement segment.
+2
CyberAgentOct 2024
Financial18 pages
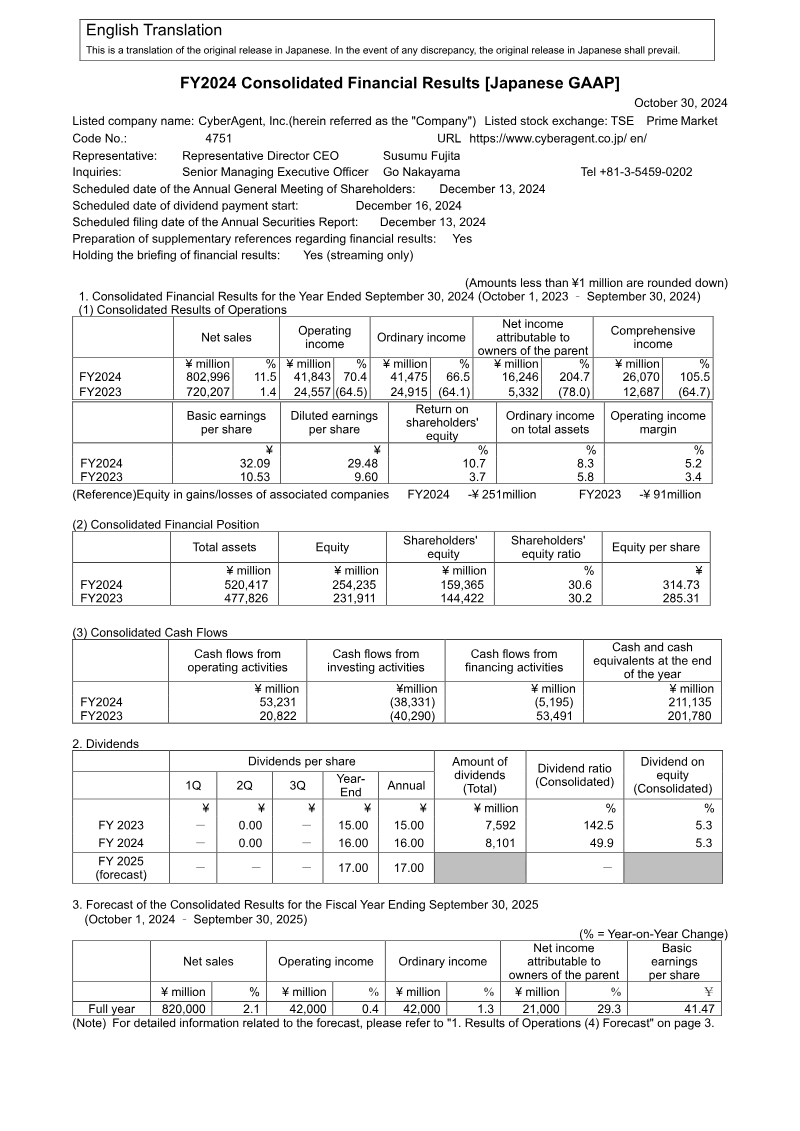
FY2024 Consolidated Financial Results (Japanese GAAP): Japan
CyberAgent achieved significant financial expansion during the 2024 fiscal year, characterized by an 11.5% increase in consolidated net sales to ¥802,996 million and a dramatic 204.7% surge in net income. This performance was primarily driven by the robust recovery of the Game Business, which saw operating income rise by 34.6%, and a strategic narrowing of losses within the Media Business. The "ABEMA" platform moved closer to profitability, reducing its annual losses from ¥11.5 billion to ¥1.9 billion. These results supported a strengthened cash position, with operating cash flow reaching ¥53,231 million and total equity rising to ¥254,235 million.
The geographic scope of these operations remains heavily concentrated in Japan, where over 90% of sales and assets are located. While the Game Business remains a primary revenue driver with ¥195,648 million in sales, it also faced challenges, including a rise in impairment losses to ¥5,102 million. Despite these specific write-downs, overall corporate profitability improved substantially, as evidenced by basic earnings per share rising from ¥10.53 to ¥32.09. The company also increased its annual dividend to ¥16 per share, reflecting confidence in its liquidity and long-term asset growth, including a doubling of its goodwill balance.
Projections for the 2025 fiscal year indicate a continued upward trajectory, with forecasted sales of ¥820 billion and a 29.3% increase in net income. This growth strategy relies on the Media Business achieving full profitability and the Internet Advertising segment maintaining its steady expansion. The Game Business intends to sustain its current momentum through a combination of new title launches and lifecycle extensions for existing high-performing games. Based on these targets, the year-end dividend is expected to rise further to ¥17 per share, signaling a transition from heavy infrastructure investment toward a phase of sustained earnings growth.
- CyberAgent reported a 204.7% surge in net income for FY2024, with consolidated net sales rising 11.5% to ¥802,996 million.
- The Game Business drove performance with a 34.6% increase in operating income and ¥195,648 million in sales, despite recording ¥5,102 million in impairment losses.
- The ABEMA media platform significantly reduced annual losses from ¥11.5 billion to ¥1.9 billion, moving the segment closer to full profitability.
- Basic earnings per share tripled from ¥10.53 to ¥32.09, supporting an increase in the annual dividend to ¥16 per share.
- FY2025 projections target ¥820 billion in sales and a 29.3% increase in net income, with the year-end dividend expected to rise to ¥17 per share.
CyberAgentOct 2024

Financial43 pages
3Q FY2024 Presentation Material
CyberAgent demonstrated significant financial momentum during the third quarter of fiscal year 2024, characterized by a 10.9% year-over-year increase in consolidated sales to 190.3 billion yen and a nearly fivefold surge in operating income to 8.5 billion yen. This robust performance, primarily driven by a resurgence in the gaming sector and continued expansion in digital media, prompted an upward revision of the full-year operating income forecast to 41 billion yen. The results reflect a successful stabilization of core business pillars and a strategic pivot toward high-growth intellectual properties and cross-media monetization.
The Game business served as a primary growth engine, recording 38.8 billion yen in sales and a return to profitability with 5.1 billion yen in operating income. This recovery was fueled by the successful May 2024 launch of Gakuen iDOLM@STER and the sustained performance of established franchises like Umamusume: Pretty Derby. Simultaneously, the Media segment achieved record engagement levels, with ABEMA reaching 27.4 million weekly active users in June 2024. This growth is supported by a strategic focus on original IP ownership, exemplified by the acquisition of Nitro Plus and the development of creative infrastructure like the Manga Apartment VUY project.
Looking ahead, the corporate strategy emphasizes a fusion of technology and creativity to scale operations globally. By leveraging a diverse portfolio that includes major titles such as Final Fantasy VII Ever Crisis and Jujutsu Kaisen Phantom Parade alongside its dominant internet advertising business, the firm aims to capitalize on digital transformation trends. The transition toward a merit-based corporate structure and an expanded creative ecosystem underscores a long-term commitment to maintaining a competitive edge in the international entertainment and advertising markets.
- CyberAgent reported a 10.9% year-over-year increase in consolidated sales to 190.3 billion yen and a nearly fivefold surge in operating income to 8.5 billion yen for 3Q FY2024.
- The company raised its full-year operating income forecast to 41 billion yen following the strong quarterly performance.
- The Game business returned to profitability with 5.1 billion yen in operating income on 38.8 billion yen in sales, driven by the May 2024 launch of Gakuen iDOLM@STER and the performance of Umamusume: Pretty Derby.
- The Media segment reached record engagement levels, with ABEMA recording 27.4 million weekly active users in June 2024.
- CyberAgent is expanding its creative ecosystem through the acquisition of Nitro Plus and the development of the Manga Apartment VUY project.
+1
CyberAgentJul 2024
Financial37 pages
FY2024 Presentation Material: January–March 2024
CyberAgent’s financial results for the second quarter of fiscal year 2024 reflect a period of record-breaking sales and significant profit recovery. Consolidated net sales reached 215.1 billion yen, a 10% increase year-on-year, while operating income rose 12.2% to 21.0 billion yen. This performance marks a strategic pivot toward a new growth phase, with the company successfully positioning FY2023 as its earnings floor.
The game business served as a primary growth engine this quarter, with sales increasing 8.1% year-on-year to 67.1 billion yen and operating income surging 421.2% quarter-on-quarter to 18.2 billion yen. These results were driven by the successful global launch of Granblue Fantasy: Relink, which sold one million units in eleven days, and the third-anniversary events for the flagship title Uma Musume Pretty Derby. The internet advertisement business also achieved record sales of 107.3 billion yen, maintaining steady growth through the integration of generative AI tools to maximize ad effectiveness.
A major milestone was achieved in the media segment, where the ABEMA streaming platform turned profitable on a quarterly basis for the first time since its investment phase began. ABEMA’s weekly active users grew to 23.64 million, supported by expanded sports programming through partnerships with DAZN and WOWOW. Across all segments, the company is leveraging technological advantages, including proprietary large language models and AI-driven production studios, to improve operational efficiency.
Based on these results, the company reports strong progress toward its full-year forecasts, having already achieved over 90% of its annual operating profit target by the end of the second quarter. The strategic outlook focuses on stabilizing the game business through long-term IP management and establishing ABEMA as a permanent fixture of social infrastructure.
- CyberAgent achieved record consolidated net sales of 215.1 billion yen in Q2 FY2024, a 10% year-on-year increase, with operating income rising 12.2% to 21.0 billion yen.
- The game business segment saw operating income surge 421.2% quarter-on-quarter to 18.2 billion yen, driven by the global launch of Granblue Fantasy: Relink and Uma Musume Pretty Derby anniversary events.
- The ABEMA streaming platform reached quarterly profitability for the first time, supported by a weekly active user base of 23.64 million and expanded sports programming partnerships.
- CyberAgent has already secured over 90% of its full-year operating profit target by the end of the second quarter.
- The internet advertisement business reached record sales of 107.3 billion yen, bolstered by the integration of generative AI tools to enhance ad performance.
+2
CyberAgentApr 2024
Financial9 pages
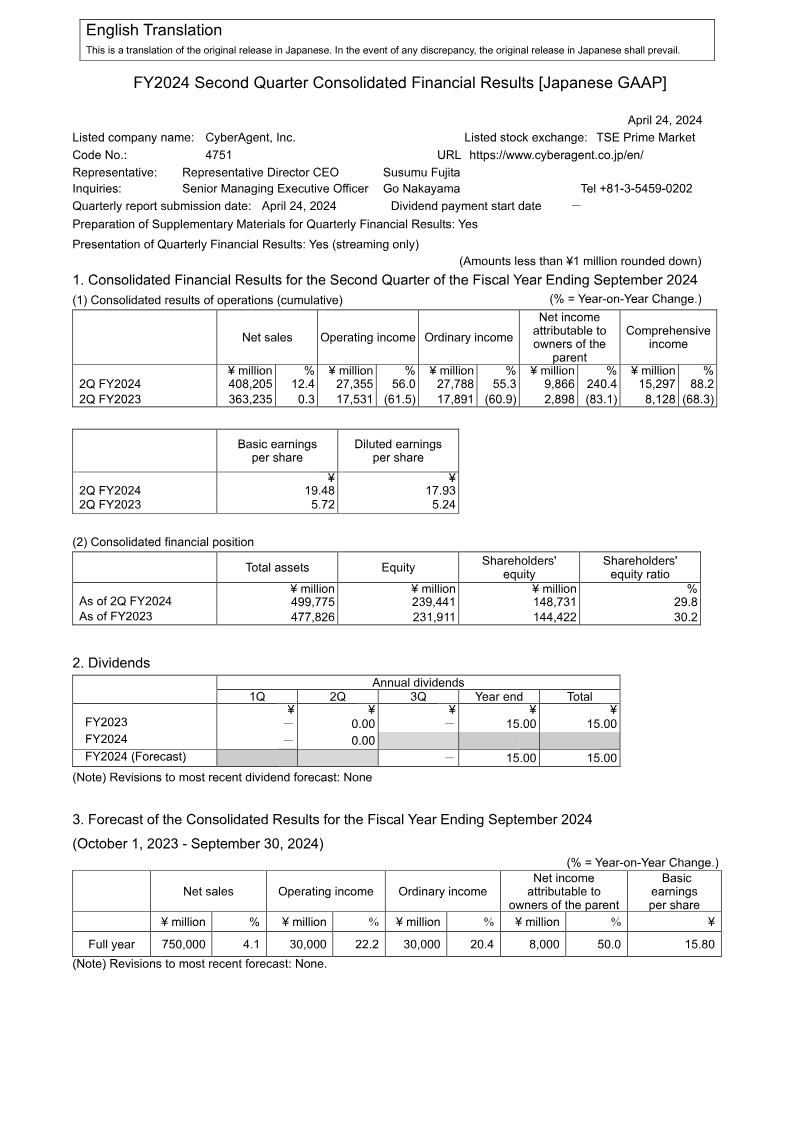
FY2024 Second Quarter Consolidated Financial Results [Japanese GAAP]
CyberAgent’s financial performance for the second quarter of fiscal year 2024 reflects robust growth across its core business pillars, characterized by a 12.4% year-over-year increase in net sales to ¥408.2 billion. Operating income saw a substantial surge of 56%, reaching ¥27.4 billion. This upward trajectory was primarily fueled by record-high sales in the internet advertising division and the successful launch of a new hit title within the game business. Furthermore, the media segment, anchored by the ABEMA streaming platform, demonstrated improved fiscal health by significantly narrowing its operating losses.
The game business remains the organization’s primary profit engine, generating ¥21.7 billion in segment income from ¥112.2 billion in sales during this period. While net income attributable to the parent rose to ¥9.9 billion, the company faced higher extraordinary losses stemming from strategic business withdrawals and asset impairments. Despite these costs, the financial position remains stable with a cash reserve of ¥205.6 billion. Corporate general and administrative expenses remained consistent, with approximately ¥4.69 billion in unallocated costs reported for the quarter.
Although current net income figures have already surpassed initial full-year targets, the official fiscal year 2024 forecast remains unchanged. This conservative stance accounts for potential volatility in the market valuations of subsidiary stocks and other external economic factors. The results indicate a period of strategic consolidation and operational efficiency, where high-performing segments are effectively offsetting the investment costs associated with long-term media projects and portfolio optimization.
- CyberAgent achieved a 12.4% year-over-year increase in net sales to ¥408.2 billion and a 56% surge in operating income to ¥27.4 billion for Q2 FY2024.
- The game business remains the primary profit driver, contributing ¥21.7 billion in segment income from ¥112.2 billion in total sales.
- Growth was primarily driven by record-high sales in the internet advertising division and the successful launch of a new hit title in the game segment.
- The media segment, anchored by the ABEMA streaming platform, significantly narrowed its operating losses, contributing to improved overall fiscal health.
- Net income attributable to the parent reached ¥9.9 billion, despite the company absorbing higher extraordinary losses from strategic business withdrawals and asset impairments.
CyberAgentApr 2024

Financial34 pages
1Q FY2024 Presentation Material: October to December 2023
CyberAgent’s financial results for the first quarter of fiscal year 2024, covering October to December 2023, demonstrate a strong start across its three primary business segments: Internet Advertisement, Game, and Media. Consolidated net sales reached 193.0 billion yen, a 15.2% increase year-over-year, while operating income rose to 6.2 billion yen, reversing a loss from the same period the previous year. This performance aligns with the strategic goal of establishing fiscal year 2023 as a profit trough and entering a new growth phase.
The Internet Advertisement business remains the primary revenue driver, generating 105.3 billion yen in sales (up 10.1% YoY) with an improving operating profit margin of 5.4%. The Game business saw a recovery in sales to 45.0 billion yen (up 10.1% YoY) driven by the successful launch of Jujutsu Kaisen Phantom Parade, though operating profit declined 32.9% YoY to 3.4 billion yen. The Media business, centered on ABEMA, significantly reduced its operating losses to 0.9 billion yen, an 8.3 billion yen improvement over the previous year, supported by a 27.8% increase in sales and the growth of Weekly Active Users to over 20 million during peak periods.
Geographically focused on the Japanese market with expanding digital interests, the data indicates that the company is on track to meet its full-year forecast of 750 billion yen in sales and 30 billion yen in operating profit. Methodology involves consolidated financial reporting of internal business units and user engagement metrics for digital platforms. The long-term strategy emphasizes the digital shift of industries through AI and DX in advertising, the creation of high-quality global game titles, and the evolution of ABEMA into a profitable social infrastructure.
- CyberAgent reported consolidated net sales of 193.0 billion yen for 1Q FY2024, a 15.2% year-over-year increase, with operating income reaching 6.2 billion yen compared to a loss in the same period last year.
- The Media business, anchored by ABEMA, achieved an 8.3 billion yen improvement in operating performance, reducing losses to 0.9 billion yen alongside a 27.8% increase in sales and peak Weekly Active Users exceeding 20 million.
- The Internet Advertisement segment remains the company's largest revenue contributor, generating 105.3 billion yen in sales—a 10.1% year-over-year increase—with an operating profit margin of 5.4%.
- Game business sales rose 10.1% year-over-year to 45.0 billion yen, bolstered by the launch of 'Jujutsu Kaisen Phantom Parade', though operating profit for the segment fell 32.9% to 3.4 billion yen.
- The company remains on track to achieve its full-year fiscal forecast of 750 billion yen in sales and 30 billion yen in operating profit.
+2
CyberAgentJan 2024

Financial54 pages
FY 2023 Presentation Material
CyberAgent achieved record consolidated sales of 720.2 billion yen in fiscal year 2023, marking twenty-six consecutive years of growth despite a 64.5% decline in operating profit to 24.5 billion yen. This financial divergence was primarily driven by the natural slowdown of the major hit title Uma Musume Pretty Derby, which caused the gaming segment to experience a 21.6% drop in sales and a 62.5% decrease in profit. However, the fourth quarter showed signs of recovery with a 25.4% sequential increase in gaming revenue following the successful launch of Final Fantasy VII Ever Crisis.
The media segment, centered on the ABEMA platform, demonstrated significant momentum by narrowing its operating losses and reaching nearly 18.8 million weekly active users. ABEMA’s 25.9% year-over-year growth was bolstered by the expansion of high-growth related businesses such as WINTICKET, which saw transaction volumes increase by 30%. Meanwhile, the internet advertisement business maintained steady performance, supported by strategic investments in digital transformation and the aggressive implementation of generative AI to enhance production efficiency.
Looking toward fiscal year 2024, the strategic focus shifts toward stabilizing the gaming portfolio through global console releases for the Granblue Fantasy franchise and the launch of at least three new titles. The company forecasts a recovery in operating profit to 30 billion yen, underpinned by the continued monetization of ABEMA and the opening of a major AI-driven production studio. By prioritizing the longevity of high-quality intellectual properties and leveraging AI across all business units, the organization aims to balance long-term media investments with the high-margin potential of its gaming and advertising sectors.
- CyberAgent achieved record consolidated sales of 720.2 billion yen in FY 2023, though operating profit fell 64.5% to 24.5 billion yen due to the performance decline of the major title Uma Musume Pretty Derby.
- The gaming segment experienced a 21.6% drop in sales and a 62.5% decrease in profit, though Q4 revenue recovered by 25.4% sequentially following the launch of Final Fantasy VII Ever Crisis.
- ABEMA reached 18.8 million weekly active users with 25.9% year-over-year growth, supported by a 30% increase in transaction volumes from the WINTICKET business.
- The company forecasts a recovery in operating profit to 30 billion yen for FY 2024, driven by the monetization of ABEMA and the launch of at least three new gaming titles.
- Strategic priorities for FY 2024 include global console releases for the Granblue Fantasy franchise and the opening of a new AI-driven production studio to improve efficiency.
+2
CyberAgentNov 2023
Financial17 pages
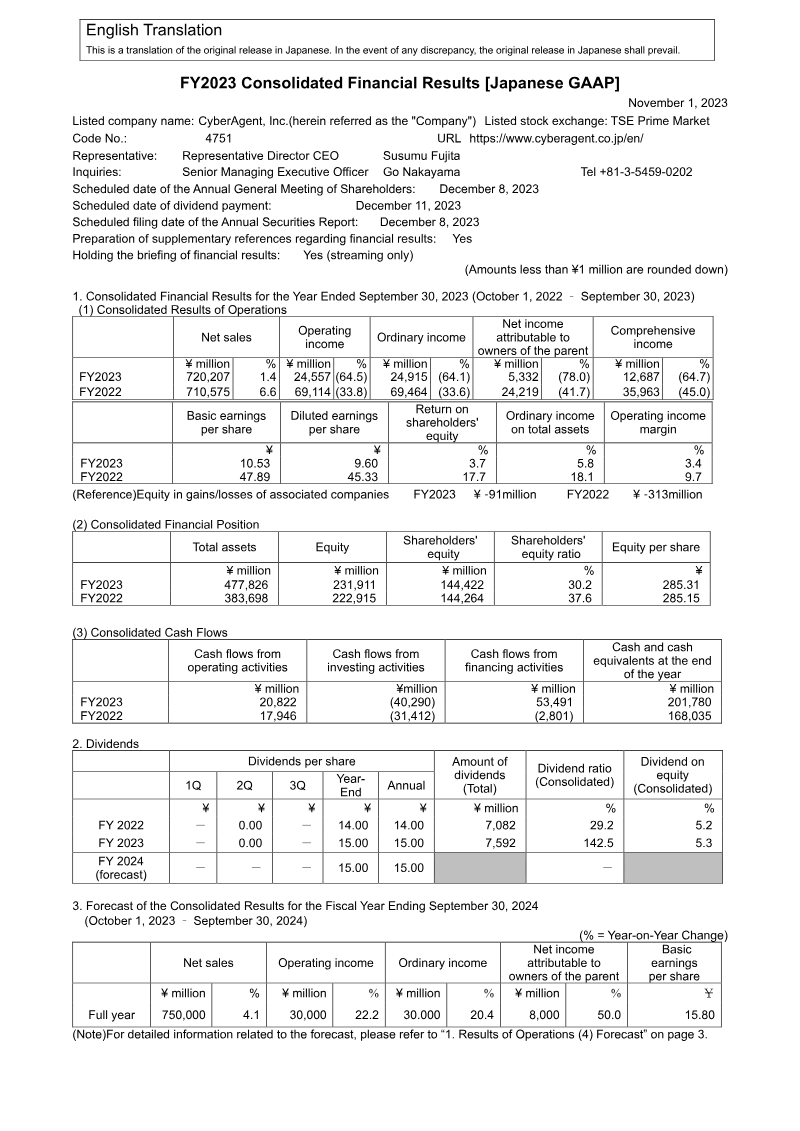
FY2023 Consolidated Financial Results [Japanese GAAP]
CyberAgent, Inc. experienced a period of significant transition during the 2023 fiscal year, characterized by modest revenue growth alongside a sharp contraction in profitability. Consolidated net sales reached ¥720,207 million, representing a 1.4% year-over-year increase, yet operating income plummeted by 64.5% to ¥24,557 million. This decline was primarily driven by the Game Business, where profits fell 62.5% due to the natural lifecycle decline of high-margin titles. Simultaneously, the Internet Advertisement segment, while remaining the largest revenue contributor at ¥381,206 million, faced margin pressure from upfront investments in artificial intelligence.
The Media Business emerged as a growth engine, with the ABEMA platform driving a 25.9% increase in segment sales and successfully narrowing its operational deficits. Despite the drop in net income attributable to owners—which fell from ¥24,219 million to ¥5,332 million—the company significantly strengthened its liquidity position. Cash and cash equivalents rose to ¥201,780 million, bolstered by over ¥53 billion in financing activities, including the issuance of convertible bonds and the acquisition of long-term bank loans. These strategic financial moves ensure a stable capital base for future expansion within the predominantly Japanese market, where over 90% of sales and assets are concentrated.
Projections for the 2024 fiscal year indicate a strategic pivot toward recovery and renewed growth. Management forecasts net sales to reach ¥750 billion, supported by a pipeline of new game releases and the continued scaling of the Media segment. Operating income is expected to rebound by 22.2%, while net income is projected to increase by 50%. This outlook suggests that the heavy investment phase and the volatility in the gaming portfolio observed in 2023 are expected to stabilize, allowing for improved earnings per share and a more balanced contribution across the advertising, gaming, and media divisions.
- CyberAgent's FY2023 operating income fell 64.5% to ¥24,557 million, primarily due to a 62.5% profit decline in the Game Business caused by the lifecycle maturity of key titles.
- Consolidated net sales grew by 1.4% to ¥720,207 million, while net income attributable to owners dropped significantly from ¥24,219 million to ¥5,332 million.
- The Media Business, led by the ABEMA platform, achieved a 25.9% increase in segment sales and successfully reduced operational deficits.
- The Internet Advertisement segment remains the company's largest revenue contributor at ¥381,206 million, though margins were compressed by upfront AI investments.
- The company bolstered its liquidity to ¥201,780 million in cash and equivalents through ¥53 billion in financing activities, including convertible bonds and long-term loans.
CyberAgentNov 2023

Financial45 pages
3Q FY2023 Presentation Material
The third quarter of fiscal year 2023 represents a transitional period characterized by a significant contraction in profitability despite stable consolidated sales of 171.7 billion yen. This financial performance was primarily impacted by the Game business, which experienced a 27% year-over-year decline in sales and a shift into operating losses as flagship titles like Uma Musume Pretty Derby moved into a post-peak stability phase. These headwinds necessitated a downward revision of the full-year operating profit forecast to 25 billion yen, signaling that the current fiscal year serves as an earnings floor for the organization.
In contrast to the volatility in gaming, the Internet Advertisement and Media segments demonstrated resilience and growth. The advertising division achieved record quarterly sales exceeding 100 billion yen, while the Media segment, anchored by ABEMA, narrowed its operating losses through a 13.1% increase in sales. ABEMA reached a milestone of over 20 million weekly active users, supported by a 1.3x surge in WINTICKET transaction volumes. Strategic expansion into the anime musical space via the acquisition of Nelke Planning further underscores an intent to diversify content revenue streams and strengthen the broader media ecosystem.
Looking toward fiscal year 2024 and beyond, the strategic focus shifts toward a recovery phase driven by technological innovation and a robust product pipeline. Investments in generative AI, including the development of a proprietary Japanese Large Language Model, are intended to enhance operational efficiency and digital transformation. Furthermore, the upcoming release of high-profile titles such as Final Fantasy VII Ever Crisis and Jujutsu Kaisen Phantom Parade is expected to revitalize the Game business. By leveraging talent management and global expansion initiatives, the group aims to return to a trajectory of sustainable earnings growth.
- The Game business shifted to an operating loss with a 27% year-over-year sales decline, leading to a downward revision of the full-year operating profit forecast to 25 billion yen.
- The Internet Advertisement segment achieved record quarterly sales exceeding 100 billion yen, providing a stable financial offset to the volatility in the gaming division.
- The Media segment, anchored by ABEMA, narrowed operating losses as sales grew 13.1% and weekly active users surpassed 20 million.
- WINTICKET transaction volumes surged 1.3x, serving as a primary growth driver for the Media segment's performance.
- The company acquired Nelke Planning to expand into the anime musical space and diversify its content revenue streams.
+1
CyberAgentJul 2023