CyberAgent
Game Co.111 documents
Internet/media company, parent of Cygames (Granblue Fantasy, Uma Musume, Princess Connect). Game segment is major revenue driver.
Documents
Presentation55 pages
FY2021 Presentation Material
CyberAgent achieved record-breaking financial performance in fiscal year 2021, characterized by consolidated sales of 666.4 billion yen and a more than threefold increase in operating profit to 104.3 billion yen. This surge was primarily catalyzed by the Game business, which experienced 68.6% year-over-year growth following the massive commercial success of Uma Musume Pretty Derby. While the Game segment provided the most significant profit contribution, the Internet Advertisement business maintained steady double-digit growth, and the Media segment narrowed its operating losses through the expansion of ABEMA and the WINTICKET betting platform.
The strategic focus for the period centered on leveraging high-performing assets to fund long-term growth initiatives. WINTICKET emerged as a critical driver within the Media segment, capturing 25% of the Keirin online betting market and tripling its transaction volume. Simultaneously, the company utilized profits from its established advertising and gaming pillars to invest in ABEMA’s digital transformation and content offerings, including pay-per-view services. This diversification strategy aims to stabilize the inherent volatility of the gaming industry, which led to the omission of specific earnings forecasts for the upcoming fiscal year.
Future growth is predicated on a robust pipeline of high-profile intellectual properties and strategic partnerships with industry leaders such as Nintendo, SEGA, and Bandai Namco. Upcoming releases, including titles based on the Final Fantasy VII and Jujutsu Kaisen franchises, are expected to sustain the momentum established in 2021. By aligning its corporate purpose with digital innovation and cross-media expansion, the organization seeks to transition from a gaming-heavy profit structure toward a more balanced ecosystem where media and advertising provide consistent, long-term value.
- CyberAgent achieved record-breaking FY2021 performance with 666.4 billion yen in consolidated sales and a 104.3 billion yen operating profit, representing a more than threefold increase.
- The Game business was the primary profit driver, recording 68.6% year-over-year growth fueled by the commercial success of Uma Musume Pretty Derby.
- WINTICKET captured 25% of the Keirin online betting market and tripled its transaction volume, significantly contributing to reduced operating losses in the Media segment.
- The Internet Advertisement business maintained steady double-digit growth, serving as a stable financial pillar alongside the high-volatility gaming segment.
- Management opted not to provide earnings forecasts for the upcoming fiscal year due to the inherent revenue volatility associated with the gaming industry.
+1
CyberAgentOct 2021
Financial19 pages
FY2021 Consolidated Financial Results [Japanese GAAP]
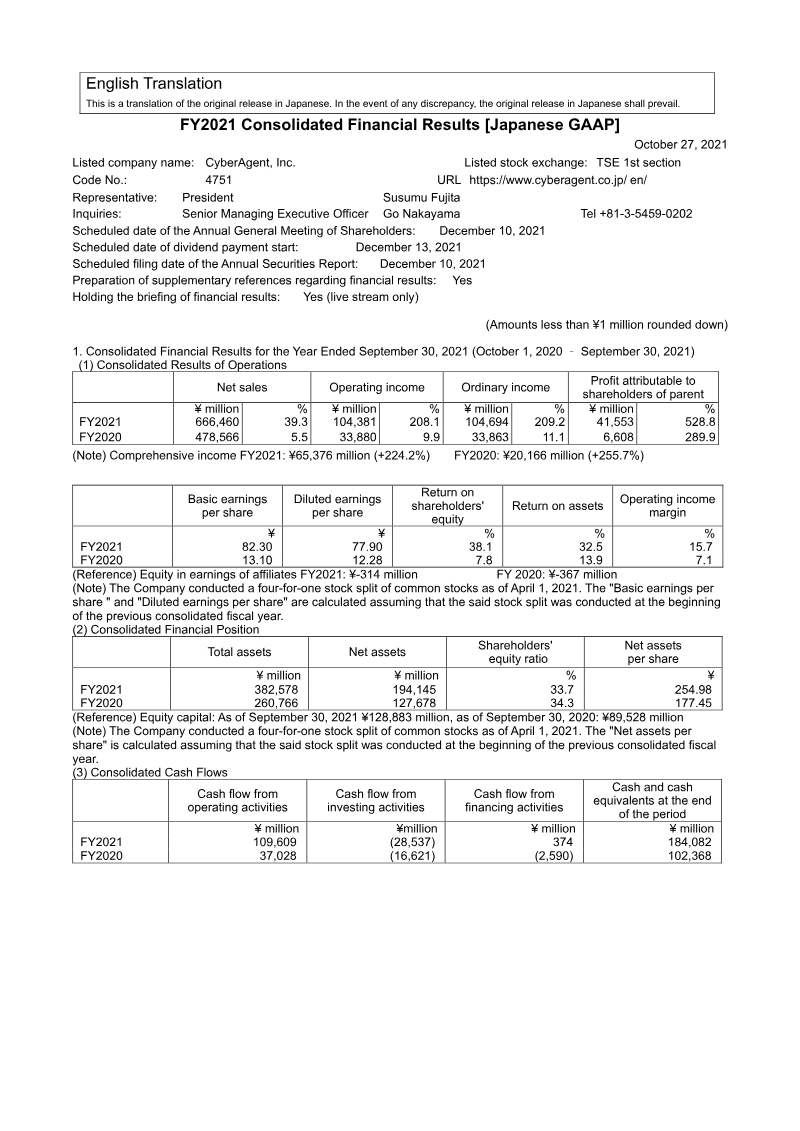
CyberAgent, Inc. achieved exceptional financial growth during the 2021 fiscal year, characterized by record-breaking performance across its primary business segments. Consolidated net sales rose 39.3% to ¥666,460 million, while operating income experienced a dramatic surge of 208.1%, reaching ¥104,381 million. This momentum was largely fueled by the Game Business, which saw net sales increase by 68.6% and operating income jump 217.9% to ¥96,445 million, primarily due to the massive success of a major new title. The Internet Advertisement and Media businesses also contributed to these record highs, resulting in a nearly fivefold increase in net income to ¥66,671 million.
The company’s financial position strengthened considerably over this period, with total assets expanding to ¥382,578 million and cash and cash equivalents rising to ¥184,082 million. Robust operating cash flows of ¥109,609 million provided the liquidity necessary to fund investment securities and subsidiary acquisitions while supporting a four-for-one stock split and an increased dividend of ¥11.00 per share. Profit attributable to shareholders rose from ¥6,608 million to ¥41,553 million, reflecting a significant leap in basic earnings per share from ¥13.10 to ¥82.30.
Despite this historic profitability, management has opted to withhold financial forecasts for the 2022 fiscal year. This decision stems from the inherent volatility of the gaming industry, where the timing and performance of new launches remain difficult to predict. While the Game Business currently serves as the primary engine for growth and capital accumulation, the company remains focused on balancing these high-risk, high-reward cycles with the steady expansion of its advertising and media infrastructure to ensure long-term stability.
- CyberAgent achieved record-breaking FY2021 financial results with consolidated net sales rising 39.3% to ¥666,460 million and operating income surging 208.1% to ¥104,381 million.
- The Game Business served as the primary growth driver, delivering a 68.6% increase in net sales and a 217.9% jump in operating income to ¥96,445 million, largely due to a successful new title launch.
- Net income for the fiscal year increased nearly fivefold to ¥66,671 million, with profit attributable to shareholders rising from ¥6,608 million to ¥41,553 million.
- Basic earnings per share grew significantly from ¥13.10 to ¥82.30, supporting a four-for-one stock split and an increased dividend of ¥11.00 per share.
- The company’s financial position strengthened with total assets reaching ¥382,578 million and cash and cash equivalents rising to ¥184,082 million.
CyberAgentOct 2021
Presentation50 pages
3Q FY2021 Presentation Material: April to June 2021
CyberAgent experienced exceptional financial growth during the third quarter of fiscal year 2021, covering the period from April to June. Consolidated sales reached 192.2 billion yen, representing a 70.3% year-over-year increase, while operating profit surged more than fivefold to 44.5 billion yen. This performance was primarily catalyzed by the Game business, specifically the massive commercial success of Uma Musume Pretty Derby. The title surpassed nine million downloads within five months of its launch, driving segment sales up by 151.7% and operating profit by over 480%. The success of this intellectual property has further expanded into a multi-media franchise encompassing anime, music, and live events, prompting an upward revision of full-year forecasts to 650 billion yen in sales and 100 billion yen in operating profit.
The media segment, led by the streaming platform ABEMA, also demonstrated significant momentum with quarterly sales more than doubling to 10.5 billion yen. Weekly Active Users reached a peak of 14.9 million, supported by high-profile sports broadcasting and original content. A critical component of this segment's monetization strategy is the WINTICKET online betting service, which saw transaction volumes grow 5.5 times year-over-year to 39.3 billion yen through strategic integration with ABEMA’s programming.
Beyond current hits, the strategic focus remains on technological innovation and pipeline development. The advertising business reported high adoption rates for AI-driven creative tools, while the gaming division is preparing for future growth with high-profile upcoming titles based on the Final Fantasy VII and Jujutsu Kaisen franchises. These results indicate a robust diversification strategy where high-performing gaming assets and integrated media services drive record-breaking financial outcomes across the Japanese market.
- CyberAgent’s consolidated sales grew 70.3% year-over-year to 192.2 billion yen in 3Q FY2021, with operating profit increasing more than fivefold to 44.5 billion yen.
- The 'Uma Musume Pretty Derby' game drove a 151.7% increase in gaming segment sales and a 480% surge in operating profit, reaching nine million downloads within five months of launch.
- Driven by the success of 'Uma Musume', CyberAgent revised its full-year forecasts upward to 650 billion yen in sales and 100 billion yen in operating profit.
- The ABEMA streaming platform saw quarterly sales more than double to 10.5 billion yen, supported by a peak of 14.9 million Weekly Active Users.
- The WINTICKET online betting service, integrated with ABEMA, achieved a 5.5-fold year-over-year increase in transaction volume to 39.3 billion yen.
+1
CyberAgentJul 2021

Financial9 pages
FY2021 Third Quarter Consolidated Financial Results (Japanese GAAP)
CyberAgent’s consolidated financial results for the third quarter of fiscal year 2021, ending June 30, 2021, reveal a period of significant growth and upward momentum. Net sales reached ¥486.7 billion, a 36.1% increase year-on-year, while operating income surged by 171.9% to ¥77.5 billion. Profit attributable to shareholders of the parent saw the most dramatic rise, increasing 462.1% to ¥33.0 billion. This performance was driven primarily by the Game Business and the Internet Advertisement Business, leading the company to revise its full-year earnings and dividend forecasts upward.
The Game Business served as a primary growth engine, with net sales rising 59.5% to ¥186.3 billion and operating income jumping 196.4% to ¥68.6 billion, largely due to the significant contribution of a new game title. The Internet Advertisement Business also achieved record-high net sales of ¥239.1 billion, up 17.0%, benefiting from a steadily expanding smartphone advertising market. While the Media Business, including ABEMA, reported an operating loss of ¥11.2 billion, this represented an improvement over the previous year’s loss as the company continues to invest in the platform as a long-term strategic pillar.
Geographically focused on the Japanese market, the results reflect a cumulative nine-month period. The company’s financial position strengthened, with total assets increasing to ¥343.7 billion, supported by a four-for-one stock split executed in April 2021. Based on these results, CyberAgent raised its full-year sales forecast to ¥650 billion and its operating income forecast to ¥100 billion. The company also increased its year-end dividend forecast to ¥11 per share to maintain a Dividend on Equity (DOE) ratio of 5% or more, signaling confidence in its continued capital efficiency and business growth.
- CyberAgent reported a 36.1% year-on-year increase in net sales to ¥486.7 billion and a 171.9% surge in operating income to ¥77.5 billion for the first nine months of FY2021.
- The Game Business served as the primary growth driver, achieving a 59.5% increase in net sales to ¥186.3 billion and a 196.4% jump in operating income to ¥68.6 billion, fueled by a new title launch.
- The Internet Advertisement Business reached record-high net sales of ¥239.1 billion, representing a 17.0% year-on-year increase driven by the expanding smartphone advertising market.
- Profit attributable to shareholders rose 462.1% to ¥33.0 billion, prompting the company to raise its full-year sales forecast to ¥650 billion and operating income forecast to ¥100 billion.
- The Media Business, including ABEMA, recorded an operating loss of ¥11.2 billion, though this figure reflects a year-over-year improvement as the company maintains long-term strategic investment.
CyberAgentJul 2021
Presentation52 pages
2Q FY2021 Presentation Material: January to March 2021
CyberAgent experienced exceptional financial growth during the second quarter of fiscal year 2021, characterized by a 26.6% year-over-year increase in consolidated sales to 163.4 billion yen and a doubling of operating profit to 25.8 billion yen. This performance was primarily catalyzed by the Game business, which achieved record-high quarterly sales of 63.9 billion yen. The massive success of Uma Musume Pretty Derby, which secured over five million downloads within its first 45 days, served as the primary engine for this expansion. Coupled with the strong performance of titles like NieR Re[in]carnation and a robust pipeline including Final Fantasy VII Ever Crisis, the company significantly upgraded its full-year forecasts, raising sales targets to 600 billion yen and nearly doubling its projected operating profit range.
The media segment, centered on the ABEMA platform, demonstrated significant scale despite ongoing operating losses of 3.4 billion yen. Sales for the segment grew 1.4 times year-over-year, reaching 19.8 billion yen, bolstered by the rapid expansion of the online betting service WINTICKET. Transaction volumes for WINTICKET surged 9.1 times annually to 31.9 billion yen, highlighting a successful diversification of revenue streams beyond traditional advertising. Weekly active users remained stable at approximately 12 million, supported by a strategic mix of original dramas, variety content, and anime.
To sustain this momentum, the organization is prioritizing digital transformation and cross-media strategies. The Internet Advertisement business reached record-high performance levels, while ABEMA is undergoing a comprehensive user interface redesign to better integrate linear and on-demand viewing. These initiatives, combined with AI-driven operational efficiencies, aim to transition the media segment toward long-term monetization while maintaining the high-growth trajectory established by the gaming and advertising divisions within the Japanese market.
- CyberAgent’s consolidated sales grew 26.6% year-over-year to 163.4 billion yen in 2Q FY2021, with operating profit doubling to 25.8 billion yen.
- The Game business reached record quarterly sales of 63.9 billion yen, driven primarily by the launch of 'Uma Musume Pretty Derby,' which surpassed five million downloads in 45 days.
- Due to strong gaming performance, CyberAgent raised its full-year sales forecast to 600 billion yen and nearly doubled its projected operating profit range.
- The media segment, anchored by ABEMA, saw sales grow 1.4 times year-over-year to 19.8 billion yen, despite recording an operating loss of 3.4 billion yen.
- WINTICKET online betting transaction volume surged 9.1 times year-over-year to 31.9 billion yen, providing a critical revenue stream outside of traditional advertising.
CyberAgentApr 2021
Financial12 pages
FY2021 Second Quarter Consolidated Financial Results (Japanese GAAP)
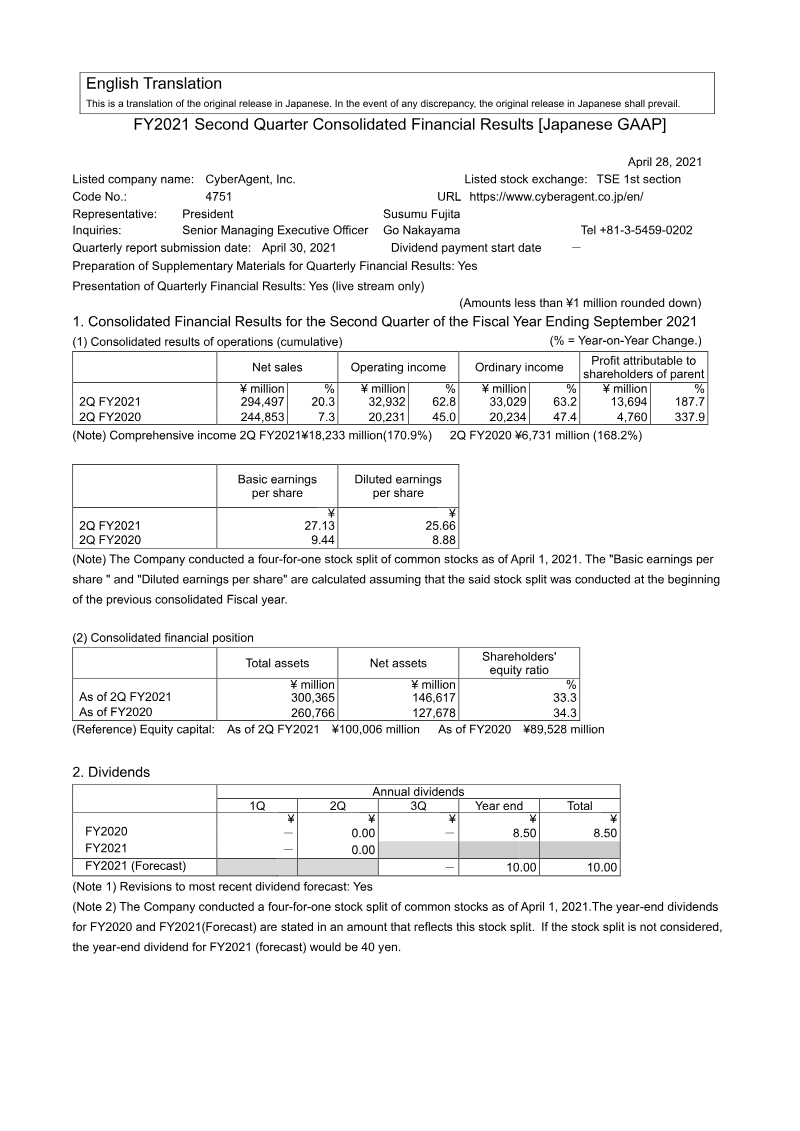
CyberAgent experienced substantial financial expansion during the first half of fiscal year 2021, characterized by a 20.3% increase in net sales to ¥294.5 billion and a 62.8% surge in operating income to ¥32.9 billion. This growth trajectory was primarily fueled by record-breaking performance in the Internet Advertisement Business and a transformative period for the Game Business. The gaming segment saw net sales reach ¥93.9 billion, while segment income rose to ¥24.3 billion, representing a 56.5% increase in operating income following the successful market entry of two major new titles. These gains effectively offset continued strategic investments in the ABEMA media platform, demonstrating the company's ability to balance long-term ecosystem development with immediate profitability.
The robust financial results prompted an upward revision of full-year earnings and dividend forecasts, with the year-end dividend set at 10 yen per share to uphold a Dividend on Equity ratio of at least 5%. Profit attributable to owners of the parent more than doubled to ¥13.7 billion, reinforcing a strong consolidated balance sheet that features over ¥100 billion in cash and total assets of ¥300.4 billion. To further enhance market accessibility and share liquidity, a four-for-one stock split was implemented in April 2021, bringing the total number of issued shares to 505.7 million and necessitating adjustments to the conversion prices of outstanding convertible bonds.
Geographically focused on the Japanese market during the second quarter of the 2021 fiscal year, the findings highlight a period of high operational efficiency and successful product launches. The synergy between the established advertising business and the high-margin gaming division has provided the capital necessary to sustain heavy investments in intangible assets and securities. This strategic positioning suggests a transition toward a more diversified digital entertainment and media conglomerate, supported by a solid financial foundation and a commitment to shareholder returns through both dividends and improved stock liquidity.
- CyberAgent reported a 20.3% increase in net sales to ¥294.5 billion and a 62.8% surge in operating income to ¥32.9 billion for the first half of fiscal year 2021.
- The Game Business segment achieved ¥93.9 billion in net sales and a 56.5% increase in operating income to ¥24.3 billion, driven by the successful launch of two major titles.
- Profit attributable to owners of the parent more than doubled to ¥13.7 billion, supported by a strong balance sheet with over ¥100 billion in cash and total assets of ¥300.4 billion.
- The company upwardly revised its full-year earnings and dividend forecasts, setting a year-end dividend of 10 yen per share to maintain a Dividend on Equity ratio of at least 5%.
- A four-for-one stock split was implemented in April 2021 to improve market accessibility and liquidity, resulting in 505.7 million total issued shares.
CyberAgentApr 2021
Presentation44 pages
1Q FY2021 Presentation Material: October to December 2020
CyberAgent achieved record-high consolidated sales of 131 billion yen during the first quarter of fiscal year 2021, representing a 13.3% year-over-year increase. This growth was primarily propelled by the Media and Advertising segments, offsetting a temporary downturn in the Game business. While the Game segment saw revenue decline 15% to 29.9 billion yen and operating profit drop 77.8% due to seasonal factors and elevated marketing expenditures, the company maintained a strong financial foundation with 252 billion yen in total assets. This performance establishes a solid trajectory toward meeting full-year targets despite the mixed results across different business units.
The Media segment emerged as a significant growth engine, with ABEMA driving a 67% surge in revenue to 20.4 billion yen. This expansion was supported by a premium subscriber base exceeding 921,000 users and an elevenfold increase in transaction volume for the WINTICKET platform. To capitalize on this momentum, the company restructured ABEMA into distinct Free and Premium business units. Simultaneously, the Game business prepared for a recovery through the high-profile launches of titles such as Uma Musume Pretty Derby and NieR Re[in]carnation, signaling a strategic focus on high-quality content to stabilize future earnings.
Corporate strategy remains centered on governance and technological adaptation within the Japanese market. The organizational structure utilizes a clear distinction between supervision and execution, supported by a board of eight directors that includes significant outside representation. By emphasizing environmental data disclosure and the integration of artificial intelligence within advertising and media functionality, the company aims to align with modern ESG standards. These initiatives, framed within the context of the New Normal, reflect a commitment to long-term sustainability and operational agility in a rapidly evolving digital landscape.
- CyberAgent achieved record-high consolidated sales of 131 billion yen in 1Q FY2021, a 13.3% year-over-year increase driven by strong performance in the Media and Advertising segments.
- The Media segment grew revenue by 67% to 20.4 billion yen, bolstered by ABEMA’s premium subscriber base exceeding 921,000 users and an elevenfold increase in WINTICKET transaction volume.
- The Game business experienced a 15% revenue decline to 29.9 billion yen and a 77.8% drop in operating profit, attributed to seasonal factors and increased marketing spend.
- To drive future earnings recovery, the company is focusing on high-quality content launches, specifically Uma Musume Pretty Derby and NieR Re[in]carnation.
- Management restructured ABEMA into separate Free and Premium business units to better capitalize on current growth momentum.
+1
CyberAgentJan 2021
Financial9 pages
FY2021 First Quarter Consolidated Financial Results [Japanese GAAP]
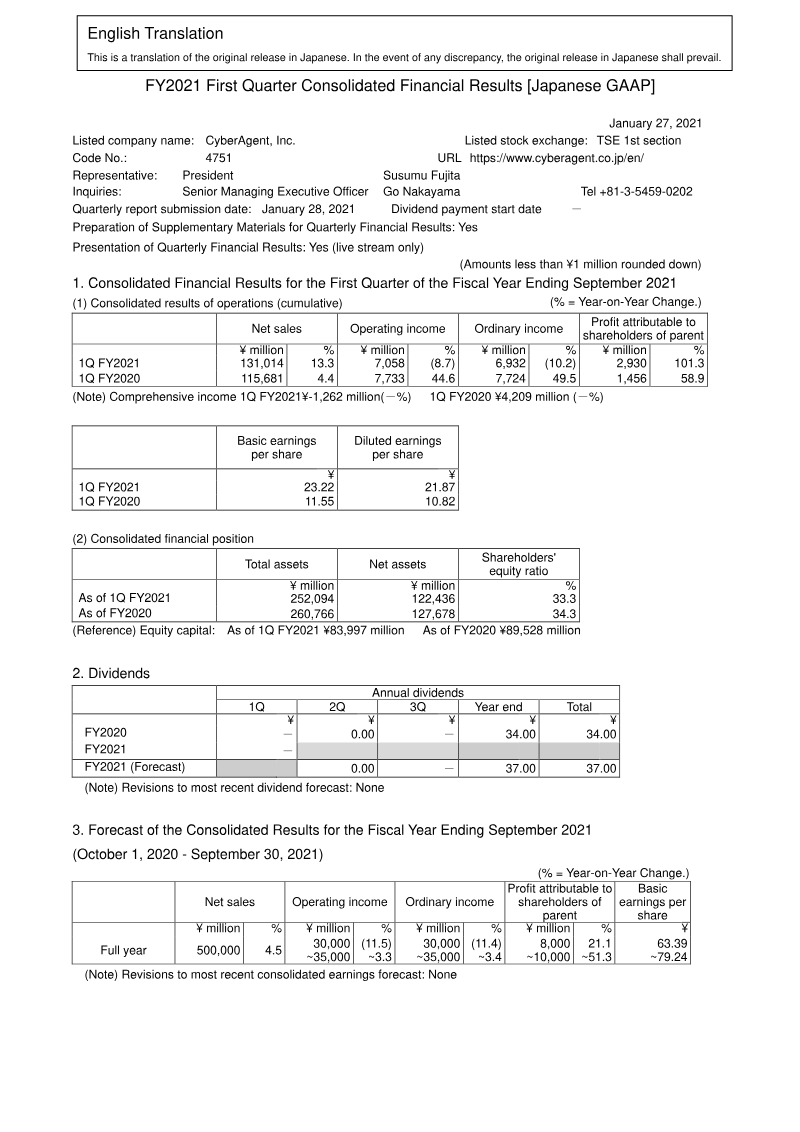
CyberAgent’s consolidated financial results for the first quarter of the fiscal year ending September 2021 reveal a period of significant revenue growth alongside shifting profitability across its diverse business segments. Covering the period from October 1, 2020, to December 31, 2020, the data shows net sales increased by 13.3% year-on-year to ¥131,014 million. While operating income saw a moderate decline of 8.7% to ¥7,058 million, profit attributable to shareholders of the parent surged by 101.3% to ¥2,930 million.
The Media Business, which includes the ABEMA streaming platform, reported a substantial 67% increase in net sales to ¥20,428 million. Although this segment remains in an investment phase, its operating loss narrowed from ¥5,050 million to ¥3,926 million. The Internet Advertisement Business achieved record-high net sales of ¥76,587 million, up 13.8%, maintaining its position as the primary revenue driver. Conversely, the Game Business experienced a downturn, with net sales falling 15% to ¥29,954 million and operating income dropping 77.8% to ¥1,137 million, attributed to seasonal factors affecting major existing titles. The Investment Development Business provided a significant boost, with operating income rising 74% to ¥4,636 million.
The financial position remains stable despite a slight decrease in total assets to ¥252,094 million, primarily due to corporate tax and dividend payments. CyberAgent maintained its full-year forecast, projecting net sales of ¥500,000 million and operating income between ¥30,000 million and ¥35,000 million. These results, prepared under Japanese GAAP, reflect the company's strategic focus on scaling its media and advertising operations to offset fluctuations in the hit-driven gaming market during the ongoing global pandemic.
- CyberAgent reported a 13.3% year-on-year increase in net sales to ¥131,014 million for Q1 FY2021, while profit attributable to shareholders surged 101.3% to ¥2,930 million.
- The Internet Advertisement Business remains the primary revenue driver, achieving record-high net sales of ¥76,587 million, a 13.8% increase compared to the previous year.
- The Media Business, including the ABEMA platform, saw a 67% revenue jump to ¥20,428 million while successfully narrowing its operating loss from ¥5,050 million to ¥3,926 million.
- The Game Business experienced a significant downturn, with net sales falling 15% to ¥29,954 million and operating income dropping 77.8% to ¥1,137 million due to seasonal factors affecting major titles.
- The Investment Development Business provided a strong financial boost, recording a 74% increase in operating income to ¥4,636 million.
+1
CyberAgentJan 2021
Presentation54 pages
FY2020 Presentation Material
CyberAgent achieved record-high financial performance in fiscal year 2020, reporting consolidated sales of 478.5 billion yen and an operating profit of 33.8 billion yen. These results represent year-over-year increases of 5.5% and 9.9% respectively, surpassing initial forecasts despite the operational challenges posed by the global pandemic. Growth was primarily catalyzed by the Game business, which generated 155.8 billion yen in sales. This segment benefited from the sustained performance of legacy titles and the successful launch of Project SEKAI, which acquired over two million users within its first three weeks.
The Media business, centered on the ABEMA streaming platform, remains a critical pillar for long-term expansion. ABEMA experienced a 22.6% increase in annual sales to 57 billion yen, supported by a cumulative download base exceeding 59 million. While the segment continues to operate at a loss of 18.5 billion yen due to aggressive up-front investments, these losses are narrowing as new monetization streams mature. Specifically, the rapid adoption of Pay-Per-View services and a seventeen-fold increase in transaction volume for the WINTICKET cycling betting service have diversified the platform's revenue model beyond traditional advertising.
Looking toward fiscal year 2021, the strategic focus shifts toward scaling consolidated sales to 500 billion yen while maintaining a robust financial position. To manage this growth, a new governance structure has been implemented to separate management oversight from execution. Although increased selling, general, and administrative expenses led to a quarterly dip in operating profit during the final months of 2020, the overall trajectory remains positive. The combination of a highly profitable gaming portfolio and the accelerating monetization of digital media assets positions the organization for sustained domestic leadership in the Japanese internet services market.
- CyberAgent achieved record FY2020 performance with 478.5 billion yen in sales and 33.8 billion yen in operating profit, marking year-over-year growth of 5.5% and 9.9% respectively.
- The Game business served as the primary growth engine, generating 155.8 billion yen in sales driven by legacy titles and the successful launch of Project SEKAI, which reached two million users in three weeks.
- The Media segment, anchored by ABEMA, grew annual sales by 22.6% to 57 billion yen, supported by a cumulative base of over 59 million downloads.
- Despite an 18.5 billion yen operating loss in the Media segment due to aggressive investment, monetization is diversifying through Pay-Per-View services and a seventeen-fold increase in transaction volume for the WINTICKET cycling betting service.
- CyberAgent has set a consolidated sales target of 500 billion yen for FY2021 and implemented a new governance structure to separate management oversight from operational execution.
+1
CyberAgentOct 2020
Financial19 pages
FY2020 Consolidated Financial Results [Japanese GAAP]
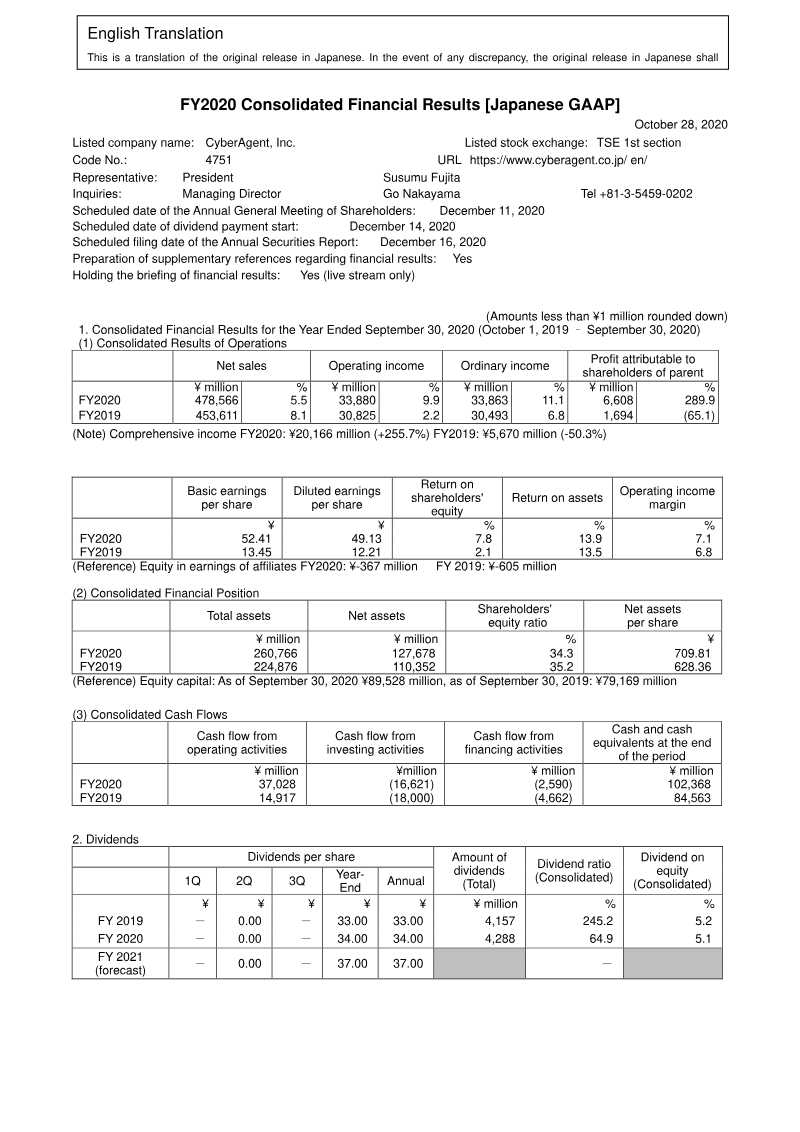
CyberAgent achieved significant financial growth during the 2020 fiscal year, reporting net sales of ¥478.6 billion, a 5.5% increase over the previous year. The most notable performance metric was the surge in profit attributable to shareholders, which rose by 289.9% to reach ¥6.6 billion. This growth was underpinned by a robust financial position, with total assets expanding to ¥260.8 billion and a year-end cash balance of ¥102.4 billion, supported by ¥37 billion in cash flow from operating activities.
The Game Business served as the primary engine for profitability, generating ¥30.3 billion in operating income through a mix of established smartphone titles and successful new releases. While the Media Business saw a 22.6% increase in sales, it continued to record an operating loss of ¥18.3 billion due to sustained strategic investments in the ABEMA streaming platform. The Internet Advertisement and Investment Development segments rounded out the core operations, contributing to a diversified revenue stream that capitalized on the expanding smartphone market.
Looking toward the 2021 fiscal year, the company forecasts continued revenue expansion to ¥500 billion. Management intends to maintain its focus on the smartphone sector while treating ABEMA as a long-term strategic pillar for future growth. Although sales are expected to rise, operating income forecasts remain flexible, ranging from a slight decrease to a modest increase as the company balances immediate profitability from its gaming and advertising divisions against the high capital requirements of its media investments. Overall, the transition from FY2019 to FY2020 marked a substantial strengthening of per-share metrics, with basic earnings per share climbing from ¥13.45 to ¥52.41.
- CyberAgent reported FY2020 net sales of ¥478.6 billion, a 5.5% year-over-year increase, while profit attributable to shareholders surged 289.9% to ¥6.6 billion.
- The Game Business served as the primary profit driver, generating ¥30.3 billion in operating income through a combination of established smartphone titles and new releases.
- The Media Business recorded an operating loss of ¥18.3 billion due to sustained strategic investment in the ABEMA streaming platform, despite a 22.6% increase in segment sales.
- Basic earnings per share saw significant growth, rising from ¥13.45 in FY2019 to ¥52.41 in FY2020.
- The company ended the fiscal year with a strong financial position, reporting total assets of ¥260.8 billion and a cash balance of ¥102.4 billion.
CyberAgentOct 2020
Presentation40 pages
3Q FY2020 Presentation Material
CyberAgent’s performance during the third quarter of fiscal year 2020 remained resilient despite the economic disruptions caused by the COVID-19 pandemic. Consolidated sales reached 112.8 billion yen, a marginal year-over-year decrease of 0.7%, while operating profit stood at 8.2 billion yen. By the end of this period, the company had already achieved between 89% and 102% of its full-year operating profit forecasts. This stability was largely driven by the Internet Advertisement segment, which successfully offset declining demand in certain sectors by pivoting toward advertisers benefiting from stay-at-home trends, and the Game business, which generated 36.7 billion yen in quarterly revenue following major title anniversaries.
The media segment, centered on the streaming platform ABEMA, demonstrated significant growth with a 19.2% year-over-year increase in sales to 13.3 billion yen. This expansion was supported by a record 56 million downloads and a surge in the WINTICKET gambling transaction business, which doubled its volume to 7.2 billion yen. Strategic priorities for this segment include reaching one million ABEMA Premium subscribers by late 2020 and leveraging new virtual production technologies, such as Pay-Per-View systems, to enhance monetization.
Looking forward, the corporate strategy focuses on establishing ABEMA as a long-term financial pillar while maintaining market share in the advertising sector through AI-driven efficiency. In the gaming division, the emphasis remains on the dual approach of developing new intellectual properties and extending the lifecycle of existing titles through robust operational management. These efforts are underpinned by a broader commitment to ESG initiatives and information security, ensuring sustainable value creation across the company’s diverse digital portfolio.
- CyberAgent reported 112.8 billion yen in consolidated sales for 3Q FY2020, achieving 89% to 102% of its full-year operating profit forecast despite a marginal 0.7% year-over-year revenue decline.
- The Game business generated 36.7 billion yen in quarterly revenue, bolstered by major title anniversaries and a strategy focused on both new IP development and lifecycle extension for existing games.
- The media segment, anchored by the ABEMA streaming platform, grew sales by 19.2% year-over-year to 13.3 billion yen, supported by 56 million total downloads.
- WINTICKET gambling transactions doubled in volume to 7.2 billion yen, contributing significantly to the media segment's growth.
- The Internet Advertisement segment maintained stability by pivoting toward advertisers benefiting from stay-at-home trends to offset sector-specific demand declines.
+1
CyberAgentJul 2020

Financial9 pages
FY2020 Third Quarter Consolidated Financial Results [Japanese GAAP]
CyberAgent’s consolidated financial results for the third quarter of fiscal year 2020, covering the nine-month period ending June 30, 2020, indicate steady growth across most business segments despite global economic uncertainties. Net sales increased 4.6% year-on-year to ¥357.7 billion, while operating income rose 21.9% to ¥28.5 billion. Most notably, profit attributable to shareholders of the parent surged 230.9% to ¥5.88 billion, a significant recovery compared to the prior year's performance.
The Game Business and Internet Advertisement Business served as the primary drivers of profitability. The Game Business, which includes subsidiaries such as Cygames and Craft Egg, reported a 21.6% increase in operating income to ¥23.1 billion, bolstered by the continued strength of major existing titles. The Internet Advertisement Business grew its operating income by 16.4% to ¥17.1 billion by successfully capturing demand from advertisers benefiting from stay-at-home consumer trends. Conversely, the Media Business, centered on the ABEMA streaming platform, reported an operating loss of ¥13.3 billion as the company continues to prioritize long-term investment in the service.
The consolidated financial position remains stable, with total assets increasing to ¥235.9 billion, primarily due to higher cash and deposits. The equity capital ratio stood at 35.7% as of June 30, 2020. Looking ahead, the full-year forecast for the period ending September 30, 2020, remains unchanged from previous projections, with net sales expected to reach ¥465 billion and operating income estimated between ¥28 billion and ¥32 billion. These results reflect a strategic focus on the expanding smartphone and video advertising markets in Japan.
- CyberAgent reported a 230.9% surge in profit attributable to shareholders, reaching ¥5.88 billion for the nine-month period ending June 30, 2020.
- Consolidated net sales grew 4.6% year-on-year to ¥357.7 billion, while operating income increased 21.9% to ¥28.5 billion.
- The Game Business, featuring subsidiaries like Cygames and Craft Egg, drove profitability with a 21.6% rise in operating income to ¥23.1 billion.
- The Internet Advertisement Business grew operating income by 16.4% to ¥17.1 billion, benefiting from increased demand during stay-at-home trends.
- The Media Business, anchored by the ABEMA streaming platform, recorded an operating loss of ¥13.3 billion as the company maintains its long-term investment strategy.
CyberAgentJul 2020