Investment reports and market data
Documents


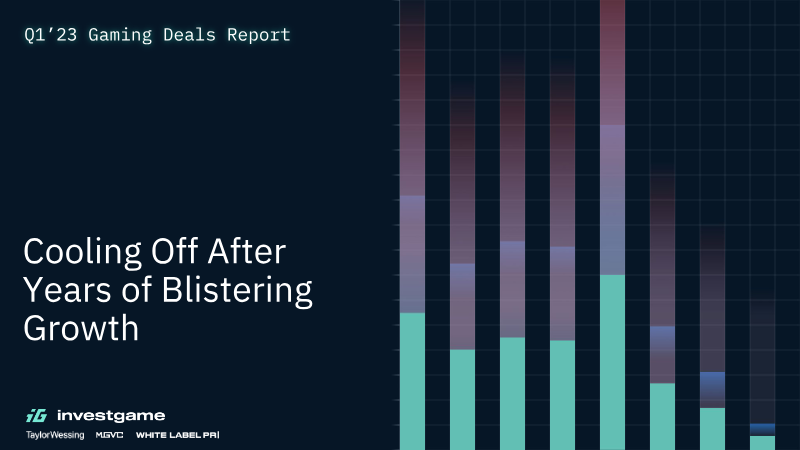
Q1 2023 Gaming Deals Report: Cooling Off After Years of Blistering Growth
The gaming industry experienced a significant cooling period in the first quarter of 2023, characterized by a sharp decline in deal activity across private investments, mergers and acquisitions (M&A), and public offerings.
- Q1 2023 marked a significant industry-wide cooling period, characterized by a sharp decline in private investments, M&A activity, and public offerings compared to previous years of rapid growth.
- M&A activity hit a low point in Q1 2023, recording approximately half the volume seen in previous years.
- Late-stage funding has stalled significantly, with only two closed transactions recorded throughout the entire first quarter.


Aktualizacja Strategii Nowe Otwarcie 2023
The strategy overview presents PCF Group S.A. as a leading Polish producer of AAA-level shooter games built on Unreal Engine, emphasizing its extensive experience, proprietary technology, and international development network.
- PCF Group targets a revenue multiplier for 2023–2027 comparable to the 4.9-fold growth seen between 2018 and 2022, when cumulative revenue reached 608 million złoty.
- The company is shifting to a self-publishing model to support the launch of four core AAA projects and three supplementary titles, including two VR games scheduled for 2025–2026.
- Strategic monetization will pivot toward a 'games-as-a-service' model, incorporating micro-transactions and seasonal passes to scale independent AAA publishing.
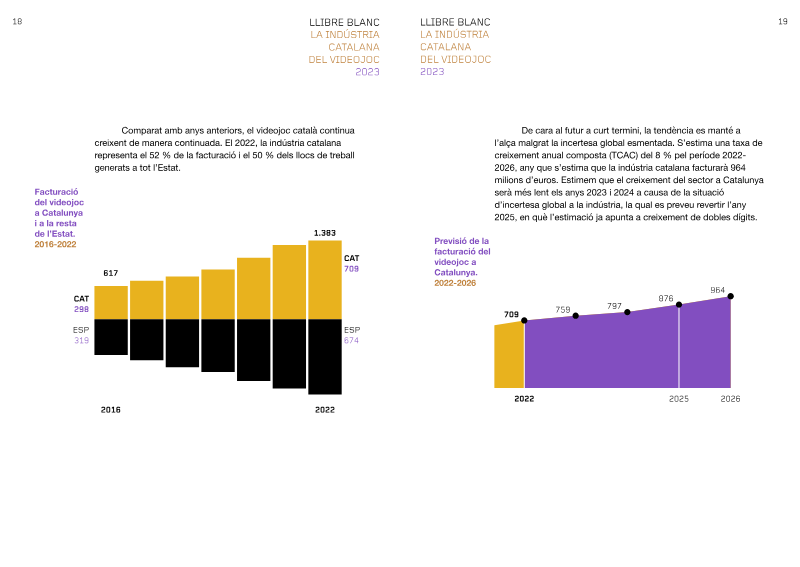
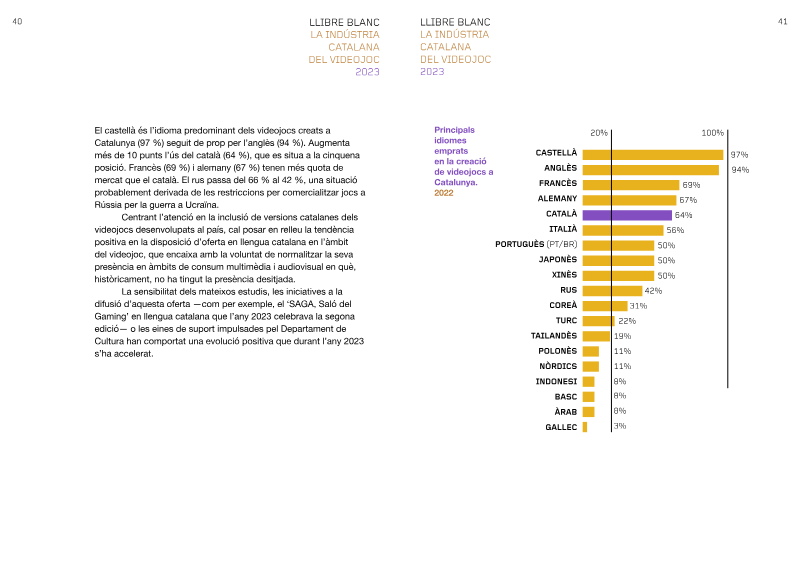
White Paper Catalan Video Game Industry 2023
The 2023 white paper on Catalonia’s video-game industry presents a detailed assessment of the sector’s economic performance and labour dynamics for the year 2022.
- Catalonia’s video game industry generated €709 million in revenue during 2022, representing a 7.5 percent decline from the previous year.
- Total employment in the sector grew by 8.7 percent in 2022, reaching a workforce of 4,619 people.
- The simultaneous decrease in revenue and increase in headcount indicates a strategic shift toward more labor-intensive development and ancillary service activities.
Australian Game Development Survey FY2023 Industry Snapshot
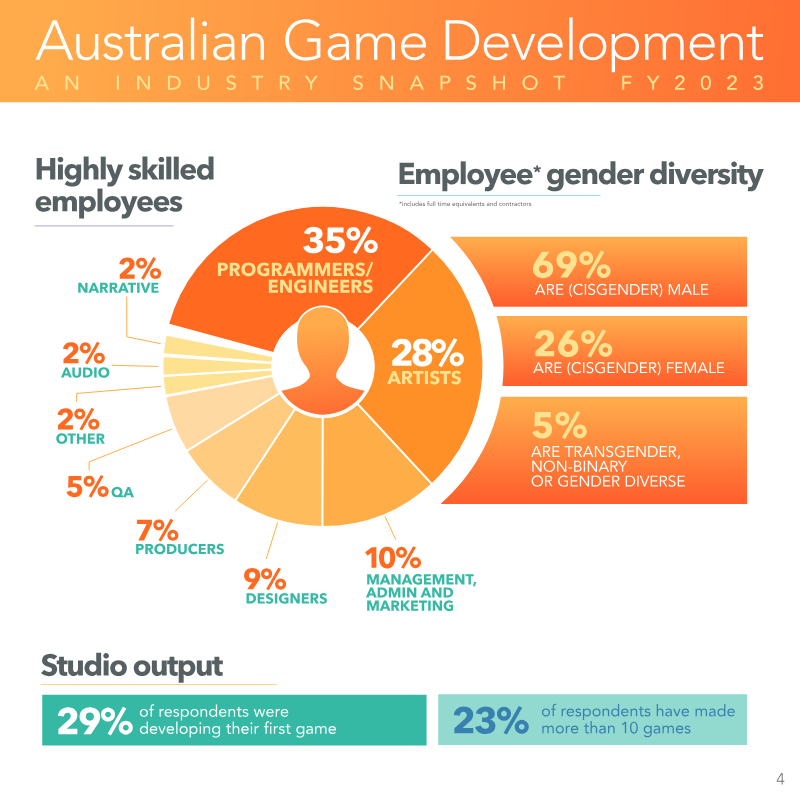
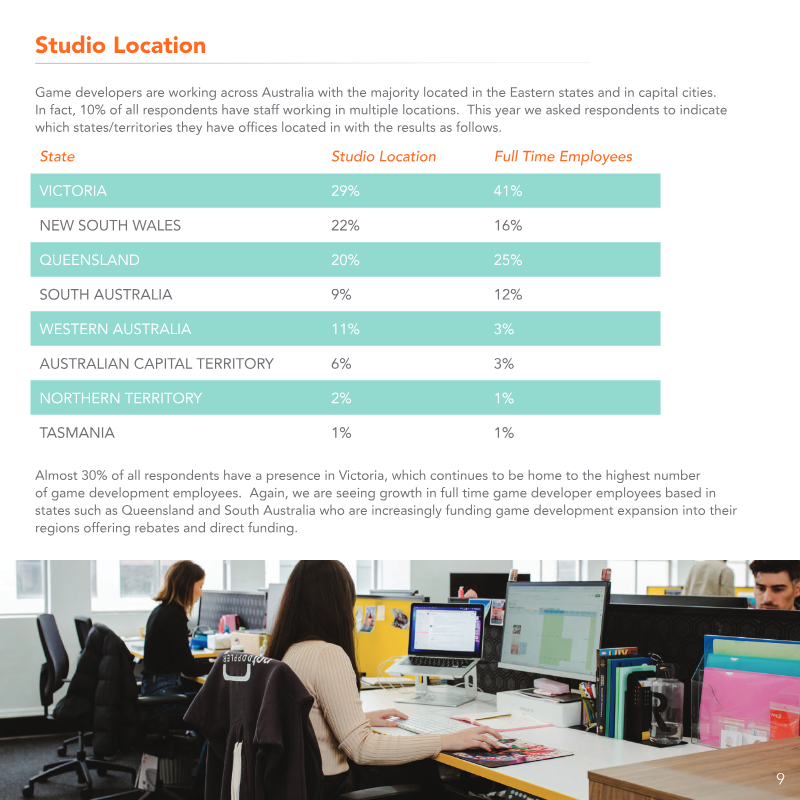
The Australian Game Development Survey: FY2023 Industry Snapshot reveals a sector experiencing significant maturation and financial expansion.
- The Australian game development industry generated $345.5 million in revenue during FY2023, representing a 21% year-over-year increase.
- The workforce grew by 17% to 2,458 full-time equivalent employees, with 63% of studios planning further hiring in the coming year.
- The sector is highly export-dependent, with 87% of total revenue derived from international markets.
New World for Gaming Startups in 2023 | Jason Chapman, Konvoy Ventures & Josh Lu, a16z
The gaming startup landscape in 2023 is defined by a significant contraction in late-stage financing, with Series B and C deal activity plummeting by 47% and 67% respectively.
- Late-stage gaming financing has contracted significantly, with Series B deal activity dropping by 47% and Series C activity falling by 67%.
- Startup valuations have undergone a major correction of 40% to 55%, forcing founders to prioritize capital efficiency and extend financial runways into 2025.
- Investors are shifting toward a 'flight to quality' strategy, favoring teams with deep expertise and metric-driven product development over speculative ventures.
2022 Gaming Deals Review & Naavik’s Highlights Awards - The Metacast by Naavik
The global gaming industry faced a period of significant contraction throughout 2022, characterized by a marked decline in both deal volume and total investment value.
- The global gaming industry experienced a significant contraction in 2022, marked by a decline in both total investment value and deal volume driven by macroeconomic instability and rising interest rates.
- Regulatory scrutiny intensified in 2022, highlighted by the Federal Trade Commission’s record-setting settlement with Epic Games regarding privacy and monetization practices.
- Despite the downturn, venture capital firms hold substantial dry powder, which is expected to support ongoing M&A activity and private investment throughout 2023.
End-of-Year Learnings & 2023 Industry Predictions - The Metacast by Naavik
The global gaming industry is currently undergoing a significant structural correction, transitioning from a period of unsustainable pandemic-era expansion toward a more disciplined, efficiency-focused operational model.
- The global gaming industry is shifting from pandemic-era expansion to a disciplined operational model, prioritizing sustainable business practices and efficiency over growth-at-all-costs strategies.
- The 2023 console market is expected to rebound strongly as semiconductor supply chain constraints resolve and a dense calendar of high-profile AAA titles launches.
- The mobile gaming sector faces ongoing revenue declines and rising user acquisition costs, exacerbated by privacy-related tracking limitations that force developers to seek new audience reach strategies.
What is China’s Console Market Landscape and Growth Potential? - The Metacast by Naavik
The global gaming landscape is currently defined by a shift toward experiential genres like cozy games and a narrowing fidelity gap between mobile and console hardware.
- The console market in mainland China remains a marginal segment, accounting for only 4% of total game sales with no significant growth expected in the near term.
- Entry into the official Chinese console market is high-risk due to a legacy of console bans, stringent government content regulations, and lengthy licensing processes.
- Developers targeting Chinese audiences are advised to bypass official regulatory barriers by utilizing cross-platform strategies or leveraging the gray market and Steam.
Censimento Game Developer Italiani 2021
The Italian video game industry has entered a phase of significant maturation, characterized by a robust ecosystem of approximately 160 companies and over 1,600 professionals.
- The Italian game industry is highly export-oriented, with 94% of business-to-consumer revenue generated outside of Italy.
- The domestic market reached €2.179 billion in revenue in 2020, marking a 21.9% increase driven by digital sales and a player base of 16.7 million people.
- The sector comprises approximately 160 companies and over 1,600 professionals, with nearly 75% of studios having operated for more than four years.
Earnings Analysis: Nintendo, Krafton, Unity, AppLovin & Roblox - The Metacast by Naavik
The global gaming industry is currently navigating a significant market correction, characterized by a 4% year-over-year revenue decline as forecasted by Newzoo.
- Unity is prioritizing profitability over revenue growth to combat market pressure, following a 50% stock surge driven by hopes for improved execution and the integration of ironSource.
- Roblox reported higher-than-expected losses in Q3 due to increased operating costs, specifically the hiring of approximately 600 new employees over the past year.
- Krafton faces significant revenue headwinds due to the ban of Battlegrounds Mobile India and a reliance on the Chinese market, which accounted for 55% of its H1 2022 revenue.
How Mobile Gaming Headwinds Affected Take-Two and EA - The Metacast by Naavik
The global gaming industry is currently undergoing a significant structural correction, transitioning from the unsustainable growth of the pandemic era toward a period defined by fiscal discipline and profitability.
- Take-Two Interactive's stock price has fallen to five-year lows, reflecting market skepticism following their acquisition of Zynga and a downward revision of full-year revenue projections by $200 million to $300 million.
- Mobile gaming revenue in China experienced a significant decline of over 20% in Q3, contributing to a broader global downturn in the mobile sector.
- Electronic Arts remains financially robust compared to its peers, leveraging strong performance from EA Sports titles like FIFA 23—which saw a 10% unit sales increase—to fund dividends and share repurchases.
Kress's Corner #2 How do gaming venture capitalists really work?
Venture capital in the gaming sector is currently undergoing a strategic shift, moving away from the speculative content-heavy investments of the 2020–2021 bubble toward more sustainable infrastructure and middleware solutions.
- Gaming venture capital is shifting away from speculative game studio investments toward B2B infrastructure and middleware solutions to build more defensible, sustainable market moats.
- Investment strategies are currently prioritizing strict valuation ratios and high-quality operators over the trend-chasing behavior that characterized the 2020–2021 market bubble.
- Venture firms operate on a 7-to-10-year fund lifecycle, focusing on rigorous deal filtering and 'smart capital' partnerships that provide founders with strategic guidance rather than just liquidity.