Showing 30 of 654 results · 1.06s
Return to Growth for Q3 2021-22: Confirmation of 2021/22 & 2022/23 Targets
Nacon
segments, including mobile and audio sales, contracted by 14.4 % to €2.0 million. Cumulative sales for the first nine months fell 8.2 % to €124.2 million, with games down
Report2 pages
Jan 2023
Libro Blanco de Accesibilidad para Desarrolladores
AEVI
mobile) and supplies developers with a practical reference for implementing auditory, visual, motor and cognitive options. Globally, roughly three billion people play video games, of whom about four
Report106 pages
Jun 2024
Q2'24 Gaming Deals Report: Gradual Recovery
InvestGame
business partners, and market insights, focusing specifically on video game publishers and developers while excluding gambling and non-gaming blockchain entities. Investment activity in Q2 2024 was characterized
Report19 pages
Nov 2022
Analyzing the Consumer and Market Impacts of Chinese Games Market Policies
Newzoo
mobile, PC, and console versions, streamlining the path to market. Despite these restrictions, a robust grey market persists. Players frequently utilize virtual private networks (VPNs) and game accelerators
Report29 pages
Jan 2020
Baromètre Annuel du Jeu Vidéo en France: 2020
Syndicat National du Jeu Vidéo
platforms, though mobile and console markets remain vital. Financially, the sector relies heavily on self-financing, supplemented by public support mechanisms such as the Video Game Tax Credit
Report19 pages
Jan 2024
Newzoo PC & Console Gaming Report 2024
Newzoo
cloud gaming is identified as a key entry point due to high awareness (32 %) and low hardware barriers. Expanding beyond a single platform—especially into mobile or cloud
Report46 pages
Jan 2018
Baromètre Annuel du Jeu Vidéo en France Edition 2018
Syndicat National du Jeu Vidéo
games in development during 2018, two-thirds of which represent new intellectual properties. Studios show a clear preference for PC development, followed by mobile and console platforms. Financially
Report17 pages
Jan 2020
State of the Game Industry 2020
Game Developers Conference
global game development landscape in 2020 is characterized by a transition toward next-generation hardware and a diversifying array of digital storefronts. While PC and mobile remain
Report33 pages
Jan 2021
Gaming Deals Activity Report Q1-Q3’2021
InvestGame
individual game titles. Geographically, the report highlights the continued dominance of strategic investors like Tencent, which closed 69 deals during the period, focusing heavily on the mobile segment
Report21 pages
Jan 2025
German Games Industry: 2025
game – Verband der deutschen Games-Branche e. V.
games industry navigated a period of significant contraction in 2024, with total market revenue falling 6% to €9.4 billion. This downturn, driven by a decline in mobile revenue
Report39 pages
Jan 2023
The MENA Games Market: From Sand to Stardom
Niko Partners
mobile-first ecosystem and a burgeoning esports sector that benefits from high engagement rates and substantial public sector backing, most notably through Saudi Arabia’s National Gaming
Report25 pages
Jan 2022
Modern Mobile Consumer 2022: App Monetization Report
ironSource
mobile consumers interact with app monetization, revealing that rewarded ads and in‑app purchases (IAP) coexist without cannibalizing revenue. Surveying 30,457 participants—18,894 from gaming apps
Report12 pages
Jan 2024
Landscape Shifts in IP Gaming: An Analysis of How the Competitive Landscape of IP in Gaming Has Shifted in 2023
Sensor Tower
While video game and anime IPs continue to command the largest market share—particularly in Asia where they account for 70% of downloads—board game IPs experienced
Report38 pages
Apr 2026
State of Mobile 2026
Sensor Tower
State of Mobile report demonstrates that the global mobile ecosystem remains mature yet increasingly monetized, with 2025 in‑app purchase (IAP) revenue reaching $85.6 billion—a 21 % year
Report97 pages
Winning Audiences Through YouTube Gaming
Stream Hatchet
game on the platform, while esports remained a critical pillar, contributing 1.2 billion hours of viewership, led by major titles such as League of Legends and Mobile Legends
Report13 pages
Jan 2024
Save Point 2024: Recapping the Year's Biggest Trends in Live Streaming
Stream Hatchet
mobile esports solidified its status as a global powerhouse, particularly during the Esports World Cup. Simultaneously, the industry benefited from a strong synergy between transmedia adaptations and gaming
Report54 pages
Jan 2025
Mobile App Trends 2025: Japan Edition
Adjust
mobile app market, characterized by a resilient consumer spend of $16.5 billion in 2024 and a 7% year-over-year increase in total installs. While the gaming sector
Report49 pages
Q3 2020/21 Sales: 48.7 M€, + 20.3%
Nacon
Game sales fell 19.7 % to €13.8 million, with only two new releases (Monster Truck® and Handball 21) and a digital sales share of 74.4 %. Other revenue, mainly mobile
Report2 pages
Jan 2026
The State of Video Gaming in 2025
Epyllion
analysis demonstrates that global video‑gaming spend has surged to roughly $200 B in 2025, a 150 % rise since 2011, yet real‑term growth has stalled and margins
Report231 pages
The 2025 Benchmark Report: Roblox Platform Trends
InvestGame
significantly higher monetization; the top 5 % of games generate over $20 per day from a single player. In contrast, games with median sessions under six minutes exhibit negligible
Report31 pages
Jan 2024
Mobile App Trends: 2024 Edition
data.ai, Adjust
casual genre. Although overall gaming sessions dipped, specific subverticals like racing and simulation saw dramatic install spikes of 61% and 53%, respectively. Global gaming stickiness remained stable
Report48 pages
Jan 2025
Unlocking Games Revenue: Player Behavior and Payment Trends in the West
Newzoo
Unlocking Games Revenue: Player Behavior and Payment Trends in the West examines the evolving monetization landscape across North America and Europe. Produced through a partnership between Newzoo
Report27 pages
Mar 2024
2023 Roblox Report: Behind the Data
GameAnalytics
Roblox platform. The study is based on 2023 data from thousands of games that utilize the GameAnalytics SDK, representing over 50% of total player engagement on the platform
Report21 pages
Jan 2022
Japan Mobile App Trends 2022
Adjust
Japanese mobile app market experienced a period of significant expansion between 2020 and 2022, characterized by a 19% surge in total installs and a dominant 52% growth rate
Report34 pages
Jan 2022
Türkiye Game Market 2022 Report
Riot Games
mobile development and esports. The primary thesis of the market’s evolution is a strategic pivot away from the rapid, volume-based "gold rush" of hyper-casual gaming
Report230 pages
Video Games as a Tool for Mental Resilience: Italy
IIDEA – Italian Interactive Digital Entertainment Association
substantial majority of Italian players utilize gaming to mitigate negative psychological states. Specifically, 71% of participants report that gaming helps reduce stress, while 60% use it to manage
Report1 pages
Jan 2023
The Xsolla Report: The State of Play
Xsolla
global gaming market is undergoing a structural transformation driven by multiplatform integration and the rapid evolution of financial technologies, with total revenues projected to reach $211.2 billion
Report51 pages
Mar 2026
Cyprus Game Industry: Senior+ Employment Landscape 2025
Values Value, InGame Job
study examines the senior‑level employment landscape in Cyprus’s game industry for 2025, drawing on an anonymous survey of 113 professionals and a comparative analysis with European
Report19 pages
Jan 2025
The Mobile App Growth Report: 2025 Edition
Adjust
Gaming continues to be the dominant vertical worldwide, particularly within the hyper-casual and hybrid-casual subgenres. This sector is especially potent in emerging markets; India’s gaming
Report34 pages
Sep 2025
Square Enix Special Feature: Erdrick Trilogy Reimagined
Square Enix
across diverse geographic markets. This strategy is complemented by a robust pipeline of mobile and niche titles, including Dragon Quest Tact and various entries in the Bravely Default
Report2 pages
Return to Growth for Q3 2021-22: Confirmation of 2021/22 & 2022/23 Targets
2 pages1k words
Summary
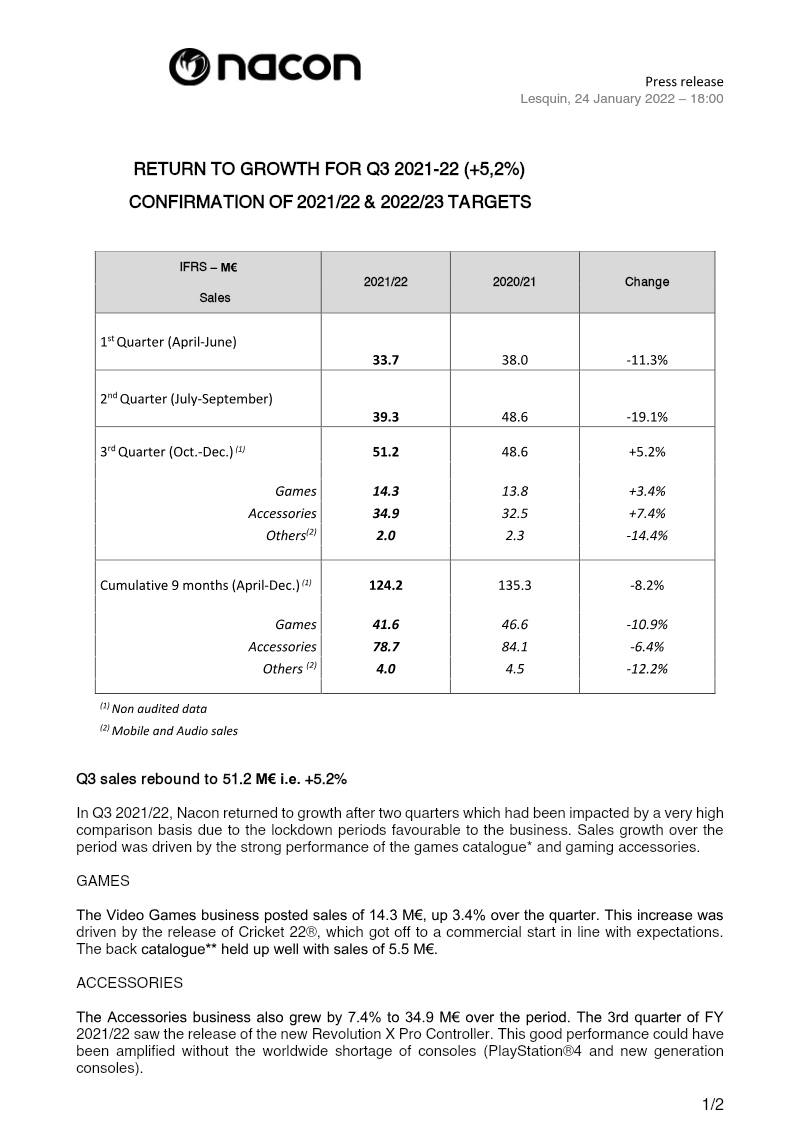
Nacon reported a rebound in Q3 2021/22, with sales rising 5.2 % to €51.2 million after two quarters of decline driven by a high comparison base from lockdown‑related demand spikes. The growth was led by the games catalogue, which generated €14.3 million (+3.4 %) and a strong back‑catalogue contribution of €5.5 million, while accessories grew 7.4 % to €34.9 million thanks to the launch of the Revolution X Pro Controller, though global console shortages limited further upside. Other segments, including mobile and audio sales, contracted by 14.4 % to €2.0 million.
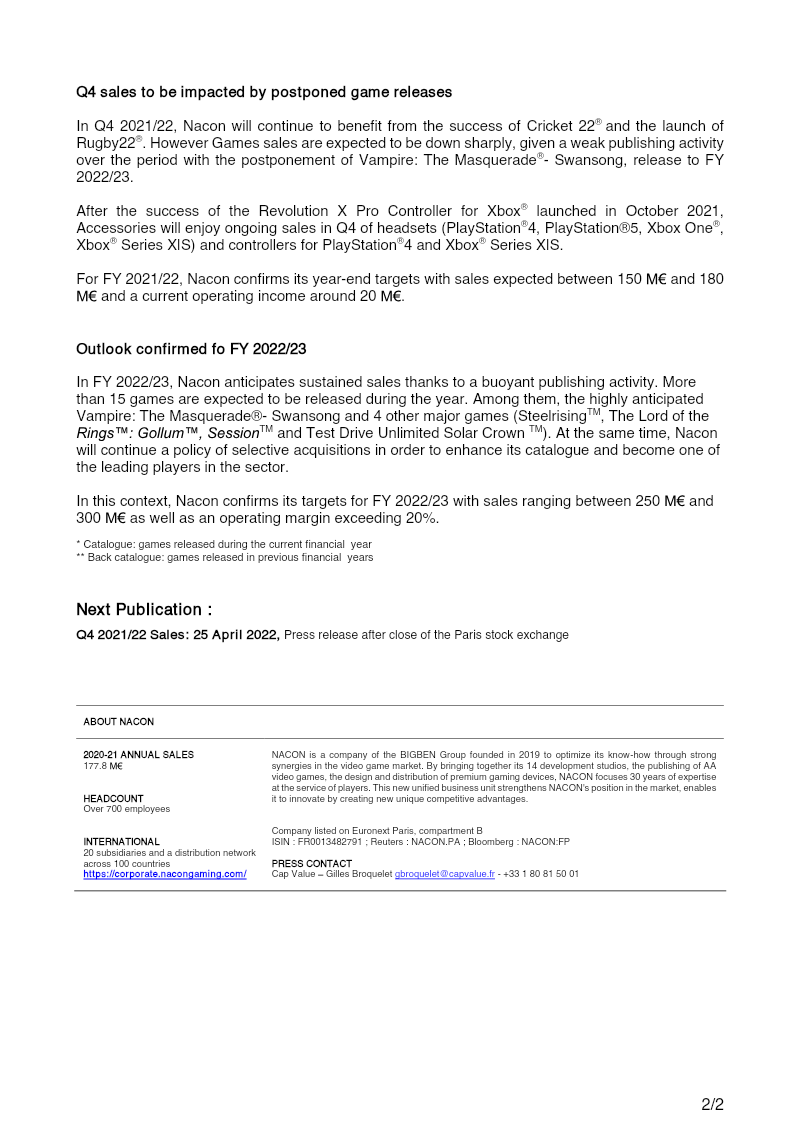
Cumulative sales for the first nine months fell 8.2 % to €124.2 million, with games down 10.9 % and accessories down 6.4 %. Nacon confirmed its FY 2021/22 targets of €150–180 million in sales and an operating income near €20 million. For FY 2022/23, the company projects a robust publishing pipeline of over 15 titles—including high‑profile releases such as Vampire: The Masquerade® – Swansong—and anticipates sales of €250–300 million with an operating margin above 20 %. The strategy includes selective acquisitions to strengthen the catalogue and position Nacon as a leading player in the global video‑game market. The outlook is based on continued demand for both new releases and established titles, with accessories sales expected to benefit from ongoing headset and controller launches across major console platforms.
Pages
Insights
- Nacon projects significant growth for FY 2022/23, targeting sales of €250–300 million and an operating margin exceeding 20%.
- Q3 2021/22 sales rebounded by 5.2% to €51.2 million, ending two consecutive quarters of decline.
- The company confirmed its FY 2021/22 targets of €150–180 million in sales and an operating income near €20 million, despite a 8.2% decline in cumulative nine-month sales to €124.2 million.
- Accessories growth of 7.4% to €34.9 million was driven by the Revolution X Pro Controller launch, though performance was constrained by global console shortages.
- The games catalogue contributed €14.3 million in Q3, supported by a strong back-catalogue performance of €5.5 million.