Report44 pages
Annual Report 2024
Thunderful Group’s 2024 Annual Report documents a decisive pivot toward a pure gaming focus, achieved through divestment of non‑gaming assets and a 20 % workforce reduction. The restructuring tightened the balance sheet, halving interest‑bearing net debt and leaving a modest cash position of SEK 29.6 million, yet it also produced a sharp decline in operating performance: net revenue fell 23.8 % to SEK 292.8 million and adjusted EBITA swung to a loss of SEK 383.9 million, largely due to cost‑cutting and the transition to higher‑margin publishing and co‑development activities.
The global gaming market grew modestly in 2024, reaching USD 187.7 billion with a 5 % rise in the player base to 1.5 billion, projected to reach 1.67 billion by 2027. Thunderful’s strategy targets a 3.1 % CAGR in the PC segment, high‑quality titles priced USD 10–30, and external project investments capped at EUR 2 million. The company has reorganised into Publishing and Co‑development & Services segments to optimise resource allocation, lower fixed costs through third‑party publishing, and balance riskier internal IP development with predictable service revenue.
Governance remains robust: a board‑led risk framework, annual review of a Zero‑tolerance Code of Conduct, and an anonymous whistleblowing function reinforce ethical standards. Executive remuneration is tightly linked to long‑term value, with fixed salaries capped at 30 % variable pay and share‑based incentives that could dilute equity by up to 4.65 % if fully exercised. Despite a net loss of SEK 887.5 million in 2024, the Group’s operating profit rose 57 % to SEK 292.8 million, signalling a turnaround post‑restructuring.
Financially, the Group’s liquidity is constrained; total assets fell from SEK 3.15 billion to SEK 772.9 million, and net cash turned negative. Impairments of over SEK 444 million on goodwill and other intangibles, coupled with significant restructuring costs, underpin the negative operating margin of –46.9 %. The company’s exposure to foreign‑exchange, interest‑rate and liquidity risks remains moderate but requires ongoing monitoring. Overall, the report presents a company in transition, balancing aggressive cost discipline and strategic realignment against a challenging financial backdrop.
- Thunderful Group reported a net loss of SEK 887.5 million in 2024, driven by SEK 444 million in asset impairments and significant restructuring costs that resulted in an operating margin of -46.9%.
- The company executed a major strategic pivot toward a pure gaming focus, involving a 20% workforce reduction and the divestment of non-gaming assets to halve interest-bearing net debt.
- Net revenue declined 23.8% to SEK 292.8 million, while adjusted EBITA fell to a loss of SEK 383.9 million as the firm transitioned toward higher-margin publishing and co-development models.
- Thunderful has reorganized into two core segments—Publishing and Co-development & Services—to balance high-risk internal IP development with predictable service revenue and lower fixed costs.
- The company’s financial position remains constrained, with total assets dropping from SEK 3.15 billion to SEK 772.9 million and a modest cash position of SEK 29.6 million.
+1
ThunderfulJan 2024
Report30 pages
Gaming Industry Report: Q4 2023
The global gaming industry reached a market valuation of $184 billion in 2023, representing a modest year-over-year growth of 0.6%. Despite this stability, the sector experienced a significant contraction in investment activity, with venture funding falling 33% quarter-over-quarter in Q4 to $308 million. This decline reflects a broader normalization of capital flows to pre-pandemic levels, as the industry shifts away from the high-growth, speculative environment of 2021 and 2022.
Key industry trends in late 2023 were defined by regulatory and operational restructuring. A landmark legal verdict against Google established that its app store practices constituted an illegal monopoly, forcing potential shifts in how developers distribute content and process payments. Simultaneously, major players like ByteDance began retreating from gaming divisions, while the industry at large grappled with approximately 10,500 layoffs. These workforce reductions were driven by a heightened focus on operational efficiency, the prioritization of high-retention projects, and the consolidation of assets following major mergers and acquisitions.
Geographically, North America remains the primary hub for venture capital, though the industry maintains a global footprint with significant activity in Asia and Europe. While venture funding and M&A deal volumes have stabilized, public gaming stocks demonstrated resilience, with leading exchange-traded funds outperforming broader market indices by year-end. Looking forward, the industry is projected to maintain a compound annual growth rate of 3.5% through 2029, supported by the continued integration of user-generated content platforms and advancements in developer tools that emphasize productivity and cost-effective scaling.
- The global gaming industry reached a $184 billion valuation in 2023, reflecting a modest year-over-year growth of 0.6%.
- Venture funding for the gaming sector dropped 33% quarter-over-quarter in Q4 2023 to $308 million, signaling a return to pre-pandemic capital levels.
- Approximately 10,500 industry layoffs occurred in 2023 as companies prioritized operational efficiency, asset consolidation, and high-retention projects.
- A landmark legal verdict against Google ruled its app store practices an illegal monopoly, potentially forcing significant changes to content distribution and payment processing.
- The industry is projected to maintain a 3.5% compound annual growth rate through 2029, driven by user-generated content and productivity-focused developer tools.
+2
KonvoyJan 2024
Report6 pages
The Alumni Effect: A Deep Dive into Studios Founded by Ex-Rioters
The emergence of startups founded by former Riot Games employees represents a significant sub-sector of the venture capital landscape in gaming. Since 2020, investors have funneled nearly $500 million into 27 startups led by these alumni across 38 funding rounds. These founders command a substantial premium in the market, with an average round size of $11 million, which is 53% higher than the $7 million average seen across the broader gaming startup ecosystem.
The investment data reveals a high level of confidence from specialized venture capital firms, with Andreessen Horowitz (a16z Games) and Bitkraft Ventures leading the activity. These firms have participated in deals valued at $339.3 million and $236.3 million respectively. Furthermore, ex-Riot teams demonstrate superior fundraising momentum compared to the general market. A significantly higher percentage of these studios successfully secure follow-on financing within two to three years of their initial rounds, whereas the broader gaming market sees a much sharper decline in subsequent funding success over the same period.
While capital infusion is high, the majority of these ventures are currently in the pre-release phase. Out of 27 identified startups, only six have released products to date. The most well-funded projects include Theorycraft’s Supervoke, Believer’s unannounced AAA title, and Singularity 6’s Palia. The scope of these projects primarily focuses on high-ambition genres such as multiplayer RPGs, extraction MOBAs, and backend infrastructure. This trend underscores a strategic focus on complex, scalable platforms that mirror the live-service expertise associated with the founders' professional origins.
- Startups founded by former Riot Games employees have raised nearly $500 million across 27 companies since 2020.
- Ex-Riot founders command a 53% premium in average round size, securing $11 million per round compared to the $7 million industry average.
- Venture capital firms Andreessen Horowitz and Bitkraft Ventures are the primary backers, participating in deals worth $339.3 million and $236.3 million respectively.
- Alumni-led studios demonstrate superior fundraising momentum, with a higher rate of success in securing follow-on financing within two to three years compared to the broader gaming market.
- Despite significant capital infusion, only six of the 27 identified startups have released products to date.
+1
InvestGameJan 2024
Report11 pages
Supercharged: Powering the Future of the UK Video Game and Interactive Entertainment Industry
The new five‑year strategy and action plan sets out a comprehensive roadmap for the UK video‑games and interactive‑entertainment sector, positioning it as the world’s leading hub for new intellectual property and innovation by 2030. Its core thesis is that sustained growth, enhanced global perception, and a resilient, diverse talent pipeline will secure the industry’s long‑term economic and cultural impact. The plan outlines four strategic priorities—transforming public and media perceptions, building a pro‑games policy agenda, cultivating a highly skilled and inclusive workforce, and strengthening businesses through targeted support.
Key initiatives include three flagship campaigns: energising industry to turn innovative stories into globally successful IPs, empowering talent by nurturing creators and entrepreneurs, and elevating games to showcase British‑made titles as forces for good. The 2024‑25 action schedule launches a coordinated PR strategy, high‑impact partnerships with cultural and digital brands, and an evidence‑led lobbying effort aimed at more competitive tax reliefs, increased investment, and the introduction of a Digital Creativity GCSE. A new research and evidence base will underpin policy advocacy, while a sector‑wide skills network and the refreshed #RaiseTheGame programme will drive diversity, equity, and inclusion across the talent pipeline.
The plan also commits to environmental responsibility through participation in the Playing for the Planet Alliance and internal sustainability measures. Supporting stronger businesses will involve a refreshed membership strategy, expansion of the Ukie Worldwide platform for trade and investment, and the continuation of the Video Games Growth Programme. By inviting industry stakeholders to engage through surveys, working groups, mentorship, and board participation, the strategy seeks broad collaboration to deliver its ambitious objectives across the UK’s mobile, console, core and casual game segments throughout the 2024‑2030 horizon.
- The UK video game industry has launched a five-year strategy aiming to establish the nation as the global leader in intellectual property and innovation by 2030.
- The 2024-25 action plan prioritizes lobbying for more competitive tax reliefs, increased investment, and the introduction of a Digital Creativity GCSE.
- Strategic efforts to strengthen the workforce include the expansion of the #RaiseTheGame diversity, equity, and inclusion programme and the creation of a sector-wide skills network.
- Business growth initiatives include the expansion of the Ukie Worldwide trade platform and the continuation of the Video Games Growth Programme.
- The industry is formalizing its commitment to environmental sustainability through participation in the Playing for the Planet Alliance.
+1
UkieJan 2024
Report72 pages
Serbian Gaming Industry Report 2023
The 2023 Serbian gaming industry assessment quantifies the sector’s rapid expansion, maps its ecosystem, and evaluates the conditions shaping future growth. Drawing on a 97‑question survey that reached 80 % of the domestic ecosystem and validated financial data for the 21 leading firms, the analysis establishes a clear upward trajectory for Serbia’s game development landscape.
Total industry revenue reached €175 million, a 17 % year‑on‑year increase, while the workforce nearly doubled to roughly 4,300 professionals. The market now hosts 38 active studios producing 81 titles, with mobile‑first games still dominant but ceding share to core and original‑IP projects. Talent inflows from Russia, Ukraine and Belarus, together with 70 % of respondents expressing optimism, underpin this momentum, and a quarter of companies are planning foreign offices despite lingering concerns over tax incentives and regulatory red tape.
The ecosystem comprises more than 140 companies and over 500 regional stakeholders, featuring high‑profile successes such as Foxy Voxel’s “Going Medieval” (850 k+ copies), GameBiz Consulting’s $250 million revenue from 80+ global studios, Onyx Studio’s 57 million monthly players, and Sozap’s NASDAQ listing with 30 million downloads. Collaborative ties with DICE/EA, Microsoft, Google and Epic Games, alongside mentoring programmes, Gamescom exposure, and the Shift2Games and Playing Narratives initiatives, reinforce Serbia’s emergence as a European development hub. At the same time, the rollout of generative‑AI tools raises IP, privacy and deep‑fake risks, prompting EU‑wide regulatory scrutiny.
Overall, the sector is maturing into a diversified, internationally connected hub with strong growth prospects. Realising its potential will require addressing regulatory and fiscal barriers, leveraging AI responsibly, and sustaining education and mentorship programmes that nurture talent and support SMEs in scaling their operations.
- The Serbian gaming industry generated €175 million in revenue in 2023, marking a 17% year-on-year increase.
- The sector's workforce nearly doubled to approximately 4,300 professionals, supported by talent inflows from Russia, Ukraine, and Belarus.
- The ecosystem now includes 38 active studios producing 81 titles, with a strategic shift occurring from mobile-first games toward core and original-IP projects.
- High-profile industry successes include Foxy Voxel’s 'Going Medieval' (850k+ copies), Onyx Studio’s 57 million monthly players, and Sozap’s NASDAQ listing.
- Serbia has established strong collaborative ties with major global players including DICE/EA, Microsoft, Google, and Epic Games.
+1
SGAJan 2024
Report27 pages
Global Sports Tech Report 2024
I’m ready to craft a comprehensive synthesis, but I’ll need the remaining section summaries to capture the full scope, findings, and conclusions of the Global Sports Tech Report 2024. Could you please provide the rest of the section-by-section summaries?
- The sports tech sector saw record deal-making in 2024, with $86 billion in total deal value across 1,152 deals, including 18 M&A deals over $1 billion and 17 financings over $50 million, and over $6 billion raised by new funds.
- Public markets experienced a rebound in investor confidence, evidenced by a wave of debt refinancings (e.g., Liberty Media, Peloton, Flutter) and follow-on equity rounds (e.g., Liberty Media, Amer Sports), with Canal+ spinning off from Vivendi to list on the LSE.
- Major acquisitions in 2024 included Silverlake's $13 billion acquisition of Endeavor, KKR's $4.75 billion acquisition of Varsity Brands, and Standard General's $4.6 billion acquisition of Bally's Fantasy, Esports & Betting.
- Significant fundraising rounds included ŌURA's $200 million Series D, TOCA Soccer's $100 million Series F, and LOVB's $100 million round, indicating strong investment in health-tracking devices, tech-enabled sports experiences, and new sports leagues.
- Athlete Performance was the top-performing sub-sector with a 52.03% cumulative stock price return, significantly outperforming the S&P 500 (23.31%) and other sports tech categories like Fantasy/Esports/Betting (10.36%) and Digital Media/OTT/Content (5.36%).
+1
Drake Star PartnersJan 2024
Report64 pages
Blockchain Game Alliance: State of the Industry 2024
The blockchain gaming sector is entering a phase of maturation characterized by a strategic pivot from speculative financial models toward high-quality, "fun-first" development. Player asset ownership remains the industry’s primary value proposition, cited by over 71% of professionals for four consecutive years. This shift is bolstered by the entry of traditional gaming giants such as Sony and Ubisoft, which provides necessary credibility to a field where 66.3% of practitioners still identify public misconceptions of scams as a major hurdle. While the industry faces a 42.7% decline in new hiring due to market uncertainty, professional sentiment remains resilient, with over 82% of workers intending to remain in the sector long-term.
Geographically, the industry is expanding its footprint into the Middle East and South America, while Asia and Latin America lead in the adoption of player-reward mechanics. Despite this global reach, the sector continues to struggle with demographic challenges, including a lack of gender diversity and a decline in younger talent entering the workforce. Operationally, the most significant barriers to mainstream adoption are onboarding complexities and poor user experience, though the severity of these concerns has decreased significantly since 2023. Companies currently identify lack of funding and high user acquisition costs as their most pressing internal obstacles.
Looking toward 2025, the industry is moving toward "invisible" Web3 infrastructure to prioritize seamless gameplay over technical complexity. Emerging trends include the rise of fully onchain games, the integration of artificial intelligence for personalized experiences, and the use of social platforms like Telegram to simplify user acquisition. As environmental concerns continue to fade, the focus has shifted toward sustainable "play-and-earn" economies and the consolidation of fragmented infrastructure. This evolution suggests a transition toward a more integrated gaming ecosystem where blockchain serves as a foundational layer for digital property rights rather than a standalone marketing feature.
- The blockchain gaming industry is shifting from speculative models to 'fun-first' development, with 71% of professionals identifying player asset ownership as the primary value proposition.
- Mainstream adoption is being driven by the entry of traditional giants like Sony and Ubisoft, though 66.3% of practitioners still cite public perceptions of scams as a significant barrier.
- Operational barriers like onboarding complexity and poor user experience remain the top hurdles to mainstream growth, despite a notable decrease in the severity of these concerns since 2023.
- Industry hiring has declined by 42.7% due to market uncertainty, yet 82% of current workers intend to remain in the sector long-term.
- Companies are currently prioritizing funding and high user acquisition costs as their most pressing internal obstacles.
+1
Blockchain Game AllianceJan 2024
Report30 pages
Gaming Industry Report: Global & MENAP Outlook Q4 2023
The analysis presents a forward‑looking assessment of the global gaming market with a particular focus on the MENAP region, outlining the strategic opportunities that are reshaping the industry in 2024 and beyond. Central to the outlook is the rapid convergence of emerging technologies—virtual reality, artificial intelligence, mobile platforms, quantum computing, GPU‑as‑a‑Service, and cloud gaming—which together are accelerating content creation, distribution, and consumption across diverse consumer bases.
Investment activity is framed around a thesis that prioritises three core pillars: high‑value content and intellectual property, software efficiency solutions that lower development costs, and user‑generated‑content ecosystems that drive engagement and monetisation. Funding targets range from pre‑seed to Series A rounds, with typical ticket sizes of $1 million to $8 million, reflecting confidence in early‑stage ventures that can capitalize on the identified technology trends. The outreach strategy includes participation in high‑profile events such as the World Gaming Conference in Abu Dhabi (15‑16 February) and LEAP 2024 in Riyadh (4‑7 March), complemented by a dedicated “Gaming Investor” newsletter, a GameON podcast, and sponsorship opportunities for research partners.
Overall, the findings underscore a vibrant growth trajectory for gaming in both established and emerging markets, driven by technological innovation and a robust pipeline of investable startups. Stakeholders are encouraged to engage through subscription services, collaborative research, and direct investment to capture value in this rapidly evolving sector.
- Investment activity in the gaming sector is currently targeting early-stage ventures from pre-seed to Series A, with typical ticket sizes ranging from $1 million to $8 million.
- Strategic investment is focused on three core pillars: high-value intellectual property, software solutions that reduce development costs, and ecosystems centered on user-generated content.
- The industry is experiencing a rapid convergence of emerging technologies, including AI, VR, cloud gaming, quantum computing, and GPU-as-a-Service, to accelerate content creation and distribution.
- The MENAP region is a primary focus for growth, with key industry engagement scheduled for the World Gaming Conference in Abu Dhabi on February 15–16 and LEAP 2024 in Riyadh on March 4–7.
- Market growth is being driven by a combination of technological innovation and a robust pipeline of investable startups across both established and emerging global markets.
+1
Shorooq PartnersDec 2023
Presentation12 pages
Wyniki Finansowe 9M23
PCF Group S.A. experienced significant organizational growth and structural expansion during the first nine months of 2023. The workforce reached a total of 722 employees by September 30, 2023, continuing a steady upward trajectory from 612 in 2022 and 495 in 2021. This growth is distributed across a global network of studios, with a primary concentration in Europe, where the headcount rose to 473, and a substantial presence in North America, accounting for 249 staff members. The internal composition of the team remains heavily weighted toward production, consisting primarily of developers and quality assurance professionals, supported by back-office staff and specialized units such as GameOn and Incuvo.
The geographic footprint of the group spans multiple key hubs, including Warsaw, Rzeszów, Katowice, Kraków, and Łódź in Poland, alongside international locations in Newcastle, Dublin, Montreal, and New York. This infrastructure supports a diversified operational model that includes both core development studios and a dedicated publishing division. The expansion reflects a strategic commitment to scaling production capabilities across various territories to support ongoing development projects.
Financial positioning for the period is characterized by a balance sheet that emphasizes long-term value creation through development work in progress and intangible assets. Key financial components include significant investments in development projects, tangible fixed assets, and right-of-use assets, balanced against equity and liquid holdings in cash and bonds. While specific revenue figures for the nine-month period are integrated into broader reporting, the data highlights a period of intensive investment in human capital and project pipelines intended to drive future growth within the competitive global gaming market.
- PCF Group S.A. grew its total workforce to 722 employees by September 30, 2023, up from 612 in 2022 and 495 in 2021.
- The company maintains a global footprint with 473 employees in Europe and 249 in North America, operating across hubs including Warsaw, Newcastle, Dublin, Montreal, and New York.
- The organizational structure is heavily weighted toward production, with the majority of the 722 staff comprised of developers and quality assurance professionals.
- The group's operational model integrates core development studios with a dedicated publishing division and specialized units, specifically GameOn and Incuvo.
- Financial strategy for the first nine months of 2023 focused on intensive capital investment in development projects, intangible assets, and human capital to support future growth.
+1
PCF GroupNov 2023
Report68 pages
The Economic Impacts of Video Game Technology Spillover: UK and Nordic Economies
The analysis quantifies how video‑game technology generates measurable economic benefits beyond the entertainment sector, arguing that spill‑over effects constitute a significant engine of growth for advanced‑technology economies. By applying the IMPLAN input‑output model to 2021 data, the study estimates that spill‑overs contributed roughly £1.3 billion of total output and £760 million of GDP to the United Kingdom, delivering £380 million of labour income and £250 million of government revenue while sustaining about 9,900 non‑gaming jobs. These positions are concentrated in information‑technology, business services and energy extraction, with average salaries 25 % above the national mean. In the Nordic region, comparable effects amounted to £190 million of output and £40 million of GDP, underscoring the broader relevance across Western Europe.
The research situates these figures within the wider UK games ecosystem, which comprises approximately 2,600 firms and 71,400 jobs across direct, indirect and induced employment. Spill‑over activity accounts for roughly 13 % of the industry’s gross value added and 19 % of its employment, highlighting the sector’s pivotal role in supporting ancillary markets. Sectoral case studies illustrate how real‑time engines (Unreal, Unity), VR/AR headsets and haptic devices are reshaping healthcare, oil and gas, architecture, horticulture, furniture design and automotive safety, delivering faster, lower‑cost visualisation, enhanced training and new revenue streams.
The findings extend to the United States, where about one‑fifth of software‑job growth in 2016 and $0.5 billion of software output are linked to game‑technology diffusion. Collectively, the evidence demonstrates that video‑game innovations act as a cross‑industry catalyst, generating substantial fiscal, employment and productivity gains across multiple high‑value sectors during the 2021‑2022 period.
- In 2021, video game technology spill-overs contributed £1.3 billion in total output and £760 million to UK GDP, while sustaining 9,900 non-gaming jobs.
- Spill-over activity from the UK games industry accounts for 13% of the sector's gross value added and 19% of its total employment.
- Non-gaming roles supported by game technology—primarily in IT, business services, and energy—command average salaries 25% higher than the UK national mean.
- Real-time engines like Unreal and Unity, alongside VR/AR and haptic hardware, are driving productivity and cost reductions in sectors including healthcare, architecture, automotive safety, and energy extraction.
- The economic impact of game technology is significant across Western Europe, with the Nordic region recording £190 million in output and £40 million in GDP from these spill-overs.
+2
UkieNov 2023
Presentation17 pages
Financial Results 1H23
This financial analysis details the performance of PCF Group (People Can Fly) for the first half of 2023, a period characterized by strategic expansion and significant capital raising despite a year-over-year decline in profitability. The group reported revenues of 68.7 million PLN for 1H23, down from 90.6 million PLN in 1H22. This decrease, alongside a drop in adjusted EBITDA from 29.7 million PLN to 4.0 million PLN and a net loss of 13.1 million PLN, is attributed to a high comparative base in 2022 following the termination of the Take-Two Interactive contract and the release of Green Hell VR. Current results were also impacted by increased operational scale, with the workforce growing 16% to 674 employees.
The group’s portfolio remains robust, featuring eight projects across various stages of development. Key highlights include two work-for-hire projects for Microsoft (Maverick and Gemini) and three self-published titles (Dagger, Bifrost, and Victoria) slated for 2025-2026. Project Maverick is expected to contribute significantly to financial results starting in the third quarter of 2023. Additionally, the group is expanding into the VR market with Bulletstorm VR, scheduled for release in December 2023.
A pivotal development in 1H23 was the successful completion of a secondary public offering (SPO), raising 235.3 million PLN to fund the group’s updated strategy. This process brought Krafton Inc. on as a strategic investor with a 10% stake following a 144.5 million PLN investment. The agreement grants Krafton specific rights, including right of first refusal for publishing certain upcoming titles. Geographically, the group maintains a strong international presence with studios across Europe and North America, positioning itself for long-term growth through a mix of work-for-hire and self-publishing models.
- PCF Group raised 235.3 million PLN through a secondary public offering, including a 144.5 million PLN investment from Krafton Inc., which acquired a 10% stake and right of first refusal for select future titles.
- Financial performance declined in 1H23, with revenue falling to 68.7 million PLN from 90.6 million PLN in 1H22 and a net loss of 13.1 million PLN reported.
- Adjusted EBITDA dropped significantly to 4.0 million PLN from 29.7 million PLN in 1H22, driven by a high comparative base from the previous year and increased operational costs.
- The company is scaling its workforce by 16% to 674 employees to support a portfolio of eight active projects, including two work-for-hire titles for Microsoft and three self-published games expected in 2025-2026.
- Project Maverick is projected to begin contributing to financial results in the third quarter of 2023.
+2
PCF GroupSept 2023
Report19 pages
Global Gaming Report Q3 2023
The third quarter of 2023 marked a pivotal turning point for the global gaming industry as major strategic players resumed large-scale consolidation efforts following an extended period of relative inactivity. Total deal value across M&A, private placements, and public markets reached $11 billion, with 120 deals announced or closed during the period. While the quarter concluded with the landmark Microsoft-Activision merger, the period was characterized by a resurgence in activity from giants like Tencent, which led the market with five deals, including the majority acquisition of Techland.
M&A activity was particularly robust in the PC and console segments, accounting for approximately 40% of deals, followed by mobile at 21%. Notable transactions included Goldman Sachs’ $1.72 billion offer for Kahoot! and Playtika’s $465 million expansion into the casual gaming sector. Geographically, North America and Europe remained the primary hubs for deal-making, though Asian firms like Capcom and Savvy Games Group continued to exert significant influence.
Private financing saw a modest increase in value over the previous quarter, totaling approximately $1 billion across 185 deals. Investment remained heavily weighted toward early-stage companies, which represented 85% of the volume. Key segments attracting capital included AI-driven tools, blockchain gaming, and platform infrastructure, highlighted by significant raises from Candivore, Second Dinner, and Inworld AI. Venture capital activity was led by firms such as BITKRAFT and Andreessen Horowitz.
The outlook for 2024 suggests a steady increase in M&A as strategic buyers like Sony, Take-Two, and Savvy Games Group remain active, while others like Embracer Group focus on divestitures. Although mid-to-late-stage financing remains cautious, the emergence of successful tech IPOs and increased interest from private equity firms—driven by attractive public valuations—point toward a potential reopening of the public listing window and a rise in large-scale, PE-led acquisitions in the coming year.
- The global gaming industry saw a significant resurgence in consolidation during Q3 2023, with 120 deals totaling $11 billion in value, headlined by the Microsoft-Activision merger.
- M&A activity was concentrated in PC and console segments at 40% of deal volume, while mobile accounted for 21%.
- Tencent emerged as the most active strategic buyer with five deals, including the majority acquisition of Techland, while Goldman Sachs made a $1.72 billion offer for Kahoot!.
- Private financing reached $1 billion across 185 deals, with 85% of volume directed toward early-stage companies focused on AI tools, blockchain, and platform infrastructure.
- The 2024 outlook anticipates continued M&A activity from major players like Sony, Take-Two, and Savvy Games Group, alongside potential divestitures from the Embracer Group.
+1
Drake Star PartnersSept 2023
Report16 pages
Gaming Deals Report: 2023 Q3
The gaming industry experienced a significant market correction during the first three quarters of 2023, with deal activity falling to its lowest levels since the pre-pandemic era. Total private investment value dropped fourfold compared to the 2021–2022 average, falling to $2.3 billion across 325 deals. M&A activity similarly cooled, totaling $8.5 billion—excluding the massive Activision Blizzard acquisition which closed in October 2023. Public offerings remained the weakest segment, characterized by a closed IPO window and a 29% year-over-year decline in activity.
The downturn is most pronounced in late-stage venture capital, which reached a nadir of $300 million as investors prioritized solid financials and proven exit paths over growth at any cost. Conversely, early-stage activity remained relatively resilient, maintaining volumes consistent with pre-COVID levels. Strategic shifts are evident as Western corporate investors scale back due to internal restructurings and layoffs, while Asian giants like Tencent and NetEase remain active global participants. A notable emerging trend is the surge in AI-related gaming startups, which saw an unprecedented 21 deals in the third quarter of 2023 alone.
Geographically, North America led in investment value, followed by Western Europe, though Asian strategic investors continue to drive cross-border activity. The methodology relies on tracked closed transactions across PC, console, mobile, and multiplatform segments, excluding pure gambling and non-gaming blockchain ventures. While the current landscape is defined by macroeconomic volatility and high interest rates, the presence of significant "dry powder" among private equity firms and stabilizing corporate balance sheets suggests potential for a recovery in dealmaking as the market enters 2024.
- Gaming deal activity in the first three quarters of 2023 hit its lowest level since the pre-pandemic era, with private investment value falling to $2.3 billion across 325 deals.
- M&A activity totaled $8.5 billion, excluding the Activision Blizzard acquisition, while public offerings saw a 29% year-over-year decline due to a closed IPO window.
- Late-stage venture capital funding plummeted to $300 million as investors shifted focus from growth-at-all-costs to companies with proven financials and clear exit paths.
- Early-stage investment volumes remained resilient, maintaining levels consistent with pre-COVID performance despite the broader market correction.
- AI-related gaming startups emerged as a significant growth area, recording 21 deals in the third quarter of 2023 alone.
+1
InvestGameSept 2023
Report36 pages
Gametech Report: Global & MENAP Outlook Q3 2023
This analysis examines the state of the global and MENAP (Middle East, North Africa, and Pakistan) gaming sectors during the third quarter of 2023. The primary thesis suggests that while the global industry is undergoing a period of "cautious recalibration" characterized by significant layoffs and a shift toward profitability, the MENAP region remains a resilient growth outlier. The scope covers global investment trends, game engine pricing shifts, and emerging market demographics, with specific deep dives into the Egyptian and Jordanian markets.
Key findings indicate that the global gaming market exceeded $250 billion with a 9.9% CAGR, yet Q3 2023 saw over 2,000 industry layoffs driven by M&A activity and a focus on operational efficiency. Despite these global headwinds, the MENA region grew by 6.9% year-over-year, reaching a market size of $5 billion. This growth is fueled by a youthful demographic where 70% of the population is under 30. In Egypt, the largest regional market by population, 60% of top-performing games are casual or hyper-casual, though a significant challenge remains as 40% of gamers are unbanked, necessitating innovation in fintech and alternative payment infrastructures.
The investment landscape shows a return to pre-pandemic levels, with $454 million in global venture capital secured in Q3, primarily in early-stage deals. Asia led transaction volume with 39 deals, while Jordan emerged as a regional leader in funding, securing 30% of MENA deals. The report concludes that the future of the industry will be defined by the integration of Generative AI—expected to impact over 50% of the development process within a decade—and a strategic pivot toward emerging markets to offset rising talent costs in Western territories. Methodology relies on data from partners including AppMagic and Konvoy, alongside internal venture capital tracking.
- The global gaming market reached a valuation exceeding $250 billion with a 9.9% CAGR, even as the industry underwent a period of operational recalibration resulting in over 2,000 layoffs in Q3 2023.
- The MENA region remains a growth outlier, expanding 6.9% year-over-year to reach a $5 billion market size, supported by a demographic where 70% of the population is under 30.
- Global venture capital investment returned to pre-pandemic levels with $454 million secured in Q3 2023, with Jordan emerging as a regional hub by capturing 30% of all MENA-based deals.
- In Egypt, the region's largest market by population, 60% of top-performing titles are casual or hyper-casual games, though 40% of the gamer base remains unbanked and requires alternative payment solutions.
- Generative AI is projected to impact over 50% of the game development process within the next decade.
Shorooq PartnersSept 2023
Report18 pages
H1'23 Gaming Deals Report
The first half of 2023 marked a period of significant contraction for the global video game industry’s financial landscape, characterized by a sharp decline in deal value across private investments, mergers and acquisitions, and public offerings. Total private investment fell to $1.5 billion across 239 deals, an 81% drop in value compared to the same period in 2022. This downturn was driven by a cooling late-stage venture capital market and a closed IPO window, which reduced the attractiveness of high-valuation exits. While early-stage activity remained the primary driver of deal volume, even this segment saw a threefold contraction in total value as investors shifted focus toward supporting existing portfolios rather than funding newcomers.
The mergers and acquisitions sector experienced the most dramatic decline, with deal value plummeting 97% to $0.9 billion. Strategic investors pivoted toward internal restructuring, cost optimization, and mass layoffs—exemplified by companies like Embracer—rather than aggressive expansion. Public offerings remained similarly muted due to a disparity between reported financial results and previous estimates, leading to significant valuation corrections. Despite the overall stagnation, financial sponsors like Savvy Games Group remained active, and the industry anticipates a value jump in the second half of 2023 as major pending deals, such as the Microsoft-Activision Blizzard acquisition, move toward completion.
Geographically, North America led early-stage investment volume, followed by Western Europe and MENA. Methodologically, the findings are based on tracked closed transactions in the video game industry, excluding gambling and non-gaming blockchain entities. While the broader market struggled, artificial intelligence emerged as a resilient niche, seeing a modest increase to $214.1 million in investment. Startups have largely abandoned "growth at all costs" strategies in favor of profitability and extended runways, while venture capital firms maintain significant unallocated capital that may signal a recovery in late 2023.
- The global video game industry saw a massive financial contraction in H1 2023, with private investment falling 81% to $1.5 billion and M&A deal value plummeting 97% to $0.9 billion.
- Strategic investors shifted focus from aggressive expansion to internal restructuring and cost optimization, resulting in widespread layoffs at companies like Embracer.
- Early-stage investment remained the primary driver of deal volume, though its total value contracted threefold as investors prioritized supporting existing portfolios over new ventures.
- Artificial intelligence emerged as a resilient investment niche, attracting $214.1 million in funding despite the broader market downturn.
- Public offerings remained muted throughout the first half of the year due to valuation corrections caused by a disparity between reported financial results and previous estimates.
+1
InvestGameJun 2023
Report159 pages
Impacto de la aplicación de sistemas de incentivos fiscales en la industria de videojuegos: España
The analysis evaluates how a targeted fiscal‑incentive regime would reshape Spain’s video‑game industry, arguing that a 20 % corporate‑tax credit for developers could expand sector turnover from €1.435 billion in 2022 to roughly €5.5 billion by 2028—a compound annual growth rate of about 27 %—and raise full‑time employment from just under 10 000 jobs to more than 23 000 by 2030, an 80 % increase. Despite the lower tax rate, overall fiscal receipts would grow, with a direct contribution of €1.9 billion and an additional €1.0 billion generated through reinvestment and consumer spending, indicating a net positive return for the Treasury.
Spain’s ecosystem comprises roughly 760 active studios, of which 445 are incorporated, and 71 publishers, with the top ten accounting for almost 95 % of revenue. Development costs vary markedly by platform—averaging €419 k for consoles, €338 k for PC and €94 k for mobile—while break‑even periods range from 8.6 to 15.5 months, underscoring the financing pressure on predominantly
- Implementing a 20% corporate tax credit for developers is projected to grow Spain’s video game sector turnover from €1.435 billion in 2022 to €5.5 billion by 2028, representing a 27% compound annual growth rate.
- The proposed fiscal incentives are expected to increase full-time employment in the industry from under 10,000 jobs to more than 23,000 by 2030.
- The tax regime is forecast to be net-positive for the Treasury, generating €1.9 billion in direct contributions plus an additional €1.0 billion through reinvestment and consumer spending.
- The Spanish market is highly concentrated, with the top ten companies accounting for approximately 95% of total industry revenue.
- Development costs vary significantly by platform, averaging €419k for consoles, €338k for PC, and €94k for mobile.
+2
AEVIJun 2023
Report4 pages
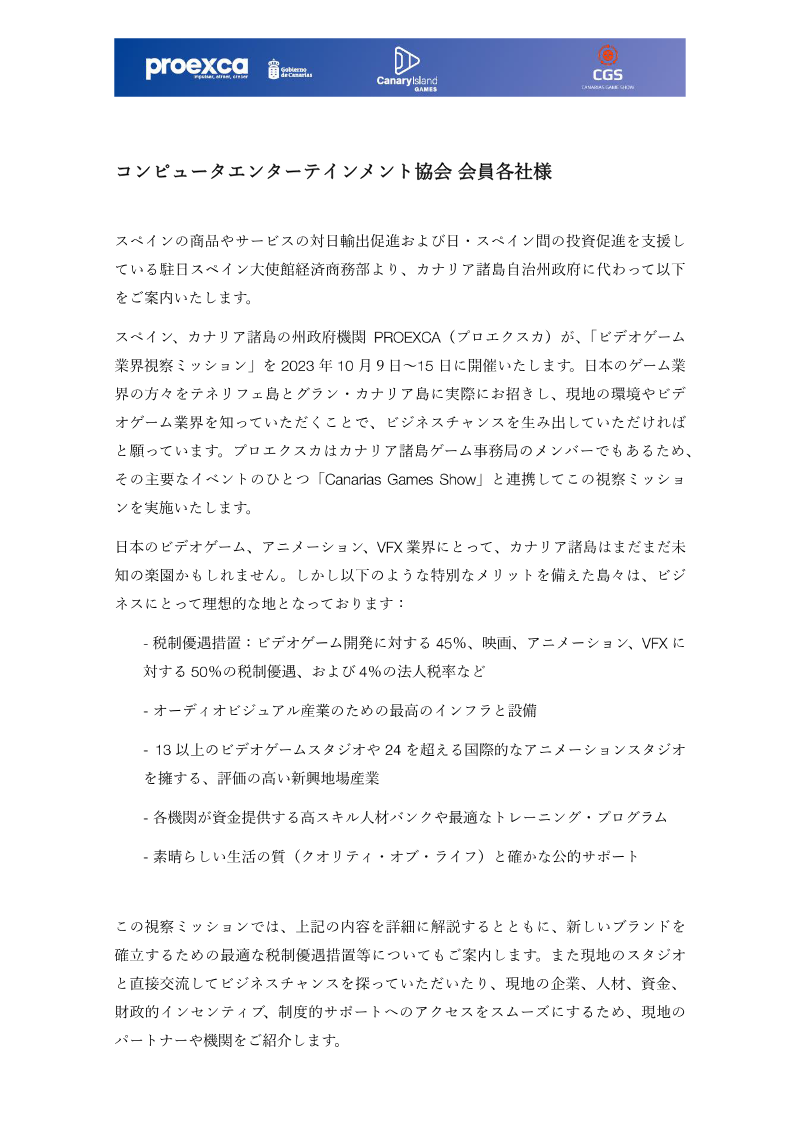
スペイン、カナリア諸島の州政府機関から「ビデオゲーム業界視察ミッション」のご案内
The invitation seeks to generate business opportunities for Japanese video‑game, animation and related audiovisual firms by showcasing the Canary Islands as a strategic production hub. It positions the archipelago as an emerging, tax‑friendly environment, highlighting preferential rates for game development, film and animation, as well as a reduced corporate tax rate, alongside high‑quality infrastructure, skilled talent pools, and strong public support. The core thesis is that direct exposure to local studios, financing mechanisms and regulatory incentives will encourage Japanese companies to establish subsidiaries, pursue co‑production agreements, or outsource projects to Canary Island partners.
The mission is scheduled for 9 – 15 October, with participants traveling from Japan to Tenerife on 9 October and returning after the final day on 15 October. The itinerary includes briefings on the regional industry and tax regime, visits to multiple development studios such as Drakhar, Foxter, The Game Kitchen, Promineo and No Brake Games, a tour of a super‑computer facility, and attendance at the Canarias Game Show on Gran Canaria, featuring B2B matchmaking, conference sessions and networking dinners. All travel costs—including economy‑class round‑trip airfare, hotel accommodation, meals and intra‑island transport—are covered by the organizers, with additional support offered for group participation.
Target participants are Japanese firms contemplating legal entity formation in the Canary Islands, joint‑development projects, or outsourcing production to local studios. The program is coordinated by the Spanish Embassy’s Economic and Commercial Section in Tokyo and the Canary Islands government agency Proexca, which also serves on the regional game office. While the embassy assists with logistics, detailed tax‑incentive information is to be obtained from the Canary Islands authorities and specialist advisors. The initiative aims to deepen Japan‑Spain investment ties within the audiovisual sector by converting the exploratory visit into concrete commercial collaborations.
- The Canary Islands government is hosting a business mission for Japanese video game and animation firms from October 9–15 to promote the region as a strategic production hub.
- The mission covers all travel expenses, including economy-class airfare, accommodation, meals, and local transport, for qualified Japanese companies interested in expansion or outsourcing.
- The Canary Islands offer a competitive business environment featuring reduced corporate tax rates and specific financial incentives for game development, animation, and film production.
- The itinerary includes site visits to local studios such as Drakhar, Foxter, The Game Kitchen, Promineo, and No Brake Games, alongside a tour of a regional super-computer facility.
- Participants will attend the Canarias Game Show on Gran Canaria, which provides dedicated B2B matchmaking, industry conferences, and networking opportunities.
+2
CESA – Computer Entertainment Supplier's AssociationMay 2023
Presentation20 pages
People Can Fly: Q1 2023 Financial Results
PCF Group, the parent entity of the People Can Fly studio, reports a period of continued organizational expansion and strategic financial positioning as of the first quarter of 2023. The group has significantly grown its workforce to 642 employees by March 31, 2023, up from 612 at the end of 2022. This growth is concentrated primarily in its European hubs, including Warsaw, Rzeszów, and Newcastle, while maintaining a substantial presence in North America through its Montreal and New York studios. The team composition remains heavily weighted toward development, supported by specialized units like Incuvo and GameOn.
Financial data indicates a stable balance sheet with total assets and liabilities reaching 351.9 million PLN. A notable shift is observed in the group’s cash position, which decreased from 137.1 million PLN at the end of 2021 to 60.9 million PLN by the end of Q1 2023. Simultaneously, investment in development work in progress has surged to 139.7 million PLN, reflecting an intensive production cycle. Equity remains strong at 271.6 million PLN, providing a solid foundation for the group’s long-term objectives.
The strategic focus is transitioning from a work-for-hire model toward self-publishing. While the group continues to leverage partnerships with global publishers to ensure financial stability and experimental freedom, the ultimate goal is to release three AAA projects under a self-publishing framework. This shift is projected to drive a 4.9x revenue increase between 2023 and 2027. Funding for this strategy is secured through a combination of operational cash flow, debt financing, and a strategic investment agreement with Krafton, which contributed 144.5 million PLN via a share subscription. This diversified capital structure is intended to support the full realization of the group’s ambitious development pipeline.
- People Can Fly is transitioning from a work-for-hire model to self-publishing, with a strategic goal to release three AAA projects by 2027.
- The group projects a 4.9x revenue increase between 2023 and 2027, supported by a capital structure that includes a 144.5 million PLN share subscription from Krafton.
- Development intensity has surged, with investment in work-in-progress projects reaching 139.7 million PLN as of Q1 2023.
- The company's cash position decreased from 137.1 million PLN at the end of 2021 to 60.9 million PLN by the end of Q1 2023, reflecting heavy reinvestment into production.
- The workforce grew to 642 employees by March 31, 2023, up from 612 at the end of 2022, with expansion focused on European hubs and North American studios.
+1
PCF GroupMay 2023
Report230 pages
Turkey Game Market 2022 Report
The Turkish gaming market in 2022 serves as a critical case study of a high-growth production hub navigating significant domestic economic volatility. While the player base expanded to over 44 million users—with 81% of adults engaging in mobile gaming—total market revenue saw a sharp correction, falling from $1.2 billion in 2021 to approximately $625 million. This decline was primarily driven by the depreciation of the Turkish Lira and weakened consumer purchasing power, which has accelerated a shift toward free-to-play titles, subscription services, and a demand for high-quality localization to reach a population with generally low English proficiency.
Despite these fiscal challenges, Türkiye has solidified its position as a global leader in gaming investment and development. Istanbul ranks second in Europe and fifth globally for gaming transactions, securing over $424 million in investments across dozens of deals. The domestic ecosystem is maturing beyond its historical focus on hyper-casual mobile titles, with over 2,943 publishers on Google Play and a strategic pivot toward indie, PC, console, and hybrid-casual development. This evolution is supported by a robust infrastructure of 25 entrepreneurship centers and 19 university programs, though a deficit in qualified instructional talent remains a hurdle for long-term sustainability.
The region has also emerged as a premier esports destination, evidenced by hosting the VALORANT Champions Tour and the formal legal recognition of the Turkish Esports Federation, which oversees more than 15,000 licensed players. While traditional segments like internet cafes have declined due to rising operational costs, the integration of gamification into e-commerce and corporate sectors is expanding. Moving forward, the industry is expected to maintain a compound annual growth rate of 24.1% through 2026, driven by blockchain integration, AI technologies, and a transition toward more complex, mid-core gaming experiences.
- The Turkish gaming market experienced a significant revenue contraction in 2022, falling to $625 million from $1.2 billion in 2021 due to currency depreciation and reduced consumer purchasing power.
- Despite the revenue decline, Istanbul remains a global investment hub, ranking second in Europe and fifth globally with over $424 million secured across gaming transactions in 2022.
- The industry is projected to maintain a 24.1% compound annual growth rate through 2026, driven by a strategic shift toward mid-core, PC, and console development alongside AI and blockchain integration.
- The domestic player base reached 44 million users in 2022, with 81% of adults participating in mobile gaming and a strong market preference for free-to-play models and localized content.
- The Turkish gaming ecosystem is maturing beyond hyper-casual titles, supported by 2,943 Google Play publishers and a specialized infrastructure of 25 entrepreneurship centers and 19 university programs.
+1
Gaming in TurkeyApr 2023
Report30 pages
Gaming Industry Report: Q1 2023
The gaming industry experienced a resilient start to 2023, with a projected global market size of $201 billion, representing a 9% year-over-year increase. Public markets showed strength, with gaming-focused exchange-traded funds (ETFs) recording gains between 10% and 23% year-to-date. While private market venture funding saw a total of $761 million across 109 deals in the first quarter, activity remains concentrated in early-stage investments, as late-stage funding has slowed significantly compared to the peak levels of 2021.
Geographically, Asia led global venture funding in the first quarter, followed by North America and Europe. Emerging markets such as Africa and South America saw sporadic but notable deal activity, highlighting a broader global interest in gaming infrastructure and content. Major industry players currently hold approximately $48 billion in cash and equivalents, suggesting a stable environment for potential future mergers and acquisitions despite ongoing regulatory scrutiny regarding large-scale consolidation.
Key industry trends in early 2023 include the integration of artificial intelligence for asset generation and conversational tools, alongside a strategic shift by major tech firms toward cloud-based gaming infrastructure. Competitive dynamics are evolving as Epic Games introduces self-publishing tools to challenge Steam’s market dominance and integrates user-generated content into its Fortnite ecosystem. Furthermore, platforms like Roblox are successfully expanding their reach by aging up their user demographic. These developments, supported by a robust schedule of global industry conferences, indicate a focus on platform scalability, content diversification, and the optimization of developer tools to sustain long-term growth.
- The global gaming market is projected to reach $201 billion in 2023, reflecting a 9% year-over-year growth rate.
- Major industry players possess $48 billion in cash reserves, signaling a stable environment for future M&A activity despite regulatory headwinds.
- Venture capital funding totaled $761 million across 109 deals in Q1 2023, with investment heavily concentrated in early-stage ventures rather than late-stage rounds.
- Gaming-focused ETFs demonstrated strong performance in early 2023, recording year-to-date gains ranging from 10% to 23%.
- Asia currently leads global venture funding, followed by North America and Europe, with emerging activity appearing in African and South American markets.
+3
KonvoyApr 2023