Report26 pages
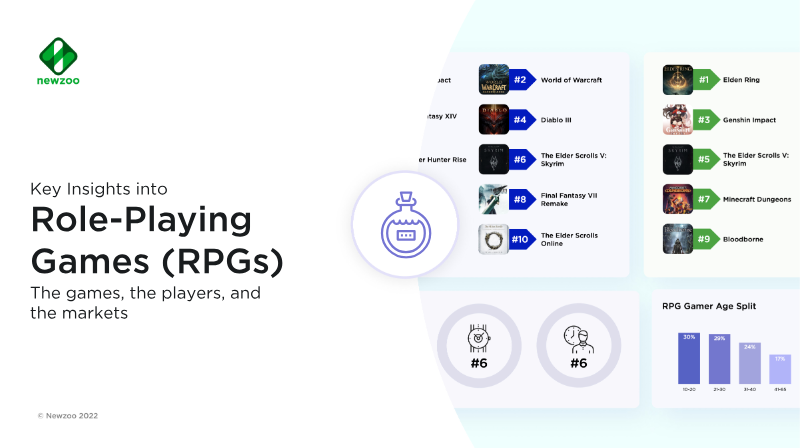
Key Insights into Role-Playing Games (RPGs)
Role-Playing Games (RPGs) represent the highest-revenue genre in the global gaming market as of 2022. The genre is characterized by deep character development, party-based mechanics, and progression systems centered on quests and combat. While RPGs are played across all platforms, they maintain a strong presence on PC and console, where they consistently rank among the top genres for monthly active users.
The demographic profile of the RPG audience is predominantly male, accounting for 58% of players, and skews toward younger age groups, with 59% of the player base falling between the ages of 10 and 30. Engagement patterns reveal that RPG players are highly active, averaging 18.8 sessions per month. The genre also demonstrates significant cross-genre appeal, with high player overlap in the adventure, shooter, and battle royale categories. High magical fantasy remains the most popular thematic element, utilized by 63% of the player base, while skill and talent trees serve as the most prevalent gameplay mechanic.
Monetization within the RPG space is dominated by pay-to-play models, which reach 97% of the player base, followed closely by in-app purchases at 90%. Geographically, the United States and Japan lead in monthly active users on PC and console. The genre also maintains a robust live-streaming presence, generating 205 million hours watched across platforms like Twitch and Facebook Gaming in June 2022. These insights are derived from data covering 37 markets, excluding China and India, and utilize proprietary gamer segmentation to analyze player motivations, viewing habits, and engagement metrics across the broader gaming ecosystem.
- As of 2022, Role-Playing Games (RPGs) rank as the highest-revenue genre in the global gaming market.
- The player base is predominantly male (58%) and young, with 59% of users falling between the ages of 10 and 30.
- Monetization is heavily driven by pay-to-play models used by 97% of the player base, supplemented by in-app purchases at 90%.
- High magical fantasy is the dominant theme, appearing in 63% of RPGs, while skill and talent trees remain the most prevalent gameplay mechanics.
- RPG players exhibit high engagement, averaging 18.8 sessions per month, with significant audience overlap in the adventure, shooter, and battle royale genres.
+2
NewzooJan 2025

Report39 pages
Annual Report of the German Games Industry 2025
Germany’s video‑game sector generated €5.84 billion in 2024, ranking fifth globally but declining 6 % year‑on‑year. The contraction was most pronounced in game purchases, which fell 17 %, while online gaming and subscription services surged 43 % to €3.26 billion, underscoring a decisive shift toward digital and cloud‑based play. In‑game and in‑app purchases accounted for €4.6 billion, a modest 3 % drop, yet mobile gaming alone grew 63 % since 2019 to €3 billion. Console and PC revenues were €1.9 billion and €1.5 billion, respectively, while hardware sales fell 10 %, with consoles down 26 %. The workforce expanded to 37.5 million players, nearly half women and with an average age of 39.5 years, indicating broader demographic penetration.
Policy analysis reveals that restrictive federal and state funding schemes have limited access for start‑ups, contributing to an 87 % negative perception of Germany’s international competitiveness. The 2025 coalition agreement introduces tax breaks and a €2 750/month “Press Start” grant for new studios, signalling a shift toward a hybrid funding model. A projected €125 million annual increase from 2026, with each tax‑credit euro expected to generate €4.80 in economic spill‑overs, is coupled with calls for university programmes, incubators, and a dedicated “Games University” to supply skilled talent. Without these reforms, Germany risks falling behind global leaders.
The industry’s ecosystem has expanded through high‑profile events such as devcom and gamescom, which attracted record attendance and showcased international diversity. Initiatives like the Press Start: Games Founding Grant, esports talent pipelines, and the Equal Esports Cup demonstrate a coordinated effort to build inclusive professional pathways. The German Games Association, through gamescom and sustainability initiatives such as “Playing for the Planet,” positions Germany as a climate‑friendly, diverse hub. Market data confirm that 60 % of Germans play video games, with mobile gaming dominating at 37.9 %, while over 90 % of households have internet access, underscoring a mature, multi‑platform market poised for continued growth across consoles, PC and mobile channels.
- Germany’s video game sector generated €5.84 billion in 2024, representing a 6% year-on-year decline despite the country maintaining its position as the world's fifth-largest market.
- Consumer spending has decisively shifted toward digital models, with online gaming and subscription services surging 43% to €3.26 billion, while traditional game purchases dropped by 17%.
- Mobile gaming has become a primary market driver, growing 63% since 2019 to reach €3 billion in revenue, while hardware sales contracted by 10% overall, led by a 26% decline in console sales.
- To combat an 87% negative perception of international competitiveness, the 2025 coalition agreement introduces a hybrid funding model featuring tax breaks and a €2,750/month 'Press Start' grant for new studios.
- The government projects a €125 million annual funding increase starting in 2026, with each euro of tax credit expected to generate €4.80 in economic spill-overs.
gameJan 2025

Report37 pages
SensorTower Report: Southeast Asia Mobile Game Market Insights 2025
SensorTower’s Southeast Asia Mobile Game Market Insights 2025 positions the region as a pivotal growth engine for mobile gaming, with 1.93 billion new installs and $625 million in IAP revenue reported for Q1 2025. The analysis draws on App Store and Google Play data, classifying titles by genre and tracking revenue while excluding ad income. Casual genres such as Arcade and Simulation dominate download volumes, whereas Strategy, Shooters, and social‑driven RPGs generate the bulk of monetization. Mobile Legends: Bang Bang and Garena Free Fire remain revenue leaders, while newer IPs like Ragnarok M: Classic and Magic Chess: Go Go rapidly climb both download and revenue charts, illustrating the market’s receptiveness to fresh, socially rich experiences.
Vietnam exemplifies deep localization success: Roblox leads downloads while Garena Free Fire dominates revenue, and local titles such as “Trò Vẽ Vui Tuổi Thơ” fuel organic growth. In the Philippines, hyper‑casual “Block Blast!” captures the largest download share, yet Mobile Legends: Bang Bang sustains top revenue. Across both markets, robust community engagement and localized content underpin strong monetization even as casual download volumes fluctuate.
From 2017 through Q1 2025, Southeast Asian titles have consistently topped global download and revenue charts. Vietnamese and Singaporean publishers now rank among the world’s top download leaders, with titles like Free Fire and Car Race expanding genre breadth. The region’s high mobile penetration, community‑driven marketing, and IP collaborations enable SEA publishers to scale player engagement and revenue on a global stage. Overall, the report underscores Southeast Asia’s emergence as both a production hub and a lucrative monetization frontier for mobile games worldwide.
- Southeast Asia generated 1.93 billion new mobile game installs and $625 million in in-app purchase revenue during Q1 2025.
- Casual genres like Arcade and Simulation drive the highest download volumes, while Strategy, Shooters, and social-driven RPGs account for the majority of monetization.
- Mobile Legends: Bang Bang and Garena Free Fire remain the region's top revenue-generating titles, though newer IPs like Ragnarok M: Classic and Magic Chess: Go Go are rapidly gaining market share.
- Vietnam and Singapore have emerged as global publishing hubs, with local developers consistently ranking among the world's top leaders for both downloads and revenue.
- Market success in the region is heavily dependent on deep localization and community-driven engagement, as evidenced by the dominance of specific titles like Roblox in Vietnam and Block Blast! in the Philippines.
Sensor TowerJan 2025

Report32 pages
Hybrid Casual Games Playbook
Hybridcasual games blend the instant‑on‑tap simplicity of hyper‑casual titles with deeper progression systems that encourage sustained engagement. The playbook outlines the genre’s rise, noting a 3 % download growth in 2022 to 5 billion downloads—up from 4.9 billion in 2021—while hyper‑casual downloads fell 15 %. Revenue has nearly doubled over two years, with ads contributing about 50 % of total earnings and in‑app purchases accounting for the remainder. Session lengths average 372 seconds, a 160‑second increase over hyper‑casual games, and retention rates at day 30 reach 54 % versus 42 % for hyper‑casual titles, with day 60 retention at 9 % versus 1 %.
The document surveys sub‑genres such as Arcade Idle, Tower Defense, and Interactive Story, citing successful titles like Aquarium Land, City Defense!, and Fight for America. It highlights how hybrid mechanics—drawing towers, RPG‑style upgrades, or automated idle workers—boost lifetime value by 17–35 % in some cases. Methodology relies on aggregate download and revenue data from 2020‑2022, coupled with in‑house analytics tracking session length, retention, and monetization funnels.
Best‑practice guidance centers on marketability, economy tuning, A/B testing, and post‑launch optimization. Case studies of Zombie Defense illustrate how adding narrative layers, social features, and tiered in‑app purchase options can lift LTV to $2+ on day 7. The playbook concludes that sustained success in Hybridcasual hinges on balancing accessibility with meta‑depth, maximizing IAP revenue, and continuously refining content based on player segmentation.
- Hybrid-casual games are outperforming hyper-casual titles, with 5 billion downloads in 2022 (a 3% increase) compared to a 15% decline in hyper-casual downloads.
- Hybrid-casual games achieve significantly higher retention, with day-30 retention at 54% (vs. 42% for hyper-casual) and day-60 retention at 9% (vs. 1%).
- Revenue is split evenly between ads and in-app purchases, with session lengths averaging 372 seconds, which is 160 seconds longer than hyper-casual benchmarks.
- Integrating hybrid mechanics like RPG-style upgrades and automated idle systems can increase player lifetime value by 17–35%.
- Successful titles such as Zombie Defense demonstrate that adding narrative layers and tiered in-app purchase options can drive day-7 lifetime value to over $2.
+1
Sensor TowerJan 2025

Report20 pages
Global Gaming Report Q2 2025
Public gaming equities surged in the first half of 2025, with the Drake Star Gaming Index climbing 28 % compared to a modest 5 % gain in the S&P 500. Leading performers included Square Enix, Roblox and Konami, underscoring a robust rebound in the sector. M&A activity remained steady at 46 deals, highlighted by Krafton’s $516 million purchase of ADK and Epic Games’ acquisition of AI studio Loci. Private‑market financing reached $3 billion across 110 placements, driven by high‑profile exits such as Dream Games’ $2.5 billion minority stake sale to CVC and Apple’s acquisition of RAC7 for its arcade portfolio. Projections indicate a continued rise in M&A and IPO activity through 2026, with artificial intelligence and technology platforms identified as primary growth catalysts.
Private‑placement capital in Q2 2025 totaled $2.6 billion across 24 deals, with the largest transaction—a $5 billion minority stake sale—valuing its target at nearly $5 billion. Deal distribution spanned mobile ($1.5 billion), PC/console ($0.8 billion), platform/tools ($0.4 billion), esports ($0.3 billion) and blockchain/VR‑AR ($0.2 billion). Key investors included CVC, Blackstone, Tencent and Bessemer Venture Partners. Notable exits such as Dream Games’ $2.5 billion minority sale and Arrowhead’s $80 million investment provided significant liquidity for early‑stage venture capitalists.
Valuation analysis reveals a pronounced divergence between high‑growth Asian titles and mature Western peers. Tencent (EV/EBITDA ≈ 5.7x, revenue growth 10%) and Sea Limited (EV/EBITDA ≈ 4.1x, revenue growth 30%) command premium multiples and robust double‑digit growth, reflecting investor appetite for fast‑growing Asian firms. In contrast, U.S. hardware and platform players such as NVIDIA (EV/EBITDA ≈ 17.9x, revenue growth 43%) and Unity (EV/EBITDA ≈ 6.2x, revenue growth –17%) exhibit lower multiples and mixed performance, indicating more modest valuations amid fluctuating earnings. This geographic and segmental disparity underscores the continued premium placed on rapid growth in emerging markets while mature Western companies face a more cautious valuation environment.
- Public gaming equities significantly outperformed the broader market in H1 2025, with the Drake Star Gaming Index rising 28% compared to a 5% gain in the S&P 500.
- Private-market financing reached $3 billion across 110 placements in H1 2025, bolstered by major exits such as Dream Games’ $2.5 billion minority stake sale to CVC.
- M&A activity remains steady with 46 deals recorded in H1 2025, including Krafton’s $516 million purchase of ADK and Epic Games’ acquisition of AI studio Loci.
- Investor sentiment shows a clear geographic divide, with high-growth Asian firms like Sea Limited (30% revenue growth) commanding premium multiples compared to the mixed performance of mature Western platform players like Unity.
- Q2 2025 private-placement capital totaled $2.6 billion, with mobile gaming leading the sector at $1.5 billion, followed by PC/console at $0.8 billion.
+1
Drake StarJan 2025

Report37 pages
The Industry Quest for Growth
Global games spending reached a record $199.4 bn in 2024, rising 3.5 % year‑over‑year and projected to stabilize near $200 bn in 2025 with modest growth thereafter. The sector remains smaller than the broader video‑related entertainment market but is nine times larger than recorded music, underscoring its expanding economic footprint. Key growth levers include a $7‑8 bn upside from Nintendo’s Switch 2, which is expected to sell 103 million units by 2030, and an additional $1‑2 bn from enhanced in‑game monetisation. Emerging markets—particularly the Middle East, Africa, and Southeast Asia—offer significant upside driven by youthful, mobile‑savvy populations.
The launch delay of GTA VI is anticipated to shave $2.7 bn from 2025 console spend, creating a sales window for other publishers and Nintendo to capture holiday‑season revenue. Untapped consumer cohorts, such as 16‑24 year‑old females and players aged 55+, represent further opportunities for market expansion.
Publishers are responding to slower growth by shifting toward higher‑margin, low‑cost strategies. Remasters and remakes—examples include Resident Evil 4 and the Final Fantasy VII remake—are becoming primary revenue engines. Simultaneously, platform diversification across PC, console, and direct‑to‑consumer web stores, coupled with hybrid monetisation models that blend advertising, in‑app purchases, and subscriptions, are being tested to optimise returns. Expanding intellectual property into music, merchandising, and cloud‑gaming subscriptions further unlocks value from dormant franchises.
- Global games spending reached a record $199.4 billion in 2024, a 3.5% year-over-year increase, with projections stabilizing near $200 billion in 2025.
- The upcoming Nintendo Switch 2 is projected to generate $7–8 billion in upside and reach 103 million units sold by 2030.
- The delay of GTA VI is expected to reduce 2025 console spending by $2.7 billion, creating a strategic window for other publishers to capture holiday market share.
- Publishers are mitigating slower growth by prioritizing high-margin, low-cost strategies such as remasters and remakes, alongside diversifying platforms and hybrid monetization models.
- Emerging markets in the Middle East, Africa, and Southeast Asia, combined with untapped demographic cohorts like 16–24-year-old females and players aged 55+, represent the primary opportunities for future expansion.
+1
NintendoJan 2025

Report94 pages
PC & Console Gaming Report 2025
Global PC and console revenues are expected to grow modestly through 2027, with consoles driving the majority of expansion at an estimated +13 % CAGR while PC revenue rises only in single digits. 2024 saw a plateau for PCs, dominated by free‑to‑play and in‑game monetisation, whereas console sales are set to rebound from 2025 thanks to strong releases such as GTA VI and the launch of Nintendo Switch 2. Player growth remains incremental, with PC players increasing at +2.3 % annually and console players at +3.5 %, driven largely by established franchises rather than breakthrough innovation.
Playtime data confirm that 2024 experienced a 6 % YoY increase, with Pay‑to‑Play titles (e.g., Call of Duty) and free‑to‑play hits (Fortnite, Roblox) accounting for most of the lift. New releases captured only about 9 % of total playtime, underscoring that long‑running series dominate the market. Console audiences remain heavily slate‑dependent: 67 % of new‑release hours come from annual franchises, while PC players show a higher share of non‑annual titles. In the US and Western Europe, non‑annual franchise games contribute a smaller slice of console revenue (≈8–22 %) compared to annual franchises, which drive the bulk of earnings.
Engagement patterns reveal a sharp decline in title diversity on PC and Xbox, with the average number of titles played per player falling 27 % on Steam in the US and up to 34 % in Russia and Brazil. PlayStation, by contrast, shows modest growth in title engagement. Genre preferences are shifting away from Battle Royale toward Adventure and Role‑Playing, reflecting a broader industry trend toward narrative‑rich, long‑form gameplay. Nostalgia and free‑to‑play models continue to sustain short‑term spikes, but long‑term retention hinges on continuous content updates and robust live‑service strategies. New IPs must prioritize originality, polished gameplay loops, and community‑first discovery to overcome the legacy brand advantage and achieve lasting commercial success.
- Console revenue is projected to grow at a 13% CAGR through 2027, significantly outpacing single-digit growth for PC, with major catalysts including the release of GTA VI and the Nintendo Switch 2.
- Market dominance is heavily concentrated in established franchises, as new releases captured only 9% of total playtime in 2024, with annual franchises accounting for 67% of new-release hours on consoles.
- Title diversity is shrinking, evidenced by a 27% decline in the average number of titles played per user on Steam in the US, with drops as high as 34% in markets like Russia and Brazil.
- Player growth remains incremental, with annual increases of 3.5% for console and 2.3% for PC, driven primarily by legacy brands rather than breakthrough innovation.
- Genre preferences are shifting away from Battle Royale toward Adventure and Role-Playing titles, signaling a market trend toward narrative-rich, long-form gameplay.
+1
NewzooJan 2025

Report67 pages
Global Games Market Report 2025
The Global Games Market Report 2025 projects a steady expansion of the worldwide player base to 3.6 billion, with payers rising to 1.6 billion and total revenue reaching $188.8 billion, a 3.4 % increase year‑over‑year. Mobile dominates growth and revenue, contributing $103 billion (55 % of the market) and expanding 4.5 % YoY, while PC and console follow at 3.1 % and 2.5 %. The report notes that average spend per payer is expected to decline slightly through 2028 as the market matures, underscoring the importance of retention, innovative monetization and post‑launch content to sustain growth in an increasingly saturated ecosystem.
Geographically, the Asia‑Pacific region leads with a 4.2 % YoY increase, and North America remains strong for console sales (5.4 %). Key growth drivers include the launch of Nintendo Switch 2, continued success of live‑service titles on PC, and a shift toward direct‑to‑consumer monetization in mobile. Discoverability challenges and content fragmentation are identified as notable hurdles across all platforms.
Single‑player AAA titles released in the February–May window outperform those launched August–November by an average of 34 %, largely due to crowded holiday windows and cannibalization. Early Access titles that transition to full release within 4–9 months generate the highest new‑player lift, while staggered cross‑platform releases capture only about 13 % of the total player base. Player attrition drops sharply in weeks 2–5 and stabilizes after week 12, indicating that longer main‑story content (20–40 hours) and simulation elements help retain players over the long term.
The commercial life of single‑player titles is increasingly driven by post‑launch content, strategic discounting and community engagement rather than initial premium spend. DLC revenue shares evolve over a game’s lifecycle, with genres aligning to specific monetization models and subscriptions gaining influence on long‑term engagement. Post‑launch content is identified as the key determinant of discoverability, retention and profitability across a game’s back catalogue.
Methodologically, the report employs a top‑down, data‑driven model that blends proprietary engagement metrics (Game Performance Monitor, Steam data), public economic indicators and partner insights to forecast platform‑specific player, payer and revenue figures through 2028. The approach excludes taxes, hardware and gambling from revenue calculations and provides detailed platform‑by‑platform forecasts (PC, console, mobile, cloud, VR) alongside analytical tools for market segmentation, genre trends and post‑launch monetization strategies.
- The global games market is projected to reach $188.8 billion in 2025, a 3.4% year-over-year increase, with mobile platforms accounting for 55% of total revenue at $103 billion.
- Mobile gaming remains the primary growth engine with a 4.5% year-over-year expansion, while PC and console segments grow at 3.1% and 2.5% respectively.
- Single-player AAA titles launched between February and May outperform those released in the August–November holiday window by an average of 34% due to reduced market cannibalization.
- Player retention is optimized by 20–40 hour main-story content and simulation elements, with attrition rates stabilizing significantly after the 12-week mark.
- Early Access titles achieve the highest new-player lift when transitioning to a full release within a 4–9 month window.
NewzooJan 2025
Report39 pages
State of the Game Industry
The survey of more than 3,000 global developers in 2025 reveals a gaming industry grappling with persistent instability while making modest progress on diversity. Layoffs have risen, with one‑tenth of respondents reporting job losses in the past year and 58 % worried about future cuts. Women and non‑binary developers now account for 32 % of the workforce, up from 29 % in 2024, and LGBTQ+ representation reached 24 %, yet white males still dominate at 66 %. Revenue pressures and market shifts continue to drive restructuring, underscoring the sector’s vulnerability.
Generative AI has transitioned from a niche experiment to an integral part of many studios, with 36 % of developers using it personally and 52 % reporting company‑wide adoption. However, enthusiasm has cooled: only nine percent of companies plan to expand AI use, and negative perceptions have climbed to 30 % from 21 %. Ethical concerns, intellectual‑property risks, and fears of job displacement now affect more than half of respondents. Internal AI policies have expanded to 64 % of studios, and optional use has become more common, though a small minority mandate AI tools.
Live‑service development remains polarised. While 42 % of studios already produce live titles, only 13 % intend to launch one next year. AAA developers are more inclined (33 %) due to potential financial upside and sustained player engagement, yet worries about market saturation, creative fatigue, predatory monetization, and burnout persist. Media adaptations interest 36 % of AAA studios, whereas internal pitch activity has fallen. Self‑funding remains the dominant financing method (56 %), though success rates vary across funding models.
Work‑hour patterns signal growing strain: the share of developers working over 50 hours a week has risen from 8 % to 13 %, and half of respondents now view excess hours as problematic. Union support remains robust at 69 %, with 58 % advocating industry unionisation, yet only 22 % have discussed it in the past year. These findings illustrate a sector negotiating between rapid technological change, creative ambition, and labour‑market pressures across diverse geographic regions and studio sizes.
- Job instability is widespread, with 10% of developers experiencing layoffs in the past year and 58% expressing concern over future job security.
- Generative AI adoption is high, with 52% of studios using it company-wide, yet negative sentiment has risen to 30% due to ethical, IP, and displacement concerns.
- Work-life balance is deteriorating, as the proportion of developers working over 50 hours per week increased from 8% to 13%, with half of the workforce viewing these hours as problematic.
- Live-service development is cooling, with only 13% of studios planning to launch a new live title next year despite 42% currently maintaining existing ones.
- Workforce diversity is showing modest gains, with women and non-binary developers rising to 32% of the industry and LGBTQ+ representation reaching 24%.
+1
GDCJan 2025

Report20 pages
Match-3 Genre Snapshot Report: May 2021
The document presents a comprehensive analysis of the mobile match‑3 puzzle segment for Q1 2021, focusing on revenue performance, genre characteristics, and player motivations. It identifies the top five match‑3 titles—Candy Crush Saga, Homescapes, Project Makeover, Gardenscapes, and Toon Blast—detailing their market share changes, revenue per download (Rev/DL), and year‑over‑year growth. Candy Crush Saga leads with a 16.74% share and a Rev/DL of $11.27, while Project Makeover shows the strongest growth at 10.57% share and a Rev/DL of $45.51, reflecting its premium monetization strategy.
The analysis breaks down genre features, noting that Royal Match and Project Makeover exemplify modern match‑3 design: fast‑paced gameplay, quick animations, and a progression system tied to home or makeover themes. Monetization models emphasize consumable boosters, lives, and continue options, with special events such as guilds, recurring tournaments, and exclusive levels driving engagement. The document also highlights unique mechanics—bonus “no‑fail” levels, mystery boxes, and avatar customization—that differentiate titles within the subgenre.
Player motivation data from a US sample classify drivers into escapism, mastery, social interaction, and management. Match‑3 games score high on mastery (completing milestones) and escapism, while social competition scores lower. The report’s methodology relies on GameRefinery’s SaaS dashboard, aggregating download and revenue metrics across the US market for Q1 2021. Overall, the document underscores that successful match‑3 titles combine rapid core loops with layered progression and event systems to sustain high monetization rates.
- Candy Crush Saga remains the market leader with a 16.74% share and a revenue per download (Rev/DL) of $11.27 as of Q1 2021.
- Project Makeover demonstrates the most aggressive growth in the sector, capturing a 10.57% market share with a high-premium monetization strategy yielding a $45.51 Rev/DL.
- Modern match-3 success is driven by fast-paced core loops, quick animations, and progression systems integrated with home or makeover themes, as seen in titles like Royal Match and Project Makeover.
- Monetization in the genre relies heavily on consumable boosters, lives, continue options, and recurring engagement events like guilds and tournaments.
- Player motivation data indicates that match-3 users are primarily driven by mastery of milestones and escapism, while social competition remains a lower priority.
+1
GameRefineryJan 2025
Report46 pages
Japan Game Market Insights 2025
The analysis demonstrates that Japan’s mobile gaming sector has reached a mature equilibrium, with download volumes stabilising after 2020 while in‑app purchase (IAP) revenue continues to grow, largely driven by high‑spending iOS users. Domestic publishers hold a dominant position in downloads—capturing roughly one‑third of the market—and command more than half of total IAP revenue, underscoring Japan’s robust monetisation models and loyal consumer base. Genre preferences have shifted toward strategy titles such as Pokémon TCG Pocket and SD Gundam G Generation ETERNAL, alongside puzzle games that now lead download charts.
Live‑ops and event‑driven monetisation prove highly effective, as illustrated by Last War: Survival’s H1 2025 performance. Aggressive daily offers and themed events produced a 2.7‑fold increase in downloads and significant revenue spikes during campaigns like Double Joy, confirming that adaptive event strategies resonate with Japanese players. Anime‑style IPs maintain a commanding presence, accounting for 42 % of in‑app purchase revenue from January to July 2025. Legacy franchises—Monster Strike, Fate/Grand Order, Umamusume—continue to perform strongly, while new titles such as Shadowverse: Worlds Beyond and Honkai: Star Rail expand the ecosystem, illustrating the enduring commercial relevance of anime IP.
Digital advertising remains tightly coupled with gaming, with mobile action/strategy titles consuming 63 % of ad spend in H1 2025. LINE dominates the channel landscape, delivering approximately 40 billion impressions and over 80 % of mobile ad exposure. Cross‑IP collaborations and event‑driven campaigns sustain long‑term monetisation, reinforcing gaming’s role as a core growth driver for digital advertising in Japan. Overall, Japanese publishers retain global leadership through strong IP‑driven franchises across PC, console, and mobile platforms, with culturally resonant engagement and targeted advertising underpinning sustained revenue growth. Sensor Tower’s comprehensive analytics platform provides the critical insights that enable stakeholders to navigate this mature yet dynamic market.
- Domestic publishers maintain a dominant market position, capturing roughly one-third of total downloads and over 50% of all in-app purchase (IAP) revenue in Japan.
- Anime-style intellectual property remains the primary revenue driver, accounting for 42% of total IAP revenue between January and July 2025.
- Mobile action and strategy titles accounted for 63% of total digital advertising spend during the first half of 2025.
- The LINE platform is the primary advertising channel in Japan, generating approximately 40 billion impressions and accounting for over 80% of mobile ad exposure.
- Live-ops and event-driven strategies are highly effective, evidenced by 'Last War: Survival' achieving a 2.7-fold increase in downloads during H1 2025 through aggressive daily offers and themed campaigns.
+1
Sensor TowerJan 2025
Report37 pages
UK Interactive Entertainment Japan Market Report 2025
The report examines Japan’s interactive entertainment market for 2025, aiming to guide UK game developers and publishers in entering or expanding within a culturally distinct yet lucrative region. Japan accounts for only 2.2 % of the global player base but generates 9.1 % of worldwide game revenue, underscoring high per‑player spend—$223 in Japan versus $145 in the UK. The PC and console segment, excluding mobile and Nintendo platforms, represents a $2.5–3.0 billion opportunity.
Key market dynamics include an older player demographic than the US and Europe, a strong preference for single‑player role‑playing games with deep narratives, and a dominance of domestic publishers—70 % of console hardware sales are controlled by Japanese firms. Nintendo’s presence is particularly pronounced, while sports titles remain marginal. Revenue growth has been robust, with PC revenue rising 16.2 % YoY in 2024 versus a global 4.4 % increase, though the pace is expected to decelerate as the Japanese yen weakens against the dollar.
Methodologically, insights derive from Newzoo’s flagship global gamer study and proprietary market intelligence tools, sampling 73 000 gamers across PC and console platforms. The analysis covers player overlap, retention, and engagement metrics (DAU/MAU), and includes forecasted growth through 2027. The report concludes that strategic localization—emphasizing narrative depth, fantasy and science‑fiction themes, and solo play experiences—will be critical for success in Japan’s competitive landscape.
- Japan generates 9.1% of global game revenue from only 2.2% of the global player base, with an average per-player spend of $223 compared to $145 in the UK.
- The PC and console segment, excluding mobile and Nintendo platforms, represents a $2.5–3.0 billion market opportunity for developers.
- PC gaming revenue in Japan grew 16.2% year-over-year in 2024, significantly outpacing the 4.4% global growth rate, though this momentum faces headwinds from a weakening yen.
- Domestic firms dominate the market, controlling 70% of console hardware sales, with Nintendo maintaining a particularly strong presence.
- Successful market entry requires prioritizing single-player role-playing games featuring deep narratives, fantasy, or science-fiction themes.
+1
UK Interactive EntertainmentJan 2025
Report23 pages
Mobile Gaming Benchmarks 2025
Mobile Gaming Benchmarks 2025 delivers a comprehensive, data‑driven reference for developers seeking to refine acquisition, monetization and content strategies across the global mobile market. The study aggregates 11 600 titles spanning nine regions, two platforms (iOS and Android), and 16 genres, capturing roughly 1.48 billion monthly active users and an average of 4.7 regions per game. By offering global, regional and genre‑specific metrics—retention at D1, D7 and D28; playtime; session length; and session count—the report positions retention as the pivotal driver of long‑term engagement, revenue, and user acquisition return on investment.
Key findings reveal a pronounced shift toward bite‑size play. Average session lengths have fallen, with top‑tier games averaging 8–9 minutes and the median tier around 5–6 minutes. Midcore titles generate the highest daily session counts (six to seven sessions per day), while Android users exhibit higher session frequency than iOS, reflecting the dominance of casual titles on that platform. These trends underscore the necessity for design that supports rapid, repeated engagement loops.
The benchmark framework is underpinned by GameAnalytics’ processing of over 27 billion daily events across 100,000 active games. Percentile data for playtime (98 % quantile), session length (97 % quantile) and new‑user acquisition are segmented by genre, platform, region and spending tier. Real‑time analytics, LiveOps tools and customizable reporting enable studios to scale optimization efforts, tailoring strategies to the nuanced performance profiles identified in the 2025 benchmarks.
- Retention is the primary driver of long-term engagement, revenue, and user acquisition ROI across the 11,600 titles analyzed.
- Average session lengths have decreased, with top-tier games averaging 8–9 minutes and median-tier games averaging 5–6 minutes.
- Midcore titles lead in engagement frequency, generating six to seven sessions per day.
- Android users exhibit higher session frequency than iOS users, a trend attributed to the prevalence of casual titles on the Android platform.
- The 2025 benchmark data is derived from 1.48 billion monthly active users and the processing of 27 billion daily events across 100,000 active games.
+1
GameAnalyticsJan 2025
Report40 pages
The Israeli Mobile Game Market Report (2022)
The Israeli mobile game market reached approximately $9 billion in 2021, driven by more than 200 companies and 14,000 employees. Casual, puzzle, and hyper‑casual titles now represent about one‑third of global mobile game advertising spend, a share amplified by COVID‑19‑induced growth in user acquisition and in‑app purchases. Israel has emerged as a pivotal source of high‑volume advertisers, particularly for action, strategy, and simulation games across iOS and Android platforms. Leading studios—Playtika, Plarium, Moon Active, and Crazy Labs—have scaled to global prominence, with their games ranking among the top 20 Israeli titles by ad spend and contributing substantially to worldwide revenue.
Two flagship games illustrate this trend. RAID: Shadow Legends, launched in 2019, has exceeded 50 million downloads and generated roughly $700 million, with the United States accounting for 70 % of revenue and 40 % of downloads. Its 2022 advertising strategy deployed an average of 1,100 creatives daily, primarily on Google Ads and Facebook, with a heavier focus on Android. Coin Master, released in 2010 and revitalized in 2019, earned about $1.3 billion in 2021—over half from the U.S.—and averaged 2,500 creatives per day in 2022. The campaign concentrated on video formats across Google Ads for both iOS and Android, reflecting the dominance of video in mobile‑game advertising.
Regional analysis shows distinct creative preferences. In the U.S., live‑action, KOL‑driven strategy tips dominate; Japanese campaigns emphasize character art and voice to drive gacha revenue; Korean ads showcase advanced graphics through extended gameplay footage. Across genres, short, engaging videos that spotlight core mechanics or narrative hooks are rising in popularity. Hyper‑casual ads now conclude on success rather than failure, strategy titles incorporate casual puzzles to widen appeal, RPGs employ influencer‑style clips, and simulation games use sympathetic drama with accessible gameplay to attract female players. These findings underscore a highly segmented, video‑centric advertising ecosystem that aligns creative content with regional tastes and genre conventions.
- The Israeli mobile game market reached approximately $9 billion in 2021, supported by over 200 companies and 14,000 employees.
- Flagship titles demonstrate massive scale: Coin Master generated $1.3 billion in 2021 with 2,500 daily creatives, while RAID: Shadow Legends surpassed $700 million in revenue and 50 million downloads.
- Casual, puzzle, and hyper-casual games now account for one-third of global mobile game advertising spend, bolstered by pandemic-era growth in user acquisition.
- Leading Israeli studios including Playtika, Plarium, Moon Active, and Crazy Labs have established themselves as global leaders in high-volume advertising across action, strategy, and simulation genres.
- Mobile advertising is heavily video-centric, with top-performing campaigns utilizing thousands of daily creatives across platforms like Google Ads and Facebook.
+1
SocialPetaJan 2025
Report10 pages
Hyper-Casual Games – Industry Snapshot 2020
The snapshot presents a quantitative overview of the hyper‑casual mobile game sector for 2020, drawing on data from over 140 000 titles and more than 2 billion monthly sessions. The analysis disaggregates key performance indicators—day‑one and day‑seven retention, average playtime, ARPPU, ARPDAU, and conversion rates—across four dominant sub‑genres: timing, traversal, physics, and shooting. Timing games achieve the highest day‑one retention (≈44 %) but lower playtime, while traversal titles show slightly higher day‑seven retention (≈41 %). Average revenue per paying user ranges from $18 for physics games to $42 for timing titles, with conversion rates consistently below 1 % across all sub‑genres.
Geographically, France and Germany dominate early retention metrics (≈49 % day‑one), whereas Japan leads in average daily playtime (63 minutes). The United States, China, and South Korea exhibit moderate retention but lower playtime. In 2020, the most successful titles—such as “High Heels!” (traversal) and “Slap Kings” (timing)—combined high download volumes with strong engagement scores, reflecting the importance of low production effort and rapid iteration.
Methodologically, the report aggregates network data from GameIntel’s Explorer platform, employing a cross‑title average approach to benchmark performance. The findings underscore that hyper‑casual games thrive on brevity, simplicity, and forgiving mechanics; developers are advised to monitor day‑one retention thresholds (≈40 %) early in development and prioritize high‑impact, low‑effort optimizations to maximize user acquisition and monetization.
- Hyper-casual developers should target a day-one retention threshold of approximately 40% early in the development cycle to ensure viability.
- Timing games lead the sector in day-one retention at roughly 44%, while traversal titles demonstrate superior long-term engagement with day-seven retention near 41%.
- Monetization performance varies significantly by sub-genre, with ARPPU ranging from $18 for physics-based games to $42 for timing titles, despite conversion rates remaining consistently below 1%.
- Geographic performance metrics show France and Germany leading in day-one retention at 49%, while Japan records the highest average daily playtime at 63 minutes.
- Successful 2020 titles like 'High Heels!' and 'Slap Kings' validate a development strategy centered on low production effort, rapid iteration, and simple, forgiving mechanics.
+2
GameIntelJan 2025
Report41 pages
Mobile Growth and Monetization Report 2023
The report establishes that mobile game monetization is most effective when focused on early‑stage conversion and strategic ad placement. Analysis of 31 billion in‑app purchase events shows that 77 % of players who convert do so within the first two weeks, with currencies and limited‑time sales accounting for 22–23 % and 15–20 % of revenue respectively. Pricing the first purchase between $1 and $5 maximizes conversion efficiency, while targeting tier‑2 markets and deploying offerwalls can further enhance retention.
Rewarded‑ad data, derived from 31 billion monthly impressions and 158 million installs, identifies high‑engagement placements between levels, in the IAP store, and lobby screens. Extra‑reward, currency, and gacha offers drive the greatest engagement. Offerwalls contribute roughly 33 % of total ad revenue, delivering about $4.68 per converted user; multi‑reward offers generate 60–82 % of conversions and can yield up to $68 per completion. These insights suggest that placing high‑visibility rewarded ads and integrating offerwalls can simultaneously boost retention and monetization.
Complementary tactics such as custom store pages further improve player engagement. Offerwall conversions can increase day‑7 to day‑120 retention by up to fivefold, especially for high‑engagement segments. Custom store pages allow developers to align in‑game messaging with ad creatives, reducing resource costs and enhancing conversion rates. Targeting genre‑specific markets—sports in Japan or trivia in South Korea—can lift click‑through rates above tier‑2 averages, underscoring the importance of data‑driven audience and creative optimization.
Overall, the findings emphasize a focused strategy: early conversion pricing, strategic rewarded‑ad placement, offerwall integration, and tailored store experiences. These combined tactics deliver measurable gains in retention, revenue, and campaign efficiency across iOS and Google Play platforms worldwide.
- 77% of players who make in-app purchases convert within the first two weeks, with the highest conversion efficiency achieved by pricing initial offers between $1 and $5.
- Offerwalls contribute approximately 33% of total ad revenue and can increase day-7 to day-120 player retention by up to fivefold.
- Multi-reward offerwall campaigns generate 60–82% of conversions and can yield up to $68 per completion, while delivering an average of $4.68 per converted user.
- In-app currencies account for 22–23% of revenue, while limited-time sales contribute 15–20%.
- High-engagement rewarded ad placements are most effective when positioned between game levels, within the IAP store, or on lobby screens.
+2
UnityJan 2025
Report40 pages
The Gaming App Insights Report: 2025 Edition
The 2025 Gaming App Insights Report presents a resilient mobile gaming market that rebounded strongly in 2024, projecting global revenue of $126.1 billion for 2025 and a 49% share of total gaming revenue, eclipsing console (28%) and PC (23%). AI‑driven personalization, dynamic monetization models, and cross‑platform play emerge as key drivers of higher retention, session length, and in‑app spending, particularly within battle royale and strategy genres. New acquisition channels—TikTok, connected TV, and influencer marketing—are reshaping player discovery, while studios that invest in AI for predictive churn mitigation and long‑term relationship building are positioned to capture the largest growth opportunities, especially as mobile gaming expands into LATAM and MENA regions.
Privacy compliance shows modest improvement, with global ATT opt‑in rates rising to 37.9 % in Q1 2025; arcade titles lead the surge (42.4 → 59.3 %). Regional gains are strongest in Indonesia (58.6 %) and Malaysia (51.9 %), whereas markets such as the UAE, Japan, Saudi Arabia, and the Philippines experienced slight declines. Despite these gains, compliance remains uneven across genres and geographies.
Advertising performance improved in 2024: installs per mille increased from 8.1 to 8.86, click‑through rates rose from 7 % to 9 %, and median cost per install fell slightly (0.38 → 0.36 USD). Median cost per mille dropped to $3.41, indicating more efficient ad spend. However, revenue‑per‑user metrics declined overall—ARPM fell across most categories and ARPMAU dropped from $0.31 to $0.28—though casino and strategy games bucked the trend with higher monetization.
The report concludes that mobile gaming’s next growth wave will hinge on AI‑driven, culturally tailored experimentation and hyper‑personalized user journeys. Precise targeting—through dynamic difficulty, hybrid monetization, and live events—combined with community‑building tactics drives higher lifetime value. Teams that leverage cross‑platform measurement and analytics to iterate on data‑driven decisions will be best positioned to scale and shape the future of mobile gaming.
- Mobile gaming is projected to generate $126.1 billion in 2025, capturing 49% of total global gaming revenue compared to console (28%) and PC (23%).
- Global ATT opt-in rates reached 37.9% in Q1 2025, with arcade titles showing significant growth from 42.4% to 59.3%.
- Advertising efficiency improved in 2024 as median cost per install fell from $0.38 to $0.36, while click-through rates increased from 7% to 9%.
- Despite improved ad performance, monetization metrics declined, with average revenue per monthly active user (ARPMAU) falling from $0.31 to $0.28.
- Growth in mobile gaming is shifting toward LATAM and MENA regions, with Indonesia (58.6%) and Malaysia (51.9%) leading in privacy compliance opt-in rates.
+2
AdjustJan 2025
Report19 pages
Hyper-Casual 9 Games Benchmark Report: Q3 2022
The report presents a quantitative assessment of hyper‑casual mobile games for the third quarter of 2022, focusing on acquisition costs, retention performance, and geographic distribution. It identifies a narrowing cost‑per‑install (CPI) gap between Android and iOS, now at 10 cents compared with an average of 15 cents over the previous four years, suggesting intensified competition on Android. Retention benchmarks reveal a consistent advantage for iOS across all performance tiers: top‑tier games achieve 51 % day‑1 and 22 % day‑7 retention versus 42 % and 16 % on Android; top‑25 games show 33 %/9 % versus 26 %/5 %; median titles record 25 %/6 % against 19 %/3 %. These figures illustrate a pronounced disparity between platforms, with iOS retaining users more effectively at every level.
Geographically, the analysis lists leading markets by player volume and revenue potential. The United States, Japan, South Korea, Brazil, the United Kingdom, Canada, Germany, India, France, and Indonesia appear repeatedly as key regions, with Japan and South Korea consistently ranking among the top three. The data imply that hyper‑casual titles should prioritize these territories for user acquisition and monetization strategies.
Methodologically, the study aggregates data from over 100 k games tracked by GameAnalytics, a leading analytics provider that serves one‑third of global mobile players. The benchmark draws on CPI figures, retention rates, and regional player counts to deliver actionable insights for developers and publishers seeking to optimize performance in the hyper‑casual segment during Q3 2022.
- iOS maintains a significant retention advantage over Android across all performance tiers, with top-tier iOS games achieving 51% day-1 and 22% day-7 retention compared to 42% and 16% on Android.
- The cost-per-install (CPI) gap between Android and iOS has narrowed to 10 cents, down from a four-year average of 15 cents, indicating intensified competition on the Android platform.
- Median hyper-casual titles show a clear performance disparity between platforms, with iOS recording 25% day-1 and 6% day-7 retention versus 19% and 3% on Android.
- Japan and South Korea consistently rank among the top three global markets for both player volume and revenue potential in the hyper-casual segment.
- Key regions for user acquisition and monetization strategies include the United States, Japan, South Korea, Brazil, the United Kingdom, Canada, Germany, India, France, and Indonesia.
TenjinJan 2025
Report66 pages
How UGC, AI, & Cloud Are Transforming Gaming Report
The report argues that user‑generated content (UGC), artificial intelligence (AI) and cloud gaming are reshaping the industry by lowering entry barriers, democratizing creation and expanding cross‑platform reach. Data show that Gen Alpha and Gen Z spend a majority of their daily gaming time, with UGC platforms such as Roblox attracting 85 million active users and cloud‑gaming subscribers rising from 62.5 million to nearly 396 million in four years. AI‑driven tools are projected to generate $4.2 B by 2029, while cloud‑gaming revenue grew from $1.1 B in 2020 to $6.9 B in 2024 and is expected to reach $18.7 B by 2027.
Indie developers benefit from cloud infrastructure that allows anyone to play AAA titles and AI engines such as Unity Muse or Unreal Engine that reduce development costs. Indie releases on Steam generated $4 B in 2024, matching AAA revenue streams, and UGC has extended the life of titles like Fortnite and Roblox, boosting retention by up to 10 % in some cases. However, quality control, cross‑platform compatibility and monetization remain challenges; dedicated mod QA teams, “mod hub” interfaces and transparent pricing are recommended to sustain high‑quality ecosystems.
Player surveys reveal mixed feelings about AI, with 54 % seeing more benefits than drawbacks but 52 % feeling nervous. Creators view AI as a productivity aid, with 83 % adopting it and reporting improved content quality (66 %) and asset variation speed (70 %). Cloud gaming is praised for cost savings (47 %) and accessibility (44 %), yet latency (76 %) and bandwidth (68 %) issues persist, underscoring the need for edge computing, AI‑based compression and better economic models.
The analysis projects cloud gaming as the dominant play model within a decade, initially targeting B2B use cases before expanding to consumers. Advances in 5G and internet infrastructure are expected to unlock low‑latency streaming, enabling cross‑platform play and the convergence of AI, UGC and live‑service models into socially connected gaming ecosystems. The report concludes that while continuous evolution and community engagement will drive growth, depth in specific genres may ultimately define the next wave of innovation.
- Cloud gaming revenue grew from $1.1 billion in 2020 to $6.9 billion in 2024, with projections reaching $18.7 billion by 2027 and a trajectory to become the dominant play model within a decade.
- Cloud gaming subscribers have surged from 62.5 million to nearly 396 million over the last four years, while AI-driven development tools are projected to generate $4.2 billion by 2029.
- Indie developers are increasingly competitive, with indie releases on Steam generating $4 billion in 2024, a figure that now matches AAA revenue streams.
- UGC platforms like Roblox have reached 85 million active users, with UGC integration in titles like Fortnite and Roblox boosting player retention by up to 10%.
- While 83% of creators have adopted AI to improve asset variation speed (70%) and content quality (66%), player sentiment remains divided, with 52% expressing nervousness regarding the technology.
+1
Room 8 GroupJan 2025
Report88 pages
Genre and Great Games: Understanding Audiences and Designing Better Mobile Games
The study demonstrates that genre is the primary factor influencing mobile game adoption, with puzzle and matching titles dominating in North America and East Asia, while card‑casino games lead elsewhere. Within these markets, strategy players—comprising 12–26 % of the player base—exhibit high retention when titles incorporate live events, achievements, and daily rewards. Their spending patterns favor direct purchases over random loot boxes, especially in Japan, and they tolerate rewarded ads only when infrequent and longer. Strategy games also deliver the highest lifetime value, largely through aggressive use of battle passes (present in 92 % of top titles) and character or gear upgrades.
Role‑playing games attract players motivated by accomplishment, collection, and social interaction; churn is driven by repetitive gameplay and aggressive monetization. Successful RPGs mitigate this through frequent live events, multiple leveling paths, robust guild systems, and a balanced mix of loot boxes and bulk‑discount options. Monetization sensitivity varies regionally: U.S. players accept rewarded videos when they provide tangible benefits, whereas Korean and Japanese audiences are more tolerant of longer, character‑centric ads.
Puzzle players skew female (≈70 %) and older (≈60 % aged 35+), favoring short solo sessions for stress relief. Retention gaps stem from boredom and slow progress; top performers address this with live events, diverse level goals, and event currencies. While community engagement is low overall, a majority welcome developer communication and leaderboard features. Hyper‑casual audiences similarly value frequent updates, social cues, and ad‑friendly monetization that avoids pay‑to‑win perceptions.
Across all genres, the analysis identifies key mechanics—battle passes, VIP tiers, guilds, live‑event currencies, and ladder systems—that create recurring revenue streams and community retention. Combining season‑based progression with social collaboration and limited‑time rewards maximizes player lifetime value and monetization potential.
- Strategy games deliver the highest lifetime value in mobile gaming, driven by battle passes—which are present in 92% of top-performing titles—and character or gear upgrades.
- Strategy players, who make up 12–26% of the mobile base, prefer direct purchases over loot boxes and exhibit high retention when games feature live events, achievements, and daily rewards.
- Puzzle games, which dominate North American and East Asian markets, attract a demographic that is approximately 70% female and 60% aged 35 or older, favoring short sessions for stress relief.
- RPG player churn is primarily driven by repetitive gameplay and aggressive monetization, which successful titles mitigate through multiple leveling paths, guild systems, and a mix of loot boxes and bulk-discount options.
- Monetization sensitivity varies by region: U.S. players prefer rewarded videos with tangible benefits, while Japanese and Korean audiences show higher tolerance for longer, character-centric advertisements.
+1
Facebook GamingJan 2025