The 2012 UK Games Market report provides a comprehensive analysis of the gaming landscape in the United Kingdom, focusing on player demographics, platform usage, and evolving business models. The primary objective is to offer strategic insights into market growth by synthesizing consumer, transactional, and financial data. The analysis highlights a robust gaming environment, identifying 33.6 million active gamers in the UK—a 9% year-on-year increase—with 64% of these individuals engaging in paid gaming activities.
The research utilizes a proprietary Screen Segmentation Model to categorize gaming behavior across four primary screens: computer, console, personal, and floating (mobile) devices. Findings indicate that while console and PC gaming remain dominant, accounting for 43% of total daily game time, mobile and social gaming are significant drivers of industry expansion. The data reveals that the average UK gamer utilizes 3.9 different platforms, reflecting a highly fragmented and multi-platform consumption habit. Furthermore, the report emphasizes that the industry is shifting toward "games as a service," where free-to-play models necessitate a delicate balance between consumer value and corporate profitability.
Methodologically, the findings are derived from Newzoo’s extensive consumer research, which cross-analyzes over 200 variables across 12 countries. The scope of the report covers the UK market specifically, with comparative benchmarks against broader European and US trends. By tracking key growth indicators—including player counts, time spent, paying users, and total revenue—the analysis concludes that success in the modern market requires publishers to adapt to cross-screen accessibility and implement sophisticated, service-oriented business models to maintain long-term profitability.

Newzoo · 2026

Google · 2026

Newzoo · 2026

Newzoo · 2026

Newzoo · 2026

Newzoo · 2026

Newzoo · 2026
Newzoo · 2026

Deconstructor of Fun · 2026

Newzoo · 2026
Newzoo · 2026
Newzoo · 2026

Aream & Co · 2026
Epyllion · 2026
Aream & Co · 2025
Newzoo · 2025
Epyllion · 2025

Meridian Play · 2025
Newzoo · 2025
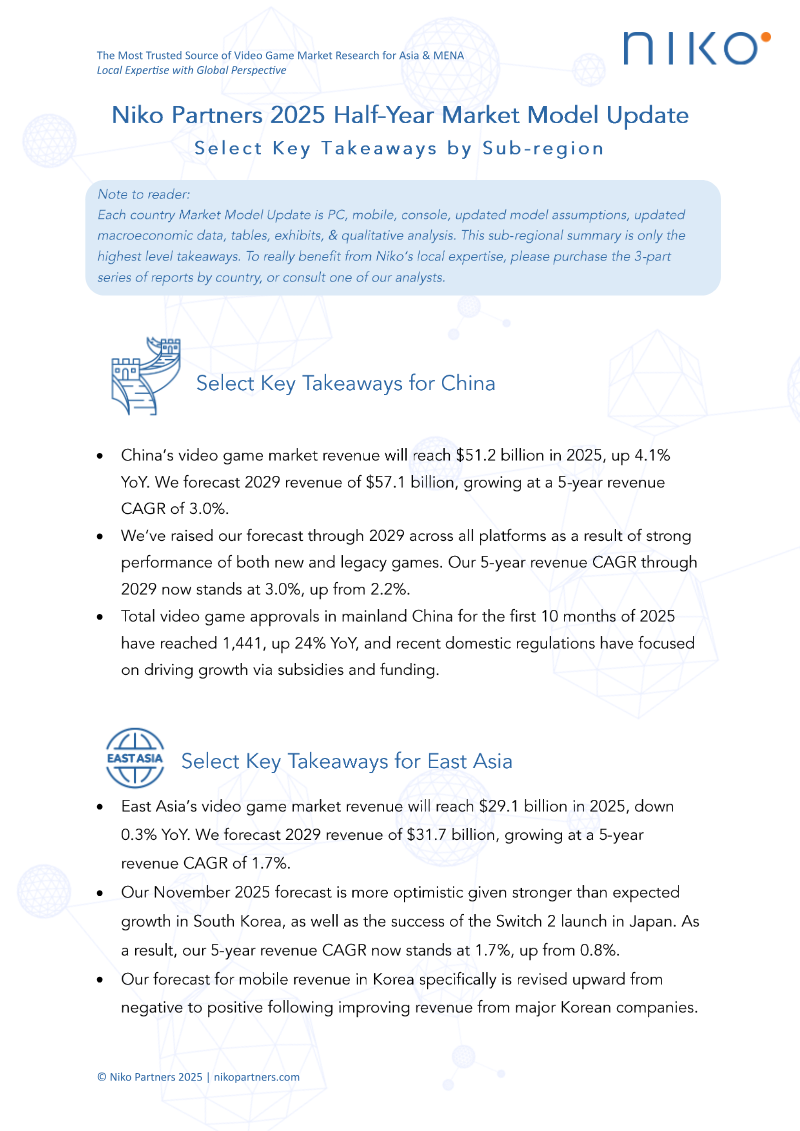
Niko Partners · 2025
Konvoy · 2024
Aldora · 2024
Konvoy · 2023
Newzoo · 2023