VideoPocketGamer.biz
Session: State of the Gaming Industry - Chirag Ambwani, Sensor Tower
9 Feb 202624 min video
Transcript
to kick off the global trend session. I'd like to welcome Shurag from Sensor Tower who's going to be talking about the state of gaming for 2026. So, please welcome Shurag to the stage. Uh, thank you guys for having me here. Uh, I was going to say I'm surprised we're already into 26. I feel like 25 flew. So, hopefully, you know, for the next 20 minutes, I know we have a packed schedule. The plan is to show you guys how we are seeing the game space and ultimately what are some fun takeaways as we go into 26. Uh I think first and foremost let me
start off by saying I mean I feel like every time I come to one of these conferences there's a general feeling that gaming is not doing well. Uh and I say this every time the numbers don't say that. Uh when we look at the game space um g 25 was a massive year for gaming. Just to put some numbers behind it we're looking at 52 billion downloads that have went through the game space. I think we're in a cool position now that we can talk about it from the whole landscape. Uh across Apple, Google, Steam, Xbox, PlayStation, 52 billion. This is a record year that gaming had in 25. And then you sort of look at this on the revenue side. It's even a bigger number. Um 82 billion went through the Apple App Store and the Google Play Store. And just to put that into context, the last time uh we saw that number was in the peak of the pandemic in 21. So gaming is back. uh and for folks I see some people that I seen in the audience this does not include the web store revenue which we are in the process of also including so this number
is even bigger on the mobile side so mobile's doing extremely well and then when we look at this on the PC side 12 billion Steam had another record year just to give you guys a sense like gaming in all aspects is doing really well um however when we take a step back and actually look at this for the different stores this is where things get really interesting Let's focus first on the download side. Um you know one of the big themes if folks had a chance to listen to this session I did maybe two years ago. We had mentioned this theme around more and more developers and publishers are focused on their live titles in the market. It's now sort of been 2 years we're starting to see uh it really impact on the download side where we've seen the Apple App Store and the Google Play Store decline about 6 to 8%. Uh Steam had a had a 12% decline. Part of that was it was just such a big year for Steam last year. Um, but revenue is where things get really interesting, right? We're still seeing over a percent growth on the Apple App Store, which
topped over 50 billion just for the Apple App Store. Uh, 3% on Google. This is a recovery from the last couple years. So, Google is starting to grow again at 30 billion. And then Steam, I mentioned it, it's at 12 billion and a record year for Steam. And we'll have we'll talk through some of the games that really impacted this audiences. I I had a chance to see the last session. I think people were talking about like who is the gaming audience. I mean when we sort of look at who exactly is playing titles. I think this is where things get really interesting and I think why mobile is so much bigger than the console and the PC landscape which is when we look at the console space. It's exactly what we all think a gaming market is. It's males. it's still 35 and above that dominate the PC and the console space. But it's really the mobile side that I want to kind of touch on. Uh we've actually seen the core mobile gamers start having introducing more women into the audience. It's about 30% of folks who are playing now core mobile titles are women, which I think is a great sign
that the mobile space has started to find a way to incorporate the women audience to core hard player games. And then of course casual gaming and hyper casual. This is where women tend to lean more on the gaming side. Now let's talk about this from how many games are actually being launched on these different stores. I had mentioned let's focus on the mobile side first. Uh there was a theme if you uh saw any of the earnings for the ba major publishers like Play Tikka, they had mentioned back in 22 and 23, we want to focus on our live titles and you see that in the data, right? Uh 22 was the big year for the mobile space almost 100,000 games launched in the mobile app store. We've seen this decline and now last year a little under 70,000 games. still healthy, but you can clearly see people and folks are focusing on their live titles in the market for mobile. However, a really different story, right? When you see this drop in the 22 time frame, you see this massive acceleration on the PC side and PC last
year uh just on the Steam ecosystem topped over 20,000 new games. So, it is still a very competitive space, but luckily from the revenue side, as we talked about, it's still a really healthy market for folks who are building really good content. Speaking of competition, I think we all for folks who are game developers, getting to your audience is the hardest part. And I wanted to put some numbers behind it on the ad side. Uh we saw over 12 billion spent on just video ads last year. Ultimately, the the biggest challenge for any game developer is how do you get and retain your audience? And I think marketing has been a big focus area driving over 1 trillion impressions. So again, it's really healthy, but this is the biggest area that we see our customer base having the most struggle with. Uh just to put into perspective, the most competitive space for from an advertising SP standpoint, it's the puzzle space. It is where majority of the revenue comes from mobile. It is where you see the biggest titles launch.
Uh the biggest spender last year should not surprise anyone. It's also a puzzle title. It's a mobile game called Royal Kingdom. I think I saw some Dream Game folks uh doing really well. Uh and then on the PC side, it's our this is now a couple years in a row, but Fortnite is still the dominant spender on the PC side. Uh and now if we actually look at where does the dollars go, this is where I think things get really interesting. When we look at this on the mobile side, majority of the the spend goes to mobile apps. And what we consider mobile apps are companies like AppLoving, Unity. And and this just shows mobile gaming is still extremely uh focused on driving ROI. And ultimately it's the difference between performance marketing and brand marketing. And you can see it just from the data. Mobile is still very performance marketing focused. And then of course you see the big socials, Instagram and Tik Tok really driving a lot of engagement. But when we look at this on the PC side, I think this gets really interesting where you still see YouTube being the dominant. And I think
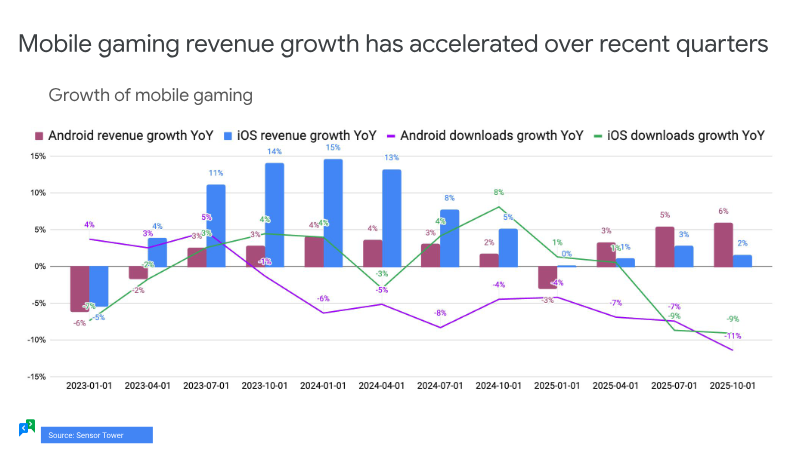
for folks who run u marketing, YouTube's always been known as where the hardcore player has been. And that's where you can you start seeing still a lot of focus from PC console developers on YouTube, but then again, it's Instagram, it's Tik Tok, they're starting to become a bigger part of this ecosystem as well. So now let's go a little bit into uh deep dive into the mobile space specifically. As I mentioned, let's look at downloads. We did see uh this was a record decline on the download side. Part of it is again folks are focused on specifically their live titles on the market. But I think one thing I did also want to highlight, we are seeing weakness specifically from the Asia side. and we'll walk through the numbers, but specifically the Japanese market really is where we're seeing a lot of uh challenges. But again, I think on the revenue side, I think this is a really healthy story on the mobile front. It's 82 billion. As I mentioned, the last time we saw that number was in 21, and this does not include the web store revenue. So, in reality, you can
make a case that uh 24 and 25 were actually higher gaming revenue years than the pandemic, which I think is a great sign for the mobile space. As I mentioned, let's actually look at how does this look on the geographic breakdown. Uh, as I mentioned, this is now three years in a row that Japan has been on this uh left-hand side. Uh, it's the only country that's had a minus5 in terms of both the downloads and on the revenue side. Um, there's a couple reasons for it. I would say the biggest reason is Japan still has quite a concentration risk in RPGs specifically. it they drive majority of the downloads and the revenue for that ecosystem. I think there's a there's a big opportunity for western publishers because casual is starting to grow in Japan but still uh the vast majority of downloads is coming from RPG space. China's another interesting one. Uh I have some fun slides on China specifically but on of course we don't
have the nonapp store view but you know we are seeing about a 15% decline on the download side but again the revenues are pretty healthy minus 2%. Um the US still the biggest games market uh we've saw a slight growth about a a percent uh on the revenue side and then similarly minus 10% on the download side. And then of course we are in Europe. So let's talk about the European story. Um one thing that's been really interesting and I had mentioned this in a previous presentation I had done is when we have conversations with game developers, we've always used to have conversations is like how do we do our strategy in the west where a lot of that strategy would come from the US market. We're now starting to see more and more of our customers actually doing strategies for individual markets in the west like the European markets. And you you're starting to see that on the num numbers side, right? I mean, the UK um it saw over 10% uh growth on the mobile side in revenue. Again, I think this
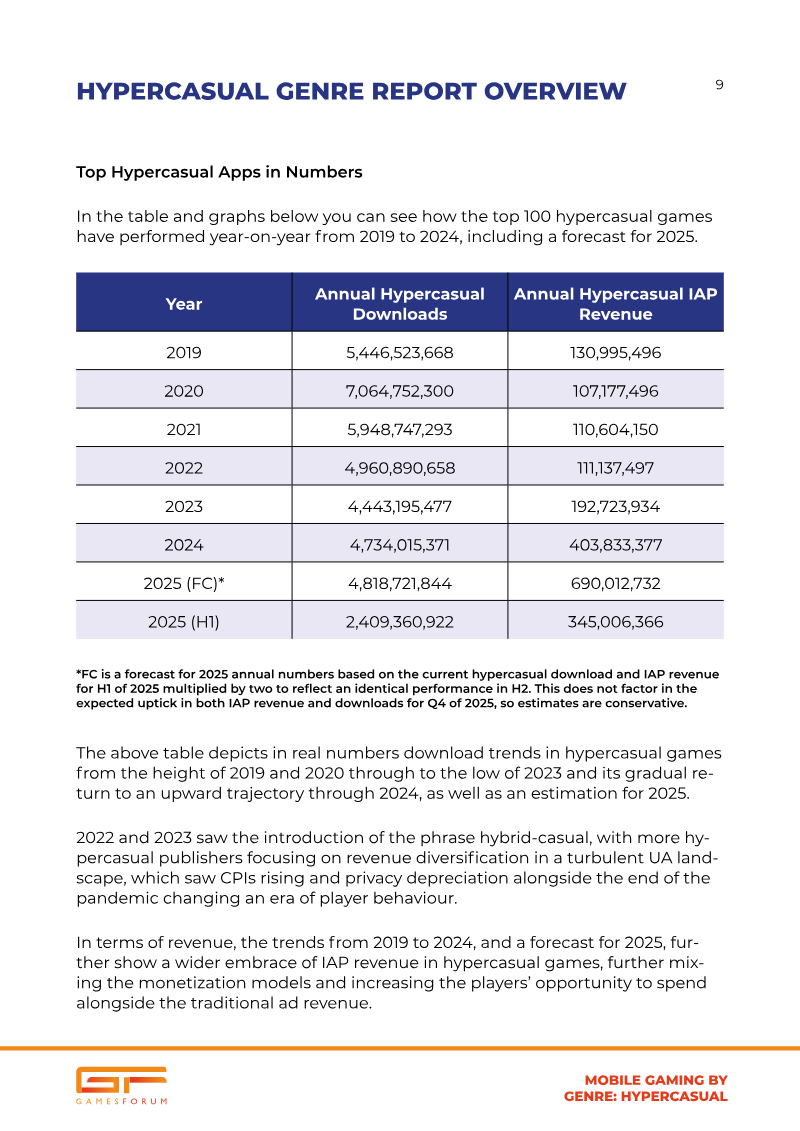
goes back to the story on decoupling countries and having a strategy at a country level versus just looking at the west versus the east. Uh similarly, France had a really good year um over close to almost 8% in revenues. And then some of the other bigger markets like Germany. Another fun one to look at is Canada. Uh, selfishly I am Canadian, but it's been the big soft launch country market for a a while. I think it started to get really expensive, but we're starting to see more soft launches going back into Canada. Maybe this is a sign that uh things are looking out for the western markets again. Uh, and now when we look at this kind of like the segments of the mobile gaming space, this is where things get really interesting. Hybrid casual, we've been talking about this for the last 5 years. uh the record growth for them over a 100 million in revenue that the hybrid casual space drove uh last year uh lot of big titles the likes of take 2's titles and some of their u dominant titles starting to become in the top 50
uh hyper casual uh still kicking uh still doing well I think it's it's an interesting year it hasn't been on this slide for a while uh but again I want to paint the story on the midcore side uh it had a another big negative year and again as I mentioned This is where a lot of the weakness from Asia, Japan, uh, China is really starting to show. Um, and now when we look at who are the top publishers and top games in the market, this is where things get really interesting. Uh, I mean, everyone knows about Roblox. I feel like I don't have to talk a lot about it. They are in a league of their own. Uh, I would I would also say I don't consider them games anymore. I I feel like I might start removing this off the given they are a platform. I think the story is more let's look at the other nine. Um this is a fun view. A lot of people ask me what would if I was a western developer what would I be nervous about? Uh I think this slide shows it which is five of the top nine are eastern publishers. Uh the
APAC market now dominates the west. Um the just to point out a couple last war survival uh white out survival sentry games. uh the western publishers or eastern publishers are doing extremely well in the west. Um these are games that have launched only about a year ago and already have grossed a billion which should hopefully give uh a sign to anyone who's trying to launch mobile titles. There's still a massive opportunity for good if you're launching good titles on the market. Um and then again there are some legacy ones. You still see Candy Candy here being in the top 10. Uh Coin Master which is now over 5 years old. So again, the mobile gaming market is really healthy. Um, and now who are the publishers? Uh, again, it's similar to Roblox. Tencent dominates. It's the only one that's driving over 300 million downloads a year and over close to 8 billion in revenue. Um, but I think this is where things get really interesting. Of course, you see Take 2's acquisition of
Zinga that doesn't get talked about a lot, but Take 2 is doing really well on the mobile side, partially because of their focus on hyper hybrid casual. Um, this is the first time that Supercell is back in the top five. If you've been paying attention, Clash and a lot of the major have had record years. I think this the stat is the last time Clash made as much money last month was when it was back in 2012. So, it's been a decade since Clash has been on the top of the leaderboard. And then you start seeing the new players. You see Sentry Games. Um, you're seeing the likes of Dream Games with Royal Match, uh, Scoply, Play Tikka. Uh, again, it's a it's a really interesting sign that it's a lot of Western and it's a lot of eastern publishers now battling. Again, I think Live Ops has been a really big focus. Part of the reason being people are focused on their live titles in the market. And I think this is a fun view for folks, which is what we're seeing based off our we track essentially the the space for the top
100 games on the space. What's been really interesting is the amount of new unique events that are coming out in a game. So these are events that we've never seen before. It was a record year last year. 12% of these events are brand new. Again, it's just showing that the companies that have their live titles in the market are really focused on building new content, which is why I think you're seeing the life cycle of these games starting to grow and actually take share from the smaller developers is because they're very much focused on uh providing the best uh content for their for their players. And again, you can kind of see this record number of events. You're starting to see now the average mobile game has over 30 events per per month which is a record high and just a sign that more to come for the mobile space in terms of live ops. Uh one thing for the casual folks in the audience uh casual is having a retention problem. Again part of that could be uh there's been a lot of focus on casual and another reason could be the top five
casual games have been the top five casual games for the last five years. It's Candy Crush. It's Royal Match. Um, this is where I think there's an opportunity here where maybe there's a opportunity for new developers to try to really uh release new content, but C casuals had now a two-year decline uh on as a category from a retention standpoint. Another thing is specifically on ads and where folks are putting their dollars. I I had mentioned the the thing that we get asked the most from our customer bases like how do we get to the user and I think this is a really interesting and telling sign which is we've seen just the dollars have shifted on where their ads uh are going. We saw last year a lot of focus specifically on image ads and we've actually seen that change now where more and more budgets are going to video which are traditionally more expensive but they tend to also bring a much more engaged audience. Similarly,
we're seeing a pretty big record growth. Almost roughly 15% of ads now going to rewarded video ads. And again, just a sign, how do you get players to see and ultimately play your titles? So, these more expensive uh ad placements are starting to see bigger growth than uh last year. And then again, this is a really fun one. Uh I was I was telling some folks I was at a VIP dinner and I had some executives ask me around ROI and which was surprising. I don't get a lot of questions around uh profitability in gaming but this is a fun slide I wanted to highlight which is the amount of spend versus the amount of money that that category makes. And I think this is a really fun one. As I mentioned lifestyle puzzle drives the most spend. Uh what's really interesting is you could see the amount of money however uh the lifestyle puzzle space makes in um the mobile space is actually about 20%
smaller than how much is spent per year. Part of this is of I think there's a general sentiment that you know we will bring ROI in like a year or two if we get this person in our audience. And again I think uh the challenging thing is as we saw on the retention side casual is having some challenges. So I do think the casual space is going to have some uh tricky years ahead of us given you could see this uh widening gap between the amount of spend and the amount of revenue that casual brings. But then you see on the opposite side action and strategy even though I'd mentioned uh Japan is starting to see revenue declines. I mean from a spend and uh spend and revenue standpoint it's still quite healthy. Uh casino uh again I know it's very taboo but casino does really well. it makes still a ton of money per user. And then sports and racing, this has been like I think four years in a row where the sports and racing category has declined in revenue. Um, so again, maybe this is just a general sentiment that I think all of us
are spending less time watching sports, but again, I think this is a fun view to just show the ads versus the revenue piece. And then uh on the PC console side, as I mentioned, PC console's still doing really well. Uh Steam is by far the dominant um platform when it comes to getting your title to that kind of audience, driving over 850 million downloads in the in the space, followed by PlayStation and Xbox. But again, I think this is a really interesting one just to put into perspective. You know, this combination is about 2 billion in installs. the mobile space did about 40 last year. So just gives you a sense of the magnitude scale between how many audience is in uh mobile versus PC console. But again PC is starting to see a really big focus from developers. And it's one thing to say, it's another thing to show a couple years in a row. Uh as you can see just from a pure revenue standpoint, I mean Steam's
doubled in uh almost seven years or more than doubled in seven years, topping over 12 billion. And again, it just goes back to their dominance and just this ease of use on keeping all your titles in one ecosystem. I think Steam will continue being the dominant player for the PC space. Um, again, what's also really interesting again to to that point is you see this really big uh uh you see this really big focus on driving new content specifically on Steam. Uh while revenues are 12 billion now, 20 20,000 new games launch in Steam. It's getting extremely competitive and it I don't know if there's PC or console developers in the audience, but again we're starting to see more and more mobile gaming companies also releasing their content on PC for crossplatform. Uh it's it's competitive. It's not a joke. Um and lastly, who won the PC space? I think this is a really fun view that I wanted to talk about. It's been a while since I've talked about EA in a slide,
but EA dominated last year. They have the top three title for AAA. Battlefield 6 was the biggest uh console game in the market, but then EAFC and EAFC 26 and 25 respectively took the top two and three titles. But even on the free-to-play side, who knew uh Skate was the number one uh game last year on the PC side. Again, it's just a sign that there is still a really healthy um market for freetoplay and AAA titles. Uh but then again, uh 25 was the year of the indie and the doublea. You know, we had massive games like Repo that drove over 18 million installs. We had Peak driving almost 15 million installs. And then of course some of the AAA titles that we all love and play. Um, I spent a lot of time personally in in the holidays playing Arc Raiders, a massive launch, um, over 11 uh 11 million units, and of course the game of the year with uh,
Expedition 33 almost driving uh, 9 million. So again, I've said this a couple times, gaming is really healthy. If you have great content, there is a opportunity for it. And then lastly, IPs. Uh, specifically PC console has been always very IP focused. And what's been really nice is to actually see that showing up on the on in the revenues. Marvel, the Disney still dominates on the PC console space in terms of IP penetration. Marvel rivals I had mentioned was the number two freetoplay titles. It's still doing well. Um and then you see some of the major sports titles. You see NBA here and NFL, you see the UFC, which there's a big fight on the weekend. So, uh I think that you'll start seeing them being more focused on the game space. And then you see some legacy titles. Ubisoft if there's folks from uh there. I mean Assassin's Creed did really well. It was the first time it's been in the top five in a really long time. So overall in conclusion, I know I went a
few minutes over, but ultimately gaming is really healthy. Uh specifically the PC console side we think is going to have a really good year this year, especially Steam with another uh dominant year. But again on the gaming on the mobile side, it's matured. It's been averaging between 80 to 85 billion for the last couple years. This doesn't include the web store revenue, so you could probably make the case it's closer to 90 billion. Um, but again, it's still there's still a massive opportunity if you have great titles on the market. Um, specifically mobile gaming, there's a lot of growth opportunity when you're focused on these individual markets. As I had mentioned, traditionally Europe Europe wasn't a market that few people would focus on individually. They would focus on the US. But as we saw these last couple years, you've seen the UK, Germany, France really lead in terms of revenue growth and I think there's still a big opportunity for it. And then again, as I'd mentioned, uh the Chinese developers and specifically the eastern developers in general are doing extremely well. I would definitely spend
some time looking at them and and seeing some of their strategies. And then lastly, Steam going to do great. Uh PC console is set for a big year and big growth. And ultimately, I think there's a I think we're off to a really big year for 26 for gaming. And with that, I think I'm done. Thank you guys.
Auto-generated captions from YouTube — names and numbers may be misheard.
Key insights
7 takeaways · ~3 min read- 01The mobile gaming market is shifting toward a live-service model, evidenced by a decline in new game launches from nearly 100,000 in 2022 to under 70,000 in 2025 as publishers prioritize existing titles.
- 02Mobile revenue remains resilient at $82 billion, despite a 15% decline in downloads, with the UK market showing notable strength through 10% year-over-year revenue growth.
- 03Competition in the mobile space is increasingly dominated by Eastern publishers, who now hold five of the top nine spots in the Western market with titles like 'Whiteout Survival' and 'Last War: Survival' grossing over $1 billion within a year of launch.
- 04The PC market, led by Steam, continues to grow, with annual revenue topping $12 billion and over 20,000 new games launched on the platform in the past year.
- 05Mobile developers are significantly increasing live-ops intensity, with the average game now featuring over 30 unique events per month, a record high aimed at improving retention.
- 06User acquisition remains the primary challenge for developers, with over $12 billion spent on video ads and 1 trillion impressions generated annually, while rewarded video ads have grown to represent 15% of total ad spend.
- 07The puzzle category is the most competitive and highest-spending segment in mobile gaming, though it faces a retention challenge despite driving the majority of revenue.
Ask AI about this video
Cite this video
Citation
Generating citation…
Comments