Transcript
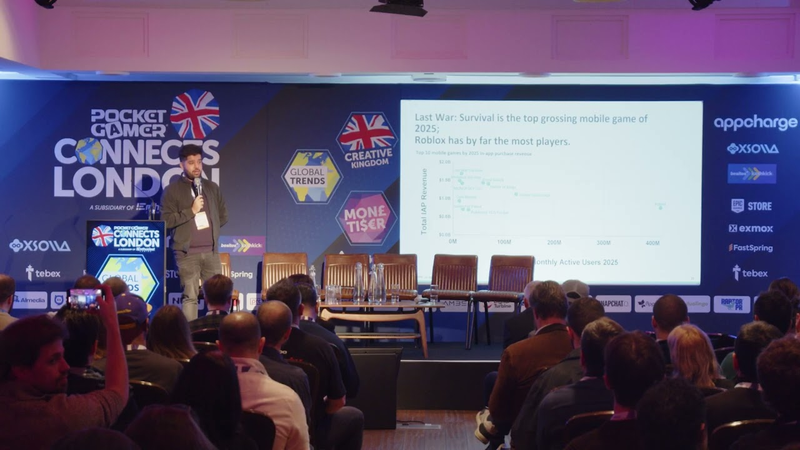
Up next, I would like to welcome Alyssa from Sensor Tower who's going to be talking about the state of gaming in uh in 2025. So, please welcome Alyssa to the stage. Okay. Hi everyone. My name is Alyssa Paramore. I am the team director of gaming at Sensor Tower. Um today I'm going to talk about our newly released state of gaming report. It came out last week. Have a look everybody. I put some cards down here with a QR code where you can download the report. It's free. Don't worry, I'm not trying to sell you anything. Um so, today we're going to talk about the themes that shaped 2024 and 2025. Um before we get into that, can I have
everybody in the room close your eyes? I want you to imagine a 2025 where IDFA and ATT changes have not yet happened. CPI is still low. Mobile is booming and welcoming to new entrants. You can still effectively target your markets by frankly kind of a sketchy amount of data points. And the world is looking bright. All right, you can go ahead and open your eyes cuz that's like just absolutely not going to happen for 2025. But, today we're going to talk about reasons why you can be optimistic about that for this year. Um we're here today to prepare you about the incoming challenges of the next year and how you can get ahead of them. All right, so what we're very excited to report this year is that we are returning to growth in 2024. So, uh very happy about that after a down year of 2022 and 2023. Um we're seeing really a focus on efficiency of new
titles. Um less focus on new titles and more focus on existing titles. Every single dollar that you have in UA in development is precious. The cost of CPI and cost per install is very, very high. So, extra focus on live ops and more There we go. Do I use this one? Oh, okay. Um and the evergreen titles that have been out for 5 plus years are seeing much more success. Um and it's very, very hard for new entrants to come into the space. Um we're seeing a shift away from um performance marketing and into more brands marketing and transmedia. And we're also seeing success in next gen social platforms such as TikTok um and a higher share of voice on um ad networks such as AppLovin. And lastly for the year, we saw success in the hybrid casual monetization, which is also up. All right, quick snapshot of what the
year looked like. Um across the board, we see lots of positives here. Um we have increase in IAP purchase revenue, increase in total hours spent, total sessions, and gaming ad impressions that were captured. Um as you'll notice on the left, the one thing that is down is new games downloads. Uh and we're going to see this over and over again today and what exactly is causing this decrease in, you know, downloads and is revenue more successful comparatively? Is there a market maturation? Like what exactly is causing that? So, first, we're going to talk about downloads. So, over here on the graph, you know, you'll notice it was very tough after the COVID boom. Um on the left side of the graph, we're looking at apps and games, which is about 1% down year over year. And then on the right side of the the you'll see about a 6.6% decline year-over-year for iOS and Google Play games. Uh of course, this is suggesting that the gaming downloads are declining
more than overall apps on the App Store. Um however, 49 billion is still a big number. Um App Stores are still healthy and there's still demand from consumers, um but there is some hesitancy and you'll see competition between these two stores. You'll notice on the right side of the graph where we're looking at iOS, which is in that like lighter blue color, and the darker blue color is in Android. iOS stayed about stagnant with declines in Google Play. So, what is causing that? Um we are seeing a bit of a decline there. We'll talk about that in in future slides of what might be causing that. So, um on this graph, you'll notice on the left, we are talking about the various product models. So, we have hyper-casual, casual, hybrid-casual, and mid-core as an overall market share of downloads. Glaringly on the right side of the graph, you'll notice about a 17% decline in casual downloads
year-over-year. Um what exactly is causing that? It's not all doom and gloom. While we are seeing a decrease in downloads in casual, we are seeing an increase in revenue, which suggests that they are better monetizing the users that they already have. It's tough for new entrants to come into this space, but as you focus on live ops and fostering the arsenal that you already have within casual, we are seeing revenue increases. So, audiences are sticking with what they know in casual, and evergreen titles are really driving the growth. Um but again, we are seeing a decline in new downloads. We're also seeing a 3% increase in hybrid-casual, um and there were a lot of big releases this year. Um mid-core was about flat to declining, and then of course, we see a 2% uh decline in hypercasual. Um Now, let's take a look at this globally. Um I want to draw your attention to the uh right side of the screen, where you'll see our biggest market, Asia, which is about 21 billion market. Uh
we're about a 6% year-over-year decline. However, when you compare that to North America and Europe, which saw 7% and 8% decline, respectively, um it's not declining at the same rate as North America and Europe is. So, we can see a 7% decline and 8% decline in North America and Europe. Uh I also want to bring your attention to the Middle East, uh which was the only growth region on this graph. Um as you know, there's been lots of investment in the region, and there is a big focus on growth. Um the Middle East is actually the only region that it saw growth in both downloads as well as revenue. So, definitely keeping eyes on the region as more investment pours into the space. And we also saw an 8% decline in Latin America, as well. Okay. All right. So, we're making our way over to revenue now, which is what we're looking at. Revenue is up. Now, we're into the good
news, the positive things to look forward to in 2025. So, again, revenue is up. On the left side of the graph, we're looking at apps and games, which are up about 13%. Um we saw growth in both iOS and Google Play. On the right side of the graph, we are looking at just games themselves, which we see Android and iOS, and then about a 3.8% growth year-over-year. Um so, what exactly is this telling us? We see that Google Play on the right side of the graph actually graph actually saw a decline, which is being offset by some of the growth in iOS. So, what exactly is causing that? Um as we saw with uh declines in Asia, we see relative stagnation in gaming revenue across Asia uh where Google Play is dominant. This year, the US and Europe had a much stronger year where iOS is dominant in those regions. Now, what exactly is causing this revenue stagnation in Asia? We'll talk
about in successive slides. All right. So, we're looking at uh what we were looking at earlier by revenue uh but instead for casual, midcore, and a hybrid casual. You'll notice that there is no hyper casual on this graph, of course, because there is no IAP revenue in hyper casual. So, we've talked about the high cost of CPI, right, in previous slides. Um, it's very, very expensive to acquire the right types of users. Um, however, we do see a 6% increase in the revenue in casual um over the past year. And we also saw a 37% increase in revenue in hybrid casual. Um, you'll also notice in terms of the market share on the left side of the graph that hybrid casual only went from 3 to 4%, which again is a very small portion of the market. But again, we would be remiss not to mention that 37% growth. Um, casual with this growth, the higher LTV from casual means a higher CPI is
more sustainable. We saw lots of titles grow in casual over the past year. Um, big gains in but with Monopoly Go as well as Royal Match over the year. And um uh um and we also saw midcore kind of flat and slightly declining. You'll see this in various sections throughout the platform, what a challenge it was for midcore over the past year. So, however, I don't want to, you know, talk bad on midcore cuz we're still talking about 2/3 of the overall market here in terms of revenue. They're still very effectively monetizing their users as compared to other product model types. All right. so let's look at that global um graph again. This is a great slide that demonstrates just what a great year it was for North America, Europe, Middle East, kind of across the board here. Um North America is up 9% and Europe was up about 14%. Quick callout for Europe as well. Russia was taken out of the estimates last
year, which is about 25% of the overall market. So, this is still really great growth to have seen in with that segment having been removed from the Europe estimates. Um Asia and is the only segment within this graph that actually saw a revenue decline, which we're going to tie a bit later into um some of the causes from the RPG genre having a pretty rough year. All right, and then also as well, we'll see the growth here from the Middle East, uh which saw 18% year-over-year revenue growth, uh which is the the highest growth on this uh graph here, as well as the Latin American market, which is up about 13%. So, let's talk a bit more about what genres specifically are causing this growth and decline and the engagement amongst these genres as well. So, within North America, um you'll see your usual suspects here, right? For casual casino, puzzle, and strategy are all up. Casino is up about 16%, puzzle up 13, and strategy up 17%.
So, what is causing this this growth? In casino, about 27% of the growth in the North American market was caused by Monopoly Go. In puzzle, about 15% of that was driven by Royal Match. And in strategy, about 13% of that was driven by Last War: Survival, um which as you know saw rapid growth and have a massive UA campaign in the past year. I think everyone in this room has probably seen a million of those ads. I know that I have. Um and then we also saw RPG has a double-digit decline. You'll notice of the top genres here, this is really the only one that saw such a large decline, about 10%. So, we'll see this throughout the the challenge that RPG had throughout this year. And then we're going to move over into Europe first. So, oftentimes uh people typically lump North America and Europe together uh as similar markets. However, I think that this graph should paint a picture of enough distinguishing uh variability
between the two regions of of how they're different. So, up here on the top you'll notice that strategy is up 32% in Europe. Um, there's a similar usual suspects between what is driving the growth in each of the It's again, so Last War Survival, Royal Match, and Monopoly Go um against amongst strategy, puzzle, and casino. But, just about every genre in Europe was up year-over-year. The only genre that saw a decline, as we were already discussing, was RPG. And even that was only down about 3% comparatively. So, it was a great year for European revenue. All right. Next, let's go into Asia, which has typically had different tastes and attitudes and opinions of of what their top genres are. RPG has been king in Asia for a very long time. Um, as we know, if RPG had a tough year, that's likely what is causing a lot of the challenges within that region. So, you see that RPG is
down 19% year-over-year. Strategy is up 10%, shooter's up 3%, action is up 74%, which is actually driven by Tencent's uh Dragon and Fighter Mobile. Um Puzzle, we see that increase by Royal Match, which has seen actually a 100% year-over-year growth in the region. Uh Japan is actually now their number two market. Now, what is causing this challenges within Asia within the RPG? Um there's a lot of different factors. We have macroeconomic factors where many currencies are weak against the dollar. Um we also are experiencing some cannibalization within the top publishers in RPG. As you know, Mihoyo's uh two RPGs, we're looking at Honkai: Star Rail and Genshin Impact, had a really rough year. We saw about a 15% year-over-year decline in Genshin Impact last year. So, if that revenue was not sustained previously, that's going to show big declines in the number one genre within this region. But, it's not
all doom and gloom for the region because we do see increases in various casual genres, um which is an interesting opportunity market for the region. All right, so let's talk about breakout games of 2024, the exciting stuff. Um this is going to be ranked by the consumer spend growth within 2024. Um obviously there's a lot of new entrants that have come out in the last 2 years on this list, but interestingly enough, there's a few titles that have been around for quite some time. When we're looking at Brawl Stars, Royal Match, and Roblox, to have been out for the length of time that they have and still be amongst this top growth lists is crazy. And we'll talk about the next slide about how we're seeing top-heavy concentration of evergreen titles driving a lot of this revenue. However, we do have our new releases uh in the past 2 years of course on this list, so we're talking about Monopoly Go, uh which was one of the most successful
launches of all time. Uh actually, I think it was the most successful mobile gaming launch of all time. Um Whiteout Survival also had a massive year, Last War: Survival, Legends of Mushroom, just a lot of creativity in people doing new things um on familiar formats. Now, as I mentioned in the top-heavy concentration, there has been a lot of revenue concentrated to these evergreen titles that I keep talking about. Those have been out for 5 plus years and have been around for a while. We'll talk about that a bit later. Actually, we're going to talk about that now. So, um talking about the top-heavy concentration, we are looking at this graph here on the left between the splits of them. In 2019, it was a much more diverse, um market, right? We had uh a lot of money being driven by new titles as well as legacy titles as well. And you'll notice
as time passes throughout 2024, the disparity of revenue that's being driven by titles that have been out for longer naturally is growing. What this means is that it's going to it's much harder of a market to enter into with the level of saturation that we're seeing. And so, there's a high amount of challenge for new titles. So, this brings us back to the themes that I was talking about at the beginning in that people are really focusing on what they already have in their arsenal. Really investing on live ops and engaging and inquiring audiences for their titles that do already exist. Um and again, you know, titles that have been out for a while, we're talking about Candy Crush, which has been out for about 13 years, had its largest year last year. Titles like Pokémon Go, Clash of Clans, and Brawl Stars all saw a massive year. Okay, and let's actually go back to uh we're going to go back to
the audience slide. So, as we're seeing difficulties in acquiring new audiences and launching new titles, it's more important than ever for publishers to truly understand who their audience is. What are their tastes, attitudes, and opinions? Where are they spending their time outside of their title? So, on this graph here, you'll see amongst the major genres of casino, puzzle, strategy, simulation, everybody knows that casino is a male-dominant genre, right? That's, you know, just a fact. But, did you also know that of people that are interacting with casino titles, that they're also very, very comfortable with peer-to-peer playing paying platforms? So, they're sending Venmo transactions. They're sending Zelle transactions. So, they're very comfortable exchanging money on um outside apps. Uh simulation games, it's a pretty even split between male and female. Um but, we're also seeing, of course, anybody who's playing simulation games are likely playing Roblox. But,
what we're seeing amongst this audience is that people that are playing Roblox are also interacting with apps that indicate that they are parents. So, what is that telling us? Is that people that are playing Roblox, they might be playing on their parents' phones. So, we are now knowing, okay, these are the other apps that they're interacting with. Uh and then my favorite example here between strategy and RPG, uh who might be locked in a basement playing the game for 10 hours, they over-index for uh interacting with fast-food apps. So, they're ordering McDonald's. They're interacting with Chick-fil-A um while they're also playing these titles. So, it's super, super important to understand who our audiences are so that we can effectively target them and grow the titles that we already have within our arsenal. All right. So, let's go down down to publisher trends. So, I know this graph is a bit overwhelming. Bear with me here. Um we are looking at the market concentration here by publisher for
overall worldwide consumer spend. Um and you'll notice that a lot of these genres, actually most of them, have about 1/3 of the global revenue uh taken up by two publishers. So, there's really dominance by quite a few publishers in a lot of these genres. RPGs actually the most competitive by the amount of publishers that are within that space. I think it's about five 55% of it is outside the top 10 publishers within the area. Um shooter genre, more than 50% of that comes from Tencent alone within shooter. So, we do see a high amount of concentration. Um but what this is telling us is that it is extremely challenging if you're the little guy to come into these spaces when we have such dominance of these larger publishers. Um over there on the right side, you'll see the number one, two, and number three publishers, but of course there's a lot of usual suspects here and it's going to be really, really hard to enter into these new spaces.
Which again brings us back to, you know, the original point of today is what has been the focus of 2024. Um really, really hard for new entrants. We've seen a lot of focus on um encouraging the titles that you already have. Focusing on live ops and really trying to better understand your audience and acquiring new audiences. This is not the right one. This is the old slide. Sorry everybody, we're skipping toward the end. Um all right, so what are we expecting for 2025? Um we're going to see a strong return to growth. Um bit controversial, but most of this is likely going to be driven by larger publishers who already dominate their market. It's going to be really, really hard to enter into the new to new spaces as we've already seen. If you're a newer publisher coming out with a title, it's very, very costly and expensive to develop it and then to acquire those right types of users. We are also going to see smaller developers look to diversify their
revenue streams, whether that means taking their titles cross-platform or launching on an external web store or porting their titles to another platform. They will look for creative ways to grow what they already have within their basket. And lastly, marketing is still going to be a challenge, but we must adapt with next-gen social platforms and short-form content and leverage clever IP that resonates with our audience. So, understanding who our audience is and how we can expand by doing transmedia and working with various other brands to further expand the audiences that we do have. If we can implement each of these things and take into consideration everything that we've talked about today, I think we just might be okay. All right. Thank you, everybody.
Auto-generated captions from YouTube — names and numbers may be misheard.
Key insights
7 takeaways · ~3 min read- 01The mobile gaming market is increasingly top-heavy, with revenue growth driven by evergreen titles over five years old—such as Candy Crush, which saw its largest year ever—making it significantly harder for new entrants to gain market share.
- 02While total gaming downloads declined by approximately 6.6% year-over-year on iOS and Google Play, overall in-app purchase revenue grew, indicating that publishers are successfully focusing on better monetizing existing user bases through live ops.
- 03Hybrid-casual games emerged as a high-growth segment, recording a 37% increase in revenue, even though they still represent a small portion of the total market at 3% to 4% share.
- 04The Middle East was the only region to experience growth in both downloads and revenue, with an 18% year-over-year revenue increase, while North America and Europe saw declines of 7% and 8% respectively.
- 05The RPG genre experienced a double-digit decline of approximately 10% in North America and faced significant challenges in Asia due to macroeconomic factors and cannibalization among top titles like Genshin Impact, which saw a 15% year-over-year revenue drop.
- 06Market concentration remains high, with roughly one-third of global revenue in most genres controlled by just two publishers, and Tencent alone accounting for over 50% of the shooter genre's revenue.
- 07Successful growth strategies are shifting away from traditional performance marketing toward brand marketing, transmedia, and leveraging next-gen social platforms like TikTok to reach audiences.
Ask AI about this video
Cite this video
Citation
Generating citation…
Comments